
 Europe Gypsum Board Market | 2026-2036
Europe Gypsum Board Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gypsum Board Market Foresight
Green leasing and performance-based project finance is reconfiguring capital deployment across Europe's gypsum board supply chain. Knauf leverages its integrated plasterboard-to-insulation portfolio to capture bundled retrofit contracts. Saint-Gobain anchors its position through manufacturing scale across France, Germany, and Benelux. Etex Group specializes in lightweight panel systems that meet stricter acoustic and fire ratings for commercial towers.
Europe gypsum board consists of a calcium sulfate dihydrate core pressed between heavy paper facings, manufactured through continuous kiln calcination and slurry mixing at controlled density. The product serves primarily as interior wall and ceiling surfacing in buildings requiring rapid installation and finished aesthetics. Fire-resistant board leads product type demand as regulatory thresholds for passive fire protection rise across commercial and multi-residential construction. Renovation application growth outpaces new-build segments as aging European housing stock requires systematic interior upgrades. Contractors remain the dominant end-user channel, though architects increasingly specify certified performance grades that reshape procurement through wholesalers.
EU Green Deal building renovation targets, CE marking under the Construction Products Regulation, and national transpositions of the Energy Performance of Buildings Directive are tightening material standards and carbon disclosure requirements across member states. ECHA scrutiny of flame retardant chemistries and REACH compliance for additives are elevating formulation costs while favoring suppliers with in-house testing capabilities. Stakeholders must monitor how the EU AI Act and digital product passport mandates reshape supply chain traceability requirements for gypsum sourcing and end-of-life recycling pathways.
Market Dynamics
EU Green Deal renovation mandates are compressing project timelines and forcing material specification changes across Europe's gypsum board supply chain. The directive's 2030 building stock upgrade targets are pulling forward demand for fire-rated and thermally performing wall systems.
Growth Catalysts
- Energy Performance of Buildings Directive transpositions:National building codes in Germany, France, and Italy now mandate interior thermal upgrades that favor gypsum board with integrated insulation.
- Passive fire protection thresholds:Commercial towers and multi-family housing across Benelux and Nordic markets require enhanced fire-rated board for ceiling and shaftwall assemblies.
- Urban densification corridors:Multi-family retrofit clusters in Berlin, Milan, and Paris generate concentrated demand for rapid-install interior systems.
Market Restraints
- Natural gas cost volatility:Kiln calcination energy intensity exposes producers to input cost swings that compress margin buffers.
- Flame retardant chemistry scrutiny:ECHA evaluations of halogenated additives force formulation reformulation and testing cost escalation.
- Lightweight panel substitution:Calcium silicate and magnesium oxide boards capture specification share in premium acoustic and moisture-resistant segments.
Strategic Opportunities
- Digital product passport readiness:Early compliance with EU traceability mandates positions suppliers for preferred procurement status under CSRD-aligned purchasing.
- End-of-life gypsum recycling infrastructure:Closed-loop plasterboard recovery networks in France and Benelux unlock circular economy certification premiums.
- Prefabricated bathroom pod integration:Modular construction contractors in Germany and Netherlands specify pre-finished gypsum board assemblies for hotel and student housing.
Industry Challenges
- REACH additive compliance timelines:Extended substance evaluation periods delay new product launches and tie up regulatory affairs capacity.
- Skilled drylining labor scarcity:Aging installer populations in Italy and Eastern Europe constrain project execution speed and quality consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gypsum Board Market |
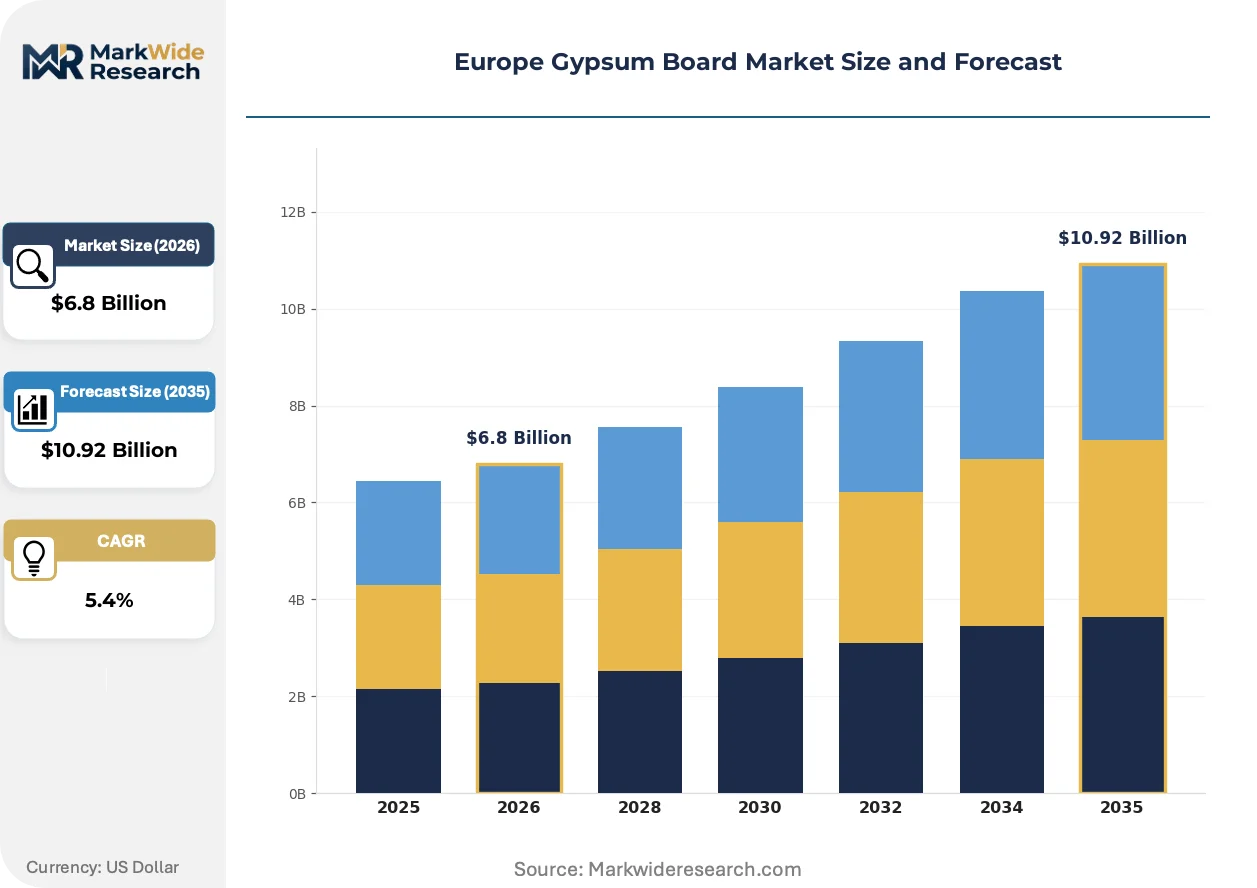
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Gypsum Board, Moisture-Resistant Board, Fire-Resistant Board, Soundproof Board Application: Residential, Commercial, Industrial, Renovation End User: Contractors, Builders, Architects, Interior Designers Distribution Channel: Direct Sales, Retail Stores, Online Sales, Wholesalers |
| Companies Covered | Holcim, Yoshino Gypsum, Knauf, Fermacell GmbH, Gyptec Ibérica, Saint-Gobain, James Hardie Europe, USG Boral, Etex Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gypsum Board Market Shifts & Advancements
Material science convergence and regulatory digitization are redefining competitive advantage in Europe's gypsum board sector. Product differentiation now hinges on embedded carbon transparency and installation speed rather than commodity availability.
Phase-change material integration is hybridizing gypsum board core formulations to deliver thermal mass buffering in lightweight wall assemblies. German and Austrian multi-family developers specify these panels for passive house retrofits where mechanical HVAC downsizing justifies material premiums. The technology is hybridizing energy performance expectations across residential and commercial specification tiers.
EU AI Act supply chain monitoring provisions are mandating automated traceability for gypsum sourcing and additive provenance. Manufacturers must retrofit production lines with sensor networks and blockchain-anchored documentation systems. French and German plants face the steepest compliance curves due to earlier national transpositions of digital product passport requirements.
Certification-driven specification is consolidating buyer influence among architects and sustainability consultants who filter wholesale catalogs for EPD-verified products. Contractors in Nordic markets increasingly delegate material selection to design-phase consultants rather than self-sourcing. This pattern is most visible in Stockholm and Copenhagen commercial towers where green leasing criteria bind tenant fit-out material choices.
Europe Gypsum Board Market Segmentation
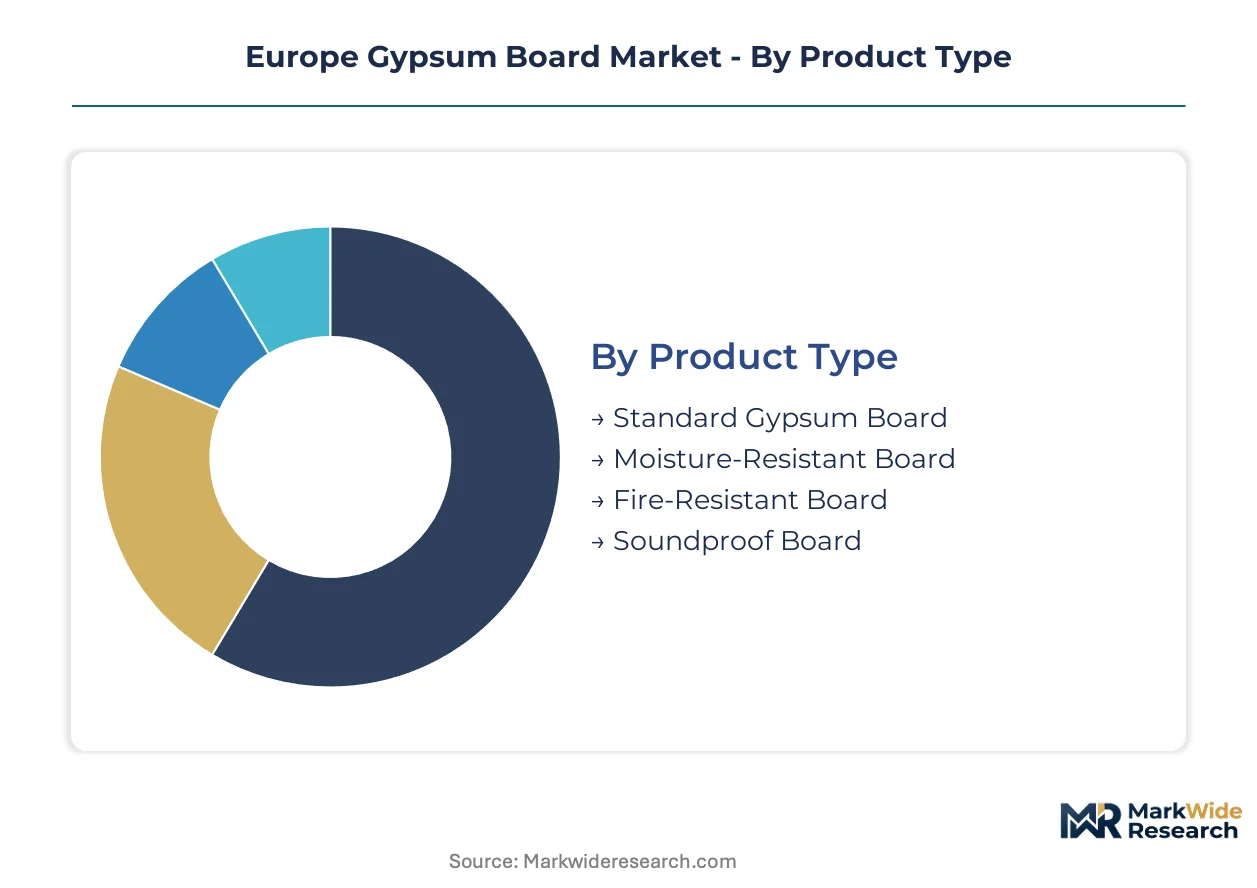
Segmentation in Europe's gypsum board market reveals how specification authority, installation logistics, and regulatory compliance reshape procurement patterns. Contractors and architects filter products through divergent lenses—cost efficiency versus certified performance—creating parallel demand tracks that suppliers must serve simultaneously.
Product Type:
After-sales intensity varies sharply across product tiers, with fire-rated and acoustic systems demanding technical support that standard boards rarely require.
- Fire-Resistant Board:Engineered with glass fiber reinforcement and crystalline water content that delays heat transfer during combustion. German and French multi-family housing retrofits specify these boards for shaftwall and ceiling assemblies under tightened national building codes. Regulatory thresholds for passive fire protection are pulling specification share from standard grades.
- Moisture-Resistant Board:Features silicone-treated paper facings and water-repellent core additives that withstand humid environments. Demand concentrates in Benelux bathroom renovations and Dutch hotel prefabrication pods where mold resistance carries warranty implications. These boards command technical consultation during specification that commodity grades bypass.
- Soundproof Board:High-density core formulations with viscoelastic interlayers dampen airborne and impact transmission. Italian and Austrian multi-family developers specify these for urban infill projects near transit corridors.
- Standard Gypsum Board:Unmodified calcium sulfate dihydrate core with untreated paper facings serves cost-sensitive residential new-build and basic renovation. Volume flows through wholesale channels with minimal technical support.
Fire-resistant board holds the largest share; momentum sits with moisture-resistant grades as bathroom-centric retrofits expand.
Application:
Cost tier stratification separates premium specification in commercial towers from price-driven residential volume.
- Renovation:Systematic interior upgrades of aging European housing stock drive demand for rapid-install systems that minimize tenant displacement. Berlin, Milan, and Paris multi-family clusters generate concentrated procurement for fire-rated and thermally performing assemblies. EU Green Deal renovation mandates compress project timelines and favor suppliers with logistics networks attuned to occupied-building work.
- Commercial:Office towers and hospitality projects in Nordic markets specify certified acoustic and fire-rated systems that satisfy green leasing criteria. Stockholm and Copenhagen developments bind tenant fit-out material choices to EPD-verified products, elevating architect influence over contractor procurement.
- Residential:New-build single-family and multi-family construction in Germany and France absorbs standard and moisture-resistant grades through wholesale channels.
- Industrial:Manufacturing facilities and warehouses require impact-resistant and fire-rated assemblies for compartmentalization, with demand tied to industrial construction cycles in Eastern Europe.
Renovation commands the dominant volume position; commercial applications are climbing the fastest as green leasing spreads.
End User:
Customer type determines whether procurement flows through specification-driven channels or price-optimized wholesale routes.
- Contractors:Dominant procurement channel for residential and light commercial projects, selecting products based on installed cost and availability through established wholesaler relationships. German and Polish drylining contractors face labor scarcity that pressures them toward faster-install systems.
- Architects:Specification authority concentrates in commercial and premium residential segments, particularly in Nordic markets where sustainability consultants filter catalogs for EPD-verified and digital passport-ready products. French and Dutch commercial towers increasingly delegate material selection to design-phase consultants.
- Builders:Volume purchasers for residential new-build, optimizing across standard grades with limited technical differentiation.
- Interior Designers:Surface finish and aesthetic integration drive selection for hospitality and high-end residential, with limited influence on core board specification.
Contractors retain the largest procurement volume; architects are gaining share fastest as certified performance grades reshape specification authority.
Distribution Channel:
Supply concentration in wholesale networks creates tiered access to technical support and inventory depth.
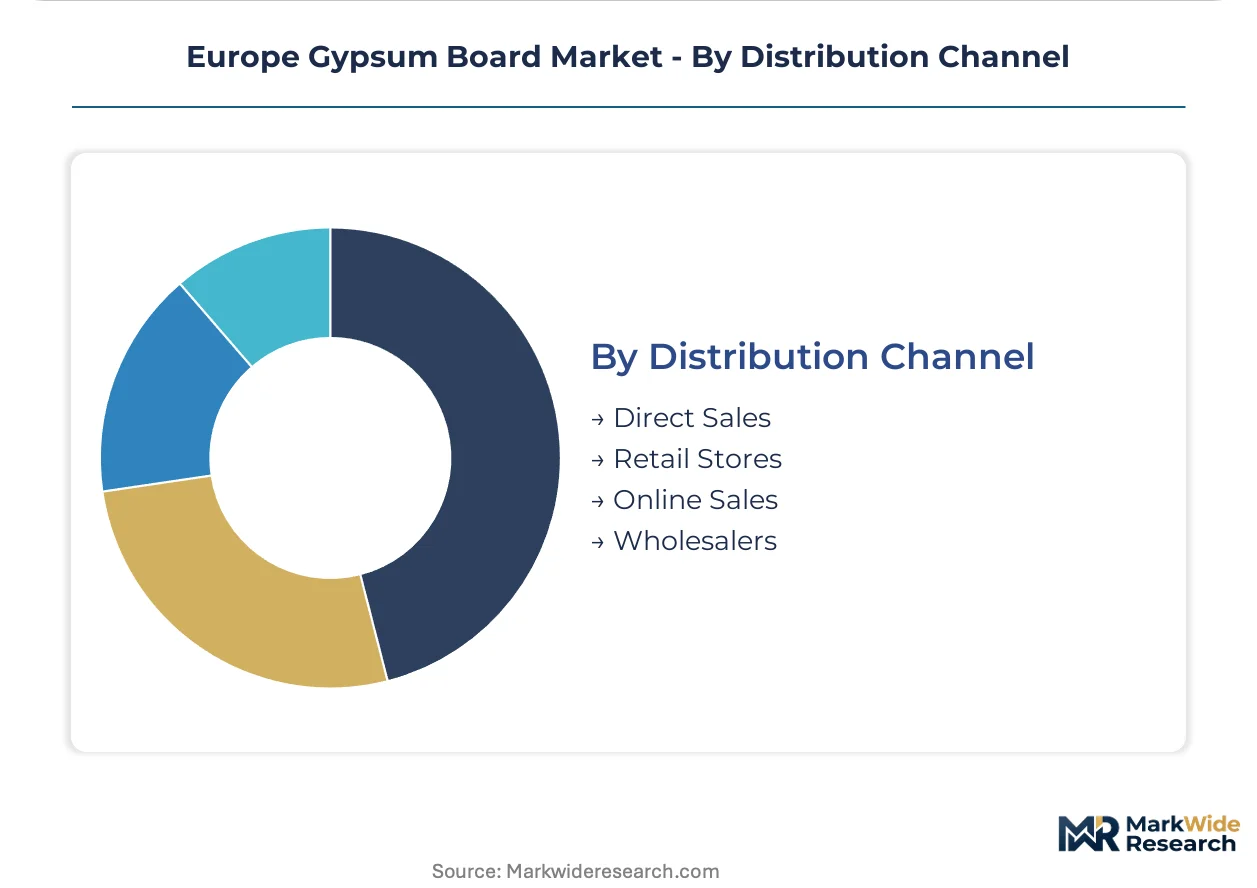
- Wholesalers:Primary channel for contractor procurement, offering consolidated access to multiple grades with regional inventory positioning. Saint-Gobain and Knauf maintain captive wholesale networks in France, Germany, and Benelux that lock in contractor loyalty through availability guarantees.
- Direct Sales:Large commercial and industrial projects bypass intermediaries for volume pricing and dedicated logistics coordination. German multi-family retrofit clusters and Dutch modular construction contractors source direct for prefabricated assemblies.
- Retail Stores:Small-scale residential renovation and DIY segment, with limited technical consultation and commodity product focus.
- Online Sales:Emerging channel for standardized products with clear specifications, constrained by logistics complexity for bulk gypsum board.
Wholesalers dominate channel volume; direct sales are expanding most quickly as bundled retrofit contracts and modular construction grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal renovation targets are redirecting public and private capital toward interior thermal upgrades across member states. National transpositions of the Energy Performance of Buildings Directive are tightening material standards and compressing project timelines for wall system procurement.
Germany
Berlin and Munich multi-family housing clusters are driving demand for fire-rated and thermally performing assemblies as landlords retrofit for energy efficiency. The federal government's Building Energy Act mandates interior insulation upgrades that favor gypsum board with integrated thermal performance. North Rhine-Westphalia's dense urban corridors concentrate contractor procurement networks for rapid-install systems.
France
Paris and Lyon commercial towers are specifying certified acoustic and fire-rated systems under green leasing criteria that bind tenant fit-out choices. The RE2020 environmental regulation tightens carbon thresholds for construction materials and elevates EPD-verified product procurement. Île-de-France's renovation clusters generate concentrated demand for moisture-resistant grades in bathroom-centric retrofits.
Italy
Milan and Rome urban infill projects near transit corridors are absorbing high-density soundproof boards for multi-family developments. National transpositions of EU energy performance standards are accelerating interior upgrade mandates for aging housing stock. Northern Italy's manufacturing belt maintains established wholesale distribution networks for standard and specialty grades.
Netherlands
Amsterdam and Rotterdam hotel and student housing developments are specifying pre-finished gypsum board assemblies for modular bathroom pods. Dutch building codes emphasize circular economy criteria that favor suppliers with end-of-life recycling infrastructure. The Randstad urban corridor concentrates demand for rapid-install interior systems in occupied-building renovations.
Poland
Warsaw and Kraków residential construction is absorbing standard and moisture-resistant grades through wholesale channels as housing stock expands. EU cohesion fund allocations are supporting building energy efficiency upgrades that pull gypsum board into interior thermal retrofit specifications. Silesia's industrial construction cycles generate intermittent demand for impact-resistant and fire-rated assemblies.
Europe Gypsum Board Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Europe's gypsum board supply chain. Wholesaler-captive networks in France, Germany, and Benelux lock in contractor loyalty through availability guarantees and bundled service offerings. Two strategic archetypes dominate: integrated building materials conglomerates with plasterboard-to-insulation portfolios, and lightweight panel specialists targeting premium acoustic and fire-rated segments. Capacity rationalization and digital product passport readiness are emerging as decisive competitive moves.
Among Germany-based building materials groups, Knauf and Fermacell GmbH occupy positions within the integrated portfolio tier. Swiss-French conglomerate Saint-Gobain anchors manufacturing scale across multiple national markets. Belgium-headquartered Etex Group exemplifies the lightweight panel specialist archetype with focused positioning in certified performance grades. These three entities represent divergent strategic paths: captive wholesale networks, multi-product bundling, and specification-driven premium positioning.
| Leading Market Players |
|---|
| Holcim |
| Yoshino Gypsum |
| Knauf |
| Fermacell GmbH |
| Gyptec Ibérica |
| Saint-Gobain |
| James Hardie Europe |
| USG Boral |
| Etex Group |
| Others |
Supply & Pricing Matrix
North Rhine-Westphalia's dense kiln capacity clusters anchor European gypsum board manufacturing, concentrating calcination energy costs that downstream buyers negotiate against. This geographic supply concentration transfers input cost volatility directly into contract renegotiations between producers and wholesale distributors.
Pricing Analysis
Certification level under CE marking and national fire-rating tiers creates the primary spread between commodity and premium grades. Three-tier pricing structure across EPD-verified, standard performance, and economy levels stratifies procurement channels. Cost compression in standard grades is intensifying because natural gas price swings erode calcination margins. Contractor buyers in Poland and Eastern Europe exhibit highest price sensitivity, while Nordic architects specifying green-leased commercial towers accept material premiums for traceability documentation.
Supply Chain Analysis
Tariff exposure between EU member states and third-country gypsum raw material sources dominates supply chain risk assessment. Manufacturing concentrates in Germany, France, and Belgium, with calcination feedstock drawing from Spanish and Turkish gypsum quarries. Supply chain risk centers on single-source vulnerability for specialized glass fiber reinforcement used in fire-rated formulations. Distribution runs through captive wholesale networks in France and Benelux, locking contractor loyalty via availability guarantees rather than price competition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward specification-driven architects and sustainability consultants as green leasing consolidates procurement authority in Nordic and French commercial towers. This fragmentation among traditional contractor channels creates margin pressure points for suppliers serving divergent buyer archetypes simultaneously.
For Market Incumbents: Insulate margin position by deepening backward integration into gypsum quarrying and captive recycling infrastructure in France and Benelux. Prioritize certification investment for digital product passport readiness under EU AI Act traceability mandates. Channel control through wholesale network exclusivity remains defensible against lightweight panel substitutes threatening premium acoustic segments.
For New Entrants and Emerging Players: Establish a beachhead in Poland's residential construction wholesale channel where standard grade price competition remains fragmented. Target modular bathroom pod suppliers in Netherlands and Germany with pre-finished assembly partnerships. Go-to-market angle should emphasize rapid-install logistics coordination rather than commodity price undercutting.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated building materials conglomerates with plasterboard-to-insulation bundling capability over standalone commodity producers. Long-term viability hinges on circular economy infrastructure ownership and EPD verification capacity. Signal to watch is REACH additive compliance timeline acceleration that would force formulation R&D consolidation among smaller specialty players.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gypsum Quarrying | Captive raw material supply buffers margin compression from energy cost volatility in German kiln operations. |
| Digital Product Passport Compliance Investment | Early alignment with EU AI Act traceability mandates secures preferred procurement status under CSRD-aligned purchasing. |
| End-of-Life Recycling Infrastructure Buildout | Closed-loop plasterboard recovery networks in France unlock circular economy certification premiums from green-lease tenants. |
| Prefabricated Assembly Partnership Formation | Modular bathroom pod integration with Dutch hotel contractors captures specification share in rapid-install segments. |
| Fire-Rating Certification Portfolio Expansion | Enhanced passive fire protection grades meet tightening national building codes in German multi-family retrofits. |
Research Methodology
A spread of perspectives from drylining contractors, architect specification consultants, wholesale distribution managers, and regulatory affairs directors converged on the working assumptions. Primary interviews with plant engineers at calcination facilities and procurement leads at multi-family developers were cross-referenced against customs trade data, national building code transpositions, and ECHA substance evaluation filings. Bottom-up volume estimates from installation activity tracking were triangulated against top-down construction spend projections.
Demand-supply balance modeling across the analysis window incorporated product type segmentation by fire resistance and acoustic performance, application splits between renovation and new-build, and end-user channel differentiation between contractor procurement and architect specification. CAGRs were derived from fitted trend extrapolation validated against historical construction cycle patterns. Industry-specific forecast inputs included EU Green Deal renovation mandate implementation timelines and natural gas price scenario bands.
Stress conditions across energy input cost bands, REACH compliance timeline delays, and lightweight substitute penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and construction labor availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
PU Waterstops Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Glass Tiles Market
Building & Construction Materials
Roofing Shingles Market