
 Plastic Extrusion Machines Market | 2026-2036
Plastic Extrusion Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Extrusion Machines Market Intelligence
Medical-grade and food-contact specification tiers is bifurcating the competitive landscape into precision-engineered and commodity supply camps. KraussMaffei leverages its twin-screw expertise to dominate high-barrier medical tubing configurations. Davis-Standard sustains strong positions in North American packaging retrofits through extensive service networks. Reifenhauser Group anchors European demand for multi-layer blown film lines with integrated thickness control systems.
Plastic extrusion machines are industrial systems that melt thermoplastic polymers through rotating screws within heated barrels, then force the molten material through shaped dies to produce continuous profiles with controlled wall thickness and dimensional tolerance. These systems serve primary manufacturing functions across packaging film, construction piping, automotive seals, and electrical insulation sheathing. Single-screw extruders retain the largest installed base due to lower capital requirements and operational simplicity, though twin-screw configurations capture expanding share in compounding and reactive processing where dispersive mixing demands exceed single-screw capability. Co-extrusion technology leads technology segment value pools because multi-layer barrier structures command premium pricing in food packaging and pharmaceutical blister applications.
US FDA food-contact regulations and EU REACH chemical authorization frameworks compel machinery builders to certify barrel and screw materials for contaminant migration limits, directly influencing alloy selection and surface finishing specifications. EPA emissions guidelines for volatile organic compounds from extrusion cooling sections shape ventilation and solvent recovery system design in American installations. Machinery buyers must weigh total cost of ownership against evolving polymer feedstock portfolios as mechanical recycling rates and bio-based resin availability reshape processing parameters.
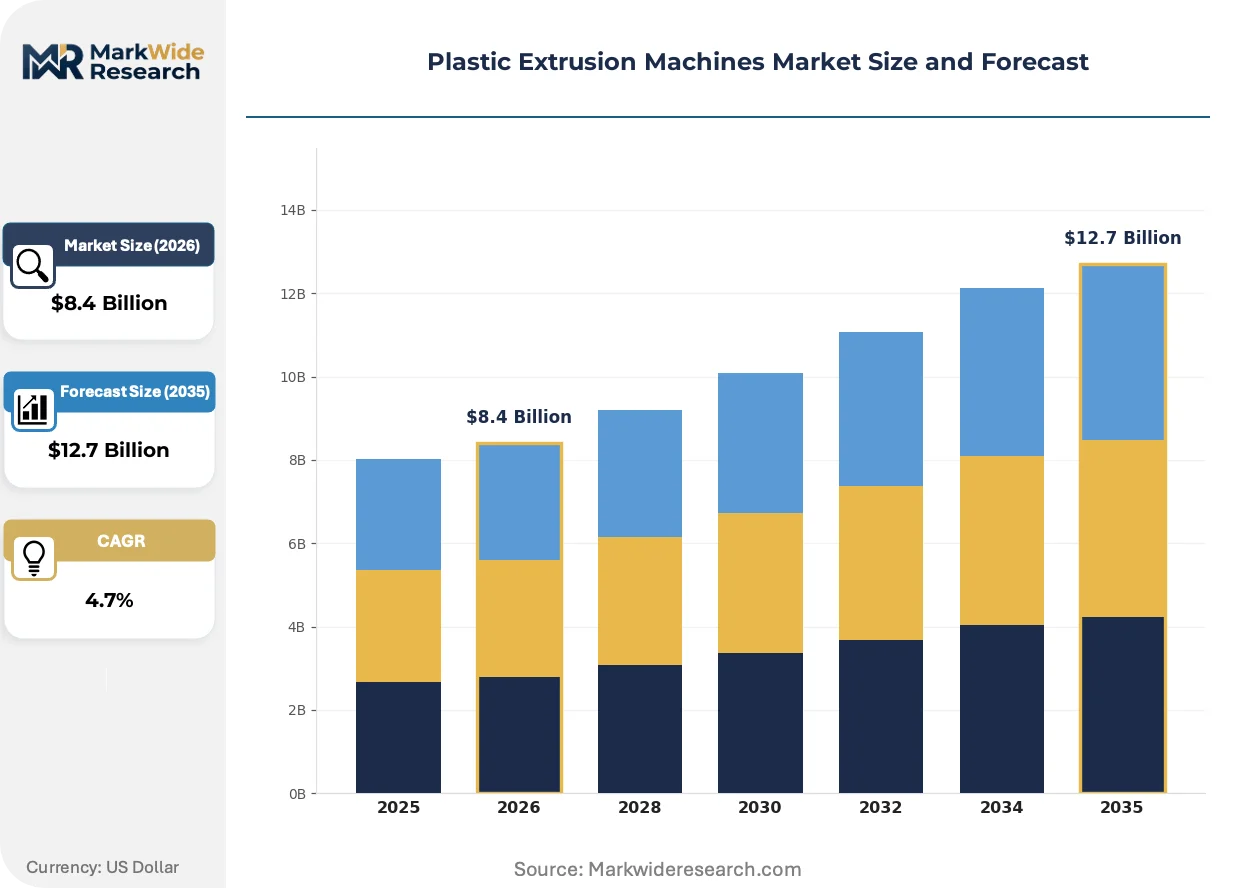
Market Dynamics
EU REACH recycled content mandates are forcing machinery OEMs to reengineer screw geometries for rPET processing, while Southeast Asian packaging converters scale flexible film capacity to capture demand migrating from China's aging coastal manufacturing zones.
Growth Catalysts
- rPET Processing Mandates:EU REACH compliance thresholds on recycled content are compelling machinery builders to redesign barrel and screw configurations for contaminated feedstock streams.
- Southeast Asian Capacity Expansion:Vietnam and Indonesia are displacing older Chinese coastal manufacturing as regional hubs for flexible packaging film production.
- Medical-Grade Specification Tier:Food-contact and pharmaceutical barrier requirements are creating demand for precision-engineered extrusion systems with validated contamination controls.
Market Restraints
- Alloy Cost Volatility:Specialized bimetallic barrel linings and corrosion-resistant screw coatings face input cost pressure from nickel and cobalt supply concentration.
- Technical Limitation in Multi-Material Processing:Existing single-screw designs struggle with viscosity mismatches in bio-based resin blends, constraining feedstock flexibility.
- Regulatory Friction from FDA Migration Limits:US food-contact certification timelines for new barrel surface finishes extend commercialization cycles by months.
Strategic Opportunities
- Underpenetrated Indian Processing Base:Domestic flexible packaging growth under BIS quality mandates is creating demand for imported multi-layer blown film lines.
- Technology Convergence:Integration of real-time thickness gauging with AI-driven die adjustment is enabling closed-loop quality control in high-speed lines.
- Service Network Disintermediation:Remote diagnostic platforms are compressing response times for screw and barrel refurbishment in North American installed base.
Industry Challenges
- Compounding Process Engineering Talent Gap:Twin-screw reactive processing expertise remains scarce relative to deployment of complex multi-component systems.
- Capex Intensity for Co-Extrusion Retrofits:Existing single-layer lines require substantial barrel and die head replacement to achieve multi-layer barrier capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Extrusion Machines Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.7 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Extruders, Ram Extruders, Twin-Screw Extruders, Single-Screw Extruders Technology: Co-Extrusion, Blow Extrusion, Multi-Layer Extrusion, Film Extrusion End User: Packaging, Automotive, Construction, Electrical Application: Thermal Profiles, Sheets, Pipes, Wires |
| Companies Covered | Bausano, Davis-Standard, KraussMaffei, Kabra Extrusiontechnik, Milacron, Coperion, Leistritz, Toshiba Machine, Reifenhauser Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Extrusion Machines Market Strategic Shifts & Innovations
Real-time process control integration and feedstock diversification are compressing traditional equipment replacement cycles while elevating technical service requirements across installed bases.
Electromagnetic thickness gauging with closed-loop die adjustment is bifurcating the blown film equipment market. Premium packaging converters in pharmaceutical and high-barrier food segments are adopting these systems to reduce material give-away. The technology is bifurcating competitive positioning between precision-engineered OEMs and commodity machinery suppliers lacking integrated control architecture.
EU F-Gas Regulation phase-down schedules are accelerating adoption of hydrocarbon and CO2-based cooling systems in extrusion lines. Machinery builders must redesign heat exchanger specifications and safety enclosures to accommodate flammable refrigerants. Blown film processors in Germany and Italy face the most compressed compliance timelines for cooling section retrofits.
Buyer consolidation among multinational packaging converters is compressing equipment procurement cycles and unbundling after-sales service contracts. Large converters in North America are negotiating direct spare parts sourcing agreements, bypassing traditional distributor networks. This pattern is most pronounced in medical tubing and pharmaceutical blister film supply chains where FDA validation requirements favor single-source maintenance relationships.
Plastic Extrusion Machines Market Segmentation
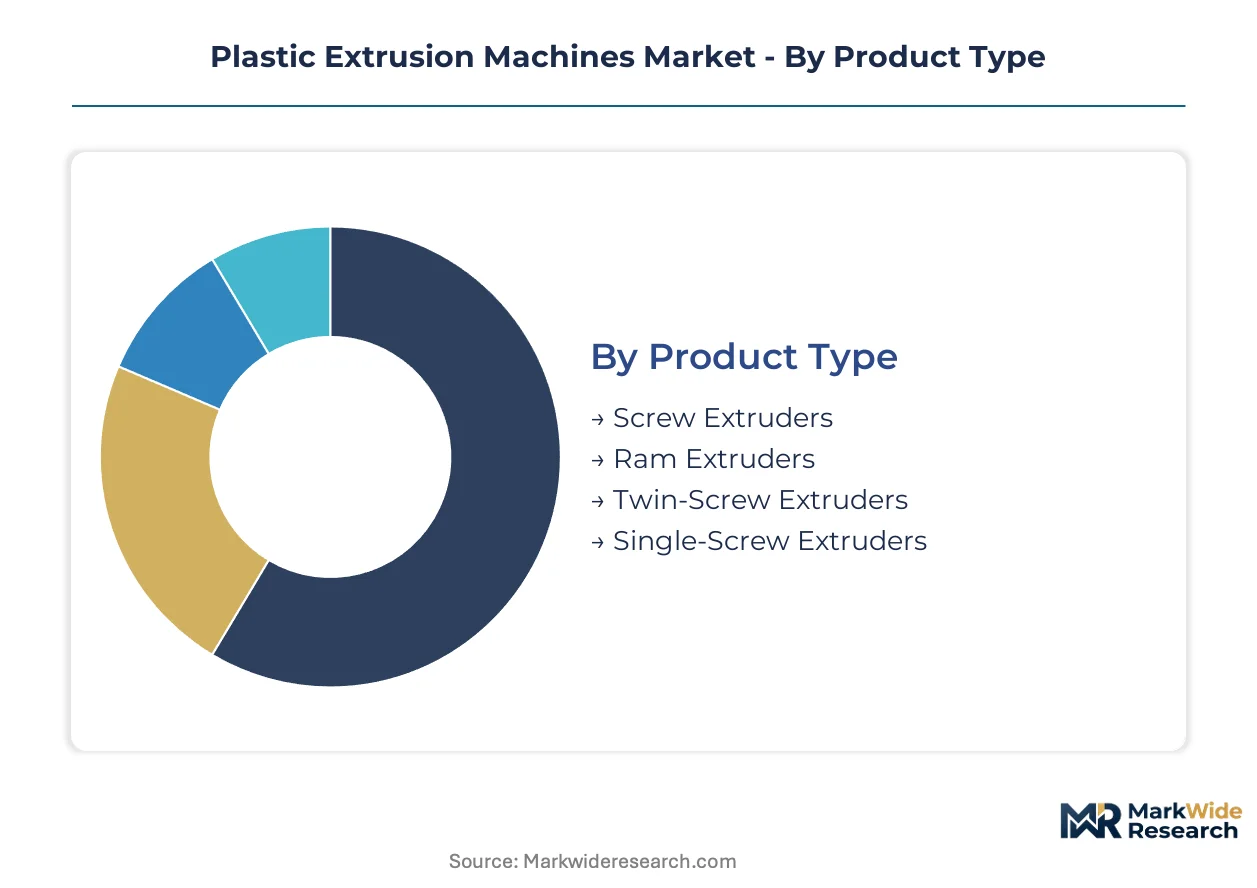
Segmentation in plastic extrusion machinery reveals how equipment specifications diverge across polymer types, processing complexity, and end-use certification requirements. Understanding these divisions exposes where capital expenditure concentrates and which technology tiers command pricing premiums.
Product Type:
Single-screw configurations dominate domestic manufacturing bases in Vietnam and Indonesia, while twin-screw systems flow primarily through German and Italian export channels serving compounding operations.
- Single-Screw Extruders:These systems employ one rotating screw within a heated barrel to convey, melt, and pressurize thermoplastic polymers. Demand clusters in Southeast Asian flexible film operations where lower capital thresholds and operational simplicity outweigh mixing limitations. Vietnamese packaging converters favor these units for commodity-grade PE film production.
- Twin-Screw Extruders:Intermeshing or non-intermeshing screw pairs enable superior dispersive mixing, devolatilization, and reactive processing. Export-led demand from European compounders processing rPET feedstock drives specification intensity, with KraussMaffei and Coperion commanding premium positioning for medical-grade configurations.
- Screw Extruders:Broad category encompassing both single and twin variants, differentiated by screw geometry and L/D ratio. Standard industrial workhorses serve construction piping and profile applications across mid-market processors.
- Ram Extruders:Piston-driven systems for high-viscosity materials and PTFE processing. Niche demand from semiconductor and chemical processing equipment manufacturers in Japan and Germany sustains limited production volumes.
Single-screw extruders hold the largest share; momentum sits with twin-screw configurations as recycled content mandates intensify.
Technology:
Technology selection correlates directly with barrier performance requirements and layer complexity, creating distinct cost tiers from commodity film to pharmaceutical-grade structures.
- Co-Extrusion:Simultaneous extrusion of multiple polymer streams through a single die produces multi-layer structures with tailored barrier properties. German and Italian OEMs lead export supply for food-contact and medical applications where EFSA and FDA migration limits apply.
- Multi-Layer Extrusion:Systems engineered for five to eleven discrete layers achieve oxygen and moisture barriers critical for pharmaceutical blister packs and retort pouches. Precision thickness control systems from Reifenhauser and Windmöller & Hölscher anchor European supply to North American pharmaceutical converters.
- Film Extrusion:Cast and blown film lines for flexible packaging substrates. Indonesian and Thai processors expand capacity here to capture demand migrating from China's coastal manufacturing zones.
- Blow Extrusion:Hollow profile production for bottles, tanks, and large-diameter pipes. Construction piping demand in India and Middle Eastern infrastructure projects sustains regional machinery assembly.
Co-extrusion commands the premium tier; multi-layer configurations are climbing the fastest as barrier specifications tighten.
End User:
End-use concentration varies sharply by geography, with packaging converters driving volume while automotive and electrical segments dictate precision specifications.
- Packaging:Flexible film, rigid containers, and barrier structures constitute the dominant demand pool. Southeast Asian converters in Vietnam and Indonesia scale capacity fastest, displacing older Chinese coastal operations for export-oriented food packaging.
- Automotive:Sealing profiles, interior trim, and under-hood tubing require heat-stabilized compounds and tight dimensional tolerance. German and Mexican automotive supplier parks sustain dedicated extrusion lines with just-in-sequence delivery requirements.
- Construction:PVC and PE piping, window profiles, and decking materials. Indian domestic demand under BIS quality mandates accelerates import substitution for multi-cavity profile lines.
- Electrical:Wire insulation, cable sheathing, and conduit systems. Cross-linked polyethylene specifications for medium-voltage cables require specialized screw designs and nitrogen cooling systems.
Packaging generates the highest unit volume; automotive specifications yield the steepest margin premiums.
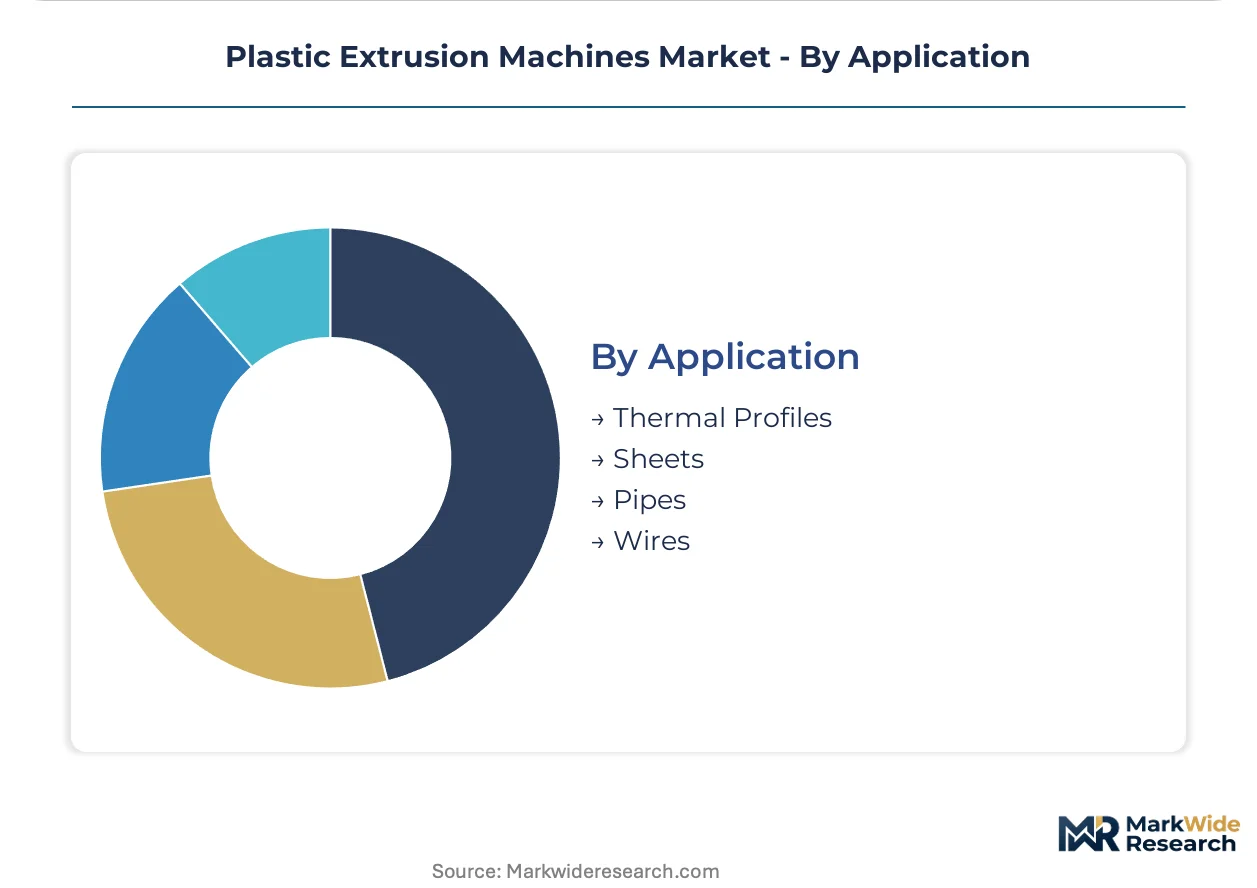
Application:
Application diversity spans thermal management, structural, and conductive functions, with each category imposing distinct rheological and cooling demands on machinery design.
- Pipes:Pressure-rated and drainage piping in PVC, PE, and PP compounds. Indian infrastructure investment and Middle Eastern construction pipelines sustain demand for large-diameter extrusion lines with vacuum calibration tanks.
- Sheets:Thermoforming substrates, signage, and construction panels. European processors adopt co-extruded sheet lines with recycled core layers to meet EU Green Deal circularity targets.
- Wires:Insulation and jacketing for power and communication cables. Cross-head extrusion dies with precise concentricity control serve automotive and renewable energy cabling requirements.
- Thermal Profiles:Heat-break inserts and insulating structural elements for window and facade systems. German passive house construction standards drive specification intensity for polyamide thermal break extrusion.
Pipes claim the greatest installed base; sheets are gaining share fastest through recycled-content integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German machinery builders export twin-screw systems to Southeast Asian compounders processing rPET feedstock, while Italian OEMs supply multi-layer blown film lines to North American pharmaceutical converters.
United States
Packaging retrofits and medical tubing specifications drive capital expenditure. FDA migration limits for food-contact barrel finishes extend equipment validation timelines. Converters in the Midwest industrial corridor negotiate direct spare parts sourcing agreements, bypassing traditional distributor networks for maintenance efficiency.
Germany
Passive house construction standards and automotive supplier park integration sustain precision extrusion demand. EU F-Gas Regulation phase-down schedules compress cooling section retrofit timelines for blown film processors. Machinery clusters in Baden-Württemberg and Bavaria specialize in co-extruded sheet lines with recycled core layers.
Vietnam
Flexible film capacity expansion captures demand migrating from China's aging coastal manufacturing zones. BIS-equivalent quality mandates from export buyers elevate specification requirements for imported lines. Ho Chi Minh City-based converters favor single-screw configurations for commodity-grade PE film production.
India
Domestic flexible packaging growth under BIS quality mandates creates demand for imported multi-layer blown film technology. Infrastructure investment in pressure-rated piping sustains large-diameter extrusion line procurement. Gujarat and Maharashtra processing bases drive import substitution for multi-cavity profile equipment.
Indonesia
Regional hub status for export-oriented food packaging attracts blown film capacity expansion. Japanese and European OEMs compete for pharmaceutical barrier line contracts. Jakarta and Surabaya industrial zones concentrate flexible film operations displacing older Chinese coastal capacity.
Plastic Extrusion Machines Market Key Industry Players
Listed leaders compete with private specialists across technology tiers and geographic coverage. The vendor base organizes around three structural positions: diversified industrial conglomerates with extrusion divisions, dedicated machinery builders with full product portfolios, and regional fabricators serving price-sensitive domestic markets. Consolidation pressure concentrates in the mid-market tier where scale advantages in service networks determine contract outcomes. Strategic moves center on technology licensing partnerships for real-time process control integration and backward integration into specialized alloy supply for barrel linings.
Within the diversified industrial tier, KraussMaffei and Davis-Standard occupy positions spanning medical-grade precision systems and packaging retrofit markets. Coperion exemplifies the specialized compounding equipment archetype with twin-screw expertise for reactive processing applications. These three anchors represent distinct competitive vectors: European engineering heritage, North American service network density, and process technology specialization respectively.
| Leading Market Players |
|---|
| Bausano |
| Davis-Standard |
| KraussMaffei |
| Kabra Extrusiontechnik |
| Milacron |
| Coperion |
| Leistritz |
| Toshiba Machine |
| Reifenhauser Group |
| Others |
Cost & Logistics Intelligence
Twelve-to-eighteen-month delivery windows for German-engineered twin-screw systems concentrate pricing power with Baden-Württemberg and Bavaria machinery clusters, while Southeast Asian buyers absorb premium freight costs for FDA-validated barrel finishes. This lead-time band compresses negotiation leverage for converters in Vietnam and Indonesia seeking medical-grade specifications, anchoring price premiums to alloy sourcing concentration rather than manufacturing scale alone.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA food-contact certification tier and bimetallic barrel alloy grade, with pharmaceutical barrier lines commanding substantial premiums over commodity packaging retrofits. Cost compression in standard-tier single-screw configurations is intensifying because Indonesian and Vietnamese converters prioritize capital efficiency over precision specifications. Mid-market packaging processors exhibit the highest price sensitivity, while North American medical tubing OEMs accept premium positioning for validated contamination controls.
Supply Chain Analysis
Strategic stockpile preferences for nickel and cobalt alloys distinguish German precision OEMs from just-in-time component sourcing among Southeast Asian fabricators. Supply concentrates in Germany, Italy, and Japan for specialized screw geometries and heat-treated barrel linings. Raw material dependencies draw from nickel ore processing, bimetallic centrifugal casting feedstock, and corrosion-resistant coating chemistries. Single-source vulnerability in cobalt supply from the Democratic Republic of Congo creates exposure for premium alloy pricing. Distribution runs through authorized service networks in North America and direct OEM relationships in emerging Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH recycled content mandates and FDA migration limit expansions are fragmenting demand across specification tiers, creating protected niches for precision-engineered suppliers and cost-optimized regional fabricators alike.
For Market Incumbents: Shield installed base revenue by locking in long-term refurbishment contracts for screw and barrel wear components before remote diagnostic platforms commoditize aftermarket service. Capacity addition in Gujarat and Maharashtra processing corridors captures Indian import substitution demand under BIS quality mandates. Backward integration into specialized alloy supply for barrel linings defends margin position against nickel cost volatility. For New Entrants and Emerging Players: Aftermarket remote diagnostics penetration gaps in the North American Midwest industrial corridor offer white-space entry below KraussMaffei and Davis-Standard service network density. Vietnamese single-screw packaging retrofits represent the most penetrable volume tier for cost-optimized configurations. A leasing-plus-maintenance bundled go-to-market angle bypasses capital-constrained converter procurement committees. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because buyer concentration among multinational packaging converters favors scaled service networks over fragmented regional fabricators. Acquisition targets should center on mid-market Italian and German OEMs with validated medical-grade process expertise but limited Asian distribution. Watch for FDA pre-submission meeting volume for novel barrel surface finishes as an inflection signal for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive nickel and cobalt sourcing insulates margin from DRC supply concentration risk. |
| Remote Diagnostic Platform Launch | AI-driven screw wear prediction compresses response times for North American refurbishment demand. |
| Medical-Grade Certification Investment | FDA-validated barrel finishes unlock pharmaceutical blister pack and tubing contract eligibility. |
| Joint Venture in Indian Regional Hub | Gujarat-based assembly addresses BIS-mandated flexible packaging growth with localized delivery. |
| Long-term Supply Agreement for rPET Systems | EU REACH compliance partnerships lock in twin-screw demand from European compounders. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with extrusion plant managers, OEM procurement teams at automotive and packaging converters, aftermarket service heads, and technical R&D directors at machinery builders. Secondary validation drew from SEC 10-K filings of listed industrial conglomerates, EU ECHA REACH authorization databases, FDA 510(k) and food-contact notification filings, and German mechanical engineering association (VDMA) export statistics. Bottom-up unit economics from individual line installations were triangulated against top-down capital expenditure surveys across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value trajectories by screw configuration type, technology tier, end-use industry concentration, and regional regulatory cluster. CAGRs were derived from polynomial trend fitting against historical replacement cycles and capacity expansion announcements. Industry-specific forecast inputs incorporated EU F-Gas Regulation retrofit timelines and Indian BIS quality mandate implementation pacing.
Underlying assumptions cover sustained rPET feedstock availability and REACH compliance enforcement continuity, with deviation risk concentrated in nickel supply disruption and FDA validation timeline extension. Forecasts reflect these documented conditions. Revision becomes warranted when alloy input cost volatility exceeds historical bands or when FDA pre-submission backlog crosses eighteen-month thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Global Hydraulic Ironworker Machine Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Die Casting Machinery Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Steel Fabrication Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
Computer Numerical Control Machines Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market