
 Sink Float Tank Market | 2026-2036
Sink Float Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Sink Float Tank Market Analytics
High-density separation-grade tank specifications is collapsing the gap between commodity and precision mineral processing equipment. Metso Outotec Corporation leverages its installed base in hard-rock mining to sustain aftermarket service revenues across Nordic and Australian operations. Eriez Manufacturing Co. competes through magnetic separation integration, while Gekko Systems Pty Ltd. specializes in modular, containerized plant designs for remote gold and polymetallic projects.
A sink float tank employs density-based separation using a fluid medium—typically water or dense slurry—to stratify materials by specific gravity, with tank depths ranging from two to six meters and throughput capacities scaling from laboratory-scale batch units to industrial continuous-flow systems processing hundreds of tonnes per hour. Modular Systems command premium positioning due to shorter commissioning cycles and lower civil engineering requirements at greenfield sites. Fiberglass construction leads in corrosive-environment applications such as salt-laden placer deposits, while Steel dominates high-wear mineral sands operations where abrasion resistance determines equipment life.
The EPA enforces effluent limitations under the Clean Water Act that directly constrain process water chemistry in US-based sink float operations, while the EU REACH framework governs chemical additives used in dense medium suspensions across European recycling and mining applications. China's MEE implements discharge standards that force domestic operators toward closed-loop water circuits. Stakeholders must weigh capital allocation between dense medium cyclone retrofits and next-generation sensor-based sorting as complementary or competing separation pathways.
Market Dynamics
Dense medium cyclone retrofits are forcing capital reallocation decisions across mineral processing and recycling operations, compressing the traditional equipment replacement cycle as operators weigh sensor-based sorting alternatives against tank-based density separation.
Growth Catalysts
- EU Green Deal mandates:Circular material recovery targets in Germany are accelerating sink float tank deployment at plastic recycling facilities to achieve mandated recycling rates.
- Modular containerized designs:Remote gold and polymetallic projects in Australia and the Nordic region are adopting skid-mounted systems to bypass civil engineering bottlenecks.
- Closed-loop water circuits:China's MEE discharge standards are driving domestic operators toward water-recycling tank configurations that reduce freshwater intake.
Market Restraints
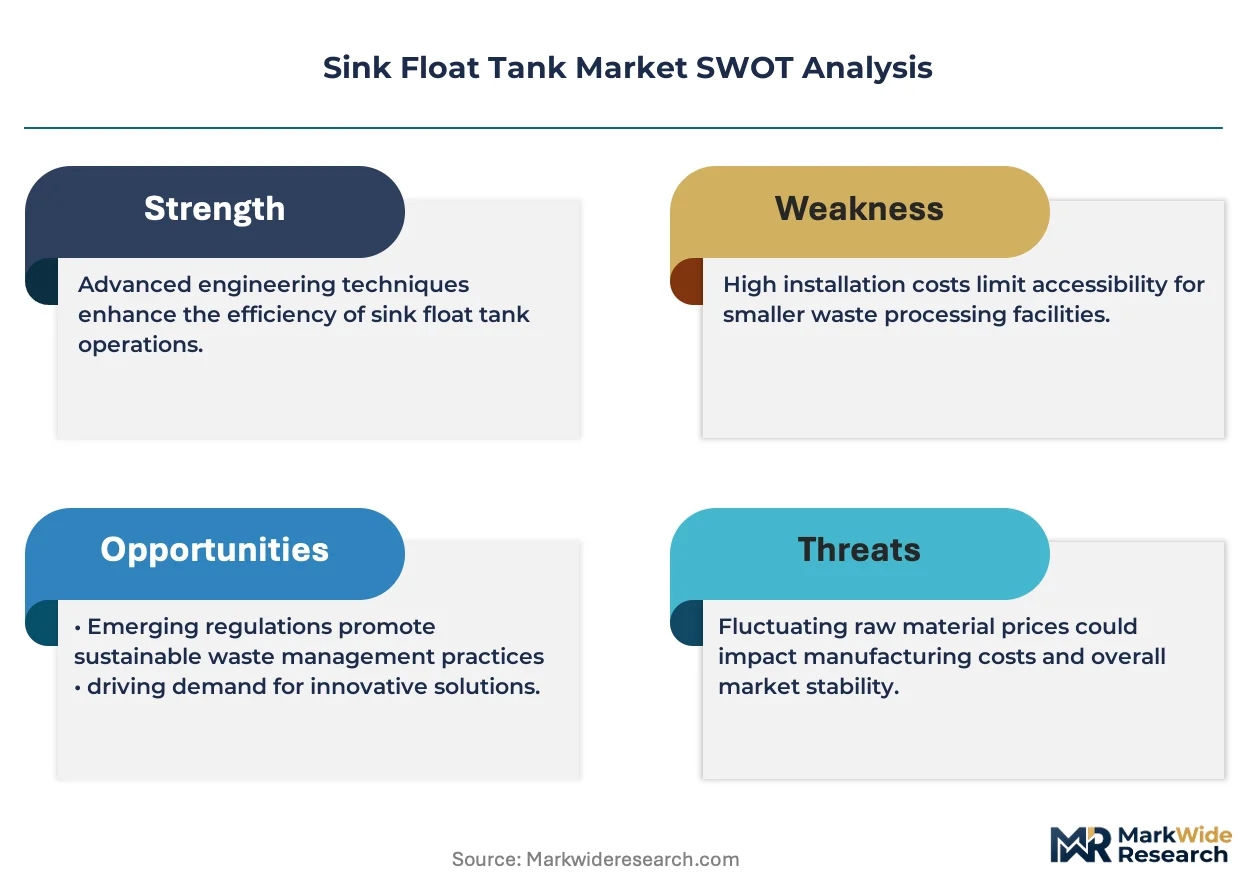
- Ferrosilicon price volatility:Dense medium suspension costs fluctuate with alloy input prices, squeezing operating margins at high-throughput mineral sands operations.
- Steel supply concentration:Abrasion-resistant tank fabrication depends on specialized metallurgical suppliers concentrated in East Asian foundry clusters.
- Sensor-based sorting substitution:X-ray transmission and near-infrared systems are capturing fractions previously routed to density separation, limiting tank demand growth in certain feed streams.
Strategic Opportunities
- India's urban mining sector:Informal e-waste collection networks present untapped feedstock potential for precious metal recovery operations requiring density pre-concentration.
- Fiberglass corrosion resistance:Salt-laden placer deposits in coastal jurisdictions are creating specification openings for non-metallic tank construction.
- Battery black mass processing:Lithium-ion recycling flows are emerging as a new application vector as cathode and anode density differentials enable sink float pre-sorting.
Industry Challenges
- Dense medium rheology expertise:Operating stability requires specialized knowledge of suspension viscosity and stability that is scarce outside established mining jurisdictions.
- Legacy control system integration:Brownfield sites face protocol mismatches when connecting modern tank automation to existing distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sink Float Tank Market |
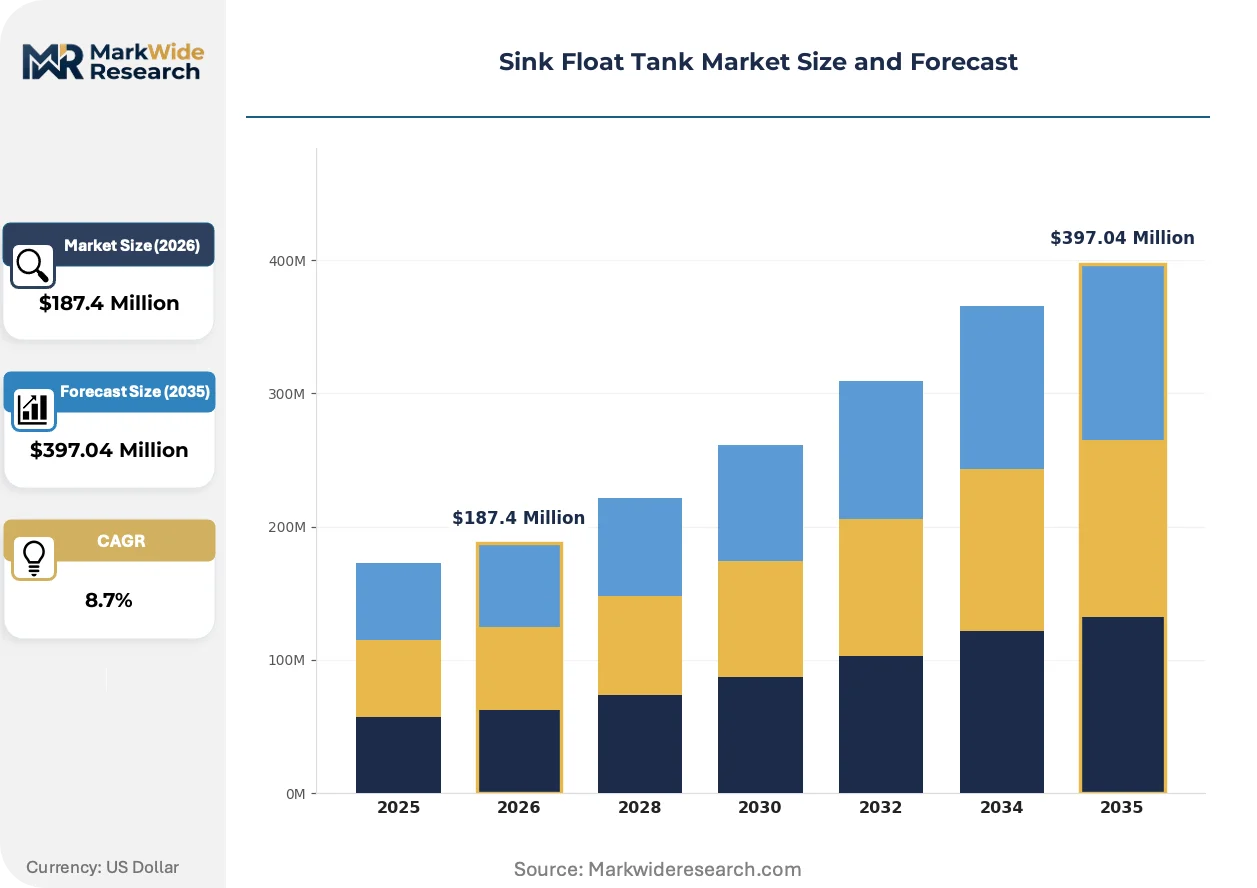
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Scale Tanks, Portable Units, Modular Systems, In-Ground Tanks Material: PVC, Fiberglass, Steel, Concrete Application: Industrial Testing, Educational Institutions, Research Labs, Recreational Use End User: Manufacturers, Universities, Research Organizations, Fitness Centers |
| Companies Covered | Multotec Group, Metso Outotec Corporation, Eriez Manufacturing Co., FLSmidth A/S, Glencore Technology, Tenova S.p.A., JKTech, Forsyths Limited, Gekko Systems Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sink Float Tank Market Evolving Landscape
Process intensification and digital instrumentation are compressing the traditional gap between laboratory-scale testing and industrial deployment, enabling faster validation cycles for new feedstock applications.
Automated density control systems are bifurcating the operator skill requirements across the installed base. Tier-one mining houses in Australia and South Africa are deploying real-time suspension monitoring with machine-learning setpoint optimization, reducing manual intervention. This technology compression is squeezing mid-tier operators who lack capital for automation retrofits into higher opex manual control regimes.
The EPA's Clean Water Act effluent limitations are tightening process water chemistry constraints at US-based operations. Operators must now document heavy metal discharge profiles and adjust flocculant chemistries to maintain compliance. Coal preparation plants in Appalachia and phosphate beneficiation facilities in Florida are most affected, with several sites pursuing zero-liquid-discharge tank circuit redesigns.
After-sales service unbundling is disrupting the traditional equipment procurement model. End-users in Brazil and South Africa are separating capital acquisition from maintenance contracts, sourcing spare wear components through independent distributors rather than original equipment channels. This channel fragmentation is most visible in high-wear mineral sands operations where impeller and densifier cone replacement cycles drive recurring expenditure.
Sink Float Tank Market Segmentation
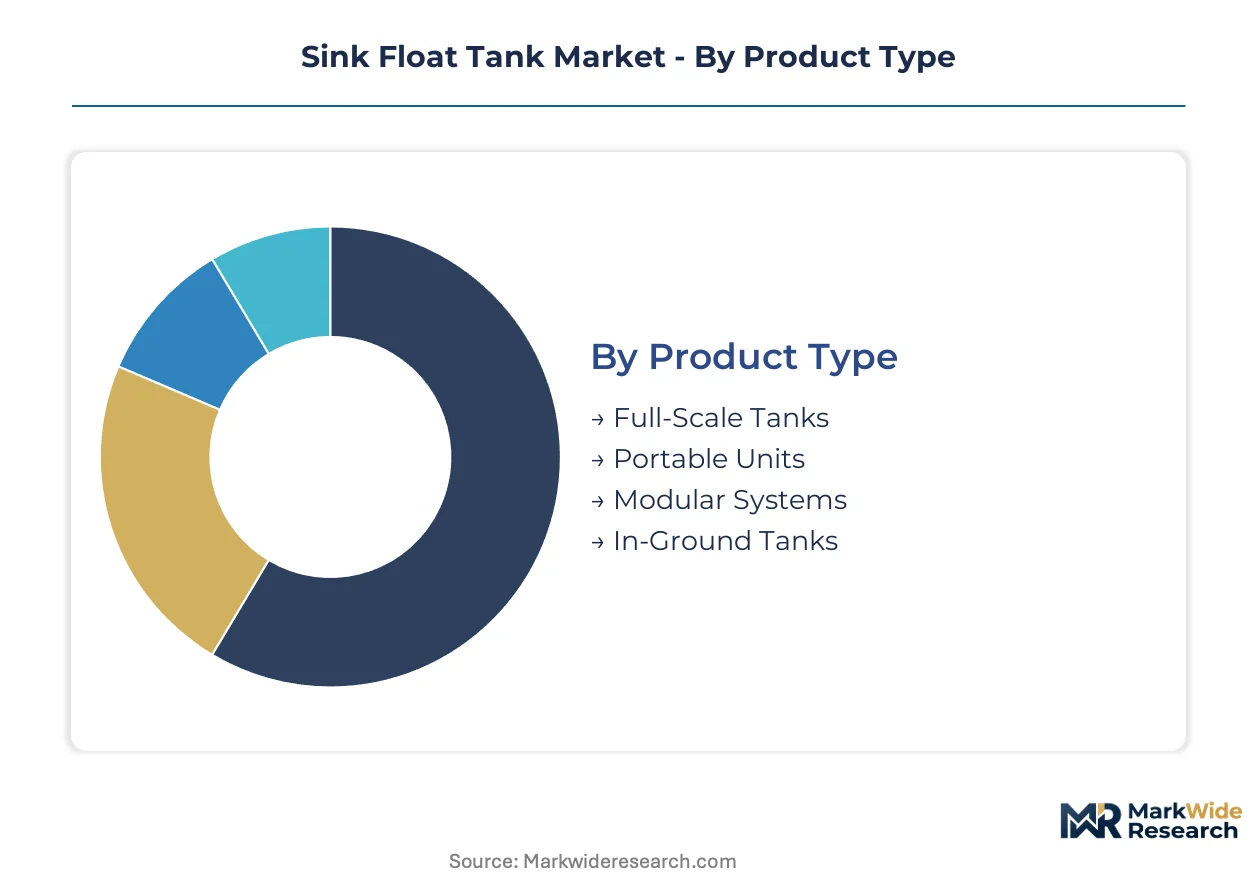
Segmentation in the sink float tank market reveals distinct procurement patterns across installation permanence, material durability requirements, and operational intensity. Each dimension carries specific implications for capital deployment cycles and aftermarket service attach rates.
Product Type:
Domestic demand concentrates in permanent infrastructure solutions across Germany and China, while export-led growth flows from Australian and Nordic suppliers specializing in rapid-deployment formats for remote mining camps.
- Full-Scale Tanks:These fixed installations span two to six meters in depth with continuous-flow processing capabilities exceeding hundreds of tonnes per hour. German plastic recycling facilities under EU Green Deal mandates are expanding full-scale capacity to achieve mandated circular material recovery rates.
- Modular Systems:Skid-mounted and containerized configurations compress commissioning cycles by eliminating civil engineering bottlenecks. Remote gold and polymetallic projects across Australia and the Nordic region favor these units for their relocation flexibility and reduced site preparation requirements.
- Portable Units:Laboratory-scale batch systems serve mobile testing requirements at exploration sites and temporary processing operations.
- In-Ground Tanks:Permanent excavated installations dominate high-throughput mineral sands operations where structural integration with material handling infrastructure reduces operational footprint.
Full-Scale Tanks hold the largest share; momentum sits with Modular Systems.
Material:
Cost tier stratification separates premium corrosion-resistant specifications from commodity abrasion-grade alternatives, with selection driven by chemical exposure severity and particle wear intensity.
- Steel:Abrasion-resistant metallurgical grades dominate mineral sands operations where high-velocity particle streams dictate equipment life. Supply concentration in East Asian foundry clusters creates procurement vulnerability for operators outside the region.
- Fiberglass:Non-metallic construction resists salt-laden corrosion in coastal placer deposits and chemical attack from aggressive process chemistries. Salt-laden jurisdictions in Australia and Southeast Asia specify fiberglass for extended service intervals.
- PVC:Lower capital cost positions this material for educational and laboratory-scale applications with moderate chemical exposure.
- Concrete:Permanent in-ground installations leverage concrete for structural rigidity and thermal mass in climate-sensitive operations.
Steel commands the largest installed base; Fiberglass is expanding most quickly in corrosive-environment specifications.
Application:
Volume concentration separates continuous industrial processing from intermittent research and educational usage, with throughput requirements determining automation level and control system sophistication.
- Industrial Testing:Continuous-density validation for process optimization and quality control at mining and recycling facilities. China's MEE discharge standards are forcing domestic operators toward closed-loop water circuits that intensify testing frequency.
- Research Labs:Method development and feedstock characterization for novel separation applications including lithium-ion battery black mass processing. Precious metal recovery operations in India's urban mining sector require density pre-concentration validation.
- Educational Institutions:Training installations for mineral processing and materials engineering curricula.
- Recreational Use:Sensory deprivation and float therapy applications with minimal relation to industrial separation technology.
Industrial Testing holds the largest share; Research Labs are gaining share fastest on battery recycling application development.
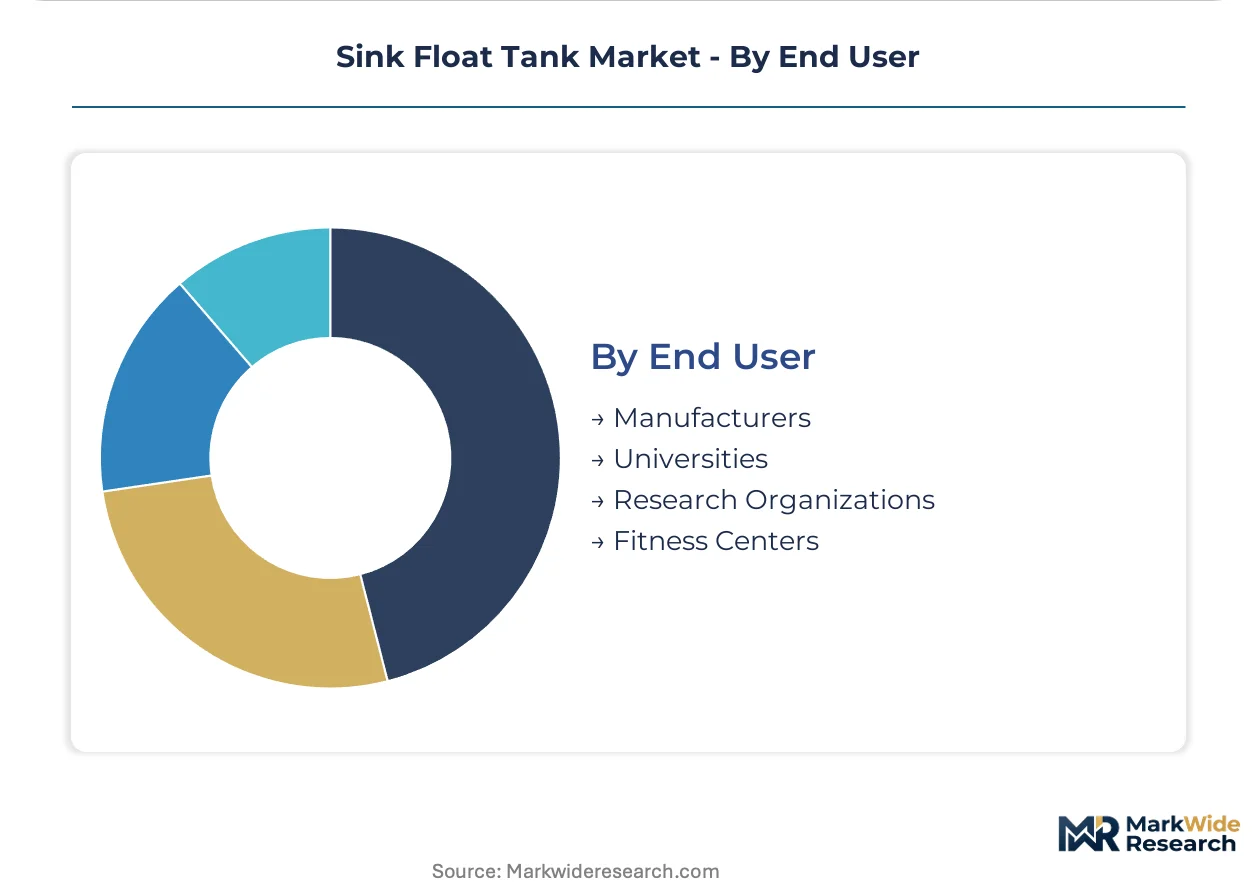
End User:
Customer type determines procurement authority structure, with integrated manufacturers exercising capital budget control distinct from institutional purchasing committees at universities and research organizations.
- Manufacturers:Mining houses and recycling operators with direct P&L accountability for separation efficiency. Tier-one Australian and South African mining houses deploy real-time suspension monitoring with machine-learning setpoint optimization.
- Research Organizations:National laboratories and contract research facilities evaluating novel feedstock applications and process intensification pathways.
- Universities:Academic institutions with capital equipment procurement cycles tied to grant funding and curriculum development priorities.
- Fitness Centers:Wellness service providers with no operational overlap to industrial density separation markets.
Manufacturers hold the largest share; Research Organizations show the steepest expansion trajectory on battery recycling and urban mining program growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian and Nordic suppliers export modular containerized systems to remote mining camps across Southeast Asia and Africa, while German fabricators ship full-scale permanent installations to plastic recycling facilities throughout the EU.
Germany
Plastic recycling facilities in North Rhine-Westphalia and Bavaria are expanding sink float tank capacity to meet EU Green Deal circular material recovery mandates. The EU REACH framework governs chemical additives in dense medium suspensions used across these operations. Industrial clusters in the Ruhr Valley concentrate equipment deployment for post-consumer packaging separation.
China
Domestic reprocessing capacity expansion drives demand for closed-loop water circuit configurations in Jiangsu and Shandong provinces. The MEE implements discharge standards that force operators toward water-recycling tank designs. Yangtze River Delta manufacturers are scaling production of abrasion-resistant steel tank fabrications for mineral sands customers.
United States
Coal preparation plants in Appalachia and phosphate beneficiation facilities in Florida pursue zero-liquid-discharge circuit redesigns under tightening EPA Clean Water Act effluent limitations. The EPA enforces heavy metal discharge documentation requirements that constrain process water chemistry. Equipment procurement concentrates around Pittsburgh and Houston industrial supply corridors.
Australia
Remote gold and polymetallic projects in Western Australia and Queensland favor skid-mounted modular systems to bypass civil engineering bottlenecks. Real-time suspension monitoring with machine-learning setpoint optimization deploys across tier-one mining houses. Perth-based engineering firms supply containerized plants to Indonesian and Papua New Guinean operations.
South Africa
Mineral sands operations on the KwaZulu-Natal coast specify fiberglass construction for salt-laden corrosion resistance. After-sales service unbundling allows end-users to source spare wear components through independent distributors rather than OEM channels. The Gauteng industrial corridor hosts fabrication capacity for high-wear steel tank variants.
Sink Float Tank Market Competitive Landscape
Listed leaders compete with private specialists across capital equipment and aftermarket service segments. The vendor base spans multinational mining technology conglomerates, regional fabrication specialists, and niche modular system designers. Strategic archetypes include hard-rock mining aftermarket service providers, magnetic separation integrators, and containerized plant specialists. Competitive moves concentrate on geographic expansion through distributor networks and technology licensing arrangements for dense medium suspension control systems.
Within the aftermarket service tier, Metso Outotec Corporation and Multotec Group exemplify the hard-rock mining heritage archetype, leveraging installed bases to sustain recurring revenue streams. Eriez Manufacturing Co. occupies a position among magnetic separation integrators competing through complementary technology bundling. Gekko Systems Pty Ltd. anchors the modular specialization segment with containerized designs for remote deployment. These three represent distinct competitive vectors rather than direct substitutes, with each archetype capturing different procurement authority structures across mining houses and recycling operators.
| Leading Market Players |
|---|
| Multotec Group |
| Metso Outotec Corporation |
| Eriez Manufacturing Co. |
| FLSmidth A/S |
| Glencore Technology |
| Tenova S.p.A. |
| JKTech |
| Forsyths Limited |
| Gekko Systems Pty Ltd. |
| Others |
Value Network & Pricing Analysis
EU REACH compliance certification gates both supplier qualification and price tier differentiation in dense medium suspension equipment, separating premium fiberglass specifications from commodity steel alternatives while constraining chemical additive sourcing to approved vendor lists. Buyers face dual certification burdens—equipment CE marking plus suspension chemistry disclosure—that compress margin flexibility at lower price points.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by abrasion-resistant metallurgical grade and after-sales service bundling. Cost compression in standard-grade steel tanks is intensifying because ferrosilicon price volatility squeezes operating margins at high-throughput mineral sands operations. Small-scale recycling operators in India's urban mining sector exhibit highest price sensitivity, while tier-one Australian mining houses prioritize automation integration over unit cost.
Supply Chain Analysis
China and South Korea anchor abrasion-resistant steel fabrication for tank construction, while Germany and Australia specialize in modular system assembly. Production draws from East Asian ferrosilicon foundries, Nordic fiberglass composite suppliers, and domestic steel rolling mills in consuming markets. Single-source vulnerability concentrates in specialized metallurgical grades from East Asian clusters. Distribution runs through OEM direct sales for full-scale installations and independent distributors for aftermarket wear components in South Africa and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where dense medium suspension control systems are becoming interoperable across OEM brands, collapsing proprietary lock-in and enabling third-party automation retrofits. Ecosystem openness is accelerating service unbundling and channel fragmentation.
For Market Incumbents: Shield installed-base revenues by deepening aftermarket service attach rates through predictive maintenance subscriptions for suspension density monitoring. Counter sensor-based sorting substitution threats by bundling tank retrofits with machine-learning control upgrades. Prioritize certification investment in EU REACH-compliant chemical additive portfolios to maintain specification access in German plastic recycling clusters.
For New Entrants and Emerging Players: CE marking fast-track for fiberglass modular systems opens white-space penetration in salt-laden coastal placer deposits across Southeast Asia and West Africa. Target India's informal e-waste collection networks with portable batch units for precious metal pre-concentration validation. Pursue battery black mass processing applications through research lab partnerships that generate reference installations before industrial scale-up.
For Investors and Strategic Acquirers: EPA Clean Water Act enforcement tightening reshapes the acquisition landscape toward zero-liquid-discharge technology portfolios with documented compliance track records. Long-term viability favors targets with dense medium rheology expertise and closed-loop water circuit IP. Watch for MEE discharge standard revisions in China as inflection indicators for water-recycling configuration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular System Platform Integration | Containerized designs from Australian suppliers bypass civil engineering bottlenecks at remote African and Indonesian sites. |
| Backward Integration into Ferrosilicon Supply | Captive alloy sourcing insulates high-throughput operators from price volatility in East Asian spot markets. |
| Sensor-Based Sorting Partnership | X-ray transmission bundling with tank-based pre-concentration defends share against pure-play optical sorters. |
| Battery Recycling Application Development | Lithium-ion black mass validation programs at research labs generate reference data for cathode-anode separation. |
| Aftermarket Service Unbundling | Independent distributor channels in Brazil and South Africa fragment OEM recurring revenue streams. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads; and secondary validation through customs trade data, SEC equipment supplier filings, MEE discharge standard documentation, and EU REACH chemical registry entries. Bottom-up installation counts triangulated against top-down mineral processing and recycling capacity estimates.
Across the analysis window, projections model product type permanence, material durability requirements, application throughput intensity, and end-user procurement authority structure. CAGRs derive from segment-level volume builds reconciled to aggregate market boundary conditions. Forecast inputs incorporate ferrosilicon price trajectory assumptions and water discharge regulatory enforcement intensity by jurisdiction.
Decision-makers should treat outputs as directional under stable alloy input costs and regulatory enforcement continuity; material deviation in ferrosilicon markets or MEE standard revisions would warrant model refresh. Recalibration cycles align with material shifts in EU Green Deal mandate implementation timelines and battery recycling feedstock availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
Silos Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
Timber Construction Connectors Market