
 Architectural Membrane Market | 2026-2036
Architectural Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Architectural Membrane Market Analysis
European PTFE and silicone-coated glass fabric producers is recalibrating capacity toward longer-span stadium commissions. Saint-Gobain leverages its integrated glass fiber supply chain to anchor premium tensile structure contracts across Western Europe. Serge Ferrari competes through specialized fluoropolymer coating technology that sustains differentiation in facade and canopy specifications. Taiyo Kogyo Corporation dominates permanent installation projects across East Asia, where its membrane engineering expertise controls access to Olympic-caliber venues.
Architectural membranes are high-performance polymer or glass-fiber fabrics, typically PTFE-coated fiberglass or PVC-coated polyester, engineered to span large distances with minimal structural support while transmitting controlled daylight and withstanding wind, snow, and UV loads. Their primary purpose is to create lightweight, durable enclosures for sports facilities, transit hubs, and public gathering spaces. Tensile structures lead the product type landscape due to decades of proven performance in stadium roofs, while ETFE cushions are displacing conventional glazing in facade applications where weight reduction and thermal performance converge. Among end users, commercial developments concentrate the largest project value, though recreational installations represent the fastest-growing application channel as municipalities fund adaptive canopy systems for parks and waterfronts.
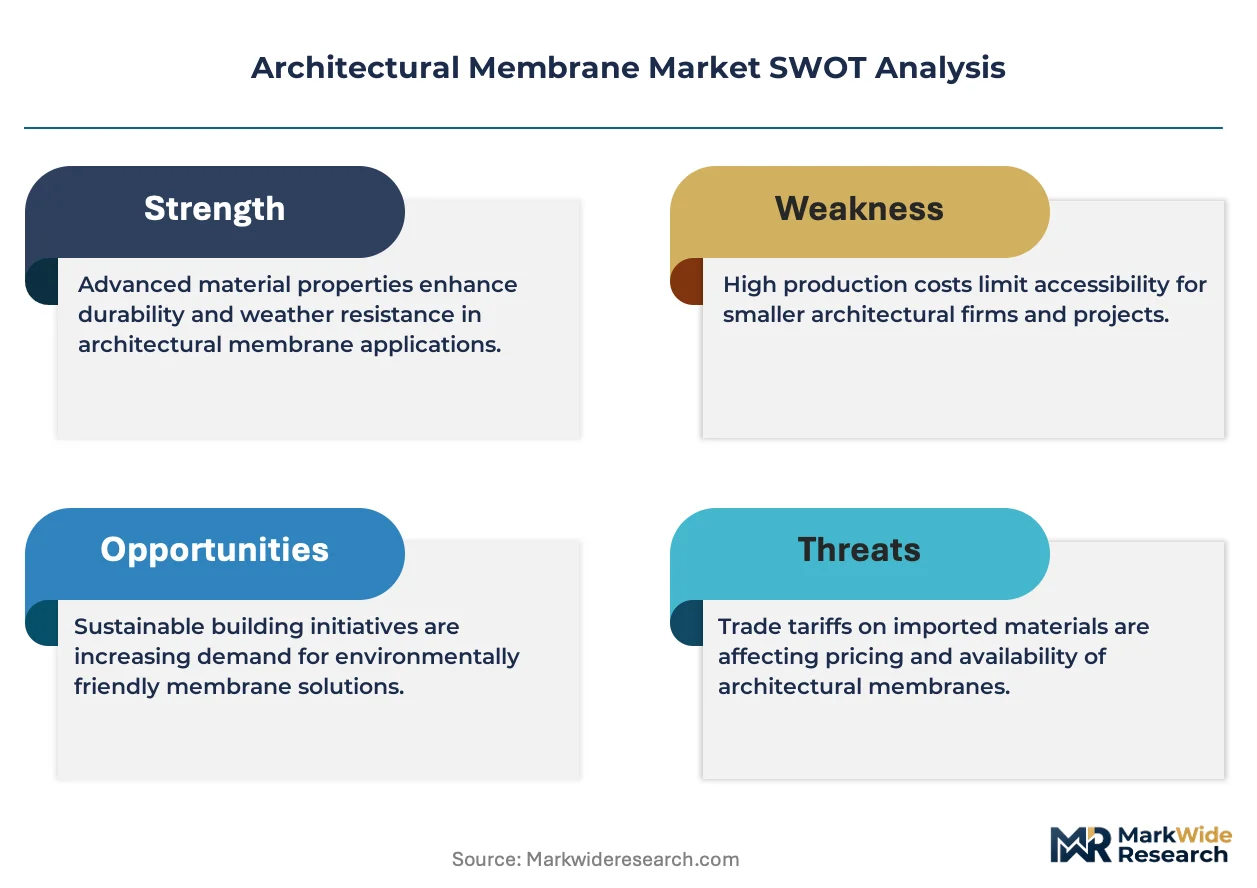
REACH and the EU F-Gas Regulation restrict fluorinated compound formulations used in membrane coatings, compelling reformulation toward lower-GWP alternatives. In the United States, ASTM E84 and NFPA 701 flame-spread standards govern membrane approval for public assembly structures, creating compliance barriers for imported materials. China's GB standards for membrane structures enforce wind-load and fire-resistance testing that shapes domestic procurement. Stakeholders must monitor evolving fire-safety codes and embodied-carbon disclosure requirements as project owners weigh total lifecycle performance against upfront material selection.
Market Dynamics
The EU F-Gas Regulation is compressing fluoropolymer coating availability while stadium architects specify longer clear spans, forcing membrane producers to reformulate or surrender premium contracts to competitors with compliant chemistries.
Growth Catalysts
- Stadium roof retrofits:Aging 1990s tensile structures across Western Europe require membrane replacement, creating recurring revenue streams for specialist contractors with proven installation records.
- REACH-compliant fluoropolymer alternatives:Coating innovators developing lower-GWP formulations capture market access denied to legacy PTFE suppliers unable to reformulate.
- Transit hub modernization:Airport expansion in the United Arab Emirates and Saudi Arabia specifies ETFE cushion systems for passenger comfort and daylight optimization.
Market Restraints
- Glass fiber supply concentration:Premium E-glass roving production clusters in China and Germany, exposing Western membrane fabricators to freight cost volatility and tariff exposure.
- Silicone raw material bottlenecks:Methyl chlorosilane monomer supply tightens periodically due to integrated chemical complex outages, disrupting silicone-coated fabric lead times.
- Steel substitution in short spans:Conventional space-frame roofing with metal cladding retains cost advantage below 40-meter spans, capping membrane addressable market in smaller venues.
Strategic Opportunities
- Adaptive waterfront canopies:Coastal municipalities in Australia fund retractable membrane systems for public pavilions, opening a recreational application channel with lower engineering complexity than stadiums.
- Photovoltaic membrane integration:Organic and thin-film solar cell lamination onto tensile substrates enables energy-generating building envelopes, converging two previously separate procurement categories.
- Carbon disclosure mandates:The EU CSRD requires embodied-carbon reporting for construction materials, creating competitive advantage for membrane producers with verified lifecycle data versus opaque imports.
Industry Challenges
- Specialized installation labor scarcity:Certified tensile structure riggers command premium wages and limited availability, extending project timelines and inflating owner costs beyond material budgets.
- Fire certification fragmentation:ASTM E84, NFPA 701, and EN 13501 test protocols yield non-comparable ratings, forcing producers to maintain multiple product variants and testing regimens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Architectural Membrane Market |
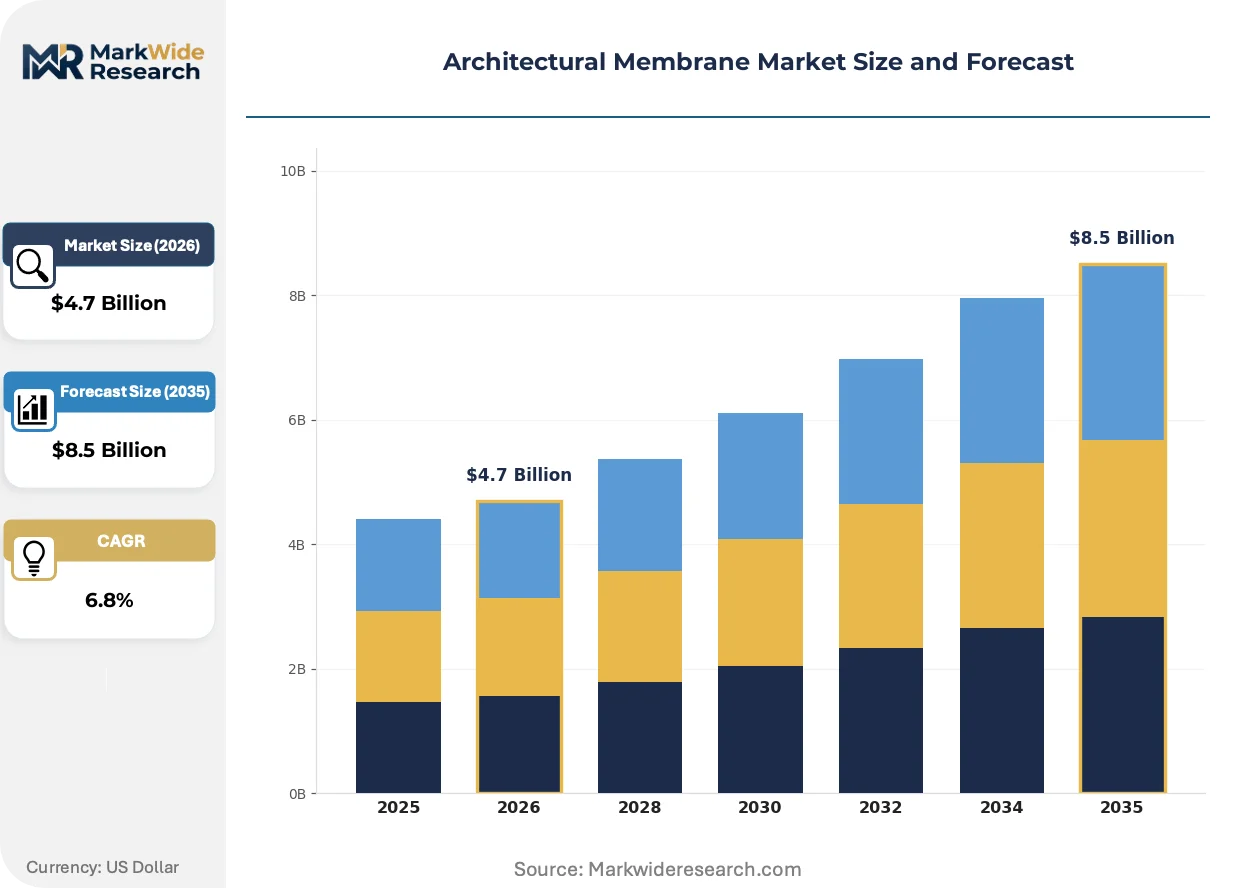
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tensile Structures, ETFE, PVC, PTFE Application: Infrastructure, Stadiums, Canopies, Facades End User: Commercial, Residential, Educational, Recreational Installation Type: Permanent, Temporary, Adaptive, Custom |
| Companies Covered | Saint-Gobain, Hiraoka, Seaman Corp, Serge Ferrari, Mehler Texnologies, Sika, Chukoh Chem, Taiyo Kogyo Corporation, Atex Membrane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Architectural Membrane Market Emerging Trajectories
Membrane engineering is converging with energy-system design and digital fabrication, compressing the traditional separation between structural, environmental, and aesthetic performance in building envelopes.
Transparent conductive oxide coating on ETFE film is unifying electromagnetic shielding, thermal control, and daylight transmission in a single substrate layer. Airport terminal designers in Germany and Singapore specify these multifunctional membranes for passenger boarding bridges and atrium roofs. The technology is compressing the supplier base by eliminating separate procurement of shading systems and RF shielding.
REACH authorization procedures for perfluorinated substances are tightening coating formulation options across the European Economic Area. Membrane producers with in-house polymer synthesis capabilities retain flexibility while toll-coating operations face ingredient obsolescence. Façade specifications in France and the Netherlands now exclude non-compliant materials regardless of price competitiveness.
Design-build procurement for sports venues is consolidating engineering and material selection under single-contractor accountability. Municipal stadium authorities in the United States and Australia favor this model over traditional design-bid-build sequences. The shift compresses membrane supplier engagement windows and rewards firms with rapid structural analysis capabilities and in-house installation teams.
Architectural Membrane Market Segmentation
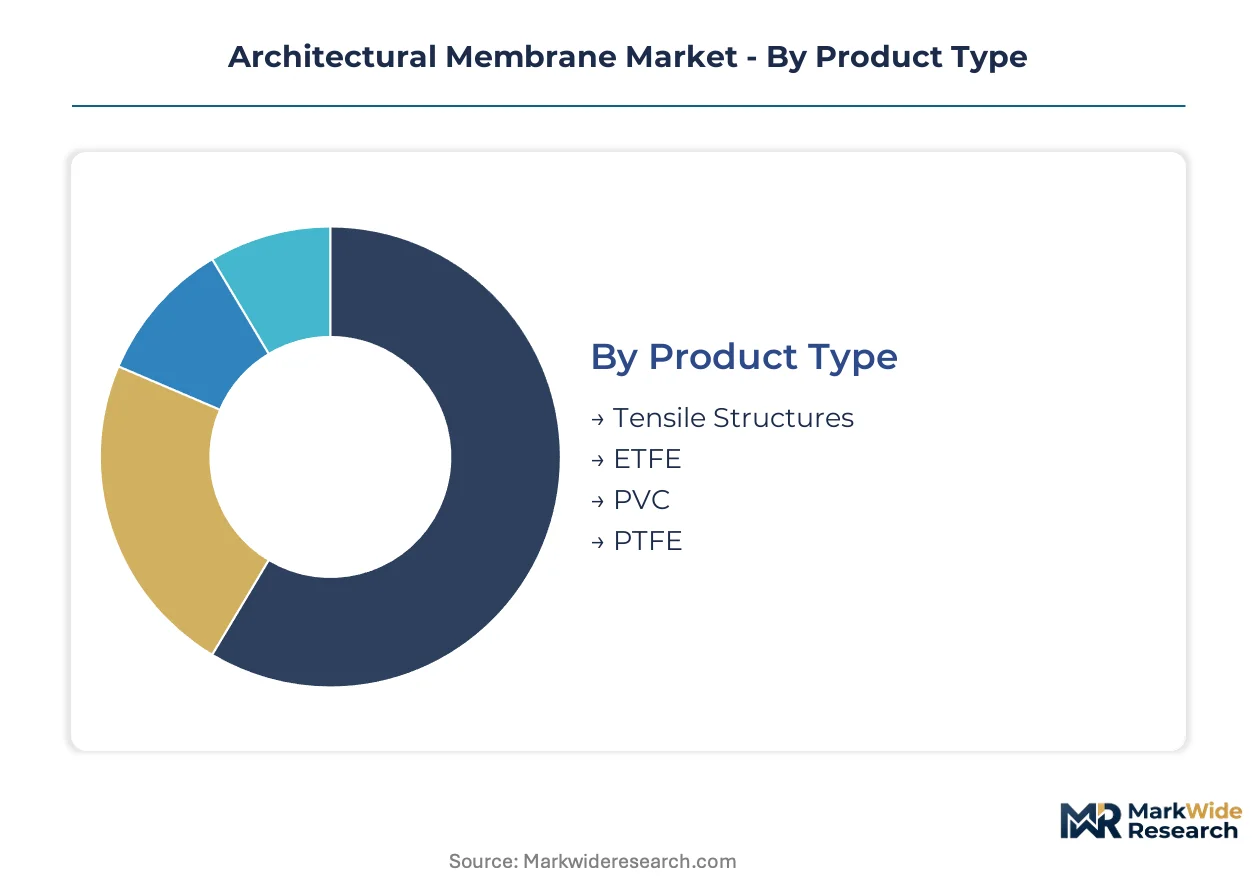
Architectural membrane procurement diverges sharply by structural permanence, coating chemistry, and end-use risk tolerance. Specification engineers weight fire certification, span capability, and lifecycle cost differently across each segment boundary.
Product Type:
Volume concentrates in proven tensile substrates while premium applications migrate toward advanced fluoropolymer systems.
- Tensile Structures:Woven PTFE-coated fiberglass or PVC-coated polyester fabrics engineered for cable-supported spans exceeding 50 meters. Stadium roof commissions in Germany and China specify these systems for their 25-30 year service life under snow and wind loads.
- ETFE:Ethylene tetrafluoroethylene film supplied in single-layer or pneumatic cushion configurations, weighing less than 1% of equivalent glass. Airport terminals in the United Arab Emirates deploy ETFE cushions for thermal performance and passenger daylighting.
- PVC:Polyvinyl chloride-coated polyester mesh offering lower capital cost for temporary installations and seasonal enclosures.
- PTFE:Polytetrafluoroethylene resin coatings on glass fiber substrates delivering maximum UV resistance and self-cleaning surface properties for permanent facades.
Mature deployment sits with Tensile Structures. Newer deployment is concentrated in ETFE.
Application:
Engineering complexity and regulatory scrutiny scale with public occupancy density and structural span length.
- Stadiums:Large-span roof structures requiring wind-tunnel validation and crowd-loading analysis under EN 1991 standards. Olympic-caliber venues in East Asia drive specification intensity for PTFE-glass systems with integrated lighting and acoustic treatments.
- Canopies:Pedestrian shelter and entrance structures spanning 10-40 meters, often specifying retractable or tensioned fabric for weather protection. Municipal parks in Australia fund adaptive canopy systems for waterfront public spaces.
- Infrastructure:Transit hub roofs, station canopies, and bridge enclosures where membrane integration with steel or concrete superstructure demands specialized detailing.
- Facades:Building envelope applications where ETFE cushions or tensioned screens replace conventional glazing for weight reduction and solar control.
Permanent installation dominates Infrastructure. Adaptive and retractable systems are expanding most quickly in Canopies.
End User:
Procurement authority and maintenance budgeting capacity vary dramatically across ownership structures.
- Commercial:Private developers and corporate campuses specifying signature architecture with lifecycle cost accountability. Retail and office projects in Western Europe prioritize CSRD-compliant embodied-carbon disclosure for membrane selection.
- Recreational:Municipal parks departments and leisure operators funding seasonal or adaptive canopy installations with lower engineering complexity than stadiums. Coastal municipalities in Australia represent a concentrated demand channel.
- Educational:University campuses and school districts specifying covered walkways and assembly spaces with constrained capital budgets.
- Residential:Private homeowners and residential developers deploying small-scale tensioned structures for pool enclosures and garden pavilions.
Commercial end users anchor project value concentration. Recreational installations are gaining share fastest as public space adaptation funding expands.
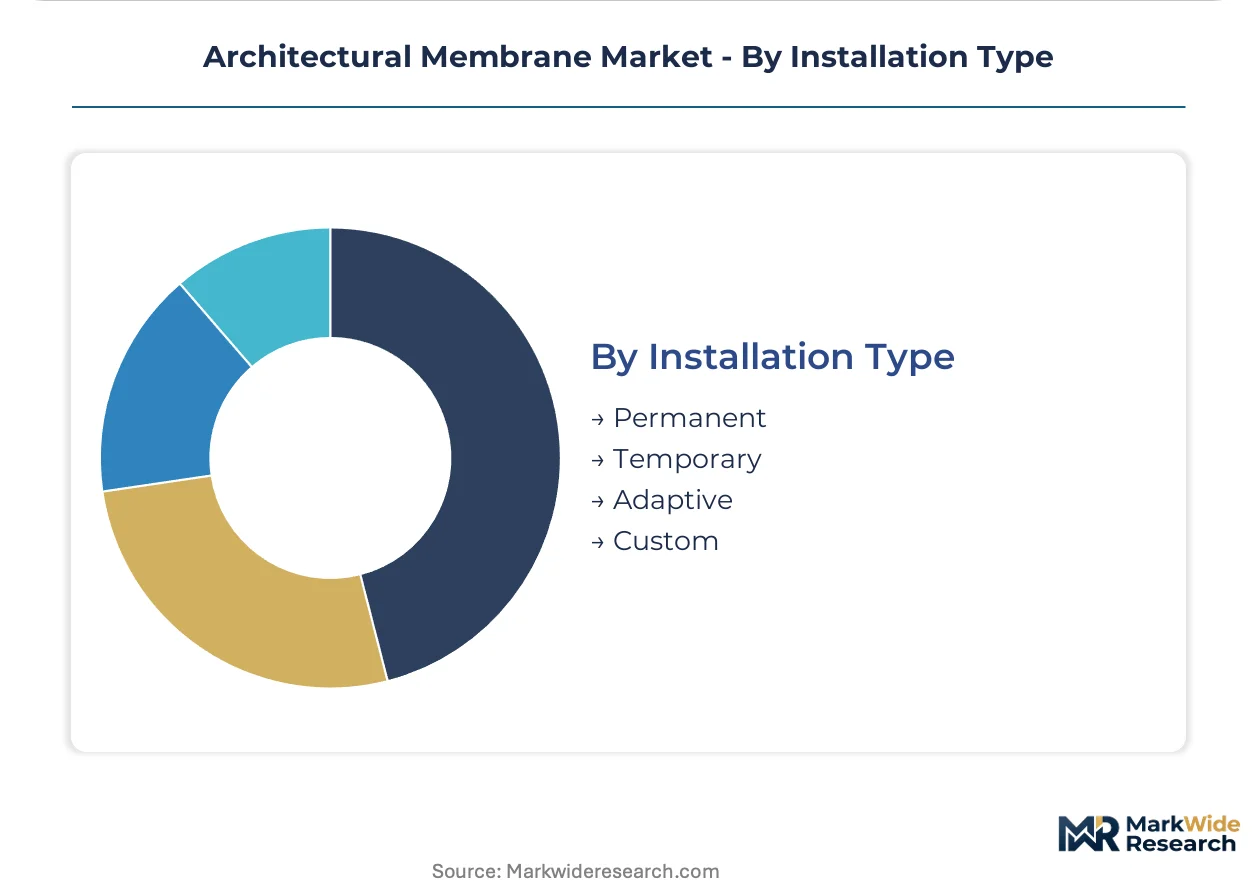
Installation Type:
Contracting structure and supplier engagement depth correlate with permanence and customization requirements.
- Permanent:Fixed cable-supported or frame-mounted systems requiring certified installation crews and long-term maintenance contracts. Design-build procurement for sports venues in the United States consolidates engineering and material selection under single-contractor accountability.
- Adaptive:Mechanically operated retractable or deployable membrane systems for weather-responsive enclosures. Waterfront pavilions in Australia specify these for seasonal programming flexibility.
- Temporary:Rapid-assembly tensioned structures for events, construction site coverage, or emergency shelter with 1-5 year service life.
- Custom:Bespoke geometry requiring project-specific patterning, cutting, and seam welding for non-standard architectural forms.
Permanent installations retain the largest project scale. Adaptive systems represent the steepest expansion trajectory as municipalities fund responsive public infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass fiber roving production clusters in Germany and China anchor membrane supply chains. Stadium commissions in the UAE and Australia drive premium specification demand. Regulatory divergence across REACH, ASTM, and GB standards fragments procurement patterns.
Germany
Stadium roof retrofits and transit hub expansions concentrate demand in the Rhine-Ruhr and Bavarian regions. The EU F-Gas Regulation and REACH authorization procedures compel coating reformulation toward lower-GWP fluoropolymer alternatives. Stuttgart and Munich engineering clusters host specialist tensile structure contractors with Olympic-caliber installation records.
China
Domestic E-glass fiber production and GB standards enforcement for wind-load testing shape procurement. The country's dual carbon goals and MIIT industrial policy accelerate embodied-carbon disclosure requirements for public infrastructure. Yangtze River Delta fabricators supply PTFE-coated glass fabric for signature sports venues.
United Arab Emirates
Airport terminal expansions and waterfront leisure developments specify ETFE cushion systems for thermal performance. MOHAP building codes and Dubai Municipality fire-safety standards govern membrane approval for high-occupancy structures. Abu Dhabi and Dubai anchor design-build procurement for adaptive canopy commissions.
Australia
Coastal municipalities fund retractable membrane systems for public pavilions and waterfront programming. TGA-equivalent state-level building codes and municipal climate adaptation grants accelerate recreational installation demand. Sydney and Melbourne specialist rigging contractors command premium wages for certified tensile structure deployment.
United States
Design-build procurement for sports venues and campus canopy installations concentrates project value. ASTM E84 and NFPA 701 flame-spread standards create compliance barriers for imported membrane materials. California and Texas municipal authorities prioritize lifecycle cost accountability in public assembly structure specifications.
Architectural Membrane Market Vendor Landscape
Global majors compete with regional champions across coating chemistry and installation capability dimensions. The vendor base stratifies between integrated glass fiber producers, specialized fluoropolymer coaters, and project-specific engineering contractors. Three archetypes dominate: upstream-integrated material suppliers, technology-specialized coating innovators, and design-build installation specialists. Capacity expansion in compliant fluoropolymer formulations and strategic partnerships for photovoltaic membrane integration represent the dominant competitive vectors.
Among integrated material suppliers, Saint-Gobain anchors premium tensile structure contracts through captive glass fiber supply. Serge Ferrari occupies a position within the specialized coating tier, exemplifying fluoropolymer technology differentiation for facade specifications. Taiyo Kogyo Corporation represents the engineering-intensive installation archetype, with project execution capabilities concentrated in East Asian stadium commissions.
| Leading Market Players |
|---|
| Saint-Gobain |
| Hiraoka |
| Seaman Corp |
| Serge Ferrari |
| Mehler Texnologies |
| Sika |
| Chukoh Chem |
| Taiyo Kogyo Corporation |
| Atex Membrane |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between EN 13501-compliant fluoropolymer systems and commodity PVC-coated alternatives manifests in both project pricing and procurement channel structures. Premium PTFE-glass contracts in Germany and the UAE bundle 25-year material warranties with specialized installation crews, while economy-tier PVC specifications in municipal recreational projects trade lifecycle performance for lower capital outlay and faster procurement cycles.
Pricing Analysis
Warranty bundling separates premium membrane procurement from unbundled commodity transactions. Three-tier pricing structure across premium, standard, and economy levels reflects EN 13501 fire certification, PTFE coating chemistry, and integrated installation service. Pricing pressure stems from REACH-compliant fluoropolymer reformulation costs compressing margins on legacy PTFE suppliers. Municipal recreational buyers exhibit highest price sensitivity, while airport authorities in the UAE prioritize lifecycle cost accountability over upfront expenditure.
Supply Chain Analysis
Freight cost volatility from China and Germany to Western fabricators is reshaping regional sourcing strategies. E-glass roving production concentrates in China and Germany, while silicone-coated fabric finishing clusters in Japan and France. Methyl chlorosilane monomer supply draws from integrated chemical complexes in Germany and the United States. Tariff exposure on Chinese glass fiber imports represents the dominant structural risk. Distribution runs through specialist tensile structure contractors with certified installation capabilities rather than commodity building-material channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as REACH and F-Gas Regulation compliance costs force smaller toll-coating operations toward acquisition or exit. Regulatory chemistry barriers are accelerating this consolidation dynamic.
For Market Incumbents: Deploy captive fluoropolymer synthesis capabilities to maintain formulation flexibility as REACH authorization procedures tighten. Saint-Gobain's integrated glass fiber supply chain and Taiyo Kogyo's in-house installation teams exemplify defensible positions against coating-technology entrants lacking compliant chemistry pipelines. For New Entrants and Emerging Players: Begin with adaptive waterfront canopy installations in Australian coastal municipalities, where engineering complexity sits below stadium thresholds and municipal climate adaptation grants fund project development. Photovoltaic membrane integration offers a differentiated go-to-market angle converging energy procurement with envelope specification. For Investors and Strategic Acquirers: Exit pathways concentrate in design-build installation specialists with Olympic-caliber project records and verified embodied-carbon lifecycle data. Long-term viability favors firms with in-house polymer synthesis rather than toll-coating dependence. The signal to watch is CSRD disclosure mandate adoption rates across Western European commercial developers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Synthesis | In-house coating chemistry secures REACH compliance and protects margin from raw material bottlenecks. |
| Photovoltaic Membrane Lamination Partnership | Energy-generating building envelopes converge procurement categories for airport and stadium developers. |
| Certified Installation Crew Expansion | Specialized rigging labor scarcity in Sydney and Melbourne commands premium project pricing. |
| Embodied-Carbon Verification Investment | CSRD-compliant lifecycle data creates competitive advantage for EU commercial project bids. |
| Adaptive Canopy System Development | Retractable membrane engineering opens municipal recreational funding channels with lower competition. |
Methodological Framework
Document review covered customs trade data, EU F-Gas Regulation filings, and ASTM certification registries, complemented by interviews with tensile structure engineering directors, fluoropolymer coating R&D leads, airport procurement managers, and municipal parks capital planners. Secondary validation drew from ECHA authorization databases, Dubai Municipality building code updates, and Australian state-level climate adaptation grant disclosures. Bottom-up project pipeline analysis triangulated against top-down material consumption estimates.
Cross-referencing historical installation records with expert panel input anchored volume projections across the analysis window. Segmentation modeling incorporated coating chemistry tier, structural permanence classification, end-user ownership structure, and regional regulatory cluster. CAGRs derived from material intensity per square meter applied to verified project completions. Industry-specific inputs included wind-load testing requirements under GB standards and ETFE cushion thermal performance specifications.
Underlying measurement precision varies by segment; permanent stadium installations carry tighter precision than temporary event structures due to public disclosure requirements. Forecasts reflect assumptions on regulatory enforcement timelines and fluoropolymer alternative commercialization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Sheet Metal Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
Technical Insulation Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Construction Sustainable Materials Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market