
 Global Drywall Textures Market | 2026-2036
Global Drywall Textures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drywall Textures Market Analysis
Multi-source procurement among specialty contractors is repositioning supply relationships across the drywall textures value chain. USG Corporation leverages its captive gypsum reserves to sustain raw material cost advantages in North American texture formulations. Saint-Gobain competes through vertically integrated mineral sourcing and continental European manufacturing density. Knauf anchors its position with broad gypsum board-to-texture system bundling that locks in specifier loyalty.
Drywall textures comprise surface-ap finishing compounds and sprayable coatings that mask joint seams, repair imperfections, and create decorative relief on gypsum panel substrates; formulations typically blend gypsum powder, acrylic binders, and mineral aggregates to achieve specific viscosity, crack resistance, and acoustic dampening properties. Knockdown textures dominate residential retrofit volume due to forgiving application tolerances and repair compatibility, while smooth finishes command premium positioning in commercial interiors where lighting uniformity exposes surface defects. Spraying methods lead new construction efficiency, though troweling persists in restoration work where substrate irregularities demand hand-calibrated coverage.
EPA lead-safe renovation standards, OSHA silica exposure limits, and California's Title 24 energy code collectively elevate product compliance burdens and contractor training investments across the United States. REACH chemical restrictions in the European Union and China's GB standards for interior building materials create parallel certification requirements that fragment formulation strategies by destination market. Stakeholders must monitor evolving low-VOC mandates and embodied carbon disclosure rules that threaten to disqualify legacy acrylic-heavy textures from public project bidding.
Market Dynamics
Residential renovation cycles across aging suburban housing stocks in the United States are compressing project timelines and elevating contractor certification requirements under EPA lead-safe renovation rules, fundamentally restructuring how texture products are specified and applied.
Growth Catalysts
- EPA Lead-Safe Certification:Federal renovation, repair, and painting rules mandate certified contractor engagement for pre-1978 housing, expanding the qualified installer base and formalizing product specification channels.
- Acoustic Performance Demands:Multi-family residential and hospitality sectors specify sprayable textures with mineral aggregate blends to meet STC rating requirements in shared-wall assemblies.
- Knockdown Texture Repair Compatibility:The forgiving application tolerance of knockdown finishes sustains steady retrofit volume across mature US housing inventories where substrate irregularities are common.
Market Restraints
- Gypsum Powder Input Volatility:Captive reserve access concentrates among three North American suppliers, exposing independent texture compounders to raw material cost swings.
- Silica Exposure Compliance:OSHA respirable crystalline silica limits impose dust suppression infrastructure requirements that elevate fixed costs for small-scale applicators.
- Smooth Finish Substitution:Commercial interiors with uniform lighting designs increasingly specify level-five skim coats that eliminate texture entirely, compressing premium coating demand.
Strategic Opportunities
- India Urban Housing Stock:Rapid multi-story residential construction in Mumbai and Bangalore creates first-mover positioning for pre-mixed spray texture systems adapted to tropical humidity.
- Low-VOC Mandate Tailwinds:California Title 24 and parallel EU Ecolabel criteria reward water-based acrylic reformulations with public project bidding preference.
- Direct-to-Contractor Digital Platforms:Specialized distribution apps bypass traditional building material wholesalers, capturing specification data and loyalty program enrollment.
Industry Challenges
- Skilled Trowel Applicator Shortage:Restoration-quality hand-finishing expertise concentrates among aging craftsperson cohorts with limited apprenticeship pipeline replenishment.
- Multi-Jurisdiction Certification Burden:Texture compounders face divergent VOC limits across US states, EU member countries, and China's GB standards, fragmenting formulation runs.
- Spray Equipment Capital Intensity:Pneumatic texture rigs with compressor systems and hopper guns require upfront investment that constrains independent contractor fleet expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drywall Textures Market |
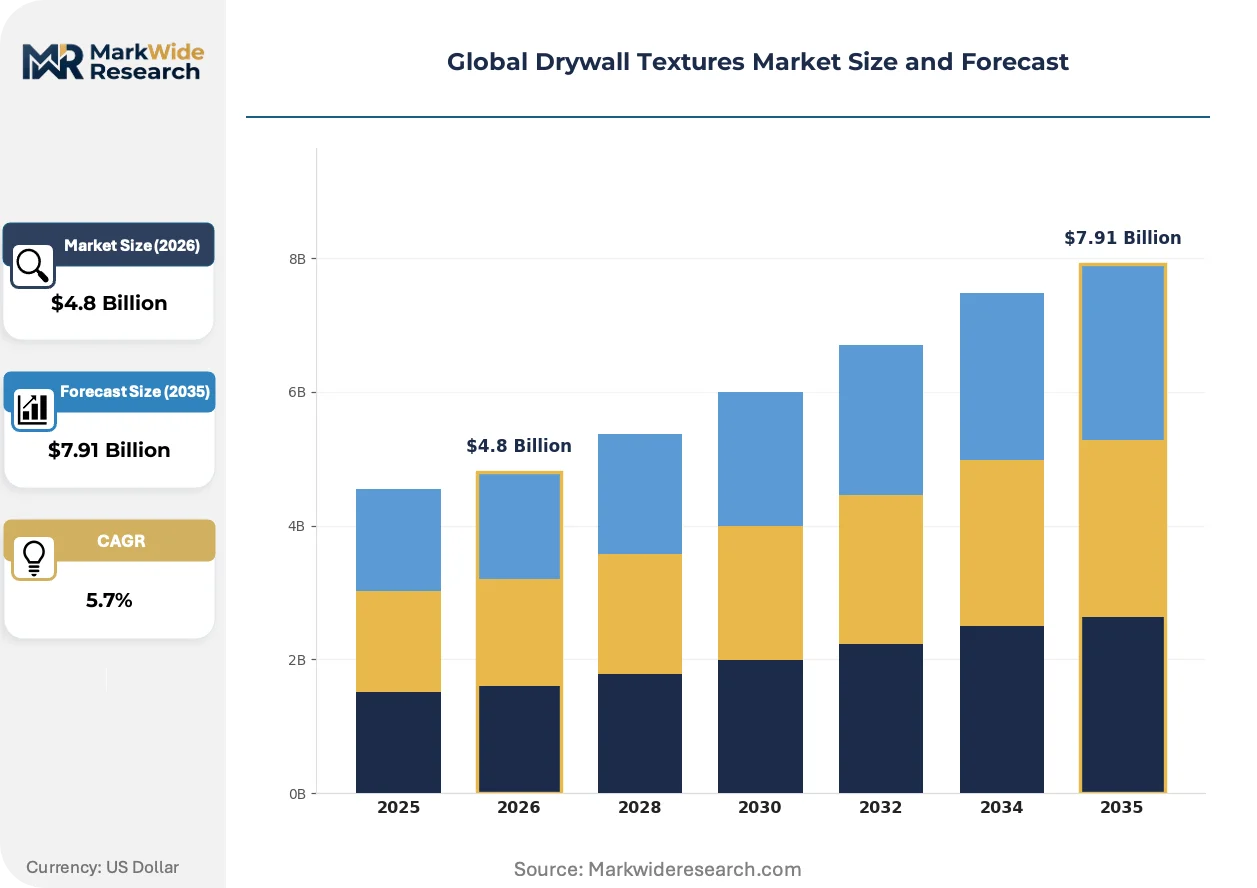
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Texture Type: Knockdown, Smooth, Popcorn, Spanish Lace Application: Residential, Commercial, Industrial, Institutional Installation Method: Rolling, Spraying, Troweling, Stamping Material: Cement, Gypsum, Acrylic, Coatings |
| Companies Covered | USG Corporation, National Gypsum, Saint-Gobain, Knauf, Georgia-Pacific, Sherwin-Williams, PPG Industries, PABCO Gypsum, 3M Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drywall Textures Market Emerging Trajectories
Spray application technology and formulation chemistry are converging to compress installation timelines while regulatory disclosure requirements are embedding carbon and chemical transparency into product selection criteria.
Pre-mixed, pump-grade texture compounds with extended pot life and freeze-thaw stability are electrifying residential new construction efficiency. National production homebuilders specify these systems for tract housing volume, enabling crew specialization and same-day joint finishing-to-texture sequencing that compresses cycle times by eliminating on-site mixing variables.
REACH chemical restrictions and the EU Green Deal's embodied carbon disclosure framework are forcing reformulation transparency across acrylic binder supply chains. German and French texture manufacturers now face downstream customer demands for Environmental Product Declarations, compressing competitive positioning for legacy petroleum-based formulations.
Specification influence is migrating from general contractors to certified specialty applicators with direct EPA RRP credentials. These trades now control product selection on renovation projects, displacing traditional distributor relationships in the United States where lead-safe compliance liability concentrates with the certified firm.
Global Drywall Textures Market Segmentation
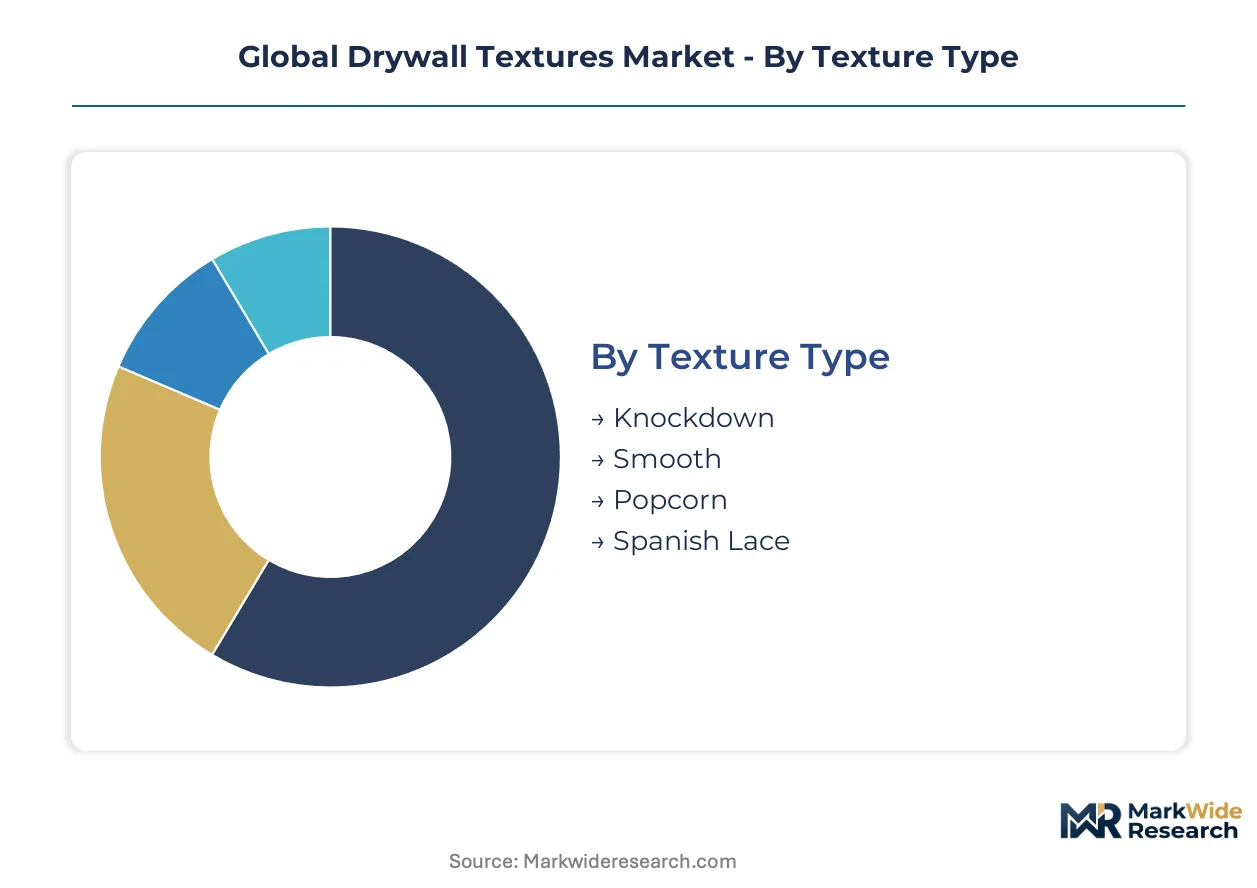
Drywall texture markets fragment across four intersecting dimensions that determine specification pathways and contractor skill requirements. Texture type and installation method together dictate capital deployment and labor sourcing strategies for applicators.
Texture Type:
Capital intensity varies sharply across finish categories, with spray-dependent textures requiring pneumatic infrastructure investments that hand-troweled alternatives avoid.
- Knockdown:Spray-applied compound partially flattened after initial set creates mottled surfaces that hide substrate imperfections. Demand concentrates in United States suburban renovation markets where EPA RRP-certified contractors specify forgiving repair-compatible finishes for aging housing stocks.
- Smooth:Level-five skim coats eliminate surface relief entirely through successive thin applications and sanding sequences. Commercial interiors in Germany and France specify these finishes where uniform LED lighting exposes texture shadows, though labor intensity constrains residential uptake.
- Popcorn:Acoustic ceiling texture applied through hopper guns delivers sound dampening in multi-family housing.
- Spanish Lace:Hand-troweled skip-trowel pattern creates irregular relief favored in Mediterranean-influenced residential architecture.
Most installed capacity flows through Knockdown. Expansion is steepest in Smooth.
Application:
Project type determines specification authority and compliance burden, with institutional work carrying the heaviest certification requirements.
- Residential:Single-family and multi-family housing drives volume through renovation cycles and new construction tract development. United States demand dominates here, with California Title 24 energy codes and EPA lead-safe rules elevating product compliance thresholds.
- Commercial:Office, retail, and hospitality interiors specify textures that reconcile acoustic performance with maintenance durability. STC rating requirements in shared-wall assemblies drive mineral aggregate formulations in German and French hospitality sectors.
- Industrial:Manufacturing and warehouse facilities prioritize moisture-resistant and impact-durable surface treatments.
- Institutional:Schools, healthcare, and government buildings face the most stringent VOC and embodied carbon disclosure rules under EU Green Deal frameworks and California procurement mandates.
Residential channels absorb the majority of compound volume. Institutional specification is climbing fastest as public project bidding tightens environmental criteria.
Installation Method:
Equipment ownership separates contractor tiers, with spray systems creating barriers to entry that rolling and troweling avoid.
- Spraying:Pneumatic hopper guns and compressor rigs enable rapid coverage of large surface areas with consistent pattern replication. National United States homebuilders specify spray systems for production volume, compressing cycle times through crew specialization.
- Troweling:Hand-finishing with broad knives and hawk-and-trowel sets allows substrate-calibrated coverage where irregularities demand artisan adjustment. Restoration work in mature United States housing stocks relies on this method, though skilled applicator shortages concentrate expertise among aging craftsperson cohorts.
- Rolling:Textured roller application suits small-scale repairs and DIY segments with minimal equipment investment.
- Stamping:Patterned tools imprint decorative relief for specialty architectural finishes.
Spraying handles the bulk of new construction square footage. Troweling maintains its position in restoration niches where hand calibration proves indispensable.
Material:
Raw material sourcing strategies diverge across binder chemistries, with petroleum-derived acrylics facing substitution pressure from mineral alternatives.
- Gypsum:Powder and pre-mixed compounds leverage captive North American reserve access among integrated manufacturers. Formulations balance viscosity, crack resistance, and acoustic dampening through mineral aggregate blends specified for multi-family STC compliance.
- Acrylic:Water-based synthetic binders deliver freeze-thaw stability and extended pot life for pump-grade systems. REACH chemical restrictions and EU Ecolabel criteria are forcing reformulation transparency across European supply chains.
- Cement:Portland-based textures provide moisture resistance for exterior and wet-zone applications.
- Coatings:Specialty primers and sealants complete system specifications for high-performance environments.
Gypsum formulations dominate residential and light commercial volume. Acrylic systems are gaining share fastest where pre-mixed convenience and climate stability justify premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is fragmenting production geography as compliance cost differentials widen between jurisdictions with stringent VOC mandates and those with emergent building codes. Manufacturers are relocating formulation capacity to capture cost-of-compliance gaps while maintaining market access through distributed blending networks.
United States
EPA RRP-certified contractor networks dominate specification authority in pre-1978 housing renovation, with California Title 24 energy codes imposing the strictest low-VOC thresholds nationwide. OSHA silica exposure limits elevate dust suppression infrastructure requirements for applicators in Texas and Florida markets. The Sun Belt corridor from Phoenix to Atlanta sustains the densest concentration of production homebuilders specifying spray-grade pre-mixed systems.
Germany
EU Green Deal embodied carbon disclosure frameworks force reformulation transparency across acrylic binder supply chains serving multi-family residential construction. REACH chemical restrictions eliminate legacy petroleum-based additives from public project bidding in Berlin and Hamburg metropolitan zones. The Rhine-Ruhr industrial cluster anchors continental European manufacturing density for mineral-sourced texture compounds.
China
GB standards for interior building materials create certification requirements that fragment formulation strategies for both domestic consumption and export-oriented production. MIIT dual carbon goals accelerate substitution pressure on high-emission acrylic-heavy textures in Shanghai and Shenzhen high-rise residential towers. The Yangtze River Delta concentration of gypsum board manufacturing feeds downstream texture compound blending in Jiangsu province.
India
Rapid multi-story residential construction in Mumbai and Bangalore creates first-mover positioning for pre-mixed spray texture systems adapted to tropical humidity conditions. BIS certification requirements for building materials elevate product compliance burdens for imported formulations against domestic compounders. The Delhi-NCR corridor exhibits accelerating specification of acoustic-rated textures in premium multi-family developments.
Canada
Health Canada and PMRA oversight of interior building materials parallels US EPA frameworks while maintaining distinct VOC disclosure thresholds for cross-border product registration. Provincial energy codes in British Columbia and Ontario reward low-emitting texture systems in public housing procurement. The Greater Toronto Area concentration of mid-rise residential construction sustains steady uptake of repair-compatible knockdown finishes.
Global Drywall Textures Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty acoustic and low-carbon formulation niches that command specification premiums in institutional segments. The vendor base concentrates among integrated gypsum reserve holders and independent compounders sourcing raw materials through contractual offtake. Three archetypes dominate: captive-reserve integrated manufacturers, regional blending specialists, and coating-system diversifiers extending from paint into texture. Competitive moves center on backward integration into mineral sourcing and geographic expansion through distributed blending capacity.
Among North American integrated manufacturers, USG Corporation, National Gypsum, and Georgia-Pacific exemplify the captive-reserve archetype that controls raw material cost structures. These entities occupy positions where upstream gypsum access locks in formulation economics against independent compounders exposed to input volatility. Saint-Gobain and Knauf represent European-originated multinationals with continental manufacturing density and system-bundling strategies that capture specifier loyalty across board-to-texture specifications.
| Leading Market Players |
|---|
| USG Corporation |
| National Gypsum |
| Saint-Gobain |
| Knauf |
| Georgia-Pacific |
| Sherwin-Williams |
| PPG Industries |
| PABCO Gypsum |
| 3M Co. |
| Others |
Supply Flow & Price Mechanics
Pre-mixed pump-grade texture compounds with extended pot life are compressing field labor costs while concentrating procurement leverage among national homebuilders who negotiate direct formulation contracts. This production-method transition simultaneously elevates economies of scale for integrated gypsum reserve holders and squeezes independent compounders exposed to spot gypsum powder markets.
Pricing Analysis
Distributor margin layers in the United States typically capture 15-25 points between manufacturer gate and certified contractor pickup, though direct-to-builder programs bypass this markup entirely. Three-tier pricing structure across premium, standard, and economy levels separates EPA RRP-certified specialty applicators from commodity roll-on DIY products, with brand premium and volume scale as primary differentiation drivers. Cost compression in standard-grade gypsum compounds is intensifying because captive reserve access concentrates among three North American suppliers. Price-sensitive independent contractors in the Sun Belt corridor face the tightest margins, while institutional specifiers in California and Germany exhibit lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Freight cost differentials between bulk powder shipments and pre-mixed pail distribution are reshaping regional blending economics, favoring distributed manufacturing nodes over centralized production. Geographic supply concentration centers on the United States, Germany, and China, with the Rhine-Ruhr cluster and Yangtze River Delta anchoring continental European and Asian manufacturing density respectively. Raw material dependencies rest on synthetic gypsum from flue-gas desulfurization, mined gypsum reserves, and water-based acrylic binders subject to REACH chemical restrictions. Tariff exposure on acrylic emulsion imports into the European Union presents structural supply chain risk. Distribution runs through building material wholesalers, though direct-to-contractor digital platforms are displacing traditional channels in North American renovation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Drywall Textures Market functions as a regulatory compounder where EPA lead-safe certification mandates and REACH chemical restrictions continuously reshape product qualification thresholds and contractor specification authority.
For Market Incumbents: To counter silica exposure compliance burdens that elevate fixed costs for small-scale applicators, deepen backward integration into synthetic gypsum processing and expand distributed blending capacity in high-growth corridors. Prioritize certification investment in EPA RRP training infrastructure to lock in specifier loyalty among the shrinking pool of qualified installers. For New Entrants and Emerging Players: Specialty acoustic applicators serving German and French multi-family hospitality projects represent an underserved buyer archetype with limited incumbent attention. First-mover positioning in Mumbai and Bangalore pre-mixed spray systems adapted to tropical humidity offers the most penetrable geography. Pursue direct-to-contractor digital platforms as the primary go-to-market angle to bypass entrenched wholesaler relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blending specialists with contractual gypsum offtake but lacking brand recognition in institutional specification channels. Long-term viability over the coming decade hinges on low-carbon formulation transparency and EU Green Deal compliance positioning. Watch for BIS certification acceleration in India as the inflection signal indicating formal market maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Gypsum | Captive flue-gas desulfurization feedstock locks in raw material cost structures against spot market volatility. |
| EPA RRP Certification Infrastructure Buildout | Training program ownership captures specification influence in pre-1978 housing renovation channels. |
| Low-VOC Formulation Reformulation | California Title 24 and EU Ecolabel compliance opens public project bidding access. |
| Distributed Blending Network Expansion | Regional manufacturing nodes reduce freight cost exposure on pre-mixed pail distribution. |
| Direct-to-Contractor Digital Platform Launch | Specialized distribution apps capture specification data and loyalty program enrollment from certified applicators. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with specialty drywall contractors, EPA RRP-certified applicators, building material procurement managers, and formulation chemists at integrated manufacturers. Secondary validation drew from EPA enforcement data, OSHA silica exposure guidelines, EU ECHA substance restriction updates, and customs trade records for gypsum powder and acrylic emulsion flows. Bottom-up project pipeline estimates and top-down construction spending aggregates were triangulated to anchor volume assumptions.
Comparable-period anchoring linked historical renovation cycle data to forward projection assumptions across the analysis window. Segmentation dimensions modeled include texture type, installation method, material chemistry, and application sector, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs were derived from fitted trend extrapolation against construction activity indices and housing stock age demographics. Key inputs encompassed EPA RRP certification rolls, multi-family housing permit volumes, and Title 24 low-VOC adoption curves.
Underlying measurement precision varies by segment; institutional and commercial specification channels carry tighter precision than fragmented residential DIY activity. Forecasts reflect documented assumptions about regulatory enforcement intensity and contractor certification pipeline replenishment. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
GCC Faucet Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Global Builder Hardware Market