
 Global Rainscreen Cladding Market | 2026-2036
Global Rainscreen Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rainscreen Cladding Market Foresight
Specification channels for rainscreen cladding systems is fragmenting as architects, contractors, and facade consultants each develop independent procurement pathways. Kingspan Group leverages its insulated panel heritage to anchor specification in Northern European commercial projects. Tata Steel competes through integrated steel-to-system supply chains across British and Dutch development corridors. Etex Group differentiates via fiber cement specialization that sustains margin pools in heritage-sensitive cultural building applications.
Rainscreen cladding denotes a non-loadbearing exterior wall assembly comprising an outer weather-resistant skin, ventilated cavity, and inner structural wall with drainage provisions, typically achieving U-values below 0.25 W/m²K when paired with mineral wool insulation. The assembly manages moisture ingress through pressure moderation while reducing thermal bridging across the building envelope. Fiber cement boards and aluminum composite panels represent the most mature product categories with established supply chains and price transparency, whereas high-pressure laminates and terracotta panels command premium positioning in cultural and hospitality applications where aesthetic differentiation justifies longer procurement cycles. Ventilated systems lead technology adoption due to simpler installation protocols, while pressure equalized systems are gaining traction in high-rise commercial towers across wind-load-critical zones.
The EU Green Deal and REACH frameworks mandate embodied carbon disclosure and restrict hazardous substance content in facade materials, reshaping supplier qualification criteria across European specification channels. The EPA and ASHRAE standards in the United States drive comparable performance benchmarks for thermal efficiency and air leakage containment. Stakeholders must monitor evolving code convergence between European and North American energy performance standards as this determines which material systems and assembly designs achieve cross-border specification portability.
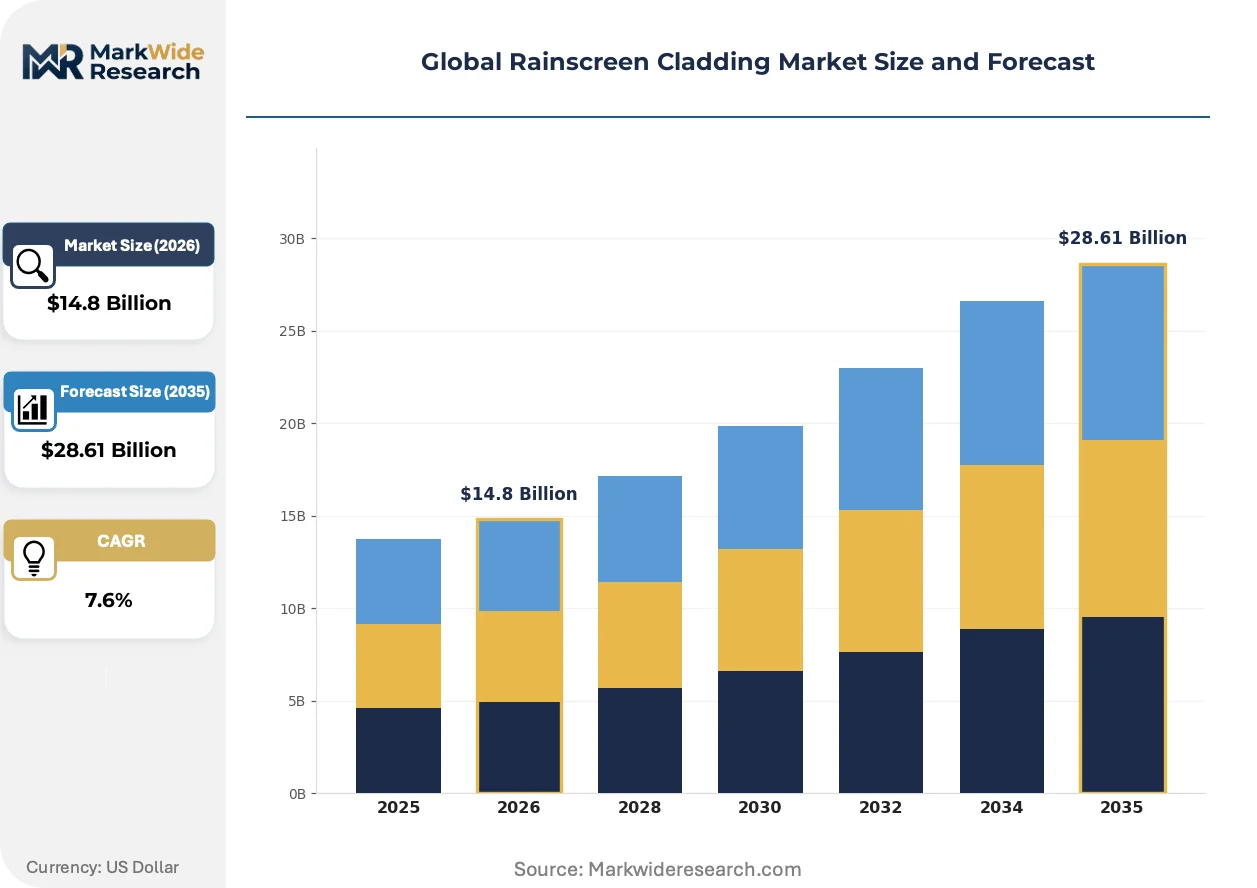
Market Dynamics
Energy-efficiency mandates across Germany, the United Kingdom, and the United States are compressing specification cycles for ventilated facade systems while fragmenting procurement authority between architects, contractors, and facade consultants.
Growth Catalysts
- EU Green Deal enforcement:Tightening embodied carbon disclosure requirements for commercial building envelopes are accelerating retrofit specifications across German and British urban corridors.
- Aluminum composite panel standardization:Mature supply chains and price transparency in this material category are reducing procurement friction for high-volume commercial developers.
- Wind-load engineering advances:Pressure-equalized system adoption in high-rise towers across Chicago and Frankfurt is expanding addressable project scale.
Market Restraints
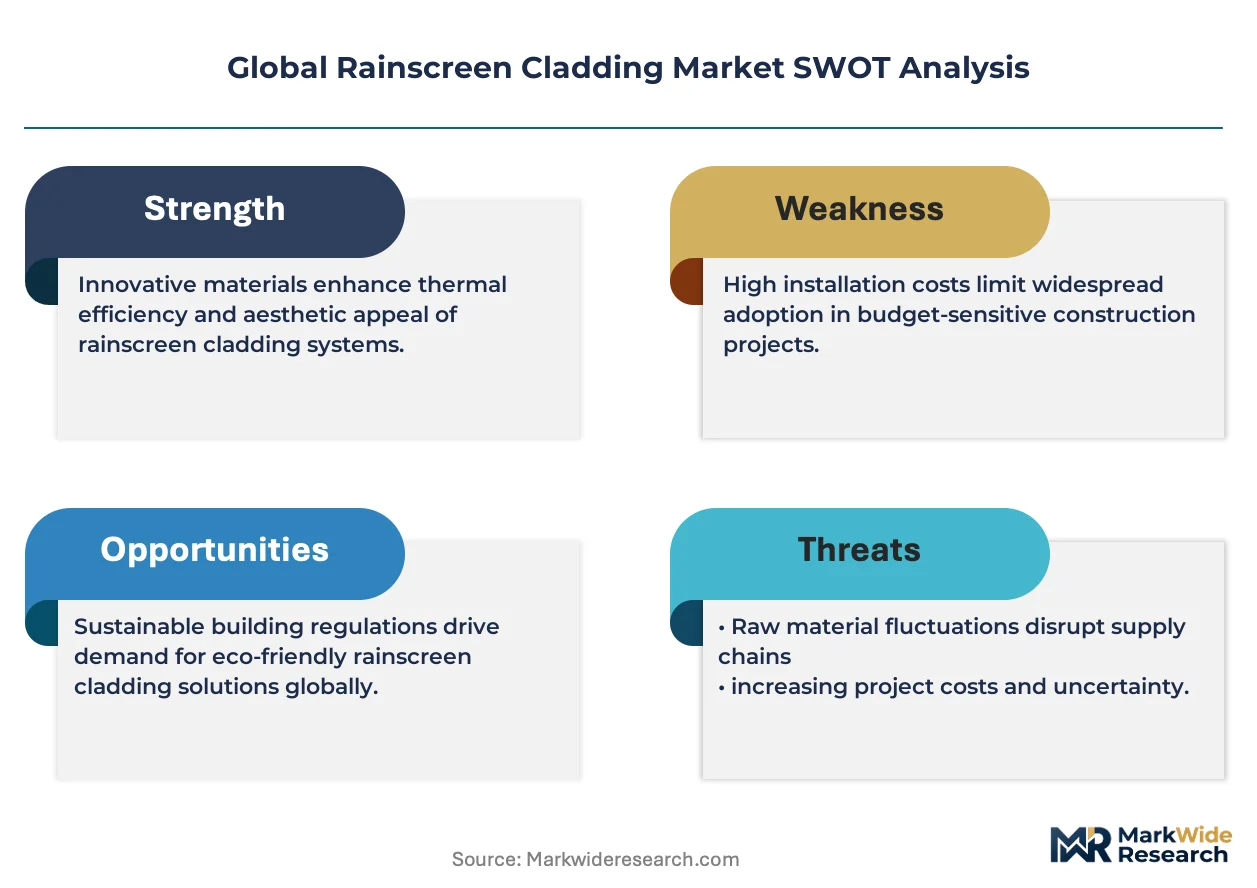
- Mineral wool insulation cost volatility:Input price swings for this thermal barrier material are compressing margin predictability for system integrators.
- REACH substance restrictions:Hazardous content limitations on facade coatings and adhesives are extending supplier qualification timelines by 4-8 months.
- High-pressure laminate substitution ceiling:Premium positioning in cultural buildings limits volume scaling despite superior aesthetic performance.
Strategic Opportunities
- Indian commercial construction acceleration:Underpenetrated specification of ventilated systems in Mumbai and Bangalore high-rises offers first-mover positioning before BIS energy codes tighten.
- Photovoltaic facade convergence:Integration of building-integrated solar generation with rainscreen cavities is creating new performance-based procurement categories.
- Digital twin specification channels:BIM-enabled facade consultants are bypassing traditional distributor networks in Dutch and Danish markets.
Industry Challenges
- Facade engineer talent scarcity:Specialized expertise in pressure-equalized cavity design is concentrating among a limited pool of consultants in London and New York.
- Multi-jurisdiction certification complexity:Divergent ASHRAE, EU Green Deal, and evolving BIS thermal performance standards are forcing redundant testing protocols.
- Legacy building envelope integration:Retrofit installations must accommodate unpredictable substrate conditions in 1960s-1980s commercial stock across Manchester and Detroit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rainscreen Cladding Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Composite Panels, Fiber Cement Boards, High-Pressure Laminates, Timber Cladding, Stainless Steel Sheets, Terracotta Panels Technology: Ventilated Systems, Pressure Equalized Systems, Rainscreen with Insulation, Double Skin Facades, Structural Glazing, Expanded Metal Mesh Application: Commercial Buildings, Educational Facilities, Cultural Buildings, Government Institutions, Hospitality Venues, Sports Complexes End User: Architectural Firms, Construction Contractors, Property Developers, Building Maintenance Companies, Civil Engineering Consultants, Facility Managers |
| Companies Covered | Etex Group, Trespa International, Kingspan Group, SFS Group, Tata Steel, Compagnie de Saint-Gobain, Arconic Corporation, Everest Industries, Rockwool International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rainscreen Cladding Market Shifts & Advancements
Specification workflows are digitizing rapidly while material science advances compress the performance gap between premium and standard system tiers. Three forces are actively restructuring competitive positioning.
Terracotta rainscreen systems are migrating from heritage-sensitive cultural institutions toward mainstream commercial hospitality and corporate headquarters. Marriott and Hyatt development teams in London and Singapore are specifying these panels for 18-24 month procurement cycles that prioritize aesthetic differentiation over speed-to-occupancy. This migration from niche to volume applications is forcing aluminum composite panel suppliers to defend position through accelerated color-matching capabilities and compressed lead times.
REACH framework updates through ECHA are mandating expanded substance-of-very-high-concern screening across facade coating supply chains. German and Dutch system integrators must now document full material ingredient transparency to maintain specification eligibility for publicly funded commercial projects. Fiber cement board manufacturers with pre-certified supply chains are capturing disproportionate share in Rotterdam and Hamburg municipal developments where procurement officers face audit liability.
Architects in Chicago and Frankfurt are consolidating specification authority through direct relationships with facade engineering consultants, disintermediating traditional general contractor procurement channels. This concentration of decision-making is compressing distributor margins while rewarding suppliers with in-house technical support capabilities. The shift is most visible in high-performance commercial towers where envelope performance guarantees now flow directly from system manufacturers to developer owners.
Global Rainscreen Cladding Market Segmentation
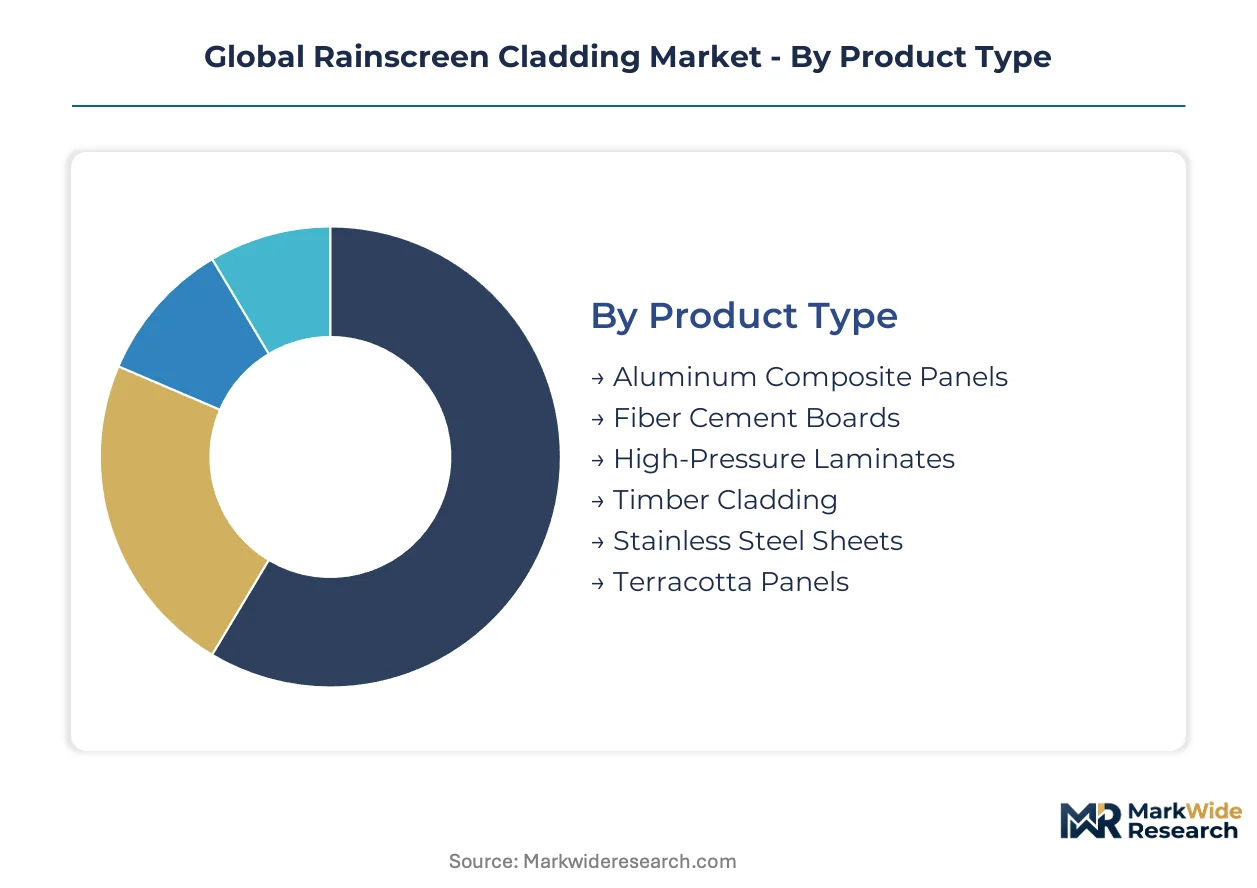
Rainscreen cladding procurement cycles vary dramatically across material and technology categories, with specification timelines stretching from 6 months for standardized aluminum systems to 24 months for custom terracotta installations. Understanding these velocity differentials enables suppliers to align inventory and technical support resources with segment-specific demand patterns.
Product Type:
Specification cycles compress from 18-24 months for heritage-sensitive materials down to 4-6 months for standardized panel systems, creating distinct service models across the supplier base.
- Aluminum Composite Panels:Multi-layer aluminum-polyethylene sandwich construction delivers weight efficiency and color consistency at scale. Demand concentrates in German and US commercial office towers where developers prioritize speed-to-occupancy over aesthetic customization, though REACH substance screening now extends qualification timelines.
- Fiber Cement Boards:Cellulose-reinforced cement composite offers fire resistance and dimensional stability with established European supply chains. Rotterdam and Hamburg municipal projects specify these panels disproportionately as procurement officers seek pre-certified material transparency under ECHA mandates.
- High-Pressure Laminates:Resin-impregnated kraft paper core with decorative surface layer commands premium positioning in London cultural institutions.
- Timber Cladding:Modified wood species with factory-applied coatings serve sustainability-focused Nordic commercial developments.
- Stainless Steel Sheets:Cold-rolled austenitic grades with brushed or mirror finishes target coastal hospitality venues in Singapore and Sydney.
- Terracotta Panels:Kiln-fired clay with through-body color and rainscreen-compatible anchoring systems anchor Marriott and Hyatt corporate specifications.
Aluminum composite panels anchor the volume base while terracotta panels gain share at the steepest rate.
Technology:
Cost tiers separate rapid-install ventilated cavities from engineered pressure-equalized assemblies requiring specialized facade consultant involvement.
- Ventilated Systems:Open-jointed outer skin with 50-200mm drained and ventilated cavity represents the most deployed configuration globally. Manchester and Detroit retrofit clusters favor these systems for substrate tolerance and installer familiarity.
- Pressure Equalized Systems:Compartmentalized air chambers with engineered pressure moderation deliver superior wind-load performance in high-rise towers. Chicago and Frankfurt commercial towers above 30 stories specify these assemblies exclusively as facade engineers assume direct liability for envelope performance.
- Rainscreen with Insulation:Factory-bonded mineral wool backing reduces site labor and thermal bridging.
- Double Skin Facades:Active air cavity with operable glazing and solar shading integration serves net-zero commercial targets.
- Structural Glazing:Silicone-bonded glass rainscreen with minimal metal framing commands airport and transit premiums.
- Expanded Metal Mesh:Open-weave stainless or aluminum screens provide solar shading with visual transparency.
Ventilated systems dominate current volume while pressure equalized systems expand most quickly in high-rise corridors.
Application:
Customer types fragment procurement authority, with architects controlling cultural and hospitality specifications while contractors dominate educational and government verticals.
- Commercial Buildings:Office towers and mixed-use developments constitute the primary volume driver across German, British, and US urban corridors. ASHRAE 90.1 thermal performance targets and EU Green Deal embodied carbon thresholds compress specification cycles as developers race to secure occupancy permits.
- Educational Facilities:University campuses and K-12 buildings prioritize durability and maintenance accessibility over aesthetic differentiation. British university estates in Oxford and Cambridge specify fiber cement systems through framework agreements that emphasize lifecycle cost predictability.
- Cultural Buildings:Museums, galleries, and performance venues demand material authenticity and heritage compatibility.
- Government Institutions:Municipal and federal buildings require domestic content compliance and extended warranty terms.
- Hospitality Venues:Hotel brands with standardized design guidelines favor rapid color-matching and global supply consistency.
- Sports Complexes:Stadiums and arenas require impact-resistant surfaces and crowd-load engineering.
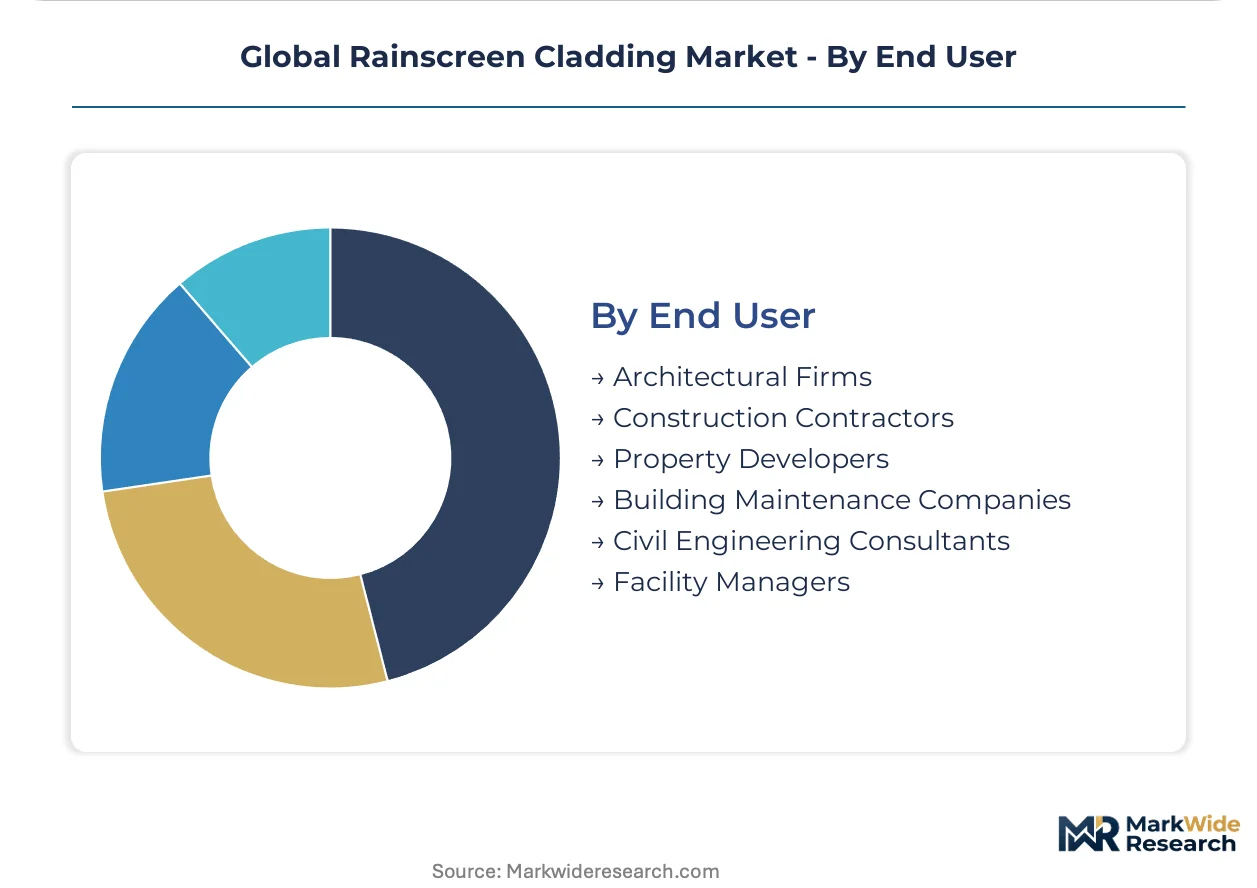
Commercial buildings anchor the volume base while cultural buildings gain share at the steepest rate.
End User:
Supply concentration varies sharply, with three facade engineering consultancies in London and New York controlling pressure-equalized specification while distributors serve fragmented contractor demand.
- Architectural Firms:Design authority concentrates in 200-300 global practices with facade specialization. Chicago and Frankfurt towers now see architects delegating envelope performance guarantees directly to system manufacturers, bypassing general contractor procurement channels.
- Construction Contractors:Volume procurement through framework agreements and project-specific bidding dominates German commercial construction. Contractors in Dusseldorf and Munich favor aluminum composite panels with fixed-price supply contracts that transfer mineral wool cost volatility to manufacturers.
- Property Developers:Risk-bearing owners in US Sun Belt markets specify performance-based contracts with envelope guarantees.
- Building Maintenance Companies:Retrofit specification authority grows as facade asset management contracts expand.
- Civil Engineering Consultants:Structural engineers influence substrate preparation and anchoring design.
- Facility Managers:Operations teams increasingly specify replacement cladding for 1970s-1990s commercial stock.
Construction contractors anchor the volume base while architectural firms gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's bulk material throughput underwrites Dutch distribution dominance for facade components entering Northern European construction corridors. German rail freight corridors from Duisburg radiate cladding assemblies toward Polish and Czech retrofit markets. Dubai's Jebel Ali port complex enables Gulf-based developers to source composite panel systems with 30-day landed lead times.
Germany
Commercial tower development in Frankfurt and Munich drives pressure-equalized system demand for structures exceeding 30 stories. The EU Green Deal's embodied carbon disclosure mandates compress supplier qualification timelines for publicly funded projects. The Rhine-Ruhr corridor hosts system integrator clusters in Dusseldorf that serve Benelux export markets.
United States
ASHRAE 90.1 thermal performance targets accelerate ventilated facade specifications across Chicago and New York high-rise corridors. EPA energy efficiency standards for commercial buildings tighten envelope leakage containment requirements. Detroit's commercial retrofit cluster favors substrate-tolerant systems for 1970s building stock rehabilitation.
United Kingdom
Post-Grenfell regulatory reform drives aluminum composite panel substitution toward fire-rated fiber cement alternatives in London commercial developments. British Standard 8414 fire performance testing extends procurement cycles for facade system approvals. Manchester's urban retrofit concentration specifies ventilated cavities for unpredictable 1960s substrate conditions.
India
Mumbai and Bangalore high-rise commercial construction exhibits underpenetrated ventilated system specification ahead of anticipated BIS energy code tightening. The country's national building standards regulator is developing thermal performance benchmarks modeled on EU frameworks. Gujarat-based fabricators serve domestic demand through import-substitution panel production.
United Arab Emirates
Dubai's hospitality-driven construction pipeline specifies terracotta and high-pressure laminate systems for aesthetic differentiation in premium hotel developments. The emirate's green building regulations mandate envelope thermal performance disclosure for commercial projects above 50,000 square meters. Abu Dhabi's government district developments favor pre-certified supply chains with full material transparency documentation.
Global Rainscreen Cladding Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in insulation, fastening, and coating supply. The vendor base organizes around three strategic archetypes: steel-to-system vertically integrated suppliers, fiber cement specialization houses, and insulated panel heritage players extending into facade assemblies. Competitive dynamics center on M&A consolidation for supply chain control and geographic expansion through specification engineer relationships in high-rise corridors.
Among European-based material specialists, Etex Group and Kingspan Group exemplify divergent platform strategies—Etex anchors heritage-sensitive cultural building specifications through fiber cement transparency certification, while Kingspan leverages insulated panel manufacturing integration for Northern European commercial volume. Tata Steel occupies a position representing steel-to-system supply chain control across British and Dutch development corridors.
| Leading Market Players |
|---|
| Etex Group |
| Trespa International |
| Kingspan Group |
| SFS Group |
| Tata Steel |
| Compagnie de Saint-Gobain |
| Arconic Corporation |
| Everest Industries |
| Rockwool International |
| Others |
Supply & Pricing Matrix
The Port of Rotterdam's bulk mineral wool and aluminum coil throughput anchors Northern European cladding supply capacity, with Rotterdam-based distributors translating upstream input concentration into tiered pricing power across German and Benelux commercial project pipelines. Duisburg rail freight terminals radiate finished panel assemblies toward Polish and Czech retrofit corridors, compressing delivery cost differentials between volume contract holders and spot buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates terracotta and high-pressure laminate specifications from aluminum composite panel volume tiers and economy-grade fiber cement alternatives. Price differentiation centers on certification grade under REACH substance disclosure rules and volume scale across multi-tower development portfolios. Pricing pressure stems from mineral wool insulation cost volatility that manufacturers struggle to pass through to fixed-price framework agreements. Contractors in German commercial corridors exhibit highest price sensitivity, while London cultural institutions prioritize aesthetic performance over unit cost.
Supply Chain Analysis
Extended payment terms from Dutch and German system integrators to Rotterdam-based distributors reflect working capital intensity across long-cycle terracotta procurement. Supply concentrates in Germany, the Netherlands, and China, with Chinese aluminum coil and polyethylene core materials feeding European panel lamination facilities. Raw material dependencies span mineral wool from Rockwool International's Danish production, aluminum coil from Norwegian smelters, and specialty coatings from German chemical suppliers. Tariff exposure on Chinese aluminum products creates margin vulnerability for non-vertically integrated assemblers. Distribution runs through facade engineering consultancies in London and Frankfurt that increasingly specify direct from manufacturer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against photovoltaic facade convergence, where building-integrated solar generation threatens to displace traditional rainscreen specification in net-zero commercial towers.
For Market Incumbents: Build certification moats around REACH-compliant material transparency to defend Rotterdam and Hamburg municipal procurement channels against fiber cement specialists with pre-certified supply chains. Deepen backward integration into mineral wool insulation production to capture margin pools currently leaking to Rockwool International and compress cost volatility exposure. Pressure-equalized system expertise concentration among London and New York facade engineers represents a defendable capability barrier against aluminum composite panel commoditization. For New Entrants and Emerging Players: Pursue first-mover positioning in Mumbai and Bangalore high-rise corridors ahead of BIS energy code tightening, where ventilated system specification remains underpenetrated relative to EU penetration rates. Target digital twin specification channels in Dutch and Danish markets where BIM-enabled facade consultants bypass traditional distributor networks. Anchor entry through photovoltaic facade integration partnerships that create performance-based procurement categories distinct from incumbent material supply. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance play because EU Green Deal embodied carbon disclosure and REACH substance restrictions are structurally elevating supplier qualification barriers. Acquisition targets should emphasize facade engineering consultancies with pressure-equalized cavity design capabilities concentrated in London and New York. The signal to watch is BIS energy code finalization in India, which would trigger specification convergence toward European thermal performance benchmarks and validate early entrant positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Wool | Captures insulation margin pools and reduces cost volatility exposure for German system integrators. |
| REACH Certification Investment | Secures specification eligibility for Rotterdam and Hamburg municipal developments under ECHA mandates. |
| Photovoltaic Facade Partnership | Creates building-integrated solar procurement category distinct from traditional rainscreen material supply. |
| Facade Engineering Consultancy Acquisition | Concentrates pressure-equalized specification authority currently fragmented across London and New York. |
| India Market Entry | Establishes first-mover positioning in Mumbai and Bangalore ahead of BIS thermal performance code tightening. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU construction permit databases, ECHA substance registration filings, and ASHRAE standard evolution documentation. Primary interviews engaged facade engineering consultants, commercial developer procurement directors, aluminum composite panel plant managers, and municipal building authority officials across German, British, Dutch, and US urban corridors. Secondary validation drew from construction industry association technical bulletins, national building code regulatory filings, and customs trade data for mineral wool and aluminum coil imports. Bottom-up project pipeline analysis triangulated against top-down market sizing from material supplier shipment disclosures.
Forecast inputs span technology adoption curves for pressure-equalized versus ventilated systems, regulatory enforcement timelines for EU Green Deal embodied carbon disclosure, and material substitution elasticity between aluminum composite panels and fire-rated fiber cement alternatives. Segmentation modeling covers product type, technology configuration, application vertical, and end-user procurement authority across the projection horizon. CAGRs derive from regression against historical construction permit issuance and energy code stringency indices. Industry-specific inputs include facade engineer talent availability in London and New York, and REACH substance restriction expansion schedules through ECHA.
Sensitivities concentrate around BIS energy code finalization timing in India, EU Green Deal enforcement acceleration, and mineral wool input cost volatility. Forecasts reflect assumptions regarding regulatory convergence between European and North American thermal performance standards. Macroeconomic construction cycle downturn, regulatory rollback, or photovoltaic facade technology cost breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Drywall and Gypsum Board Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Europe Green Buildings Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
North America Fabricated Metal Products Market