
 Building Vibration Isolation Market | 2026-2036
Building Vibration Isolation Market Size, Share, and Industry Trends Forecast 2026-2036
Building Vibration Isolation Market Analysis
German elastomer compounders is expanding production of high-damping rubber bearings for seismic and HVAC applications. Mason Industries leverages deep product specialization in spring and rubber isolators to sustain leadership across North American commercial projects. Fabreeka anchors its position through advanced cork-elastomer composites that dominate precision manufacturing environments. Kinetics Noise Control differentiates via integrated noise and vibration control systems that extend its reach into critical healthcare and laboratory infrastructure.
Building vibration isolation encompasses engineered systems designed to decouple mechanical equipment and structural elements from transmitted oscillatory energy, typically employing elastomeric compounds with loss factors exceeding 0.15, steel springs with natural frequencies below 5 Hz, or tuned mass configurations calibrated to specific resonant frequencies. These systems protect occupant comfort, safeguard sensitive instrumentation, and extend structural service life by dissipating kinetic energy before propagation through building frames. Pads and bearings command the largest installed base due to their versatility beneath heavy rotating equipment and structural columns, while tuned mass damper technology represents the fastest-growing category as skyscraper heights push dynamic response limits. Active isolation systems concentrate margin pools in semiconductor fabrication and nanotechnology research facilities where sub-micron vibration thresholds justify premium control architectures.
ISO 2631 human vibration exposure standards, Germany's DIN 4150 structural vibration guidelines, and ASHRAE equipment vibration criteria collectively shape product certification requirements and specification minimums across commercial and industrial projects. China's GB 50463 seismic isolation code and Japan's JIS B 0911 machinery vibration standards further segment compliance obligations by geography and application intensity. Stakeholders must monitor evolving green building certifications that increasingly credit acoustic and vibration performance alongside energy metrics when positioning isolation solutions for next-generation developments.
Market Dynamics
Data center construction is compressing specification cycles for precision isolation systems as hyperscale operators demand sub-micron vibration thresholds beneath server racks and cooling infrastructure.
Growth Catalysts
- Subway Expansion:China's metro construction pipeline is amplifying structural damping requirements beneath high-rise foundations adjacent to tunnel boring operations.
- DIN 4150 Tightening:Germany's revised structural vibration thresholds are mandating upgraded isolation specifications across EU commercial and residential projects.
- High-Damping Rubber:Advanced elastomer compounds with loss factors exceeding 0.25 are displacing conventional bearings in seismic and HVAC retrofit applications.
Market Restraints
- Natural Rubber Volatility:Input cost swings for Malaysian and Indonesian rubber feedstocks are compressing margin predictability for elastomer bearing manufacturers.
- Spring Steel Concentration:Specialty coil spring production clusters in Germany and Japan, creating supply vulnerability for North American project timelines.
- Tuned Mass Complexity:Skyscraper damper calibration requires site-specific wind tunnel data, extending engineering cycles and freezing capital.
Strategic Opportunities
- India Data Centers:Greenfield hyperscale construction in Mumbai and Hyderabad is opening specification windows for active isolation beneath precision IT loads.
- Healthcare Convergence:MRI and proton therapy installations are merging vibration and magnetic field isolation into unified procurement packages.
- EU Green Deal Credits:Acoustic performance metrics in building certification schemes are creating regulatory tailwinds for premium isolation specification.
Industry Challenges
- Seismic Certification Bottlenecks:ISO 2631 human exposure testing and project-specific peer review are extending approval timelines for hospital and laboratory contracts.
- Legacy Equipment Integration:Retrofit isolation beneath existing rotating machinery requires custom fabrication, fragmenting project economics and eroding standardization gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Vibration Isolation Market |
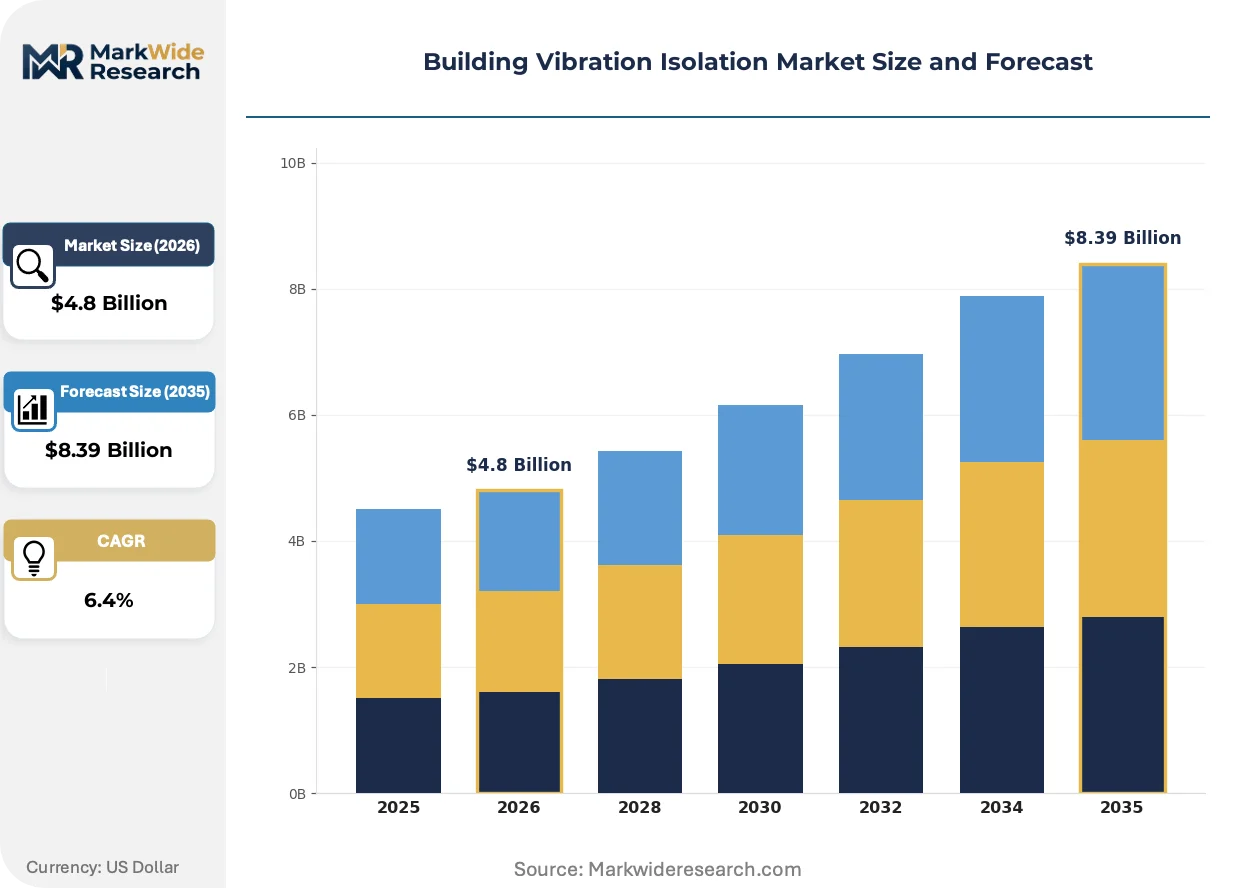
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mounts, Pads, Hangers, Bearings Technology: Active, Passive, Hybrid, Tuned Mass Damper End User: Commercial Buildings, Industrial Facilities, Residential Structures, Educational Institutions Installation Method: Embedded, Surface-mounted, Suspended, Free-standing |
| Companies Covered | Mason Industries, Fabreeka, Kinetics Noise Control, Regupol America, VibraSystems, Farrat, Getzner, ACE Stosddämpfer, VMC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Vibration Isolation Market Emerging Trajectories
Active vibration cancellation architectures are migrating from semiconductor cleanrooms into broader commercial infrastructure as sensor and actuator costs decline.
Magnetorheological fluid dampers are integrating real-time stiffness adjustment for variable-load industrial machinery. Food processing and pharmaceutical packaging lines are adopting these systems to maintain precision during batch-size transitions. The technology is integrating predictive maintenance protocols that compress downtime exposure for continuous manufacturing operations.
REACH substance restrictions on certain plasticizers are forcing reformulation of legacy elastomer compounds used in building bearings. Compounders are accelerating bio-based alternatives through accelerated aging validation protocols. HVAC and structural isolation specifications in the European Union are responding with updated material certification requirements that favor compliant suppliers.
Specification authority is concentrating with MEP engineers and acoustical consultants rather than general contractors. Design-build contracts are unbundling vibration isolation from mechanical packages, creating direct procurement channels between isolation specialists and project owners. This pattern is most visible in United States healthcare and laboratory construction where performance guarantees override first-cost considerations.
Building Vibration Isolation Market Segmentation
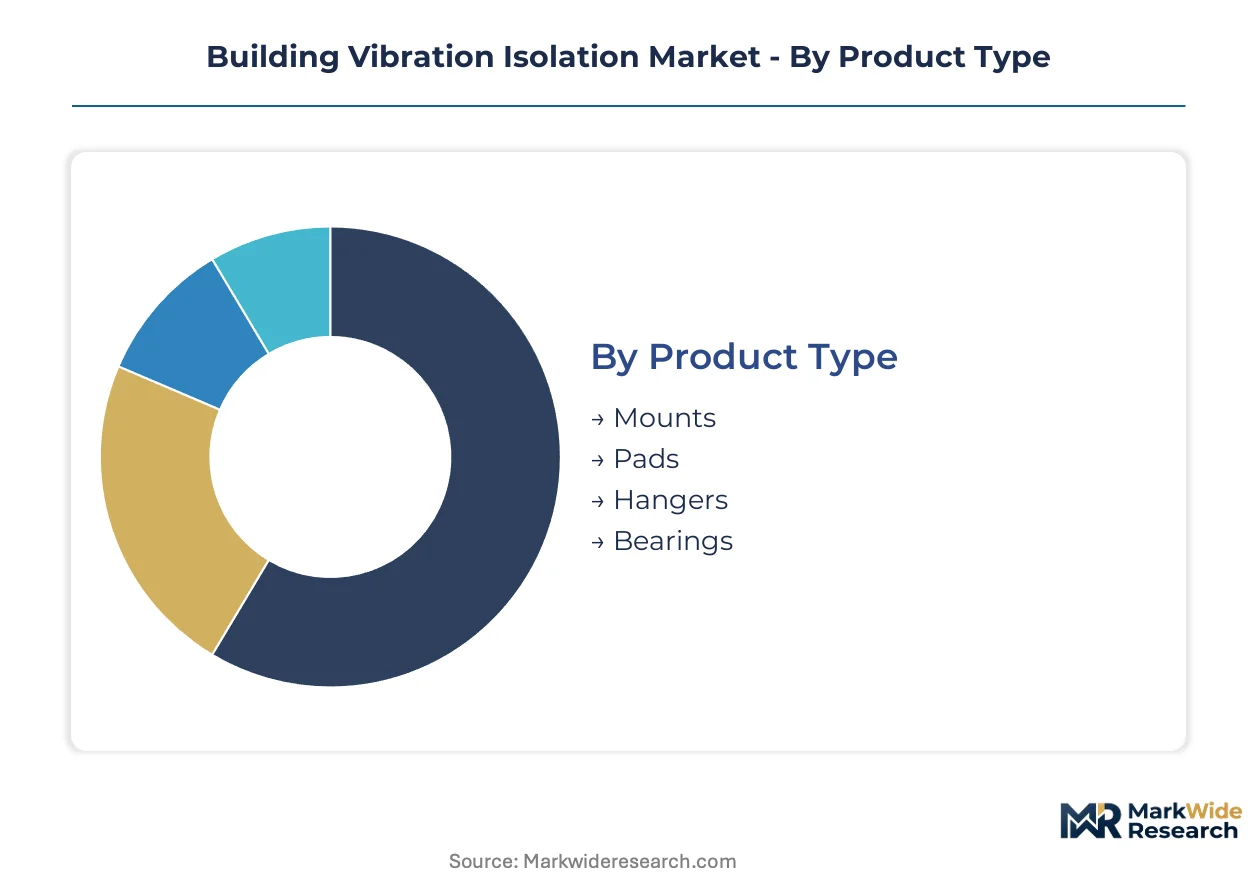
Segmentation in building vibration isolation reveals how specification authority flows from structural engineers to MEP consultants and ultimately to procurement teams. Product selection hinges on load-bearing requirements, frequency tuning precision, and compliance with jurisdiction-specific building codes rather than first-cost considerations alone.
Product Type:
Supply concentration for elastomeric compounds and spring steel favors manufacturers with backward integration into raw material processing, particularly in Germany and Japan where specialty rubber formulation and coil production clusters dominate global availability.
- Mounts:Threaded elastomer or spring-based assemblies attach directly to equipment frames, with natural frequencies tunable between 5-25 Hz depending on durometer selection. Demand concentrates in HVAC retrofit projects across Germany where DIN 4150 compliance upgrades mandate replacement of rigid connections on aging chiller and pump installations.
- Pads:Cork-elastomer or reinforced rubber sheets distribute loads across broad surface areas beneath heavy rotating machinery. China's subway expansion pipeline is amplifying specification volumes for high-damping variants beneath transformer and generator sets in underground electrical vaults adjacent to tunnel boring operations.
- Hangers:Spring or rubber-in-shear assemblies suspend piping and ductwork from overhead structure.
- Bearings:Laminated elastomer or sliding plate systems support structural columns and bridge seismic displacement.
Today's leader: Pads. Tomorrow's challenger: Bearings.
Technology:
Cost tier stratification separates commodity passive systems from premium active architectures, with hybrid configurations emerging as a mid-market bridge for facilities requiring adaptive performance without full sensor-actuator infrastructure.
- Active:Real-time sensor feedback drives electromagnetic or piezoelectric actuators to cancel incoming vibration within millisecond response windows. Semiconductor fabrication in Taiwan and South Korea sustains premium demand where sub-micron lithography tolerances justify control system complexity and maintenance overhead.
- Passive:Elastomeric, spring, or fluid-based systems rely on material damping properties without external power. India's hyperscale data center construction in Mumbai and Hyderabad is opening specification windows for conventional passive mounts beneath precision IT loads where capital constraints limit active system adoption.
- Hybrid:Combines passive load support with semi-active damping adjustment.
- Tuned Mass Damper:Counterweight systems calibrated to specific resonant frequencies for skyscraper sway mitigation.
Passive systems anchor current volume. Active architectures are climbing the fastest as sensor costs decline.
End User:
Application intensity varies dramatically across building types, with healthcare and laboratory facilities demanding performance guarantees that override first-cost considerations while residential projects prioritize code-minimum compliance.
- Commercial Buildings:Office towers, retail complexes, and hospitality structures require isolation for HVAC, elevator, and electrical infrastructure. Specification cycles are compressing in United States healthcare construction where MRI and proton therapy installations merge vibration and magnetic field isolation into unified procurement packages.
- Industrial Facilities:Manufacturing plants, power generation, and heavy process operations impose severe dynamic loads. REACH substance restrictions on certain plasticizers are forcing reformulation of legacy elastomer compounds used in European Union industrial bearings, with compounders accelerating bio-based alternatives through accelerated aging validation protocols.
- Residential Structures:Multi-family housing and single-family homes employ isolation for mechanical equipment and structural seismic protection.
- Educational Institutions:Universities and research facilities balance classroom comfort with sensitive instrumentation requirements.
Commercial Buildings dominate specification value. Industrial Facilities present the steepest expansion trajectory as manufacturing reshoring accelerates.
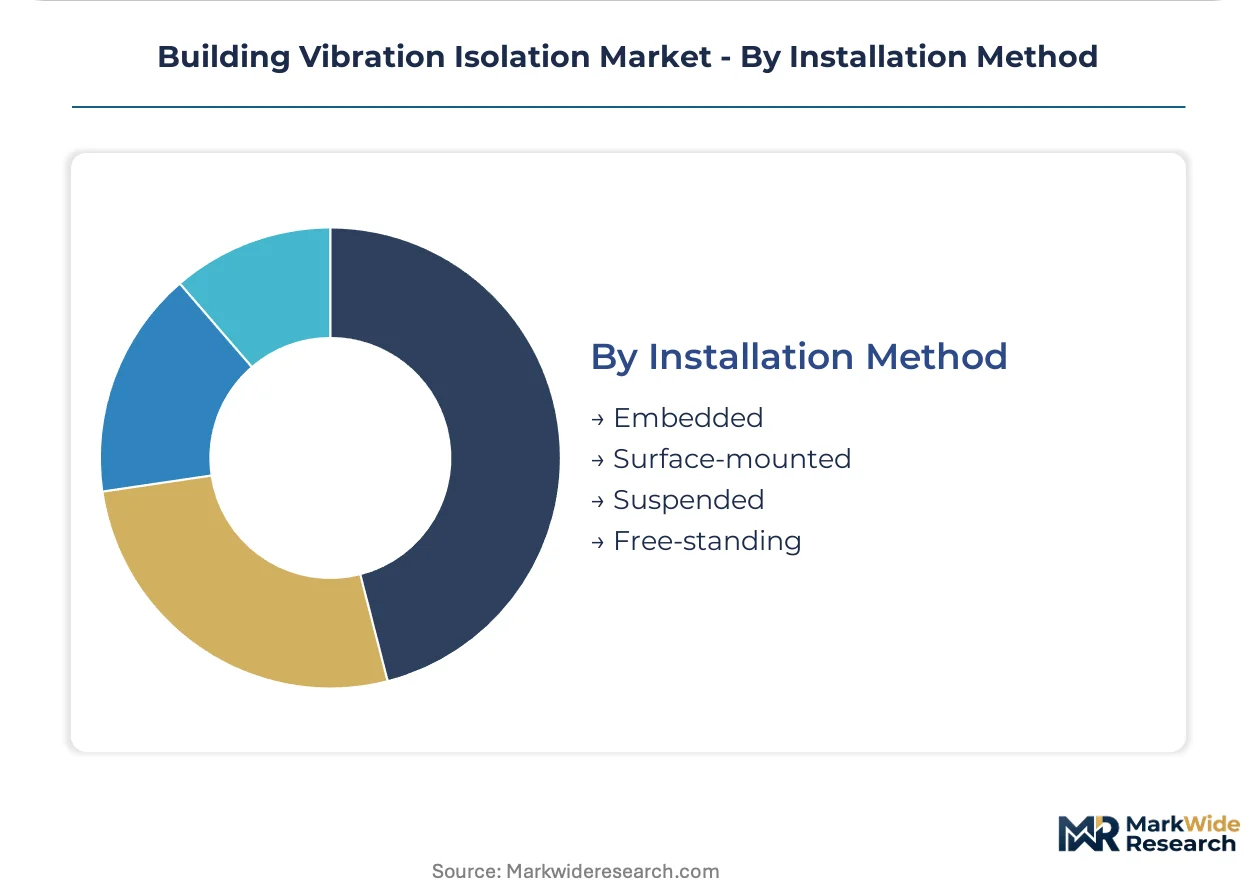
Installation Method:
Volume distribution skews toward surface-mounted and suspended configurations that minimize structural modification, while embedded systems concentrate in new construction where concrete pour sequencing permits integrated placement.
- Embedded:Isolation elements cast directly into concrete foundations or structural slabs during construction. Greenfield data center builds in Frankfurt and Amsterdam are specifying embedded spring isolators beneath precision cooling infrastructure to achieve sub-micron vibration thresholds without retrofit constraints.
- Surface-mounted:Post-construction attachment to existing structural elements using anchor bolts or adhesive bonding. Japan's JIS B 0911 machinery vibration standards are tightening retrofit requirements for surface-mounted isolators on existing rotating equipment in automotive and electronics manufacturing facilities.
- Suspended:Overhead attachment for piping, ductwork, and cable trays.
- Free-standing:Independent support structures decoupled from building frame.
Surface-mounted systems lead installed base. Embedded configurations are gaining share fastest as new construction pipeline recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting production investment toward zones with favorable compliance cost structures. Manufacturers are relocating elastomer compounding capacity to exploit gaps between REACH enforcement in Europe and less stringent chemical oversight elsewhere. This arbitrage dynamic shapes regional competitive positioning across the building vibration isolation supply base.
United States
Data center construction in Ashburn, Virginia and Phoenix, Arizona is compressing specification cycles for precision isolation beneath server racks and cooling infrastructure. ASHRAE equipment vibration criteria shape certification requirements for commercial and industrial projects. Specification authority concentrates with MEP engineers and acoustical consultants in healthcare construction across Texas and California.
Germany
DIN 4150 structural vibration standard revisions mandate upgraded isolation specifications across commercial and residential projects. Elastomer compounders in North Rhine-Westphalia expand production of high-damping rubber bearings for seismic and HVAC applications. REACH substance restrictions on certain plasticizers force reformulation of legacy compounds used in building bearings.
China
Subway expansion in Shanghai and Beijing amplifies structural damping requirements beneath high-rise foundations adjacent to tunnel boring operations. GB 50463 seismic isolation code segments compliance obligations by geography and application intensity. Manufacturing clusters in Jiangsu and Zhejiang provinces dominate domestic supply of laminated elastomer bearings for infrastructure projects.
India
Greenfield hyperscale data center construction in Mumbai and Hyderabad opens specification windows for active isolation beneath precision IT loads. BIS certification requirements for building materials create entry barriers for imported isolation systems. Industrial corridors in Gujarat and Tamil Nadu attract domestic fabrication capacity for spring and rubber isolators serving commercial projects.
Japan
JIS B 0911 machinery vibration standards tighten retrofit requirements for surface-mounted isolators on existing rotating equipment. METI industrial policy supports advanced damper development for skyscraper sway mitigation in Tokyo and Osaka. Specialty coil spring production clusters in Nagoya create supply concentration for precision isolation applications.
Building Vibration Isolation Market Vendor Landscape
German and Japanese producers anchor one tier; North American specialists hold specification relationships in domestic commercial construction. The vendor base organizes around three strategic archetypes: compounders with captive elastomer formulation, spring fabricators with metallurgical process control, and system integrators combining multiple damping technologies. Capacity expansion and portfolio diversification represent the dominant competitive moves as participants seek to span passive and active isolation categories.
Within the compounder archetype, Getzner and Regupol America exemplify regional production strategies that leverage geographic proximity to specification authorities. Mason Industries occupies a position among North American specialists with deep product concentration in commercial building applications. Fabreeka anchors the precision manufacturing segment through advanced material composites that serve semiconductor and laboratory infrastructure requirements.
| Leading Market Players |
|---|
| Mason Industries |
| Fabreeka |
| Kinetics Noise Control |
| Regupol America |
| VibraSystems |
| Farrat |
| Getzner |
| ACE Stosddämpfer |
| VMC Group |
| Others |
Supply Flow & Price Mechanics
Natural rubber feedstock costs from Malaysian and Indonesian plantations cascade through three pricing tiers downstream, with raw material volatility compressing margins most severely at compounders lacking backward integration into captive elastomer formulation.
Pricing Analysis
Distributor margins absorb the steepest compression when specialty coil spring manufacturers in Germany and Japan enforce minimum order quantities. Three-tier pricing structure across premium, standard, and economy levels separates active isolation systems with sub-micron precision guarantees from passive HVAC mounts and commodity bearing pads. Price differentiation hinges on ISO 2631 human vibration certification tier and volume scale. Cost compression in standard-tier elastomer bearings is intensifying because REACH-compliant bio-based compound reformulations carry premium feedstock burdens. Data center operators exhibit the least price sensitivity, while residential retrofit contractors face acute budget constraints.
Supply Chain Analysis
Specialty rubber formulation rests on concentrated production clusters in Germany, Japan, and China's Jiangsu province. High-damping elastomer compounds draw from Malaysian natural rubber, German carbon black additives, and Japanese synthetic polymer feedstocks. Single-source vulnerability concentrates in precision coil spring fabrication, where Nagoya and North Rhine-Westphalia facilities anchor global availability. Distribution runs through MEP engineering consultancies and acoustical specification authorities rather than general contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities open between REACH-restricted European compound costs and less stringent chemical oversight in Southeast Asian production zones, rewarding manufacturers with flexible geographic sourcing.
For Market Incumbents: Anticipate displacement pressure from magnetorheological fluid damper systems as real-time stiffness adjustment penetrates food processing and pharmaceutical packaging lines. Defend specification relationships by deepening captive elastomer formulation capacity in North Rhine-Westphalia. Prioritize DIN 4150 certification maintenance as German structural vibration thresholds tighten compliance burdens across EU commercial projects. For New Entrants and Emerging Players: Mid-tier Indian data center developers present the most penetrable buyer archetype, with Mumbai and Hyderabad greenfield construction opening specification windows beneath precision IT loads. Target passive isolation systems where capital constraints limit active architecture adoption. Pursue BIS certification pathways to overcome import barriers on foreign-manufactured bearings and mounts. For Investors and Strategic Acquirers: Consolidation pressure builds where compounder archetypes lack captive elastomer formulation and spring fabricators face metallurgical process control bottlenecks. Long-term viability favors vertically integrated producers spanning passive and active isolation categories. Acquisition targets should demonstrate specification authority with MEP engineers in United States healthcare construction. Monitor DIN 4150 enforcement intensity across EU member states as inflection indicator for premium product demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Formulation | Captive rubber compounding insulates margin from Malaysian natural rubber price volatility. |
| Active Isolation System Development | Real-time sensor-actuator architectures capture semiconductor fabrication specification premiums in Taiwan. |
| REACH-Compliant Compound Reformulation | Bio-based alternatives secure EU market access as ECHA restrictions tighten on legacy plasticizers. |
| Healthcare Specification Partnership | MRI and proton therapy procurement channels merge vibration and magnetic field isolation demand. |
| India Manufacturing Footprint Expansion | Domestic fabrication in Gujarat and Tamil Nadu satisfies BIS certification requirements for commercial projects. |
Methodological Framework
Coverage spans United States, Germany, China, India, and Japan, with primary inputs from each market cluster combining interviews with MEP engineers, acoustical consultants, elastomer compounders, and data center construction directors alongside secondary validation. Secondary sources include DIN 4150 technical documentation, GB 50463 seismic isolation code filings, ASHRAE equipment vibration criteria databases, and customs trade records for rubber bearing imports. Bottom-up project pipeline assessments triangulate against top-down construction spending aggregates.
Granularity-level framing models product type, technology tier, end-use application, and installation method dimensions at country-level resolution across the analysis window. CAGRs derive from weighted least-squares fitting to historical installation volumes and forward construction contract awards. Industry-specific inputs include subway expansion timelines in Shanghai and Beijing, hyperscale data center development schedules in Ashburn and Phoenix, and DIN 4150 revision implementation calendars.
Underlying measurement precision varies by segment; active isolation systems carry tighter precision than commodity pad and bearing categories due to concentrated semiconductor fabrication demand. Forecasts reflect assumptions regarding regulatory enforcement continuity, raw material supply stability, and construction cycle timing. Supply concentration in German and Japanese spring steel, REACH substance restriction expansion, and data center specification compression warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
Chain Link Fencing Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
External Wall Insulation Board Market