
 US Surgical Microscopes Market | 2026-2036
US Surgical Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
US Surgical Microscopes Market Intelligence
Digital fluorescence overlay and augmented reality guidance is rewriting the surgical visualization stack in American operating rooms. Carl Zeiss Meditec AG leverages its captive optics heritage to anchor premium neurosurgery installations across major US academic centers. Leica Microsystems sustains intense R&D spending to differentiate its hybrid platforms for microvascular procedures. Stryker Corporation competes through channel control, bundling microscope systems with its broader surgical navigation portfolio.
A surgical microscope is a precision optical instrument combining binocular eyepieces, adjustable objective lenses, and articulating suspension arms to deliver magnified, illuminated stereoscopic views of anatomical structures during invasive procedures; contemporary units integrate 4K digital cameras, exoscope video feeds, and robotic positioning motors to enable real-time image fusion and remote collaborative surgery. Floor-mounted configurations dominate hospital capital budgets due to stability requirements in lengthy neurosurgical cases, while compact designs are gaining fastest in ambulatory surgical centers where space constraints and turnover speed determine procurement. Optical technology retains the largest installed base, though hybrid platforms capturing simultaneous digital and direct-view pathways command the richest margin pools as surgeons demand seamless documentation and teaching capabilities.
FDA 510(k) clearance requirements govern device safety and electromagnetic compatibility for all surgical microscopes marketed in the United States, while the Centers for Medicare & Medicaid Services reimbursement coding directly shapes hospital purchasing cycles by determining procedure-level economic returns. State-level certificate-of-need regulations in markets like New York and California constrain capital equipment expansion unless providers demonstrate sufficient surgical volume thresholds. Stakeholders must monitor how CMS technology add-on payment decisions for robotic-assisted visualization will redistribute procurement authority between hospital supply chain committees and individual surgeon preference.
Market Dynamics
Hybrid digital-optical platforms are compressing replacement cycles across US academic medical centers as neurosurgery departments prioritize real-time image fusion capabilities over legacy optical-only systems.
Growth Catalysts
- FDA 510(k) clearance pathway compression:Streamlined electromagnetic compatibility reviews for robotic-assisted visualization systems are accelerating commercialization timelines for innovators targeting hospital capital committees.
- CMS technology add-on payments:Reimbursement coding expansions for robotic-assisted procedures are reshaping procurement authority toward individual surgeon preference in metropolitan surgical clusters.
- Neurosurgical volume concentration:Certificate-of-need thresholds in New York and California are consolidating demand among high-throughput academic centers capable of justifying premium platform investments.
Market Restraints
- Precision optics supply concentration:German and Japanese optical component suppliers dominate high-NA objective lens production, exposing US assemblers to transatlantic shipping volatility and currency fluctuation.
- Certificate-of-need regulatory friction:State-level CON regulations in California and New York require surgical volume demonstrations before capital expansion approval, freezing mid-tier hospital upgrade timelines.
- Hybrid platform cost structure:Simultaneous digital and direct-view optical pathways require dual sensor arrays and redundant illumination systems, elevating unit economics beyond ambulatory surgical center budgets.
Strategic Opportunities
- CMS technology add-on payment expansion:Pending reimbursement decisions for fluorescence-guided resection procedures could unlock procurement budgets among community hospital systems previously priced out of premium platforms.
- Exoscope-digital convergence:Video-feed visualization systems are penetrating spine and orthopedic applications previously served by traditional binocular microscopes, opening mid-market volume pools.
- Ambulatory surgical center channel development:Compact floor-mounted configurations with rapid sterilization cycles address space-constrained environments in Texas and Florida outpatient facilities.
Industry Challenges
- Electromagnetic compatibility certification timelines:FDA 510(k) submissions for systems integrating robotic positioning motors face extended review cycles due to novel electromagnetic interference testing requirements.
- Dual-pathway integration complexity:Hybrid platforms combining optical and digital feeds require specialized biomedical engineering support that exceeds standard hospital IT service capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Surgical Microscopes Market |
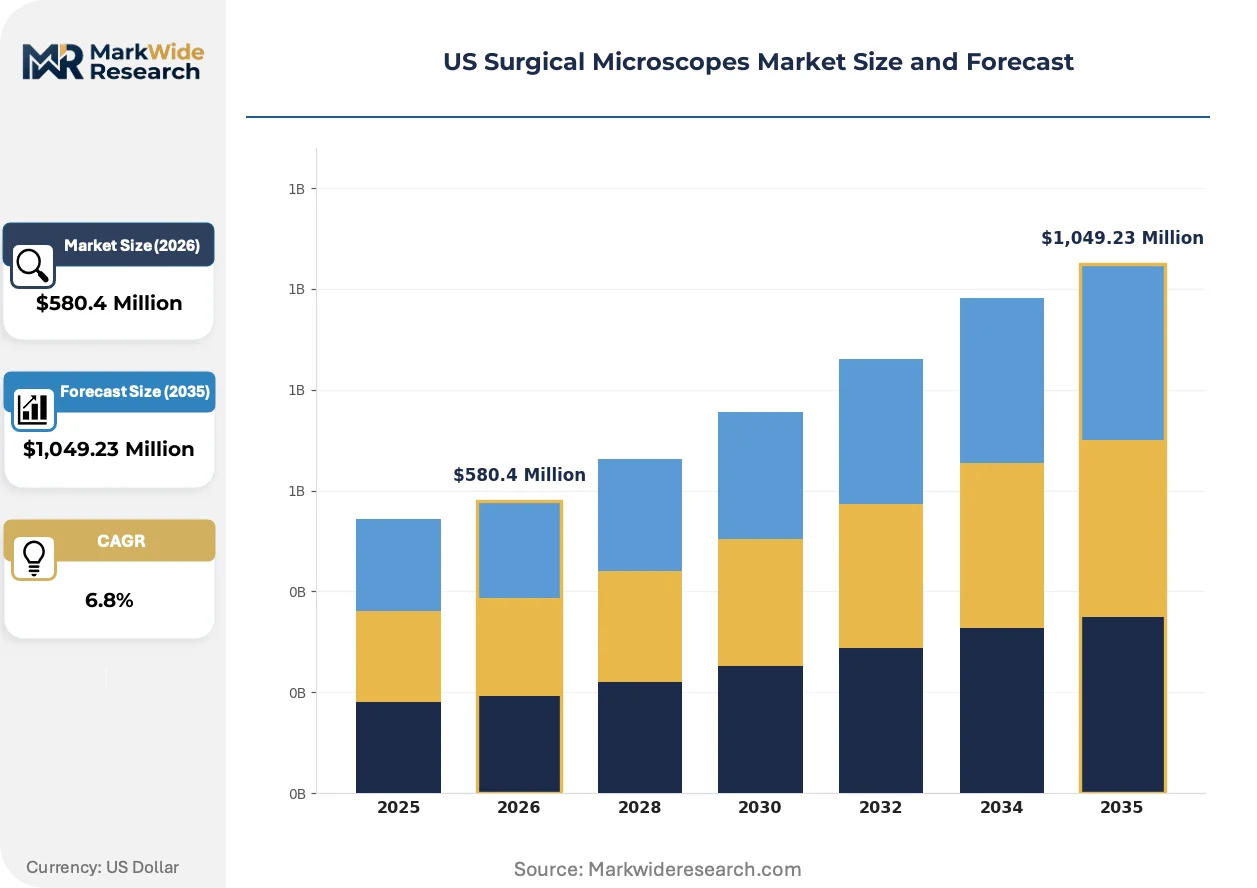
| Market Size in 2026 | $580.4 Million |
| Market Size in 2035 | $1,049.23 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Floor-mounted, Wall-mounted, Ceiling-mounted Technology: Optical, Digital, Hybrid, Robotic End User: Hospitals, Ambulatory Surgical Centers, Ophthalmology Clinics, Dental Clinics Application: Neurosurgery, Orthopedic Surgery, Plastic Surgery, ENT Surgery |
| Companies Covered | Carl Zeiss Meditec AG, Leica Microsystems, Olympus Corporation, Haag-Streit Surgical, Alcon Inc., Topcon Corporation, Stryker Corporation, Synaptive Medical Inc., Seiler Instrument Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Surgical Microscopes Market Strategic Shifts & Innovations
Digital fluorescence overlay systems are penetrating neurosurgical workflows at accelerating velocity, compressing the competitive window for legacy optical-only suppliers.
Fluorescence-guided resection technology enables real-time tumor margin visualization through indocyanine green dye activation. Academic medical centers in Boston and New York metropolitan clusters are standardizing this capability across neurosurgery departments. Traditional white-light-only visualization is rendering obsolete as residency programs now mandate fluorescence training for board certification eligibility.
CMS technology add-on payment deliberations for robotic-assisted visualization are restructuring hospital procurement committee authority. The pending reimbursement framework would shift capital equipment decision-making from supply chain officers toward individual surgeon preference cards. Neurosurgery service lines in Northeast corridor academic centers are preemptively securing budget allocation ahead of anticipated coding expansions.
Surgeon preference card unbundling is fragmenting traditional bundled equipment contracts. Hospital value analysis committees are separating microscope hardware from navigation software and maintenance agreements, enabling competitive bidding on discrete components. This disaggregation is most visible among IDN-affiliated facilities in the Midwest seeking to standardize platforms across multiple surgical sites.
US Surgical Microscopes Market Segmentation
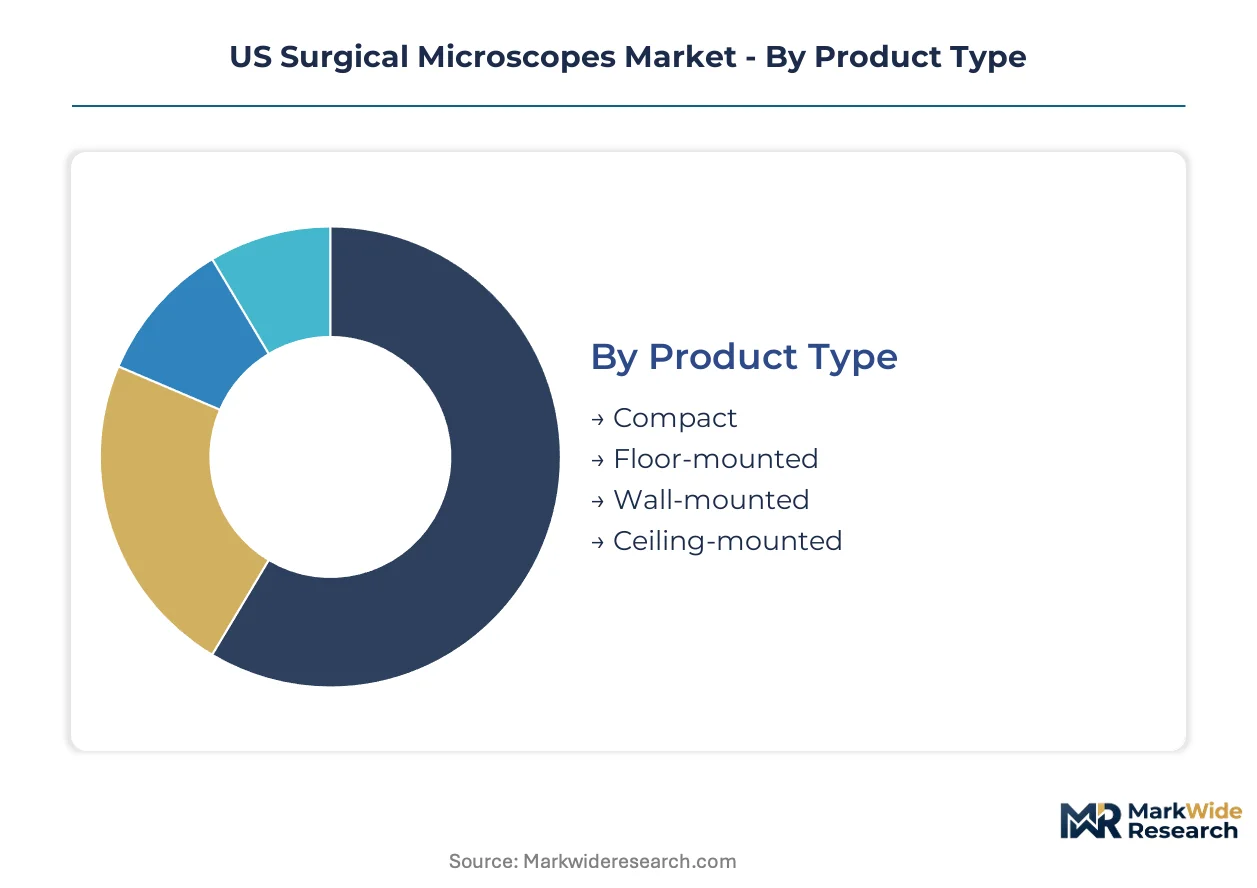
Surgical microscope procurement in the United States fragments across four distinct dimensions that shape capital allocation, reimbursement pathways, and vendor competitive strategy. Hospital value analysis committees weight product configuration against procedure volume, while technology selection determines long-term service contract economics and upgrade flexibility.
Product Type:
Cost tier differentiation separates configurations by stability requirements, installation complexity, and spatial footprint constraints.
- Floor-mounted:Heavy-duty castor-based or fixed-base units with counterbalanced suspension arms deliver maximum stability for multi-hour neurosurgical procedures. Demand concentrates in Boston and New York metropolitan academic medical centers where lengthy cranial cases justify premium capital investment and dedicated OR real estate.
- Compact:Reduced-footprint designs with rapid sterilization cycles and modular positioning systems address space-constrained environments. Texas and Florida ambulatory surgical centers are driving procurement volume as outpatient spine and ophthalmology procedures expand.
- Wall-mounted:Bracket-fixed units with fold-away arms optimize OR ceiling space for hybrid rooms requiring C-arm compatibility. Tertiary hospitals in California certificate-of-need jurisdictions favor this configuration for multi-specialty surgical suites.
- Ceiling-mounted:Overhead rail systems with motorized positioning eliminate floor obstruction entirely. Major academic centers in the Northeast corridor deploy these for complex microvascular reconstruction requiring unobstructed team movement.
Floor-mounted configurations command the established base. The steepest expansion runs through compact designs.
Technology:
Application maturity and margin capture potential stratify the technology stack from legacy optical through integrated robotic platforms.
- Hybrid:Simultaneous direct-view optical pathways and 4K digital camera feeds enable real-time documentation and remote consultation. Neurosurgery departments at Massachusetts General and Johns Hopkins are standardizing this capability for residency training and tumor board review.
- Optical:Pure binocular stereoscopic visualization through precision glass optics retains installed base dominance in community hospital settings. Cost constraints and limited biomedical engineering support keep these systems prevalent in Midwest IDN-affiliated facilities.
- Digital:Exoscope-based video feed visualization eliminates eyepiece fatigue and enables heads-up display integration. Spine surgery applications at Texas Medical Center outpatient facilities are accelerating adoption.
- Robotic:Motorized positioning with electromagnetic compatibility certification and programmable trajectory memory commands the richest pricing tier. FDA 510(k) clearance compression is accelerating commercialization for innovators targeting high-volume metropolitan surgical clusters.
Optical technology retains volume leadership. Hybrid platforms are gaining share fastest.
End User:
Customer type determines procurement authority structure, maintenance contract terms, and technology refresh cadence.
- Hospitals:Integrated delivery networks and academic medical centers with centralized capital committees and multi-year depreciation schedules. Certificate-of-need states like New York and California concentrate demand among high-throughput facilities capable of justifying premium platform investments.
- Ambulatory Surgical Centers:Physician-owned or joint-venture outpatient facilities with rapid turnover requirements and space optimization priorities. Florida and Texas certificate-of-need exemptions enable faster equipment procurement cycles.
- Ophthalmology Clinics:Specialized standalone or hospital-affiliated facilities focused on cataract and retinal procedures. Compact floor-mounted configurations with integrated OCT compatibility dominate this channel.
- Dental Clinics:Oral surgery and endodontic practices requiring lower-magnification stereoscopic visualization. Price sensitivity and limited procedure reimbursement constrain this segment to entry-level optical systems.
Hospitals anchor procurement volume. Ambulatory surgical centers are climbing the fastest.
Application:
Procedure reimbursement coding and clinical outcome evidence shape specialty-specific technology requirements and vendor targeting strategies.
- Neurosurgery:Cranial and spinal procedures demanding maximum magnification, fluorescence-guided resection capability, and extended stability. CMS technology add-on payment deliberations for robotic-assisted visualization are restructuring procurement authority toward individual surgeon preference in Northeast corridor academic centers.
- Orthopedic Surgery:Spine and hand microsurgery applications with growing adoption of exoscope-digital convergence. Texas and Florida ambulatory facilities are expanding microsurgical spine procedures previously confined to hospital settings.
- Plastic Surgery:Microvascular free tissue transfer and reconstructive procedures requiring precise anastomosis visualization. Academic centers in Boston and New York maintain concentrated demand for hybrid platform capabilities.
- ENT Surgery:Otologic and skull base procedures with moderate magnification requirements and shorter case durations. Community hospital systems in the Midwest favor cost-optimized optical configurations for this application.
Neurosurgery commands the established base. Orthopedic surgery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US surgical microscopes market exhibits pronounced regional concentration, with equipment procurement patterns reflecting local certificate-of-need regulations, academic medical center density, and metropolitan surgical volume thresholds. Import reliance for precision optical components from German and Japanese suppliers creates supply chain exposure that shapes regional distributor strategies.
Northeast Corridor
Massachusetts General Hospital and Johns Hopkins anchor neurosurgery demand for hybrid digital-optical platforms with fluorescence-guided resection capabilities. FDA 510(k) clearance compression benefits Boston-based innovators targeting academic medical center procurement committees. New York State certificate-of-need regulations consolidate capital equipment authority among high-throughput Manhattan and Long Island surgical clusters.
Texas Medical Center Hub
Texas certificate-of-need exemptions enable faster ambulatory surgical center equipment procurement cycles than coastal regulatory environments. Compact floor-mounted configurations with rapid sterilization cycles penetrate Houston and Dallas outpatient spine surgery facilities. The state's lack of CON friction attracts orthopedic microsurgical volume previously confined to hospital settings.
California
Certificate-of-need thresholds in Los Angeles and San Francisco metropolitan areas freeze mid-tier hospital upgrade timelines unless providers demonstrate sufficient surgical volume. Wall-mounted configurations optimize OR ceiling space for hybrid rooms requiring C-arm compatibility at tertiary facilities. Precision optics supply concentration exposes California assemblers to trans-Pacific shipping volatility.
Florida Peninsula
Florida certificate-of-need exemptions for ambulatory surgical centers drive compact microscope procurement for ophthalmology and outpatient spine procedures. Miami and Tampa metropolitan clusters concentrate demand for space-constrained configurations with modular positioning systems. Retiree demographic density sustains cataract surgery volume that supports dedicated ophthalmology clinic equipment refresh cycles.
Midwest IDN Networks
Integrated delivery network standardization initiatives across Illinois, Michigan, and Ohio favor cost-optimized optical configurations for community hospital ENT and general surgery applications. Surgeon preference card unbundling fragments traditional bundled equipment contracts as value analysis committees separate hardware from navigation software. Cleveland Clinic and Mayo Clinic Rochester anchor premium platform demand for residency training programs.
US Surgical Microscopes Market Key Industry Players
On the supply side, the industry is moderately consolidated around precision optics heritage and surgical navigation integration capabilities. German and Japanese optical component suppliers dominate high-NA objective lens production, creating upstream bottlenecks that shape competitive positioning. Three strategic archetypes populate the vendor landscape: captive optics manufacturers with century-long heritage, diversified surgical navigation conglomerates, and digital visualization specialists. M&A activity concentrates on fluorescence imaging technology acquisition, while portfolio diversification drives bundling of microscope hardware with navigation software and maintenance agreements.
Within the heritage optics tier, Carl Zeiss Meditec AG and Leica Microsystems exemplify premium neurosurgery installation strategies anchored to academic medical center relationships. Stryker Corporation occupies a diversified navigation conglomerate position, competing through channel control and surgical equipment portfolio breadth. Synaptive Medical Inc. represents the digital-native archetype, with electromagnetic compatibility certification for robotic positioning systems compressing FDA 510(k) timelines relative to legacy optical incumbents.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Leica Microsystems |
| Olympus Corporation |
| Haag-Streit Surgical |
| Alcon Inc. |
| Topcon Corporation |
| Stryker Corporation |
| Synaptive Medical Inc. |
| Seiler Instrument Inc. |
| Others |
Cost & Logistics Intelligence
Transatlantic tariff exposure on precision optical components from German and Japanese suppliers compresses margin structures across all pricing tiers while forcing US assemblers to reconfigure sourcing footprints and inventory depth strategies.
Pricing Analysis
Hospital capital committees anchor pricing stratification across premium, standard, and economy tiers differentiated by fluorescence capability certification and robotic positioning integration. Price differentiation hinges on FDA 510(k) clearance tier and bundled navigation software depth. Cost compression in mid-tier configurations intensifies as community hospital systems demand optical-only alternatives. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers show lowest.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk calculations for high-NA objective lens procurement. Manufacturing concentrates in Germany, Japan, and Switzerland for precision glass optics. Raw material dependencies span rare-earth illumination phosphors, electromagnetic motor assemblies, and sapphire lens substrates. Single-source vulnerability persists for robotic positioning encoders. Distribution runs through regional medical equipment distributors with GPO contract alignment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorescence imaging engineering talent scarcity constrains competitive replication speed, elevating the strategic value of incumbent R&D teams and specialized acquisition targets with captive dye-activation protocols.
For Market Incumbents: Harden electromagnetic compatibility certification pipelines to accelerate FDA 510(k) timelines against digital-native challengers. Deepen backward integration into objective lens polishing capabilities to reduce transatlantic shipping exposure. Channel control through GPO contract exclusivity remains the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in Texas and Florida ambulatory surgical centers where certificate-of-need exemptions enable faster procurement cycles. Target compact floor-mounted configurations for outpatient spine applications. Pursue exoscope-digital convergence as the primary go-to-market angle. For Investors and Strategic Acquirers: CMS technology add-on payment deliberations for robotic-assisted visualization reshape the acquisition landscape toward fluorescence-guided resection specialists. Long-term viability centers on reimbursement coding alignment rather than hardware differentiation alone. Watch for FDA 510(k) clearance compression announcements as the definitive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed electromagnetic compatibility reviews unlock metropolitan academic center procurement ahead of competitors. |
| Fluorescence Technology Acquisition | Indocyanine green dye activation capabilities differentiate tumor margin visualization in neurosurgery workflows. |
| Hospital System Partnership | GPO contract alignment with IDN value analysis committees secures multi-site standardization mandates. |
| Software Companion Development | Navigation software unbundling enables competitive bidding on discrete components beyond hardware. |
| Reimbursement Strategy | CMS technology add-on payment positioning shifts procurement authority toward individual surgeon preference cards. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and GPO contract disclosures. Interviews engaged neurosurgery department chairs, biomedical engineering directors, hospital value analysis committee members, and GPO contracts managers. Secondary validation drew from SEC 10-K disclosures, academic medical center capital budget documents, and state certificate-of-need filings. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Forecast inputs incorporate procedure volume trajectories, technology replacement cycles, and reimbursement coding evolution across the projection horizon. Segmentation modeling spans product configuration, technology tier, end-user type, and application specialty. CAGRs derive from weighted average of historical replacement patterns and anticipated adoption inflections. Industry-specific inputs include FDA clearance pipeline velocity and CMS technology add-on payment deliberation timelines.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure budgets or transatlantic shipping cost volatility would shift the trajectory. Forecasts reflect documented assumptions subject to revision from regulatory timing changes or competitive entry dynamics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cervical Retractors Market
Medical Devices
Non- Resorbable Cranial Fixation System Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Ultrasound Biometry Devices Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Cannula Market
Medical Devices
Pericardial Patches Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
Medical Electronics Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Smart Lenses Market