
 Fluorescence Cell Market | 2026-2036
Fluorescence Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorescence Cell Market Analysis
German precision optics manufacturers is broadening the supply base for fluorescence cell detection components. Thermo Fisher Scientific leverages integrated reagent-instrument platforms to sustain recurring revenue streams across clinical and research segments. Danaher Corporation anchors its position through Beckman Coulter's flow cytometry portfolio, which dominates high-parameter cell analysis in academic medical centers. PerkinElmer Inc. competes on specialized imaging workstations tailored to live-cell kinetic assays in drug discovery settings.
Fluorescence cells are optical cuvettes or microplates fabricated from quartz, fused silica, or UV-grade polymers, engineered with precise path lengths and chamber geometries to enable excitation and emission light capture from labeled biological specimens. These components serve as the fundamental sample interface in instruments quantifying cellular protein expression, viability, or molecular interactions through fluorophore emission spectra. Confocal microscopes command the largest installed base among product types, though flow cytometers generate the highest annual consumables pull through sheath fluid and fluorescent antibody reagents. Research laboratories represent the most fragmented end-user segment, while pharmaceutical companies concentrate spending on automated high-content screening systems for lead optimization pipelines.
FDA 21 CFR Part 820 quality system regulations govern fluorescence cell manufacturing for clinical diagnostics applications, while ISO 10993 biocompatibility standards constrain material selection for devices contacting biological specimens. The EPA oversees fluorophore waste disposal protocols from research facilities, adding operational compliance costs to end-user facilities. Stakeholders must monitor evolving CLIA proficiency testing requirements for cell-based diagnostic assays, as these standards directly determine instrument qualification pathways and replacement cycles for fluorescence cell consumables.
Market Dynamics
The fluorescence cell market is experiencing structural compression as instrument manufacturers consolidate reagent-instrument platforms to capture recurring revenue streams, forcing standalone component suppliers to defend position through specialized geometries and faster fulfillment cycles.
Growth Catalysts
- High-Throughput Screening Expansion:Pharmaceutical companies are scaling automated fluorescence-based workflows for lead optimization pipelines, pulling demand for standardized microplate formats and multi-channel detection cells.
- CLIA Proficiency Testing Mandates:Updated clinical laboratory quality requirements in the United States are accelerating replacement cycles for diagnostic-grade fluorescence consumables to maintain assay validation compliance.
- Quartz Supply Diversification:German precision optics manufacturers are broadening the supplier base for UV-grade fused silica substrates, reducing lead times for high-transmission cell fabrication.
Market Restraints
- Fluorophore Waste Compliance:EPA disposal protocols for hazardous fluorescent reagents add operational overhead to research facilities, constraining budget allocation for consumable procurement.
- Optical-Grade Polymer Cost Volatility:UV-transparent cyclo-olefin polymer feedstock prices fluctuate with specialty petrochemical supply chains, compressing margins for disposable cell manufacturers.
- Path-Length Precision Tolerances:Sub-micron chamber geometry requirements for quantitative fluorescence assays limit viable fabrication methods to specialized quartz grinding operations concentrated in Central Europe.
Strategic Opportunities
- Live-Cell Kinetic Assay Workstations:Drug discovery settings in Boston and San Diego biotech clusters are adopting specialized imaging platforms requiring custom chamber designs for extended time-lapse experiments.
- ISO 10993 Biocompatibility Certification:Material qualification standards for devices contacting biological specimens create differentiation pathways for suppliers offering pre-validated polymer formulations.
- Sheath Fluid Integration:Flow cytometer consumables bundles combining fluorescent antibody reagents with optimized detection cells are displacing standalone component purchasing in academic medical centers.
Industry Challenges
- Multi-Parameter Optical Alignment:High-content screening systems require precise excitation-emission path calibration across 96- and 384-well formats, extending field service deployment timelines and technical training requirements.
- 21 CFR Part 820 Documentation Burden:Clinical diagnostics manufacturers face exhaustive design history file maintenance for FDA quality system compliance, slowing new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorescence Cell Market |
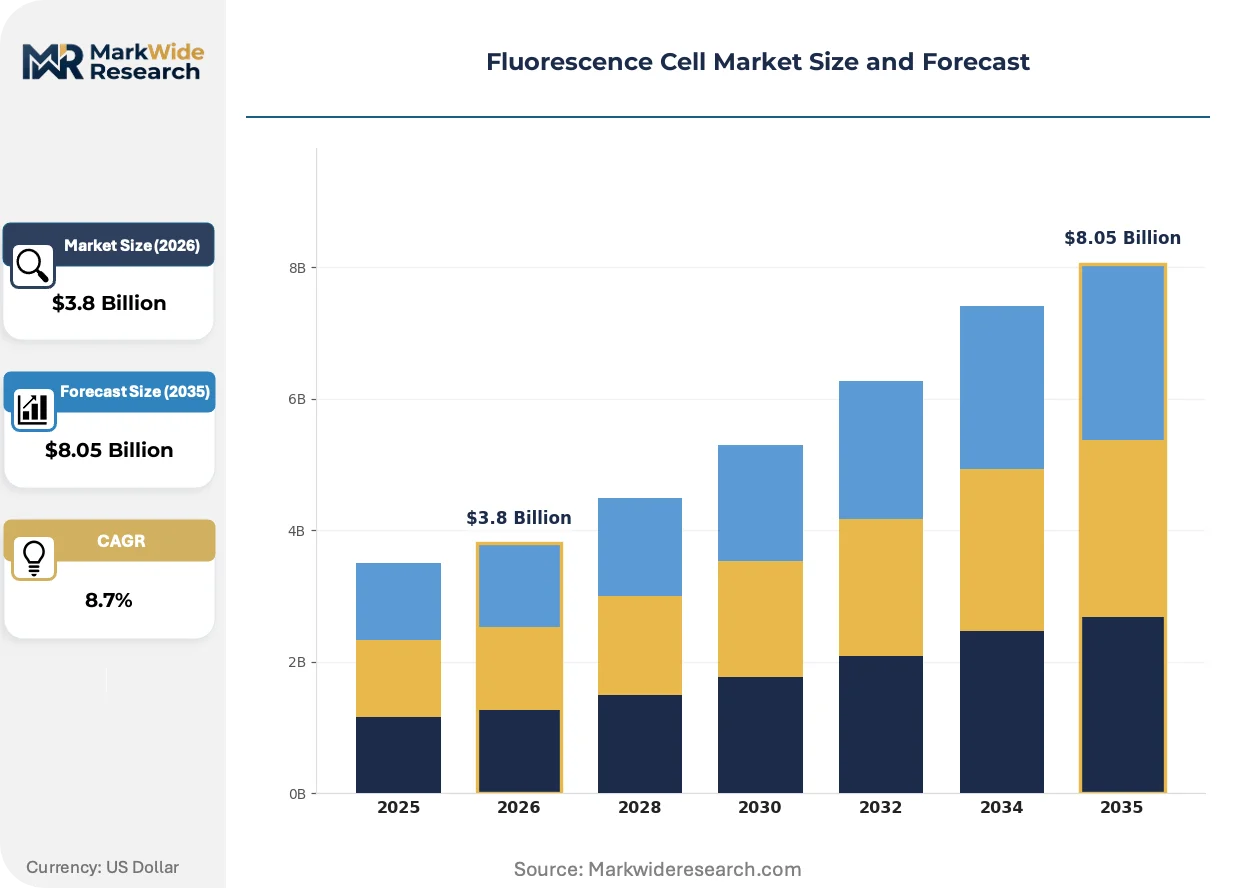
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Confocal Microscopes, Flow Cytometers, Imaging Systems, Laser Scanners Technology: Multi-Photon, FRET, SPIM, Resonance-Enhanced End User: Research Laboratories, Clinical Laboratories, Pharmaceutical Companies, Academic Institutions Application: Genetics Research, Cancer Diagnostics, Drug Discovery, Cell Biology |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, PerkinElmer Inc., Bio-Rad Laboratories, Becton Dickinson and Company, Agilent Technologies, Carl Zeiss AG, Olympus Corporation, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorescence Cell Market Emerging Trajectories
Solid-state light sources and computational imaging algorithms are compressing instrument footprints while expanding multiplexing capabilities, fundamentally altering how fluorescence detection architectures interface with sample containers.
Spectral unmixing algorithms paired with LED excitation engines is rewriting the performance benchmarks for compact fluorescence readers. Contract research organizations in the United States are adopting these platforms for decentralized screening nodes. The shift is compressing demand for traditional filter-based monochromator cells while expanding volumes for broadband-transparent quartz formats.
EMA's In Vitro Diagnostic Medical Devices Regulation implementation is tightening material traceability requirements for fluorescence cells entering European clinical workflows. Manufacturers must now document full supply chain provenance for fused silica substrates and polymer additives. German and Swiss component suppliers are responding by qualifying captive melting operations to satisfy notified body audit protocols.
Consolidated procurement contracts spanning reagents, instruments, and consumables are displacing standalone fluorescence cell purchasing in large pharmaceutical accounts. Thermo Fisher Scientific and Danaher Corporation leverage these bundled agreements to lock multi-year supply commitments. The pattern is most visible in United States NIH-funded research institutions where grant administration favors single-vendor compliance documentation.
Fluorescence Cell Market Segmentation
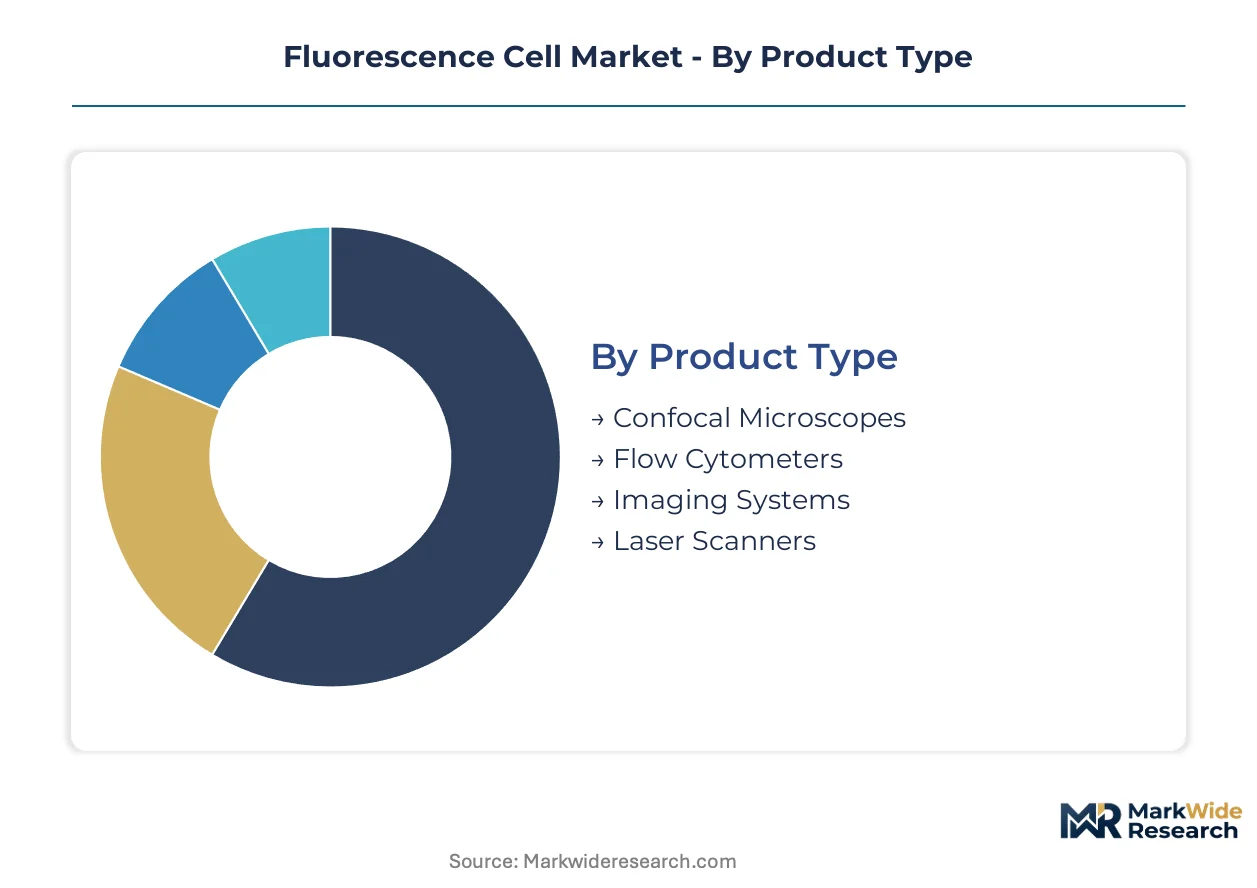
Fluorescence cell procurement decisions hinge on optical performance specifications, regulatory compliance tiers, and integration depth with existing instrument platforms. Understanding how demand fragments across product architectures and user workflows exposes where suppliers can defend margin or capture volume.
Product Type:
Purchase volume concentrates in platforms generating recurring consumables pull-through rather than standalone capital equipment.
- Confocal Microscopes:These systems employ pinhole-based optical sectioning to eliminate out-of-focus fluorescence from thick biological specimens. Demand clusters in academic medical centers across Germany and Switzerland where NIH-funded investigators require sub-micron resolution for protein localization studies. Zeiss and Leica Microsystems dominate installed base maintenance contracts in these settings.
- Flow Cytometers:Fluidics-based single-cell analysis platforms achieve high-parameter immunophenotyping through laser excitation and photomultiplier detection. Pharmaceutical companies in Boston and San Diego biotech corridors are scaling automated workflows for lead optimization, driving standardized microplate format procurement. Sheath fluid and fluorescent antibody re bundles now displace standalone cell purchasing in these accounts.
- Imaging Systems:Live-cell kinetic workstations support extended time-lapse experiments for drug mechanism studies.
- Laser Scanners:High-throughput microarray readers serve genomics screening facilities requiring rapid slide-based quantification.
Confocal microscopes lead on scale through installed base dominance; flow cytometers lead on momentum through consumables bundling acceleration.
Technology:
Technical selection criteria center on multiplexing depth, phototoxicity thresholds, and compatibility with existing fluorophore panels.
- Multi-Photon:Near-infrared excitation enables deep tissue imaging with reduced photodamage. Demand concentrates in neuroscience research institutes across the United States where intact brain slice preparations require penetration beyond 500 microns. Two-photon architectures from Thorlabs and Bruker Corporation anchor this segment.
- FRET:Förster resonance energy transfer quantifies molecular proximity through donor-acceptor emission ratio shifts. Structural biology departments at Max Planck Institute facilities in Germany drive specialized chamber demand for protein interaction validation. Precision path-length tolerances below 50 nanometers constrain supplier qualification.
- SPIM:Selective plane illumination microscopy achieves rapid volumetric imaging with minimal photobleaching.
- Resonance-Enhanced:Plasmonic substrate architectures amplify weak fluorescence signals for single-molecule detection.
FRET commands premium pricing through technical complexity; multi-photon gains share fastest through neuroscience funding expansion.
End User:
Budget authority and compliance documentation requirements fragment procurement patterns across institutional types.
- Research Laboratories:Fragmented academic and government facilities prioritize cost flexibility and grant-compliant vendor selection. United States NIH-funded institutions favor single-source documentation to streamline audit preparation. Thermo Fisher Scientific and PerkinElmer compete on integrated reagent-instrument bundles in these accounts.
- Pharmaceutical Companies:Automated high-content screening operations demand validated, traceable consumables for regulatory submission support. GSK and Novartis procurement contracts specify ISO 10993 biocompatibility certification for devices contacting biological specimens. Multi-year supply agreements now standard for lead optimization pipeline continuity.
- Clinical Laboratories:CLIA-mandated proficiency testing accelerates replacement cycles for diagnostic-grade fluorescence cells.
- Academic Institutions:Core facility shared instrumentation models concentrate purchasing authority in centralized procurement offices.
Pharmaceutical companies lead on scale through concentrated spending power; clinical laboratories lead on momentum through regulatory-driven refresh cycles.
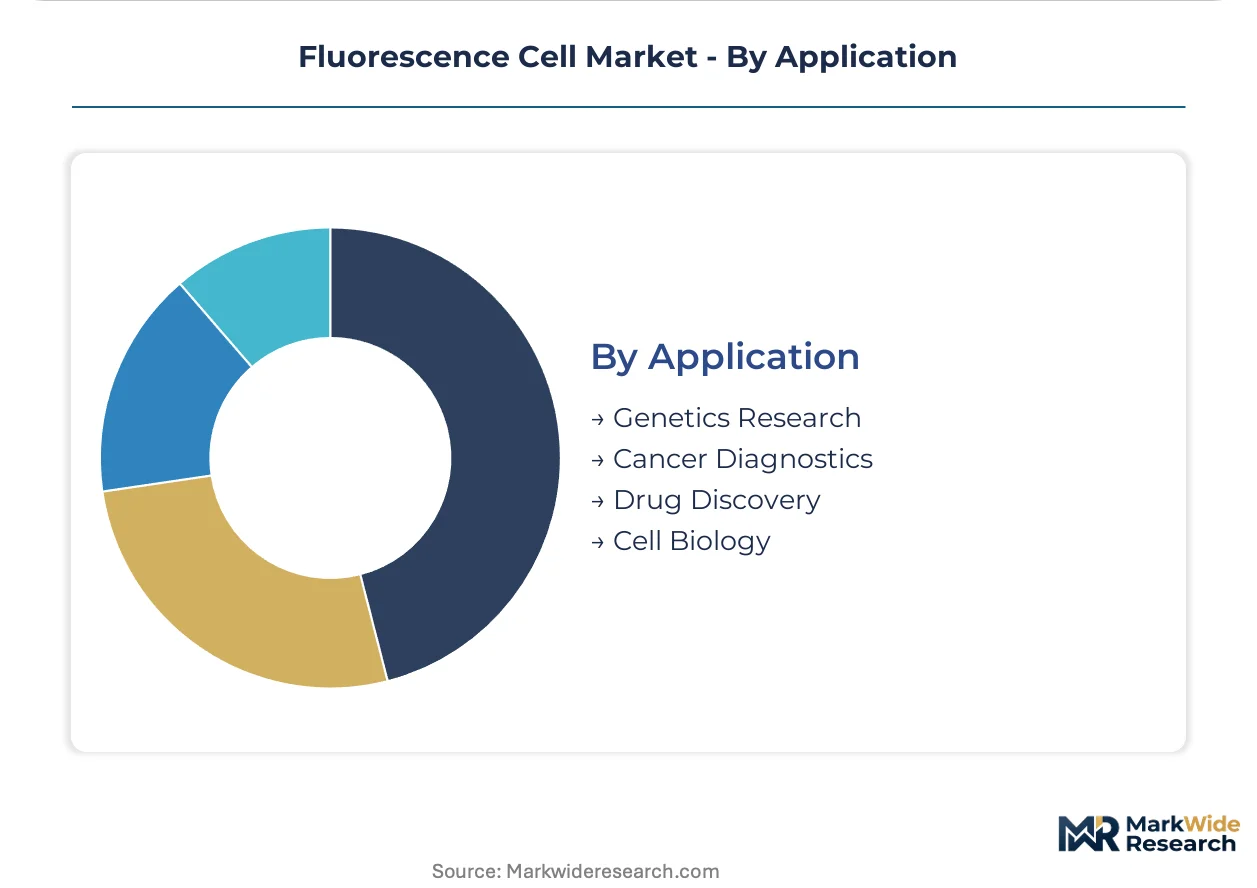
Application:
Workflow specificity determines chamber geometry requirements and optical path customization needs.
- Drug Discovery:High-throughput screening of compound libraries against cellular targets demands 384-well format compatibility and automated liquid handling integration. Contract research organizations in San Diego and Boston biotech clusters are adopting spectral unmixing platforms with LED excitation engines. These compact readers compress demand for traditional filter-based monochromator cells.
- Cancer Diagnostics:Circulating tumor cell enumeration and immunohistochemistry quantification require FDA 21 CFR Part 820 quality system documentation. Clinical laboratories in the United States face exhaustive design history file maintenance for assay validation compliance. Diagnostic-grade quartz cells carry 3-5x premium over research-grade equivalents.
- Genetics Research:CRISPR screening and single-cell RNA sequencing workflows drive specialized microfluidic chamber demand.
- Cell Biology:Fundamental membrane dynamics and organelle trafficking studies sustain baseline demand for standard cuvette formats.
Drug discovery leads on scale through pharmaceutical R&D concentration; cancer diagnostics leads on momentum through clinical assay regulatory expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fluorescence cell supply chains as manufacturers migrate production toward jurisdictions with streamlined quality system documentation, while demand concentrates in research clusters where NIH and EU framework program funding sustains instrument procurement cycles.
United States
NIH-funded research institutions and Boston-San Diego biotech corridors drive concentrated demand for high-throughput screening platforms. FDA 21 CFR Part 820 quality system regulations govern clinical diagnostics-grade cell manufacturing, tightening documentation burdens for suppliers. Massachusetts and California academic medical centers anchor the largest installed bases of confocal microscopy and flow cytometry systems.
Germany
Precision optics manufacturers in Bavaria and Baden-Württemberg dominate UV-grade fused silica substrate supply for detection cell fabrication. EMA In Vitro Diagnostic Medical Devices Regulation implementation tightens material traceability requirements for European clinical workflows. Max Planck Institute facilities in Munich and Heidelberg sustain specialized demand for FRET-compatible chamber geometries.
Switzerland
Swissmedic oversight of clinical diagnostics devices creates a premium regulatory tier for fluorescence cells entering hospital laboratories. Roche and Novartis procurement specifications cascade through CRO networks in Basel and Zurich. The country's precision engineering cluster supports sub-micron path-length tolerance manufacturing for quantitative assays.
China
NMPA medical device registration pathways are accelerating for imported fluorescence detection platforms serving domestic pharmaceutical R&D expansion. Yangtze River Delta biotech parks in Shanghai and Suzhou are scaling automated screening infrastructure. Local quartz processing capacity is expanding to reduce dependency on Central European substrate supply.
United Kingdom
UK Research and Innovation funding streams sustain core facility instrumentation at Oxford, Cambridge, and London institutional clusters. MHRA convergence with EU MDR standards post-Brexit maintains aligned quality benchmarks for diagnostic-grade consumables. London-based CROs are adopting spectral unmixing platforms for decentralized screening nodes.
Fluorescence Cell Market Vendor Landscape
German and Swiss precision optics specialists anchor one tier; United States-based diversified life science conglomerates hold consolidated positions through integrated reagent-instrument platforms. The market structure bifurcates between component suppliers defending margin through geometric specialization and full-platform vendors capturing recurring revenue via bundled procurement contracts. Three archetypes dominate: captive optics fabricators, diversified instrument-reagent integrators, and niche live-cell imaging workstation builders. Competitive intensity centers on M&A consolidation of reagent portfolios and vertical control over quartz supply chains.
Within the diversified instrument-reagent tier, Thermo Fisher Scientific and Danaher Corporation exemplify platform consolidation strategies that lock multi-year supply commitments through bundled agreements. PerkinElmer Inc. occupies a specialized position among imaging workstation builders targeting drug discovery settings with customized kinetic assay configurations. These three entities collectively represent the competitive tension between scale-driven platform bundling and application-specific technical differentiation that defines current market positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| PerkinElmer Inc. |
| Bio-Rad Laboratories |
| Becton Dickinson and Company |
| Agilent Technologies |
| Carl Zeiss AG |
| Olympus Corporation |
| Sartorius AG |
| Others |
Supply Flow & Price Mechanics
EPA fluorophore waste disposal protocols gate both qualified supply and premium-tier pricing access for fluorescence cell manufacturers serving clinical diagnostics segments. Compliance documentation burdens under 21 CFR Part 820 quality system regulations stratify the supplier base into FDA-validated tiers commanding 3-5x research-grade premiums, while non-compliant fabricators face exclusion from hospital laboratory procurement channels.
Pricing Analysis
Distributor margins in the 15-25% range separate OEM-direct contract pricing from catalog list prices for research-grade consumables. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 biocompatibility certification status, quartz optical grade, and path-length precision tolerances. Pricing pressure stems from consolidated procurement contracts bundling reagents, instruments, and consumables at pharmaceutical accounts. Contract research organizations exhibit highest price sensitivity due to grant-funded budget constraints, while clinical laboratories prioritize assay validation compliance over unit cost.
Supply Chain Analysis
China's NMPA domestic-content preferences are reshaping sourcing patterns for Yangtze River Delta biotech parks scaling automated screening infrastructure. UV-grade fused silica substrate supply concentrates in Germany, Switzerland, and emerging Chinese quartz processing capacity. Fabrication rests on specialty petrochemical feedstocks for cyclo-olefin polymers, precision grinding equipment from Central Europe, and rare-earth-doped glass for optical components. Single-source vulnerability in sub-micron path-length grinding operations constrains capacity expansion. Distribution runs through direct OEM partnerships for large pharmaceutical accounts, specialized distributors for academic medical centers, and catalog channels for fragmented research laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fluorescence cell market functions as a stable compounder anchored by CLIA-mandated replacement cycles for diagnostic-grade consumables that sustain recurring revenue visibility regardless of R&D funding volatility.
For Market Incumbents: Cement platform dominance through captive quartz supply agreements with Bavarian precision optics manufacturers and accelerated ISO 10993 certification pipelines for polymer formulations. Threat from spectral unmixing LED platforms displacing filter-based monochromator demand demands counter-positioning through integrated reagent-instrument bundles. Vertical integration into sheath fluid formulation locks multi-year flow cytometer consumables commitments at academic medical centers. For New Entrants and Emerging Players: Mid-tier contract research organizations in San Diego and Boston biotech corridors represent an underserved buyer archetype seeking faster fulfillment cycles and flexible minimum order quantities bypassing consolidated vendor agreements. White-space exists in custom chamber geometries for live-cell kinetic workstations requiring extended time-lapse compatibility. Entry angle: specialized FRET-compatible geometries for Max Planck Institute structural biology departments with precision path-length tolerances below 50 nanometers. For Investors and Strategic Acquirers: Roll-up economics work for precision optics fabricators because sub-micron grinding capability scarcity concentrates in Central European supplier clusters with limited replication feasibility. Long-term viability hinges on regulatory moat depth under evolving FDA and EMA material traceability mandates. Acquisition target archetype: German or Swiss captive melting operations with notified body audit qualification. Signal to watch: NMPA accelerated registration pathways for imported platforms signaling Chinese pharmaceutical R&D infrastructure buildout intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Substrate Supply | German captive melting operations satisfy EMA material traceability requirements for European clinical workflows. |
| ISO 10993 Biocompatibility Certification Investment | Pre-validated polymer formulations differentiate suppliers targeting GSK and Novartis procurement specifications. |
| Sheath Fluid-Reagent Bundling Expansion | Combined consumables packages displace standalone cell purchasing in NIH-funded academic medical centers. |
| Custom Chamber Geometry Development | Specialized kinetic assay configurations capture drug discovery spending at Boston and San Diego biotech clusters. |
| Regional Distribution Partnership Formation | Localized fulfillment nodes address CRO demand for faster procurement cycles and flexible order minimums. |
Methodological Framework
Coverage spans the United States, Germany, Switzerland, China, and the United Kingdom, with primary inputs from each market informing demand segmentation and competitive positioning assessments. Primary interviews with fluorescence instrument product managers, clinical laboratory directors, pharmaceutical procurement leads, and precision optics manufacturing executives combined with secondary validation from FDA 510(k) filings, EMA In Vitro Diagnostic Medical Devices Regulation guidance documents, NIH grant award databases, and German mechanical engineering association trade statistics. Bottom-up instrument installed base estimates triangulated against top-down consumables pull-through calculations derived from reagent-instrument platform revenue disclosures.
Rate-of-change decomposition across the projection horizon separates volume growth from mix shift and pricing trajectory components. Segmentation dimensions modeled include product architecture, technology type, end-user institution category, application workflow, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, adjusted for CLIA proficiency testing mandate implementation timelines and pharmaceutical R&D pipeline stage distributions. Industry-specific forecast inputs encompass NIH funding appropriation trajectories, EMA notified body audit capacity constraints, and Chinese NMPA medical device registration pathway velocity.
Underlying measurement precision varies by segment; clinical diagnostics-grade fluorescence cells carry tighter precision than research-grade equivalents due to mandatory FDA quality system documentation. Forecasts reflect assumptions regarding sustained NIH funding levels, stable EMA-MDR implementation timelines, and continued German-Swiss dominance in precision optics fabrication. Regulatory acceleration in Chinese market access, breakthrough solid-state excitation technology adoption curves, and fluorophore waste disposal cost inflation represent triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Magnetic Resonance Analyzer Market
Medical Diagnostics
Cellular Pathology Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Global HLA Typing Market
Medical Diagnostics
Asia Pacific Immunohistochemistry Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
Carrier Screening Market