
 Nerve Locator Stimulator Market | 2026-2036
Nerve Locator Stimulator Market Size, Share, and Industry Trends Forecast 2026-2036
Nerve Locator Stimulator Market Foresight
Silicone-insulated probe tips is hardening as the preferred material standard over older PVC coatings in next-generation handheld devices. Medtronic plc leverages its neurotechnology portfolio to sustain R&D intensity across electromagnetic field platforms. B. Braun Melsungen AG anchors European hospital channel relationships through specialized anesthesia accessories. Stryker Corporation competes in surgical assistance applications by integrating nerve locator stimulators with its broader powered instrument ecosystem.
A nerve locator stimulator is an electrophysiological device that delivers calibrated electrical impulses to peripheral nerves, typically operating at frequencies between 1-2 Hz and pulse widths of 0.1-1.0 milliseconds, enabling clinicians to map neural pathways prior to needle insertion or surgical intervention. Handheld devices dominate current procurement volumes across hospitals and surgical centers due to their compatibility with sterile field protocols and lower capital burden versus tabletop systems. Ultrasound guidance technology represents the fastest-expanding segment as hybrid electro-stimulation and imaging platforms reduce procedure time and complication rates in anesthesia applications. Wireless models are capturing emerging demand in emergency services where tethered equipment limits patient mobility during pre-hospital nerve blocks.
The FDA enforces 21 CFR Part 820 quality system regulations and IEC 60601-1 electrical safety standards for nerve stimulators marketed in the United States, while the EU Medical Device Regulation requires notified body conformity assessment under Annex IX for Class IIa stimulation devices. These frameworks elevate compliance costs for entrants but simultaneously protect incumbent manufacturers with established quality management systems. Stakeholders must monitor evolving reimbursement policies for nerve block procedures across Medicare and major European sickness funds, as coding changes directly influence capital equipment purchasing cycles in hospital systems.
Market Dynamics
Electrical-safety recertification under the EU MDR is forcing device manufacturers to redesign legacy stimulation platforms, compressing product lifecycles and elevating R&D burn rates across the competitive set.
Growth Catalysts
- Regional anesthesia protocols:Western European surgical centers now mandate nerve localization prior to needle insertion, embedding handheld stimulators into standard perioperative workflows.
- REACH-compliant silicone insulation:Biocompatibility-grade probe coatings are displacing PVC alternatives in next-generation devices, satisfying both clinical performance and environmental compliance requirements.
- Emergency medical services expansion:Pre-hospital care systems across Germany and France are equipping mobile units with wireless nerve stimulators for field-based pain management.
Market Restraints
- Notified body bottlenecks:EU MDR conformity assessment queues for Class IIa devices now stretch 18-24 months, freezing product launches and freezing working capital.
- Precious metal input costs:Platinum-iridium electrode tips face price volatility from South African mining supply disruptions, squeezing gross margins on precision probe assemblies.
- Ultrasound-guided substitution:Pure imaging-based nerve blocks without electrophysiological confirmation are capturing low-acuity cases in cost-constrained hospital systems.
Strategic Opportunities
- Hybrid platform convergence:Integration of electromagnetic field stimulation with real-time ultrasound imaging creates premium-tier systems for academic medical centers.
- Ambulatory surgery center penetration:Freestanding ASCs in France and Germany represent underpenetrated demand for compact, single-use-compatible devices.
- IRIA reimbursement alignment:French national health insurance coding updates for nerve block procedures create direct capital equipment purchasing incentives.
Industry Challenges
- Electrophysiology-anesthesiology skill bridging:Clinicians trained in ultrasound-guided techniques require retraining on combined electro-stimulation protocols, slowing adoption curves.
- Legacy device obsolescence:EU MDR technical documentation requirements for existing product lines demand substantial retrofit investment without guaranteed recertification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nerve Locator Stimulator Market |
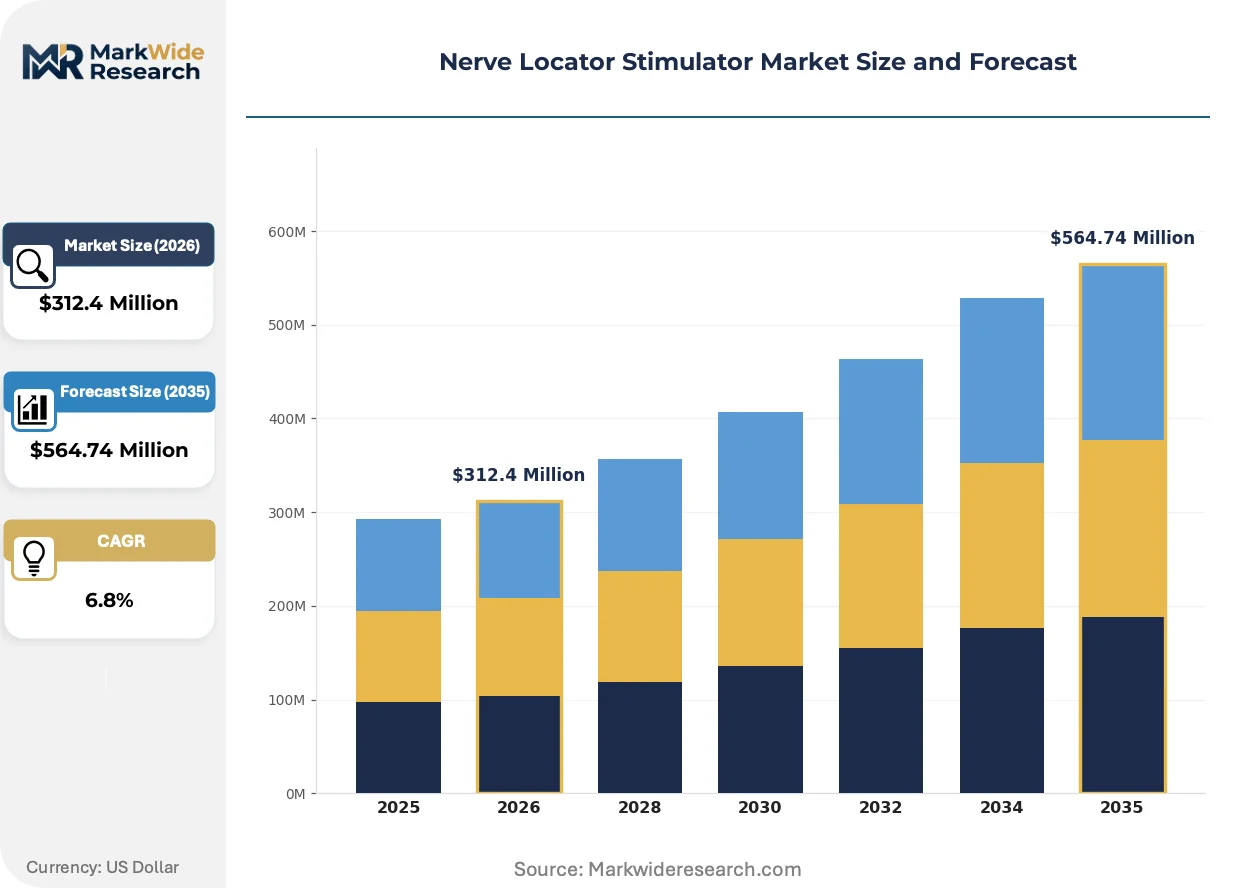
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Portable Units, Tabletop Systems, Wireless Models Technology: Electro-Stimulation, Ultrasound Guidance, Optical Imaging, Electromagnetic Fields End User: Hospitals, Clinics, Surgical Centers, Emergency Services Application: Pain Management, Anesthesia, Neuromodulation, Surgical Assistance |
| Companies Covered | B. Braun Melsungen AG, Medtronic plc, Teleflex Incorporated, Vygon Group, Pajunk GmbH, Nihon Kohden Corporation, Smith’s Medical, Ambu A/S, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nerve Locator Stimulator Market Shifts & Advancements
Device architecture is pivoting toward multimodal platforms that fuse electrical stimulation with imaging guidance, while regulatory compliance costs are restructuring competitive economics across the manufacturer base.
Silicone-insulated probe assemblies are converging with miniaturized pulse-generation circuitry to enable single-patient-use disposable tips. Academic anesthesia departments in Germany are piloting these hybrid platforms for complex brachial plexus procedures. The technology is converging with sterile supply chain protocols to reduce cross-contamination risk in high-throughput surgical environments.
The EU Medical Device Regulation is tightening electrical-safety and biocompatibility documentation requirements for Class IIa stimulation devices. Manufacturers must now submit clinical evaluation reports under Annex IX, elevating quality management system investments. Western European hospital procurement committees are prioritizing MDR-certified inventory, disadvantaging legacy devices with transitional certificates.
Hospital buying committees are consolidating vendor relationships around full-procedure solution providers rather than standalone device suppliers. French and German anesthesia departments now bundle nerve stimulator procurement with ultrasound system leases and disposable needle contracts. This concentration is most visible in university hospital systems where standardization across multiple surgical sites drives volume pricing negotiations.
Nerve Locator Stimulator Market Segmentation
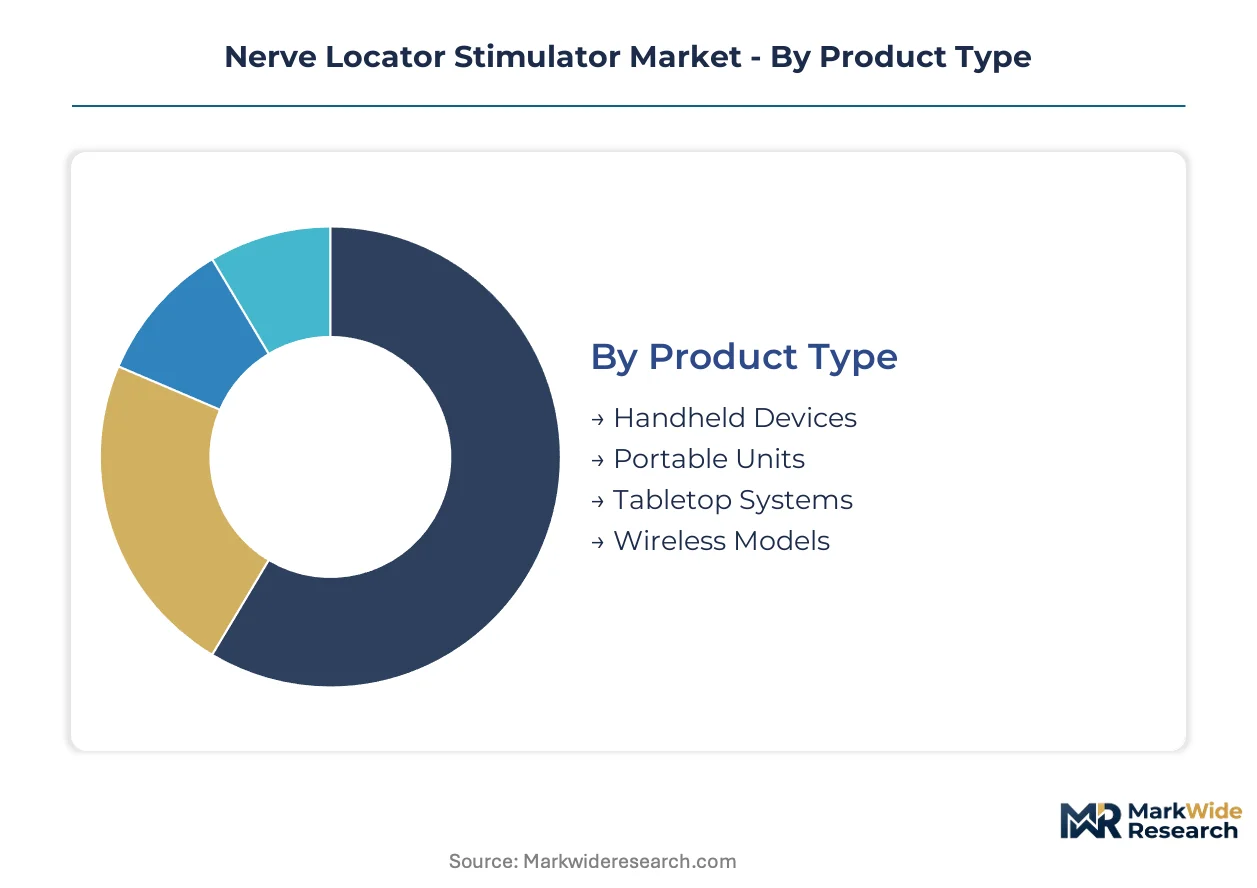
Segmentation in nerve locator stimulators reveals distinct procurement patterns across integration depths. Standalone handheld units dominate high-volume hospital purchasing, while embedded multimodal systems command premium positioning in academic surgical centers.
Product Type:
Standalone handheld devices serve rapid-deployment scenarios, whereas tabletop and wireless platforms embed into integrated surgical workflows.
- Handheld Devices:Battery-powered units with pulse widths adjustable between 0.1-1.0 milliseconds dominate German and French hospital procurement for regional anesthesia blocks. Operating room sterilization protocols favor these compact units for their compatibility with sterile draping and rapid turnover between cases.
- Wireless Models:Bluetooth-enabled stimulators with rechargeable lithium-polymer batteries are penetrating French emergency medical services for pre-hospital pain management. Field medics require untethered mobility during patient transport, driving specifications for IP-rated enclosures and extended battery life.
- Portable Units:Mid-size devices bridge handheld convenience with enhanced output precision for ambulatory surgical centers.
- Tabletop Systems:Cart-mounted platforms with integrated monitoring displays anchor neurosurgical suites requiring sustained stimulation protocols.
Volume placements concentrate in handheld devices; the faster expansion belongs to wireless models.
Technology:
Cost tiers separate mature electro-stimulation platforms from emerging imaging-hybrid systems requiring capital-intensive infrastructure.
- Electro-Stimulation:Conventional constant-current generators operating at 1-2 Hz frequencies remain the baseline technology across European hospital systems. German anesthesia departments specify these units for cost-effective nerve mapping in high-throughput orthopedic surgery.
- Ultrasound Guidance:Real-time sonographic visualization combined with electrical confirmation reduces needle passes and complication rates in brachial plexus procedures. French university hospitals are piloting these hybrid platforms for complex thoracic blocks.
- Electromagnetic Fields:Non-contact nerve localization using induced electrical fields is gaining traction in minimally invasive spinal surgery.
- Optical Imaging:Near-infrared spectroscopy for nerve differentiation remains confined to research applications in specialized neurosurgical centers.
Electro-stimulation commands the installed base; ultrasound guidance is climbing the fastest.
End User:
Customer maturity varies from protocol-standardized hospitals to fragmented emergency services with divergent purchasing authority.
- Hospitals:Centralized procurement committees in German university hospital systems bundle nerve stimulator acquisition with anesthesia disposable contracts. EU MDR certification requirements are filtering vendor pools toward established quality management systems.
- Surgical Centers:Freestanding French ambulatory surgery centers prioritize compact devices with single-use-compatible probe tips for infection control.
- Clinics:Pain management practices in regional France favor portable units for office-based peripheral nerve blocks.
- Emergency Services:Mobile medical units across German federal states are equipping wireless stimulators for field anesthesia.
Hospital systems absorb the largest procurement volumes; surgical centers are gaining share fastest.
Application:
Application segments align with reimbursement coding and procedural volume concentration in Western European healthcare systems.
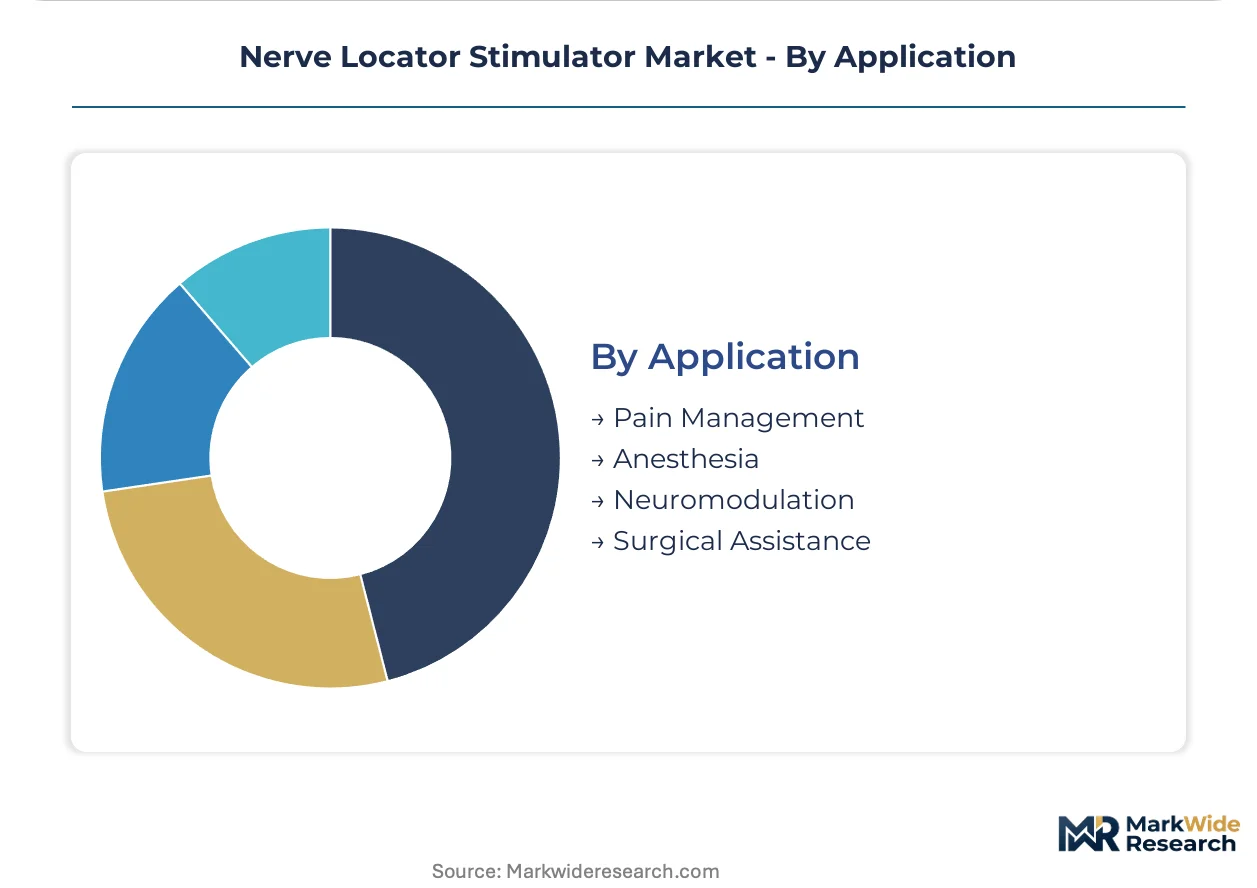
- Anesthesia:Perioperative nerve blocks for orthopedic and thoracic surgery represent the core demand driver across French and German surgical volumes. IRIA reimbursement alignment in France directly stimulates capital equipment purchasing cycles.
- Pain Management:Chronic neuropathic pain protocols in outpatient settings favor handheld devices with simplified user interfaces for non-anesthesiologist operators.
- Surgical Assistance:Intraoperative nerve monitoring during thyroid and parotid surgery requires tabletop systems with continuous feedback capabilities.
- Neuromodulation:Peripheral nerve stimulation for movement disorders remains a niche application in specialized German neurosurgical centers.
Anesthesia applications anchor procurement volumes; pain management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bavaria and Île-de-France channel medical device manufacturing investment into concentrated clusters. Tax incentives for precision electronics assembly draw component suppliers to these regions. Hospital procurement standardization across Western Europe reinforces geographic concentration.
Germany
University hospital systems in Bavaria and North Rhine-Westphalia bundle nerve stimulator procurement with anesthesia disposable contracts. EU MDR notified body assessments under TÜV SÜD and DEKRA stretch 18-24 months, freezing product launches. The Munich medical technology corridor anchors R&D activity for next-generation handheld platforms.
France
IRIA reimbursement coding for nerve block procedures directly stimulates capital equipment purchasing in Île-de-France and Auvergne-Rhône-Alpes. ANSM oversight of Class IIa device conformity elevates quality management requirements. Lyon surgical centers pilot hybrid electro-stimulation and ultrasound platforms for complex thoracic procedures.
United States
FDA 21 CFR Part 820 enforcement and IEC 60601-1 electrical safety standards shape device design specifications for the North American market. Hospital procurement committees in the Boston-Cambridge medical cluster prioritize MDR-equivalent quality documentation. The Minnesota medical device corridor sustains R&D intensity across electromagnetic field platforms.
United Kingdom
Post-Brexit UKCA marking requirements diverge from EU MDR frameworks, creating parallel compliance pathways for manufacturers. NHS England procurement frameworks standardize nerve stimulator specifications across London and Midlands surgical networks. The Oxford-Cambridge life sciences cluster supports niche development in optical imaging guidance systems.
Japan
PMDA quality system regulations and JIS electrical safety standards govern device approval timelines for the Japanese market. METI industrial policy channels precision electronics manufacturing into the Nagoya medical device corridor. Osaka-based anesthesia departments specify compact handheld units for high-throughput orthopedic surgery workflows.
Nerve Locator Stimulator Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-procedure solution providers capturing hospital committee consolidation. The vendor base organizes around three archetypes: diversified medical technology conglomerates with neurotechnology portfolios, specialized anesthesia equipment suppliers with deep European channel relationships, and surgical assistance platform integrators. M&A activity concentrates on electromagnetic field technology assets, while capacity expansion targets REACH-compliant silicone insulation supply chains.
Among diversified technology conglomerates, Medtronic plc and Stryker Corporation exemplify scale-driven platform strategies that bundle nerve stimulation with broader surgical ecosystems. B. Braun Melsungen AG anchors the specialized equipment tier through its German GmbH structure and established anesthesia accessories positioning. These three entities occupy distinct competitive vectors—technology integration, regional channel depth, and surgical workflow embedding—without overlapping core value propositions.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Medtronic plc |
| Teleflex Incorporated |
| Vygon Group |
| Pajunk GmbH |
| Nihon Kohden Corporation |
| Smith's Medical |
| Ambu A/S |
| Stryker Corporation |
| Others |
Supply & Pricing Matrix
Platinum-iridium electrode price volatility from South African mining disruptions cascades through probe assembly costs into three distinct procurement tiers across European hospital systems. REACH-compliant silicone insulation premiums compress margins at the mid-market level while MDR-certified devices command sustained pricing power against legacy alternatives.
Pricing Analysis
Short lead-time premiums of 15-20% apply to wireless stimulator orders from French emergency medical services requiring rapid deployment. Three-tier pricing structure across MDR-certified premium, transitional-standard, and economy legacy devices reflects certification-grade differentiation rather than performance alone. Pricing pressure stems from ultrasound-guided substitution capturing low-acuity nerve blocks without electrophysiological confirmation. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while German university hospital systems prioritize total-cost-of-ownership over unit pricing.
Supply Chain Analysis
Dual-sourcing mandates from German hospital procurement committees require qualified suppliers for both pulse-generation circuitry and probe tip assemblies. Component concentration centers on Switzerland for precision electronics, Germany for silicone insulation processing, and South Africa for platinum-iridium electrode material. Raw material dependencies include biocompatibility-grade silicone, lithium-polymer battery cells, and platinum-group metals. Single-source vulnerability in South African mining supply creates exposure to export restriction scenarios. Distribution runs through specialized anesthesia equipment distributors with direct hospital contracts rather than open-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nerve locator stimulator market functions as a cost-of-compliance arena where EU MDR Annex IX clinical evaluation requirements erect formidable barriers against undercapitalized entrants. Established quality management systems represent defensible moats as notified body queues stretch toward two-year cycles.
For Market Incumbents: Acquire electromagnetic field technology assets to anchor next-generation hybrid platform development. Consolidate around full-procedure solution bundling that pairs nerve stimulators with ultrasound leases and disposable needle contracts. Defend against pure-imaging substitution by embedding electrophysiological confirmation into standardized perioperative protocols. Capacity addition in Bavaria and Île-de-French manufacturing corridors secures proximity to core demand clusters.
For New Entrants and Emerging Players: French ambulatory surgery centers represent the most penetrable buyer archetype given their prioritization of compact single-use-compatible devices over established brand relationships. Wireless stimulator specifications for German emergency medical services offer a second white-space target with less entrenched vendor loyalty. A reimbursement-alignment go-to-market approach leveraging IRIA coding updates directly stimulates capital equipment purchasing cycles.
For Investors and Strategic Acquirers: The window for entry favors specialized anesthesia equipment suppliers with established European channel depth over diversified conglomerates. Long-term viability hinges on MDR certification completion timelines and hybrid platform R&D execution. Acquisition target archetypes include REACH-compliant silicone insulation specialists and electromagnetic field sensor developers. The signal to watch is ANSM and BfArM guidance on transitional certificate expiration dates.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Completion | Annex IX conformity assessment unlocks European hospital procurement committee eligibility. |
| Hybrid Platform Development | Electromagnetic field integration with ultrasound imaging commands premium positioning in academic centers. |
| Single-Use Probe Tip Conversion | Disposable silicone-insulated assemblies align with infection control protocols in high-throughput surgical environments. |
| Emergency Services Wireless Deployment | Bluetooth-enabled stimulators penetrate German and French pre-hospital pain management systems. |
| Reimbursement Strategy Alignment | IRIA coding synchronization in France directly influences capital equipment purchasing cycles. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and CMS Medicare reimbursement records underwrites the qualitative findings in this study. Primary interviews with anesthesia department heads, biomedical engineers, hospital purchasing committee members, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body assessment databases, and IRIA reimbursement coding updates. Bottom-up demand modeling from procedure volume estimates triangulates against top-down manufacturer revenue analysis.
Comparable historical reference periods spanning pre-MDR and transitional regulatory phases anchor the forecast window calibration across the projection horizon. Segmentation dimensions include product architecture, technology platform, end-user facility type, and application area with additional granularity on certification status tiers. CAGRs derive from logarithmic trend fitting against normalized procedure growth and capital equipment replacement cycles. Forecast inputs incorporate REACH compliance cost trajectories and platinum-group metal price elasticity assumptions.
Revisions become necessary when notified body assessment timelines extend beyond modeled ranges or when ultrasound-guided substitution rates accelerate in cost-constrained hospital systems. Forecasts reflect documented assumptions regarding MDR implementation uniformity across member states and reimbursement stability for nerve block procedures. A model refresh is warranted upon material change in EU MDR guidance on Class IIa device clinical evaluation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Infertility Devices Market
Medical Devices
North America and Europe Medical Technology Market
Medical Devices
Penile Implants Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Ear Tube Devices Market
Medical Devices
Advanced Infusion Systems Market
Medical Devices
IV Therapy and Vein Access Devices Market
Medical Devices
Transcatheter Pulmonary Valve Replacement Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
US Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Craniomaxillofacial Implants Market
Medical Devices
Portable OT Light Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Electrophysiology Ablation Market