
 Global Smart Wearable Healthcare Devices Market | 2026-2036
Global Smart Wearable Healthcare Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Wearable Healthcare Devices Market Foresight
Platform licensing revenue is fragmenting across wearable operating systems as hardware margins compress and data monetization models proliferate. Apple Inc. leverages its HealthKit ecosystem to anchor recurring service revenue streams. Samsung Electronics competes through open-architecture partnerships with telemedicine platforms. Garmin Ltd. specializes in ruggedized outdoor health metrics that differentiate its device portfolio from lifestyle-oriented competitors.
Smart wearable healthcare devices integrate biosensors, wireless connectivity, and embedded algorithms to capture physiological signals such as photoplethysmography-derived blood oxygen saturation and multi-lead electrocardiography waveforms for ambulatory cardiac monitoring. These instruments serve clinical decision support by enabling continuous data streams outside traditional care settings. Smartwatches with ECG and blood oxygen capabilities command the largest installed base, while glucose monitors represent the fastest-expanding category as closed-loop insulin delivery systems gain regulatory traction. Remote patient monitoring applications attract the highest reimbursement rates, whereas wellness tracking functions face margin erosion from commoditized fitness band competition.
FDA premarket clearance requirements for Class II medical device wearables shape product development timelines and R&D allocation across manufacturers. EMA MDR compliance in Europe and NMPA registration pathways in China add parallel certification burdens that favor firms with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving reimbursement codes for continuous monitoring in Medicare and national health service frameworks, as payment policy determines commercial viability faster than sensor innovation cycles.
Market Dynamics
Software as a Medical Device pathways at FDA are compressing development cycles for biosensor manufacturers while simultaneously fragmenting competitive moats as algorithmic differentiation becomes more portable across hardware platforms.
Growth Catalysts
- Closed-loop insulin delivery:Regulatory traction for automated glucose control systems is expanding addressable patient populations beyond Type 1 diabetics into prediabetic monitoring segments.
- Medicare reimbursement expansion:New CPT codes for continuous cardiac monitoring are converting wellness device purchases into reimbursable clinical expenditures across United States health systems.
- Photoplethysmography miniaturization:Advances in optical sensor integration enable multi-parameter vital sign capture from wrist-worn form factors previously requiring chest patches.
Market Restraints
- EMA MDR compliance costs:European medical device regulation recertification requirements are consuming 18-24 month approval timelines that freeze product iteration cycles for mid-tier manufacturers.
- Lithium-polymer supply concentration:Battery cell production for miniaturized wearables clusters in East Asian contract manufacturers, creating input cost volatility exposure for device OEMs.
- Clinical validation thresholds:FDA 510(k) substantial equivalence demonstrations for novel biosensors require prospective trials that delay revenue recognition by 12-18 months versus consumer wellness classifications.
Strategic Opportunities
- Germany DiGA integration:Digital health applications reimbursement under Germany's statutory health insurance framework creates direct-to-payer distribution channels bypassing traditional hospital procurement.
- Atrial fibrillation screening mandates:Population-scale cardiac monitoring programs in aging Asian and European demographics are generating institutional procurement volumes for ECG-enabled smartwatches.
- AI-interpreted sleep staging:Convergence of accelerometry with machine learning algorithms is opening prescription-grade sleep apnea detection markets previously served by polysomnography laboratories.
Industry Challenges
- Firmware validation complexity:Continuous software updates for Class II medical device wearables require regression testing protocols that strain quality assurance headcount at scaled manufacturers.
- Interoperability fragmentation:Health data exchange standards vary across Epic, Cerner, and regional EHR systems, forcing redundant integration engineering for multi-hospital deployments.
- Biocompatibility certification:Skin-contact sensor materials must satisfy ISO 10993 cytotoxicity testing that extends material qualification timelines for new form factor introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Wearable Healthcare Devices Market |
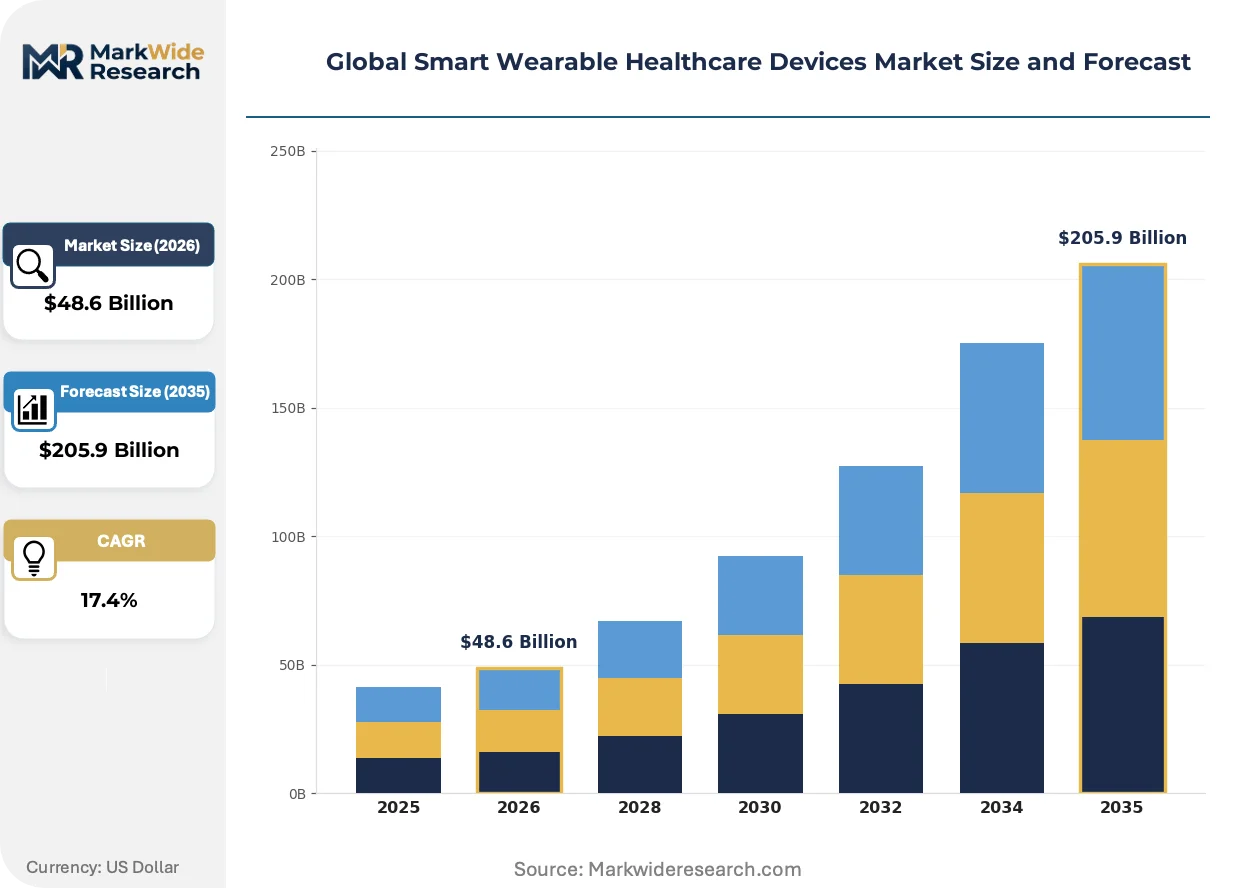
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $205.9 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Trackers, Smartwatches, ECG Monitors, Glucose Monitors, Blood Pressure Monitors Technology: Photoplethysmography, Accelerometer, Electrocardiography, Bioimpedance, Temperature Sensor Application: Remote Patient Monitoring, Chronic Disease Management, Preventive Care, Wellness Tracking, Post-operative Care End User: Home Users, Fitness Enthusiasts, Elderly Care Centers, Telemedicine Providers, Rehabilitation Clinics |
| Companies Covered | Apple Inc., Samsung Electronics, Garmin Ltd., Fitbit, Huawei Technologies Co., Ltd., Xiaomi Corporation, Withings, OMRON Healthcare, Inc., Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Wearable Healthcare Devices Market Shifts & Advancements
Algorithmic interpretation of physiological signals is displacing hardware-centric differentiation as the primary value capture mechanism in wearable healthcare, compressing margins for sensor manufacturers while expanding addressable use cases for platform operators.
Multi-lead electrocardiography is virtualizing the diagnostic function of ambulatory Holter monitors through software-derived vector reconstruction from wrist-worn sensors. Cardiology practices in the United States and Germany are adopting these systems for post-ablation monitoring, replacing 30-day patch-based telemetry with patient-owned devices. This compression of monitoring infrastructure is collapsing the traditional rental-based revenue model for cardiac event recorders.
EMA MDR Article 120 transition deadlines are forcing wearable manufacturers to rebuild technical documentation for legacy products previously certified under the Medical Devices Directive. Firms with dedicated regulatory affairs infrastructure in Ireland and Switzerland are capturing market share as competitors withdraw non-compliant SKUs from European distribution. The regulatory burden is disproportionately affecting single-parameter wellness devices seeking clinical claim upgrades.
Hospital-at-home programs are unbundling device procurement from episodic care reimbursement, creating direct purchasing relationships between health systems and wearable OEMs that bypass traditional durable medical equipment distributors. United States Medicare Advantage plans and United Kingdom NHS trusts are piloting these models for heart failure and COPD cohorts. The channel shift is compressing distributor margins while demanding enhanced logistics capabilities for patient onboarding and technical support from device manufacturers.
Global Smart Wearable Healthcare Devices Market Segmentation
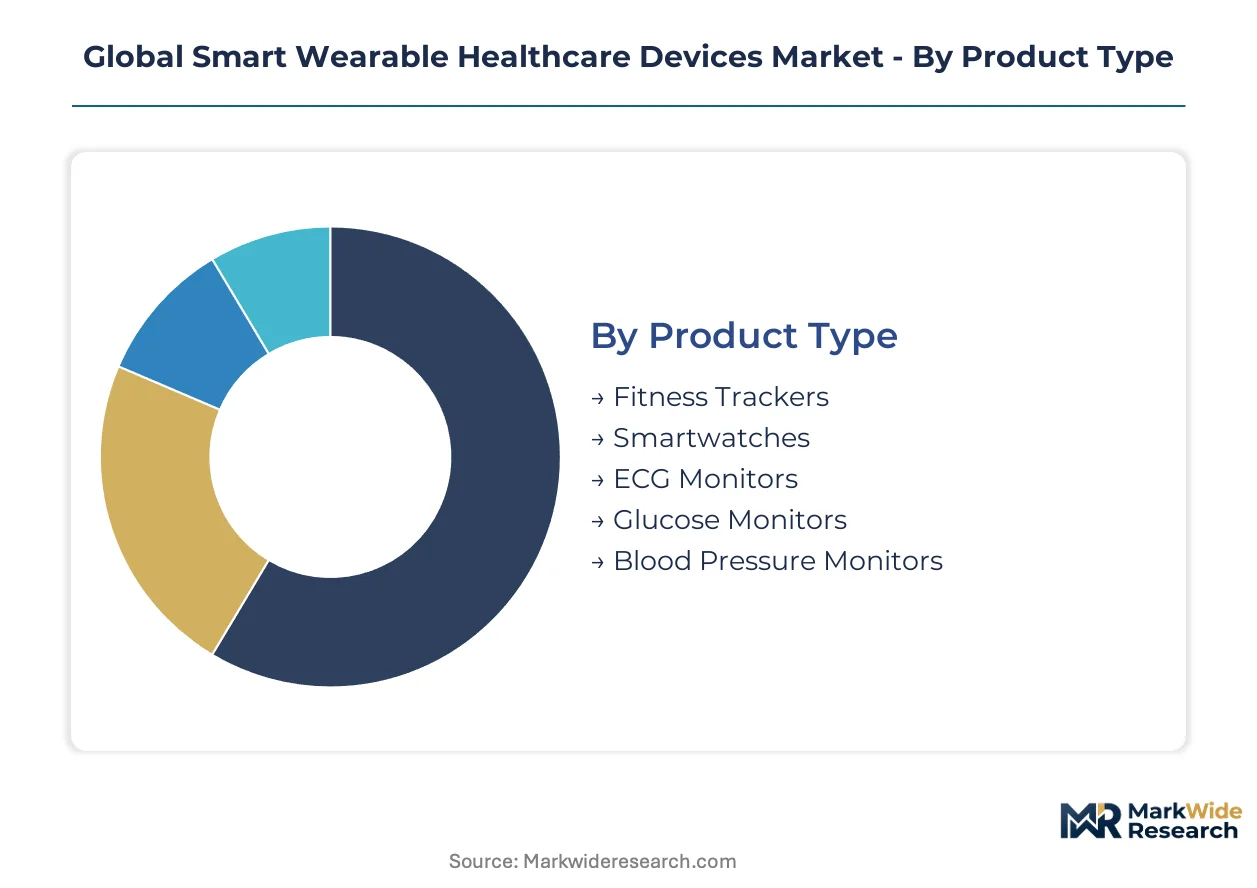
Device taxonomy in wearable healthcare separates hardware form factors from the physiological signals they capture. Each segmentation dimension reveals distinct margin structures, regulatory pathways, and procurement channels that determine commercial viability.
Product Type:
Cost tier stratification separates consumer wellness purchases from reimbursable clinical devices, with hardware complexity and FDA classification status driving pricing architecture.
- Smartwatches:Multi-sensor wrist-worn platforms integrate ECG, photoplethysmography, and accelerometry in sealed enclosures. Demand concentrates in the United States and Germany where Medicare Advantage plans and statutory health insurance frameworks reimburse continuous cardiac monitoring. FDA 510(k) clearances for atrial fibrillation detection have converted these from consumer electronics into clinical decision support tools.
- Glucose Monitors:Continuous interstitial glucose sensors paired with algorithmic insulin dosing controllers enable closed-loop metabolic management. Patient populations are expanding beyond Type 1 diabetics into prediabetic monitoring segments in China and the United States as regulatory pathways compress development timelines.
- Fitness Trackers:Accelerometer-based step and sleep counting devices face margin erosion from commoditized competition.
- ECG Monitors:Chest-patch and wrist-worn single-lead electrocardiography devices serve ambulatory arrhythmia detection.
- Blood Pressure Monitors:Oscillometric and optical tonometry wrist cuffs target hypertension management in home settings.
Smartwatches hold installed capacity. Glucose monitors are rotating up the share rankings.
Technology:
Application-specific sensing modalities determine form factor constraints, power budgets, and algorithmic processing requirements for physiological signal extraction.
- Photoplethysmography:Optical blood volume pulse detection enables heart rate, blood oxygen saturation, and respiratory rate estimation from wrist-worn LEDs. Miniaturization advances in the United States and South Korea are compressing multi-parameter sensors into single modules previously requiring chest patches.
- Electrocardiography:Skin-electrode potential measurement captures cardiac electrical activity for arrhythmia classification. Germany and Japan are adopting these systems for post-ablation monitoring, replacing 30-day patch-based telemetry with patient-owned devices.
- Accelerometer:Motion sensing supports step counting, fall detection, and sleep staging algorithms.
- Bioimpedance:Tissue electrical resistance measurement enables body composition and hydration status estimation.
- Temperature Sensor:Continuous skin or core temperature monitoring supports infection detection and fertility tracking applications.
Photoplethysmography holds installed capacity. Electrocardiography is rotating up the share rankings.
Application:
Customer type determines reimbursement eligibility, with clinical use cases commanding premium pricing against wellness-oriented consumer purchases.
- Remote Patient Monitoring:Continuous physiological data transmission to clinical teams enables hospital-at-home programs and chronic disease surveillance. United States Medicare CPT codes and United Kingdom NHS pilot programs are converting device procurement into reimbursable care delivery.
- Chronic Disease Management:Long-term metabolic, cardiovascular, and respiratory condition tracking requires FDA Class II medical device certification. Germany's DiGA framework creates direct-to-payer distribution channels bypassing traditional hospital procurement.
- Preventive Care:Population-scale screening for atrial fibrillation and sleep apnea targets asymptomatic cohorts.
- Wellness Tracking:Fitness and lifestyle metrics face pricing pressure from unregulated consumer band competition.
- Post-operative Care:Surgical recovery monitoring demands high-frequency vital sign capture and alert escalation protocols.
Remote patient monitoring holds installed capacity. Chronic disease management is rotating up the share rankings.
End User:
Volume concentration varies across direct-to-consumer, institutional procurement, and integrated care delivery models with distinct logistics requirements.
- Home Users:Individual purchasers selecting devices through retail and direct-to-consumer channels drive volume in wellness-oriented segments. The United States and China represent the largest addressable populations for self-directed health monitoring.
- Telemedicine Providers:Virtual care platforms bundle device provisioning with subscription-based clinical oversight. These entities in the United States and Germany are establishing direct purchasing relationships with OEMs that bypass durable medical equipment distributors.
- Fitness Enthusiasts:Athletic performance optimization drives demand for ruggedized outdoor health metrics.
- Elderly Care Centers:Institutional fall detection and medication adherence monitoring require enterprise-grade fleet management.
- Rehabilitation Clinics:Post-acute recovery programs utilize motion sensing and remote therapeutic monitoring for orthopedic and cardiac rehabilitation.
Home users hold installed capacity. Telemedicine providers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States channels demand through Medicare reimbursement pathways, Germany integrates devices into statutory insurance frameworks, and China pursues domestic manufacturing substitution alongside hospital-at-home pilots.
United States
Medicare Advantage plans and new CPT codes for continuous cardiac monitoring convert wellness purchases into reimbursable clinical expenditures. FDA 510(k) clearances for atrial fibrillation detection accelerate smartwatch adoption in post-ablation care. Boston and San Francisco anchor digital health innovation clusters where telemedicine platforms establish direct OEM purchasing relationships.
Germany
Statutory health insurance reimbursement under the DiGA framework creates direct-to-payer distribution channels bypassing hospital procurement. EMA MDR compliance requirements favor manufacturers with dedicated regulatory affairs infrastructure in Ireland and Switzerland. Munich and Berlin concentrate health technology startups integrating wearable data into electronic health record systems.
China
NMPA registration pathways for Class II medical device wearables compress development timelines for domestic biosensor manufacturers. Closed-loop insulin delivery systems gain regulatory traction for prediabetic monitoring segments. Shenzhen and Shanghai anchor hardware production clusters where optical sensor miniaturization advances reduce form factor constraints.
Japan
PMDA approvals for multi-lead electrocardiography wearables enable post-ablation monitoring programs replacing traditional Holter monitors. METI initiatives support aging demographic surveillance through population-scale cardiac screening. Tokyo and Osaka concentrate precision manufacturing capabilities for biocompatible skin-contact sensor materials.
United Kingdom
NHS pilot programs for hospital-at-home heart failure and COPD cohorts generate institutional procurement volumes for remote patient monitoring devices. MHRA post-Brexit regulatory divergence creates parallel certification requirements for EU-exporting manufacturers. London and Cambridge anchor digital health research clusters where AI-interpreted sleep staging algorithms advance.
Global Smart Wearable Healthcare Devices Market Competitive Landscape
Capability concentration sits with specialized biosensor developers; scale advantage sits with consumer electronics platforms with installed device ecosystems. The vendor base stratifies across three tiers: integrated platform operators controlling hardware-software-data stacks, component specialists supplying optical and electrode modules, and telemedicine intermediaries bundling devices with clinical oversight. Dominant competitive moves include strategic partnerships with health systems for direct procurement relationships and algorithmic differentiation through FDA-cleared Software as a Medical Device pathways.
Within the integrated platform tier, Apple Inc. and Samsung Electronics occupy positions anchoring recurring service revenue through health data ecosystems. Garmin Ltd. exemplifies specialization in ruggedized outdoor health metrics that differentiate from lifestyle-oriented competitors. These three entities represent contrasting archetypes: closed ecosystem control, open-architecture partnership models, and vertical application focus.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Garmin Ltd. |
| Fitbit |
| Huawei Technologies Co., Ltd. |
| Xiaomi Corporation |
| Withings |
| OMRON Healthcare, Inc. |
| Medtronic |
| Others |
Supply & Pricing Matrix
The Shenzhen-Hong Kong logistics corridor carries optical sensor modules and lithium-polymer cells from contract manufacturers to assembly facilities in Germany and the United States, with freight cost volatility compressing margins for mid-tier device OEMs while concentrating pricing power among integrated platform operators with captive supply arrangements.
Pricing Analysis
Long-term offtake agreements between hospital systems and wearable OEMs now dominate procurement for remote patient monitoring applications, replacing spot-market device purchases. Three-tier pricing structure across FDA-cleared clinical, CE-marked wellness, and unregulated fitness bands separates reimbursable expenditures from consumer discretionary spending. Cost compression in the fitness tracker tier is intensifying because of commoditized accelerometer competition from Chinese manufacturers. Telemedicine providers exhibit the lowest price sensitivity due to bundled reimbursement, while direct-to-consumer home users drive volume through promotional discounting.
Supply Chain Analysis
Contract manufacturing capacity for miniaturized biosensors concentrates in Foxconn, Luxshare, and Goertek facilities across Shenzhen, Dongguan, and Kunshan. Optical PPG modules and ECG electrode arrays draw from South Korean LED foundries and Japanese conductive polymer suppliers. Single-source vulnerability in lithium-polymer cell production creates input cost volatility exposure. Distribution runs through durable medical equipment distributors for hospital procurement, while telemedicine platforms and direct-to-consumer channels bypass traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as closed-loop insulin delivery systems and Medicare reimbursement codes convert wellness devices into clinical infrastructure, with penetration tailwinds from aging demographics in the United States, Germany, and Japan.
For Market Incumbents: Harden regulatory moats through accelerated FDA 510(k) submissions for Software as a Medical Device pathways before algorithmic differentiation becomes portable across hardware platforms. Deepen backward integration into optical sensor module production to defend margin position against contract manufacturer cost pass-throughs. Prioritize dedicated regulatory affairs infrastructure in Ireland and Switzerland to capture share as EMA MDR recertification freezes competitor product cycles.
For New Entrants and Emerging Players: Pursue white-space opportunities in AI-interpreted sleep staging for prescription-grade sleep apnea detection, where polysomnography laboratory displacement creates new reimbursement categories. Target Germany's DiGA framework for statutory health insurance reimbursement, bypassing hospital procurement bottlenecks that entrench incumbents. Lead with direct-to-payer distribution partnerships rather than distributor-dependent models.
For Investors and Strategic Acquirers: Specialized biosensor developers with FDA-cleared multi-lead ECG algorithms and dedicated regulatory affairs teams represent the highest-conviction acquisition archetype for platform operators seeking clinical credibility. Long-term viability hinges on conversion from hardware transactional revenue to recurring data service streams. Watch for inflection signals in Medicare Advantage plan device procurement volumes and CPT code expansion for continuous cardiac monitoring.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Compresses time-to-market for atrial fibrillation detection algorithms against wellness-classified competitors. |
| Hospital System Partnership | Enables direct procurement relationships for hospital-at-home programs bypassing durable medical equipment distributors. |
| Software Companion Development | Creates recurring service revenue streams through algorithmic interpretation of photoplethysmography-derived vital signs. |
| Reimbursement Strategy | Secures CPT code coverage for continuous cardiac monitoring in Medicare Advantage plans. |
| CE Marking Pathway | Opens statutory health insurance channels under Germany's DiGA framework for digital health applications. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads provided ongoing calibration across quarterly update cycles. Primary interviews with telemedicine platform operators and wearable OEM supply chain directors combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up device shipment estimates and top-down healthcare expenditure allocation triangulated to segment-level outputs.
Scenario-bracketing around reimbursement policy evolution and regulatory pathway compression shaped volume projections across the analysis window. Segmentation modeling incorporated device form factor, sensing modality, application use case, and end-user procurement channel dimensions. CAGRs derived from fitted adoption curves calibrated to historical analogs in continuous glucose monitoring penetration. Forecast inputs included Medicare CPT code expansion timelines and NMPA registration pathway efficiency for domestic Chinese manufacturers.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy, lithium-polymer commodity pricing, or FDA review queue backlogs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory clearance efficiency and payer adoption velocity. Quarterly review of Medicare Advantage plan device procurement volumes and EMA MDR recertification completion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
Global Laparoscopy Devices Market
Medical Devices
Digital Slit Lamp Market
Medical Devices
India Diabetes Devices Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
China Artificial Organs and Bionic Implants Market
Medical Devices
High Intensity Focused Ultrasound (HIFU) Market
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Global Veress Needle Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Digital Intraoral Camera Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market