
 Non- Resorbable Cranial Fixation System Market | 2026-2036
Non- Resorbable Cranial Fixation System Market Size, Share, and Industry Trends Forecast 2026-2036
Non- Resorbable Cranial Fixation System Market Analytics
The EU Medical Device Regulation is repositioning competitive priorities for permanent cranial implants by mandating enhanced clinical evidence and post-market surveillance. Stryker Corporation leverages its broad neurosurgical portfolio to sustain institutional contracts across European and North American hospital networks. DePuy Synthes anchors its position through deep orthopedic-surgical integration, while Medtronic plc competes via advanced navigation-compatible fixation platforms that align with precision surgery workflows.
Non-resorbable cranial fixation systems comprise permanent implants manufactured from titanium alloys, stainless steel, or polymer composites, designed to stabilize skull defects through mechanical fixation exceeding twelve months post-implantation. These devices typically achieve tensile strengths above 800 MPa and integrate with native bone via osseointegration without biodegradation, serving primarily to restore cranial vault integrity after trauma, tumor resection, or congenital defect correction. Titanium skull plates dominate current revenue contribution due to established biocompatibility profiles and radiolucent imaging compatibility, while carbon fiber mesh represents the fastest-expanding material category driven by pediatric and radiation-therapy applications where artifact reduction matters. Neurosurgery and trauma surgery applications together concentrate the majority of procedural demand, with craniofacial reconstruction emerging as a higher-margin subspecialty channel.
The FDA enforces Class II medical device controls requiring 510(k) substantial equivalence for non-resorbable cranial implants, while the EU MDR mandates notified body certification with enhanced clinical evaluation reports. Japan's PMDA maintains distinct pharmaceutical and medical device agency oversight with country-specific biocompatibility testing protocols that extend market access timelines. Stakeholders must monitor evolving regulatory convergence between FDA breakthrough device pathways and EU MDR Article 54 clinical investigation requirements to anticipate approval cost structures and competitive entry barriers.
Market Dynamics
The EU Medical Device Regulation is compressing competitive timelines by demanding enhanced clinical evidence packages for permanent cranial implants, forcing manufacturers to restructure post-market surveillance systems and notified body engagement strategies ahead of certification deadlines.
Growth Catalysts
- Titanium osseointegration protocols:Established biocompatibility profiles in neurosurgery departments are accelerating hardware standardization across tertiary hospital networks in the United States, Germany, and Japan.
- EU MDR Article 54 clinical investigation requirements:Regulatory convergence with FDA breakthrough device pathways is streamlining dual-market approval strategies for fixation platform developers.
- Cranial trauma procedural volumes:Elevated injury incidence in high-reimbursement markets is concentrating demand for mechanical fixation systems exceeding twelve-month implantation durability.
Market Restraints
- Titanium alloy input cost volatility:Aerospace and defense sector competition for Grade 5 titanium sponge is pressuring raw material procurement budgets for implant manufacturers.
- Notified body capacity constraints:EU MDR transition bottlenecks are extending certification timelines for permanent implantables beyond historical twelve-month benchmarks.
- Resorbable polymer substitution threat:Poly-L-lactic acid and polyglycolic acid fixation systems are capturing pediatric and short-term stabilization cases where mechanical permanence is not clinically required.
Strategic Opportunities
- Pediatric radiation-therapy applications:Carbon fiber mesh systems are penetrating oncology centers where CT/MRI artifact reduction enables precise treatment planning for cranial tumor patients.
- Navigation-compatible platform integration:Convergence of robotic surgical systems with patient-specific implant design software is opening precision surgery workflow contracts in academic medical centers.
- Japan PMDA biocompatibility harmonization:Streamlined testing protocol recognition between Japanese and ISO standards is reducing duplicate validation costs for market entrants.
Industry Challenges
- Computational design talent scarcity:Patient-specific implant engineering requires rare combinations of biomedical modeling expertise and regulatory documentation proficiency that outpaces workforce development.
- Legacy ERP integration friction:Post-market surveillance data capture systems must interface with hospital quality management databases that lack standardized interoperability protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non- Resorbable Cranial Fixation System Market |
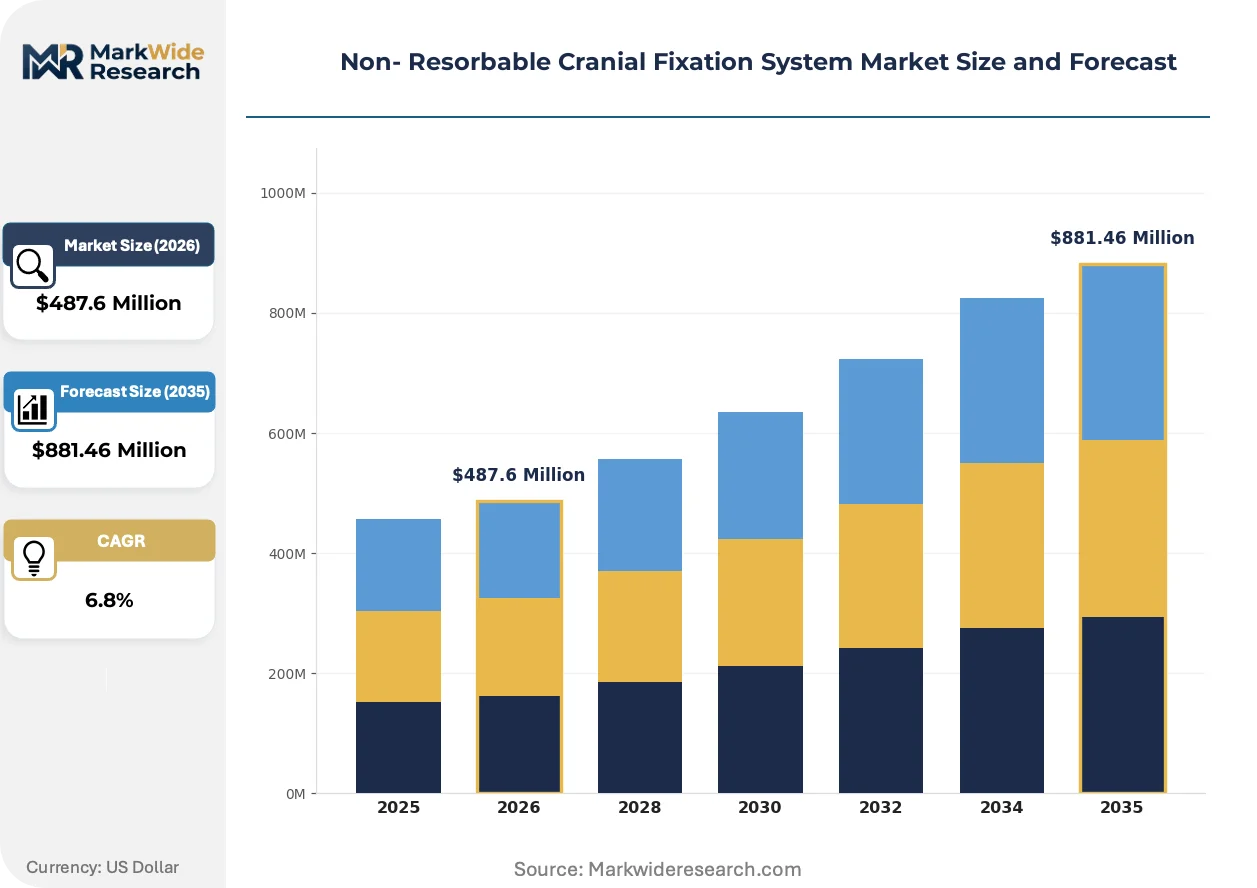
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skull Plates, Screws, Mesh, Clamps Material: Titanium, Stainless Steel, Polypropylene, Carbon Fiber End User: Hospitals, Clinics, Surgical Centers, Academic Institutions Application: Trauma Surgery, Neurosurgery, Craniofacial Surgery, Orthopedic Surgery |
| Companies Covered | Stryker Corporation, DePuy Synthes, Medtronic plc, Integra LifeSciences Corporation, B. Braun Melsungen AG, Zimmer Biomet Holdings, KLS Martin Group, OsteoMed, Medartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non- Resorbable Cranial Fixation System Market Evolving Landscape
Digital manufacturing workflows are compressing production cycles for patient-specific cranial plates while regulatory data requirements are expanding for permanent implant traceability. These forces are reshaping how fixation system developers allocate R&D resources and structure clinical evidence generation.
Additive manufacturing of titanium lattice structures is unifying structural performance with porosity gradients that accelerate osseointegration. Academic neurosurgery departments in the United States and Germany are adopting electron-beam melted implants for complex craniofacial reconstructions. This technology is unifying mechanical fixation with biological integration timelines previously requiring secondary revision procedures.
EU MDR technical documentation requirements are mandating lifetime implant traceability through unique device identification systems. Manufacturers must now maintain post-market clinical follow-up registries that extend fifteen years beyond commercialization. Small-cap specialists without existing quality management infrastructure face disproportionate compliance cost burdens relative to diversified orthopedic portfolios.
Hospital value analysis committees are consolidating supplier contracts around full-procedure bundles rather than discrete implant pricing. Integrated delivery networks in the United States are negotiating multi-year fixation system agreements that include navigation platform compatibility guarantees. This concentration is most visible in Level I trauma centers where procedural volume thresholds justify dedicated neurosurgical instrument standardization.
Non- Resorbable Cranial Fixation System Market Segmentation
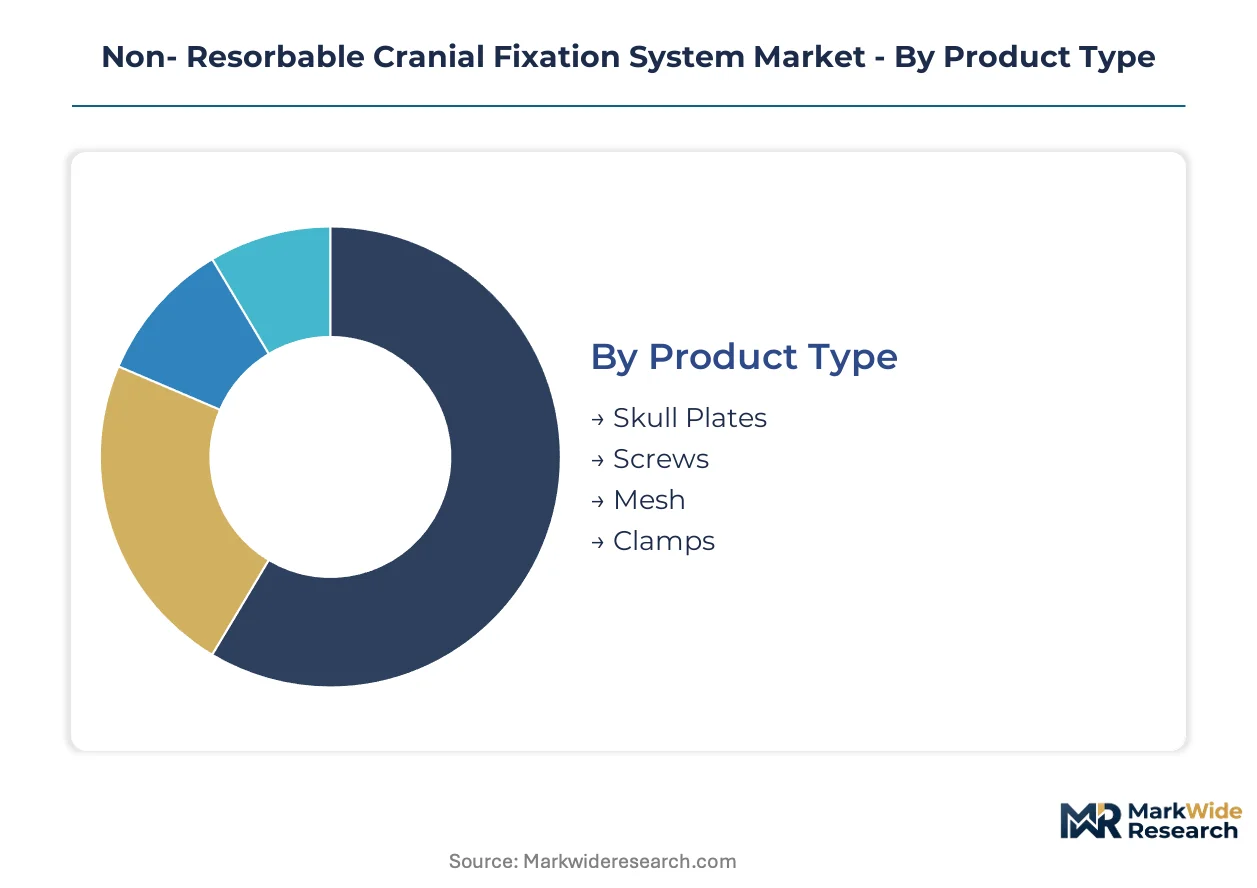
Segmentation in cranial fixation reveals how procurement priorities diverge across surgical settings. Material selection drives reimbursement pathways, while end-user scale determines service contract structures and inventory management systems.
Product Type:
Surgeons select hardware based on defect geometry and load-bearing requirements rather than cost alone.
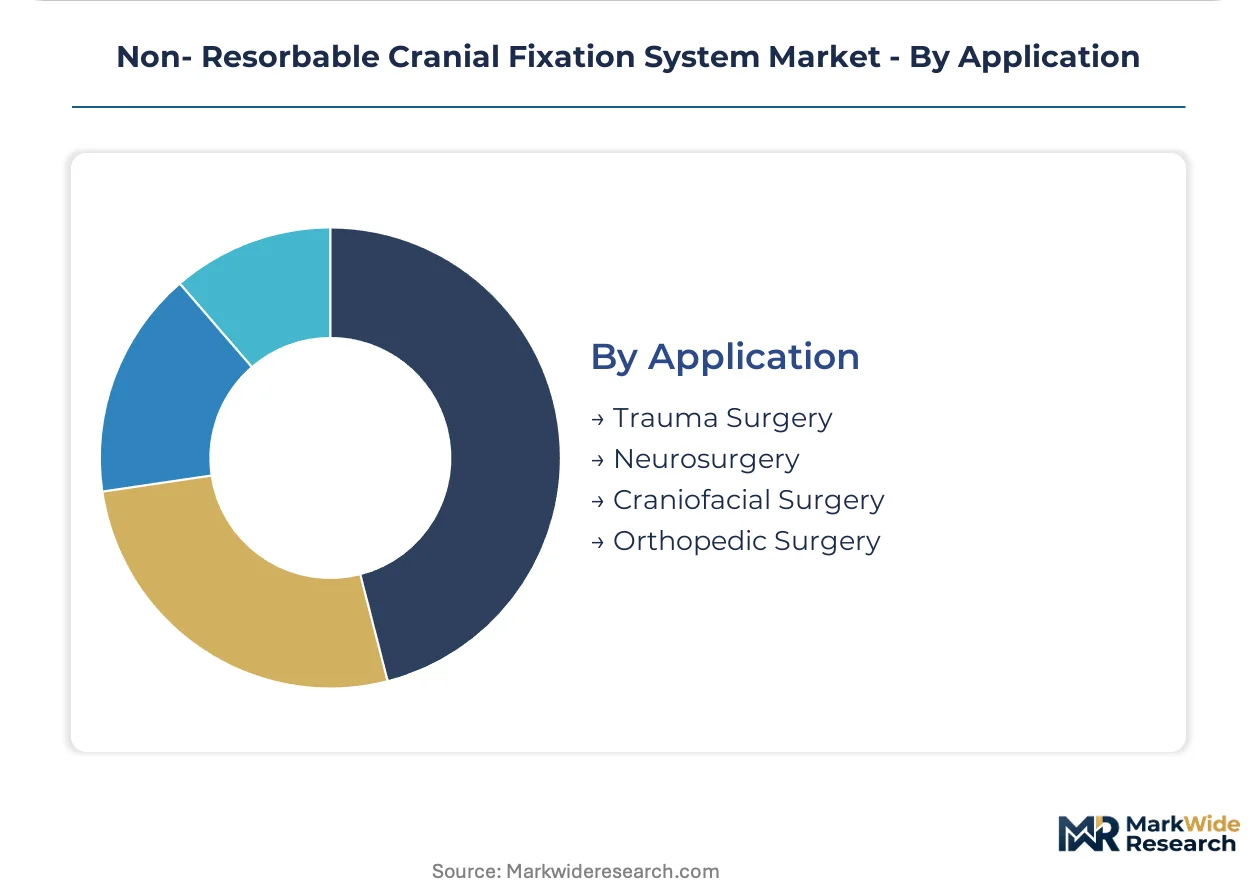
- Skull Plates:Large-format titanium constructs restore vault integrity after craniotomy or trauma. United States Level I trauma centers standardize on pre-contoured plate systems to reduce intraoperative bending time. Demand concentrates where neurosurgical volume justifies dedicated plating inventories.
- Screws:Self-tapping titanium fixation screws achieve cortical purchase at depths of 4-8mm. German university hospitals prioritize variable-angle screw designs compatible with navigation platforms. Procurement runs through bundled instrument tray agreements rather than discrete component orders.
- Mesh:Flexible titanium or polymer meshes conform to complex cranial curvatures. Pediatric oncology centers in Japan favor carbon fiber variants for radiation therapy compatibility.
- Clamps:Rigid fixation clamps secure bone flaps during cranioplasty procedures. Academic medical centers specify quick-release mechanisms for emergency decompression scenarios.
Skull plates lead volumes today; mesh configurations are gaining share fastest in specialized reconstructive applications.
Material:
Biocompatibility certification costs and imaging artifact profiles segment the supplier base into premium and standard tiers.
- Titanium:Grade 5 titanium alloys dominate permanent implantation due to established osseointegration protocols. United States neurosurgery departments specify electron-beam melted lattice structures for complex craniofacial reconstructions. FDA 510(k) substantial equivalence pathways reinforce incumbent supplier positions.
- Stainless Steel:316L surgical stainless steel serves cost-sensitive trauma applications where implant permanence exceeds twelve months but titanium cost premiums are unsustainable. Indian tertiary hospitals balance material expenditure against revision surgery risk.
- Polypropylene:Radiolucent polymer plates enable post-operative MRI surveillance without metallic artifact. German oncology centers specify polypropylene for tumor resection cases requiring serial imaging.
- Carbon Fiber:Composite structures eliminate CT/MRI artifacts entirely for radiation therapy planning. Japanese pediatric neurosurgery programs adopt carbon fiber mesh where proton beam targeting precision matters.
Titanium anchors current revenue; carbon fiber composites are expanding most quickly in radiation-oncology integrated practices.
End User:
Capital equipment integration and case volume thresholds determine contract negotiation leverage across buyer categories.
- Hospitals:Tertiary care institutions with dedicated neurosurgical suites command multi-year fixation system agreements. United States integrated delivery networks bundle implant procurement with navigation platform service contracts.
- Clinics:Outpatient surgical clinics concentrate on minor craniofacial procedures with shorter implantation timelines. German private clinics prioritize screw-based fixation over plate systems for cost containment.
- Surgical Centers:Ambulatory surgery centers select disposable instrument kits over reusable tray systems. Japanese day-surgery facilities favor simplified screw fixation protocols.
- Academic Institutions:University hospitals drive adoption of patient-specific additive manufactured implants. Research partnerships with fixation system developers secure early access to navigation-compatible platforms.
Hospitals capture the largest procurement volumes; academic institutions are pulling innovation adoption forward fastest.
Application:
Reimbursement coding and procedural complexity create distinct margin profiles across surgical specialties.
- Trauma Surgery:Emergency cranioplasty procedures require rapid hardware availability without patient-specific pre-planning. United States trauma centers maintain 24/7 implant inventories with standardized plate sizes.
- Neurosurgery:Elective tumor resections and vascular procedures enable pre-operative planning with custom-contoured fixation. German neurosurgical departments integrate fixation selection into navigation workflow protocols.
- Craniofacial Surgery:Reconstructive procedures demand aesthetic contouring alongside mechanical stability. Japanese maxillofacial surgeons specify low-profile titanium systems for pediatric craniosynostosis correction.
- Orthopedic Surgery:Skull base and orbital reconstructions cross over from neurosurgical to orthopedic caseloads. Academic centers with combined service lines standardize hardware across specialties.
Trauma surgery generates the highest procedural volumes; craniofacial applications are climbing the fastest as reconstructive technique sophistication advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Non-resorbable cranial fixation technology originated in German university hospitals during the 1980s, where titanium plating protocols for trauma reconstruction were first standardized. This heritage established Central Europe as the foundational market for permanent implant development. Today procedural demand concentrates in three high-reimbursement clusters where neurosurgical infrastructure and regulatory frameworks align.
United States
Level I trauma centers in Texas, California, and the Northeast Corridor drive titanium plate procurement volumes through 24/7 emergency cranioplasty protocols. FDA Class II 510(k) pathways reinforce established supplier positions while slowing novel material entrants. The Greater Boston academic cluster anchors patient-specific additive manufacturing adoption for complex craniofacial reconstructions.
Germany
University hospitals in Bavaria and North Rhine-Westphalia integrate navigation-compatible fixation systems into precision neurosurgical workflows. EU MDR notified body certification through TÜV SÜD or DEKRA extends timelines but preserves quality premiums for compliant manufacturers. The Stuttgart-Tübingen medical technology corridor hosts specialized machining suppliers for titanium lattice structures.
Japan
PMDA biocompatibility testing protocols extend market access timelines to eighteen months for foreign manufacturers. Tokyo and Osaka academic medical centers prioritize carbon fiber mesh systems for pediatric proton beam therapy cases. Kansai region hospitals negotiate bundled instrument tray agreements that consolidate supplier relationships.
United Kingdom
NHS England specialized commissioning frameworks concentrate cranial fixation procurement through designated neurosurgical centers in London, Manchester, and Birmingham. MHRA convergence with EU MDR technical documentation requirements streamlines dual-market submissions for domestic manufacturers. The Oxford-Cambridge innovation arc supports early-stage patient-specific implant design ventures.
Switzerland
Swissmedic maintains distinct pharmaceutical-medical device oversight with accelerated access pathways for breakthrough fixation technologies. Basel and Zurich university hospitals standardize hardware across neurosurgical and maxillofacial service lines. The country's precision manufacturing heritage supports captive titanium processing capabilities for domestic implant producers.
Non- Resorbable Cranial Fixation System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the non-resorbable cranial fixation landscape. Vertically integrated orthopedic conglomerates with captive titanium forging capacity face specialized neurosurgical instrument developers who outsource substrate fabrication. The market structure separates into three strategic archetypes: diversified orthopedic portfolios with neurosurgical divisions, pure-play cranial fixation specialists, and academic spin-outs commercializing patient-specific additive manufacturing. Dominant competitive moves include navigation platform compatibility guarantees and multi-year integrated delivery network contracts.
Among diversified orthopedic portfolios, Stryker Corporation and DePuy Synthes occupy positions representing institutional contract consolidation across United States and European hospital networks. Medtronic plc exemplifies the navigation-integrated archetype, anchoring precision surgery workflow penetration in academic medical centers. These three entities represent contrasting strategic postures: Stryker leverages broad neurosurgical instrumentation breadth, DePuy Synthes exploits orthopedic-surgical service line integration, and Medtronic aligns fixation hardware with surgical navigation ecosystems.
| Leading Market Players |
|---|
| Stryker Corporation |
| DePuy Synthes |
| Medtronic plc |
| Integra LifeSciences Corporation |
| B. Braun Melsungen AG |
| Zimmer Biomet Holdings |
| KLS Martin Group |
| OsteoMed |
| Medartis AG |
| Others |
Value Network & Pricing Analysis
Biomedical modeling talent concentration in the Stuttgart-Tübingen corridor creates labor-cost differentials that widen pricing spreads between patient-specific additive manufactured plates and standard titanium hardware. German engineering premiums feed into premium-tier positioning, while cost-sensitive trauma centers in India and Southeast Asia source 316L stainless steel alternatives that compress margin structures at the economy tier.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the non-resorbable cranial fixation market by certification grade and customization depth. FDA 510(k) substantial equivalence pathways and EU MDR notified body certification separate premium titanium lattice structures from standard pre-contoured plates, while uncertified stainless steel hardware serves price-sensitive trauma applications. Pricing pressure stems from aerospace sector competition for Grade 5 titanium sponge, which compresses procurement budgets for implant manufacturers. Academic medical centers exhibit lowest price sensitivity due to bundled navigation platform contracts, whereas ambulatory surgery centers in Japan and Germany drive hardest bargain on discrete screw and clamp procurement.
Supply Chain Analysis
Dual-sourcing requirements mandated by United States integrated delivery networks and German university hospital procurement committees force manufacturers to qualify secondary titanium forging suppliers in Switzerland and Japan. Raw material supply draws from Grade 5 titanium sponge producers in Russia, Kazakhstan, and China, with electron-beam melting powder production concentrated in Germany and the United States. Single-source vulnerability in aerospace-qualified titanium sponge creates exposure to export restriction shocks. Distribution runs through orthopedic implant distributors with captive neurosurgical instrument inventories, though direct-to-hospital contracts are consolidating around full-procedure bundles in Level I trauma centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-resorbable cranial fixation market functions as a stable compounder anchored by irreplaceable trauma surgery demand and permanent implant durability requirements that resist substitution. Neurosurgical procedure volumes in aging populations generate predictable replacement and revision cycles.
For Market Incumbents: Deepen backward integration into electron-beam melting powder production to secure titanium supply chains against aerospace sector competition. Expand notified body certification capacity ahead of EU MDR Article 54 deadlines to capture competitors stranded in regulatory bottlenecks. Carbon fiber mesh specialists represent an emerging entrant threat in pediatric radiation-oncology segments. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer the most viable white-space entry route for specialized carbon fiber mesh and patient-specific additive manufactured implants. Target Japanese pediatric neurosurgery programs where PMDA biocompatibility harmonization reduces duplicate validation costs. Lead with radiation-therapy compatibility guarantees to differentiate against incumbent titanium portfolios. For Investors and Strategic Acquirers: Diversified orthopedic conglomerates with neurosurgical divisions are the most active acquirer in this space, seeking navigation-compatible fixation platforms to complete precision surgery ecosystems. Five-to-ten year viability rests on regulatory data infrastructure and post-market surveillance registry capabilities. Watch EU MDR notified body capacity expansion as the signal for competitive entry timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Article 54 clinical investigation requirements compress competitive timelines for permanent implant developers. |
| Navigation Platform Integration | Stryker and Medtronic anchor precision surgery workflows through robotic system compatibility guarantees. |
| Patient-Specific Additive Manufacturing | Electron-beam melted titanium lattice structures accelerate osseointegration in German academic centers. |
| Carbon Fiber Mesh Development | Pediatric oncology adoption in Japan eliminates CT/MRI artifacts for proton beam therapy planning. |
| Integrated Delivery Network Contracts | United States hospital systems consolidate procurement through multi-year fixation system agreements. |
Research Methodology
Direct dialogue with neurosurgical department heads, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers grounded qualitative insights across the United States, Germany, and Japan. Secondary validation drew from FDA 510(k) substantial equivalence filings, EU MDR notified body certification databases, PMDA biocompatibility testing protocols, hospital procurement registries, and CMS Medicare reimbursement schedules. Bottom-up and top-down triangulation reconciled procedure volume estimates with implant shipment data from orthopedic distributor disclosures.
Bottom-up modeling anchored volume projections to Level I trauma center cranioplasty frequencies, neurosurgical tumor resection caseloads, and craniofacial reconstruction trends across the projection horizon. Segmentation dimensions included material grade, product type, end-user scale, and application specialty. CAGRs were derived from regression analysis against historical titanium implant adoption curves and procedural volume elasticity to reimbursement rate changes. Forecast inputs incorporated EU MDR transition timelines and PMDA harmonization progress.
Raw material cost volatility, notified body capacity constraints, and resorbable polymer substitution velocity are the dominant revision risks to the outlook. Deviation in aerospace sector titanium sponge demand would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Canada Minimally Invasive Surgery Devices Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
Home-Use Water Flosser Market
Medical Devices
Global Artificial Limbs Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Direct Energy Medical Devices Market
Medical Devices
Bunion Correction Systems Market
Medical Devices
Global 3D Printed Surgical Models Market