
 Tear Duct Plugs Market | 2026-2036
Tear Duct Plugs Market Size, Share, and Industry Trends Forecast 2026-2036
Tear Duct Plugs Market Analytics
North American manufacturing capacity for ophthalmic micro-implants is fragmenting as domestic producers respond to supply chain regionalization pressures. Ocular Therapeutix leverages its hydrogel platform expertise to sustain differentiated positioning in resorbable plug formats. Corza Medical anchors its competitive stance through specialized surgical instrumentation bundled with punctal occlusion devices. Lacrimedics competes on practitioner familiarity, occupying a defensible niche in collagen-based temporary plugs favored by anterior segment specialists.
Tear duct plugs are biocompatible micro-implants inserted into the punctal or canalicular openings to modulate tear drainage, typically measuring 0.3–0.7 mm in diameter and fabricated from silicone, collagen, or synthetic polymers through precision molding or extrusion processes. Their primary commercial purpose is to conserve the tear film in evaporative or aqueous-deficient dry eye conditions, postsurgical recovery, or ocular surface disorders. Silicone-based permanent plugs command the dominant share of procedural volume due to long dwell times and reversibility, while collagen segments represent the fastest-expanding category as temporary occlusion gains traction in perioperative protocols and allergy management. Hospital-based applications retain margin concentration through bundled reimbursement, though ophthalmology clinics are capturing incremental volume as point-of-care insertion simplifies patient throughput.
FDA 510(k) clearance requirements govern market access for permanent punctal plugs in the United States, while the EU Medical Device Regulation imposes enhanced biocompatibility and clinical evidence standards for CE-marked products sold across European member states. ISO 10993 biological evaluation protocols further shape material selection and cytotoxicity testing burdens for manufacturers targeting multiple jurisdictions. Stakeholders must monitor evolving reimbursement thresholds for dry eye procedures and the trajectory of resorbable material innovations that could displace permanent implant paradigms.
Market Dynamics
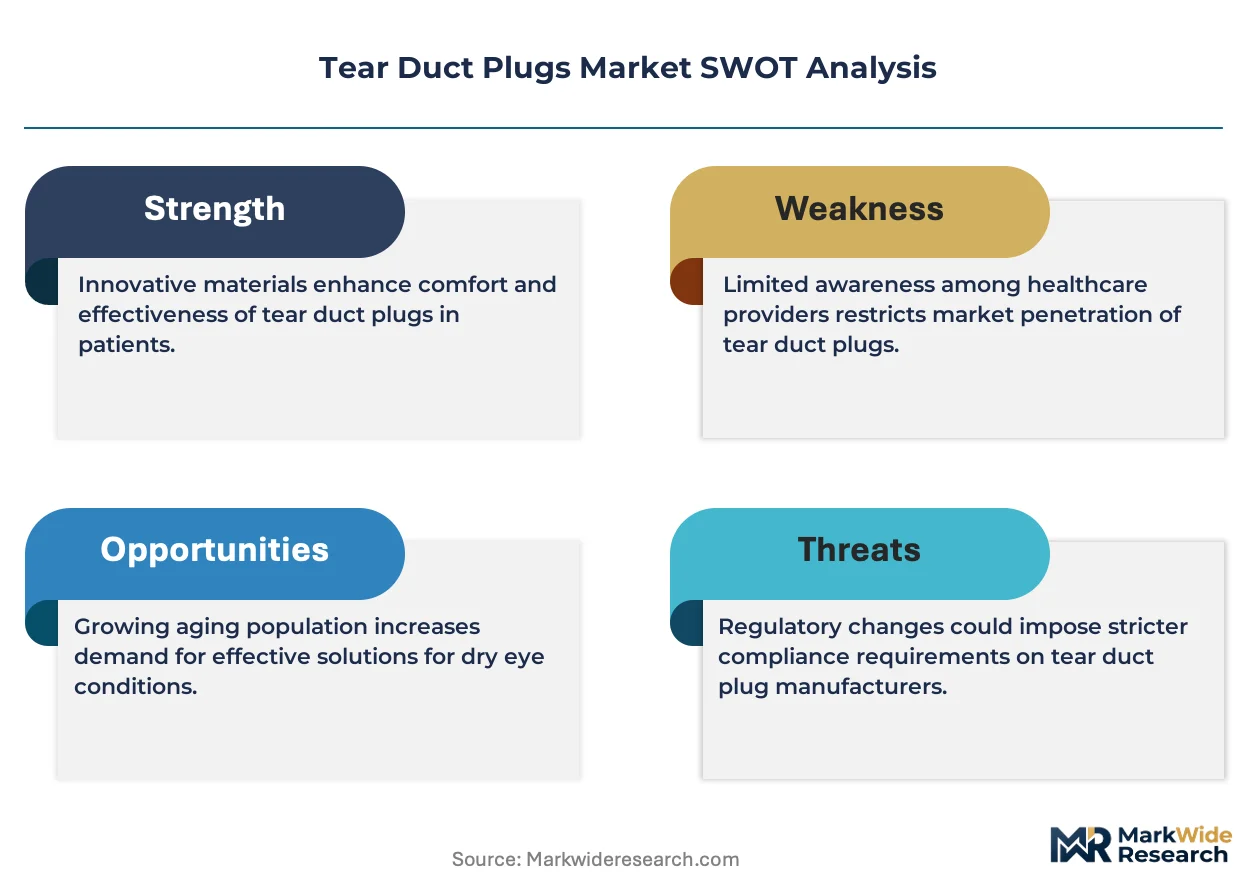
The tear duct plugs market pivots on the tension between permanent silicone implants and resorbable alternatives, as reimbursement protocols increasingly favor temporary occlusion in perioperative settings. FDA 510(k) clearance timelines and EU MDR biocompatibility requirements are compressing product development cycles while elevating capital barriers for new entrants.
Growth Catalysts
- EU MDR clinical evidence standards:Enhanced biocompatibility documentation requirements are accelerating consolidation among manufacturers with established ISO 10993 testing infrastructure, privileging incumbents over speculative entrants.
- Ophthalmology clinic expansion:Ambulatory surgical centers in the United States are building dedicated ocular service lines, creating point-of-care insertion capacity that bypasses hospital outpatient departments.
- Collagen resorption kinetics:Advances in controlled biodegradation timelines enable temporary plugs calibrated to specific healing windows, expanding applications in postsurgical recovery and allergy management protocols.
Market Restraints
- Silicone raw material concentration:Medical-grade silicone supply chains concentrate among a limited set of European and Asian chemical processors, exposing manufacturers to input volatility and qualification delays.
- FDA Class II device friction:Substantial equivalence determinations for novel plug geometries require predicate device alignment that constrains design innovation and extends regulatory timelines.
- Pharmacologic substitution:Prescription eye drops and emerging neurostimulation therapies for dry eye represent non-surgical alternatives that capture mild-to-moderate cases before procedural intervention.
Strategic Opportunities
- German corneal center density:Specialized dry eye protocols with reimbursed punctal occlusion procedures create procedural volume concentration unmatched elsewhere in Europe.
- Teleophthalmology integration:Remote diagnostic platforms are enabling pre-screening for punctal occlusion candidacy, expanding addressable patient pools beyond traditional clinic catchment areas.
- Bioresorbable polymer convergence:Cross-pollination from drug-eluting stent and suture technologies is accelerating material science advances in controlled degradation profiles.
Industry Challenges
- Micro-molding precision requirements:Dimensional tolerances of 0.3–0.7 mm demand specialized injection molding expertise and cleanroom infrastructure that constrains manufacturing scale-up.
- Multi-jurisdiction certification complexity:Simultaneous pursuit of FDA 510(k), CE marking under MDR, and Japan PMDA approval creates parallel track resource drains and timeline misalignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tear Duct Plugs Market |
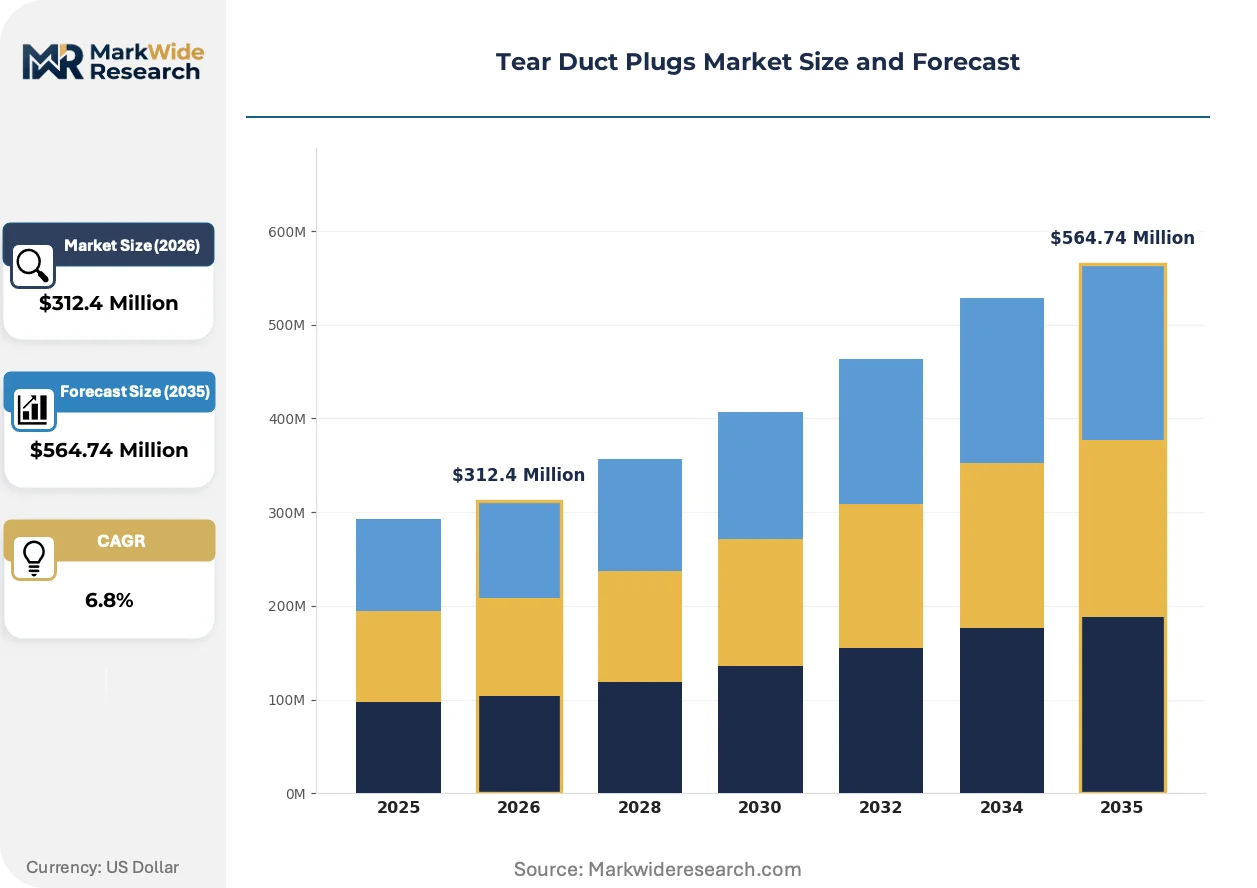
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Collagen, Gel, Acrylate Application: Dry Eye Treatment, Surgical Procedure, Allergy Management, Cosmetic Use End User: Ophthalmology Clinics, Hospitals, Home Care, Research Laboratories Delivery Mode: Topical, Injectable, Intraocular, Others |
| Companies Covered | Ocular Therapeutix, Corza Medical, OASIS Medical, Lacrimedics, Beaver-Visitec International, FCI Ophthalmics, Bausch & Lomb, Alcon, Innovia Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tear Duct Plugs Market Evolving Landscape
Material science advances are dissolving the boundary between permanent and temporary occlusion paradigms, while regulatory frameworks on both sides of the Atlantic recalibrate evidence requirements. These forces are compressing product lifecycles and reshaping competitive positioning around biocompatibility credentials rather than device geometry alone.
Resorbable synthetic polymers are hybridizing with established collagen platforms to create punctal plugs with tunable degradation timelines matched to specific clinical indications. Anterior segment specialists in high-volume ophthalmology clinics are adopting these formats for cataract surgery recovery protocols, where predictable 30-60 day dwell times eliminate removal appointments. This convergence is compressing the traditional permanent-temporary product segmentation and forcing manufacturers to build platform flexibility into molding operations.
EU MDR Annex I general safety and performance requirements are extending clinical evaluation obligations to legacy devices previously grandfathered under the Medical Device Directive. Manufacturers must now generate post-market clinical follow-up data for established silicone plug lines, elevating surveillance costs and documentation burdens. Smaller product portfolios face disproportionate compliance overhead, accelerating portfolio rationalization among mid-tier competitors.
Direct-to-practitioner distribution models are displacing traditional hospital supply chain intermediaries as ophthalmology clinics build independent procurement capabilities. Specialty distributors with cold-chain and sterile handling expertise are capturing incremental margin from manufacturers seeking to bypass group purchasing organizations. This channel fragmentation is most visible in the United States, where ambulatory surgical center networks negotiate site-specific contracts outside legacy hospital system frameworks.
Tear Duct Plugs Market Segmentation
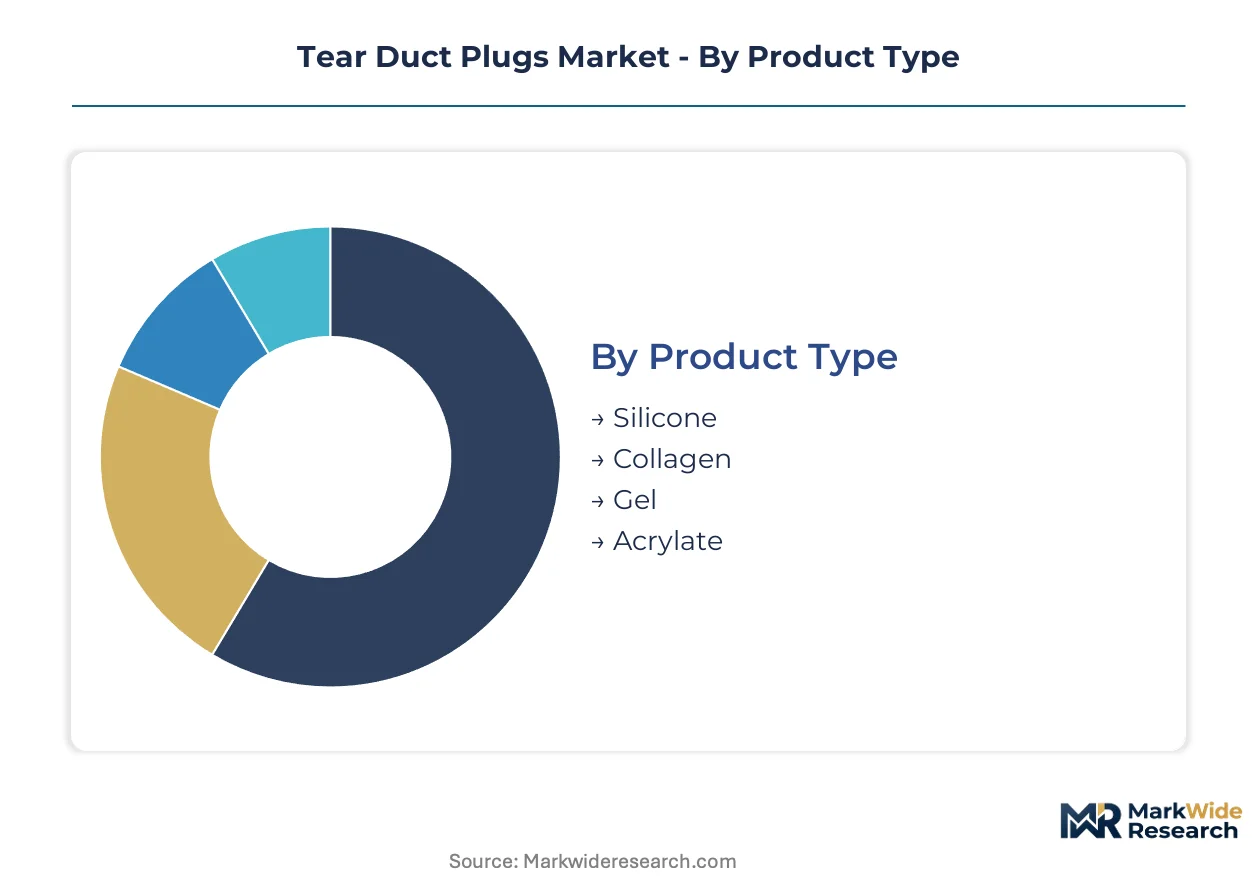
Segmentation in the tear duct plugs market reveals how dwell time requirements, reimbursement pathways, and procedural settings reshape procurement patterns. Manufacturers must align material selection and delivery formats against distinct clinical workflows that vary sharply across end-user channels.
Product Type:
Cycle times diverge dramatically: silicone implants deliver multi-year occlusion with single insertion events, while collagen formats turn over every 30-90 days as resorption completes.
- Silicone:Medical-grade elastomer formulations achieve 0.3–0.7 mm precision tolerances through micro-molding processes. Hospital outpatient departments in the United States favor these permanent implants for aqueous-deficient dry eye protocols where long-term compliance is prioritized over removal logistics. FDA 510(k) predicate requirements constrain geometric innovation but anchor reimbursement stability.
- Collagen:Purified bovine or porcine extracellular matrix structures biodegrade through enzymatic hydrolysis. German corneal centers are expanding collagen utilization for perioperative cataract recovery, where predictable 60-day dwell times eliminate follow-up removal visits and align with reimbursed temporary occlusion pathways.
- Gel:Hydrogel platforms from resorbable synthetic polymers enable tunable degradation kinetics matched to specific healing windows.
- Acrylate:Synthetic polymer alternatives offer intermediate durability between permanent silicone and fully resorbable formats.
Silicone anchors the volume base while collagen gains share at the steepest rate.
Application:
Cost tier stratification separates reimbursed medical indications from elective cosmetic procedures, with surgical recovery occupying the premium reimbursement band.
- Dry Eye Treatment:Chronic evaporative and aqueous-deficient conditions drive the core addressable population. Ophthalmology clinics in ambulatory surgical center networks capture procedural volume through point-of-care insertion capacity that bypasses hospital scheduling constraints.
- Surgical Procedure:Post-cataract and refractive surgery recovery protocols demand precise occlusion timing. Collagen resorption kinetics align with corneal epithelial healing trajectories, expanding adoption among anterior segment specialists.
- Allergy Management:Seasonal allergic conjunctivitis protocols utilize temporary occlusion to reduce antihistamine dependence.
- Cosmetic Use:Elective punctal occlusion for contact lens comfort enhancement operates outside reimbursed pathways.
Dry eye treatment commands the installed base while surgical procedure applications expand most quickly.
End User:
Customer type fragmentation concentrates procurement authority in distinct channel configurations that reshape distribution economics.
- Ophthalmology Clinics:Ambulatory settings with dedicated anterior segment specialists perform high-volume insertion procedures. United States-based clinic networks negotiate direct manufacturer contracts outside group purchasing organization frameworks, capturing margin through streamlined patient throughput.
- Hospitals:Academic medical centers and integrated delivery networks retain bundled reimbursement advantages for complex ocular surface disorders. EU MDR clinical evidence requirements elevate documentation burdens for silicone plug lines used in these settings.
- Home Care:Self-administered temporary plug formats serve patients with transportation barriers.
- Research Laboratories:Preclinical and clinical trial supply contracts demand specialized lot tracking and biocompatibility documentation.
Hospitals retain margin concentration while ophthalmology clinics capture volume at the fastest clip.
Delivery Mode:
Volume economics favor topical insertion simplicity, while intraocular approaches concentrate in specialized surgical settings with higher technical barriers.
- Topical:Direct punctal insertion without instrumentation dominates procedural volume. Standardized inserter designs reduce training burden for clinic staff.
- Injectable:Gel-based formats enable minimally controlled deposition through micro-cannula systems.
- Intraocular:Canalicular implantation requires specialized surgical instrumentation and operating room infrastructure.
- Others:Emerging delivery mechanisms include pre-loaded applicators and customized sizing systems.
Topical delivery anchors procedure counts while injectable formats climb fastest as resorbable polymer platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the procedural volume leader, while EU MDR biocompatibility standards reshape competitive access across European markets. Germany's reimbursed dry eye protocols and Japan's PMDA approval frameworks create distinct regional entry requirements that favor established ISO 10993 testing infrastructure.
United States
Ophthalmology clinics in ambulatory surgical center networks drive the fastest volume expansion as point-of-care insertion bypasses hospital scheduling constraints. FDA Class II medical device clearance maintains predicate alignment requirements that constrain geometric innovation for permanent plugs. The Southeast and Southwest corridor concentrate procedural growth where ASC ocular service lines expand fastest.
Germany
Specialized corneal centers in Bavaria and Baden-Württemberg execute reimbursed punctal occlusion protocols unmatched elsewhere in Europe. EU MDR Annex I clinical evidence requirements extend to legacy devices previously grandfathered under the Medical Device Directive. Berlin-Brandenburg hosts concentrated post-market surveillance infrastructure serving manufacturers with multi-jurisdiction portfolios.
Japan
PMDA approval timelines and JIS biocompatibility standards create parallel certification tracks for silicone-based implants targeting chronic dry eye populations. Tokyo and Osaka metropolitan areas concentrate anterior segment specialist density. Kansai region clinics pioneer temporary collagen plug adoption for perioperative cataract recovery aligned with national health insurance reimbursement windows.
United Kingdom
NHS England specialized commissioning frameworks determine access to punctal occlusion for aqueous-deficient dry eye indications. London and Southeast England concentrate private ophthalmology clinic networks negotiating direct manufacturer contracts. MHRA post-Brexit regulatory alignment creates transitional evidence requirements for CE-marked devices seeking UKCA designation.
India
CDSCO medical device registration rules and state-level ophthalmology infrastructure expansion drive procedural accessibility in tier-1 cities. Maharashtra and Karnataka host concentrated cornea specialist training centers adopting temporary plug formats for postsurgical recovery. Delhi-NCR private clinic networks build direct procurement channels bypassing traditional hospital supply intermediaries.
Tear Duct Plugs Market Competitive Landscape
Specialized ophthalmic device manufacturers and diversified surgical supply conglomerates split the market along material science expertise versus distribution scale vectors. The vendor base concentrates among mid-cap specialists with ISO 10993 testing infrastructure and large-cap surgical portfolios seeking anterior segment adjacencies. Hydrogel platform specialists and collagen-based temporary plug developers represent distinct strategic archetypes. Competitive moves center on bioresorbable polymer R&D partnerships and direct-to-clinic distribution bypassing group purchasing organizations.
Within the material science specialist tier, Ocular Therapeutix and Lacrimedics occupy differentiated positions around resorbable versus collagen-based formats. Corza Medical anchors the surgical instrumentation bundling archetype. Among diversified ophthalmic portfolios, Alcon and Bausch & Lomb exemplify scale-driven competitors leveraging established anterior segment sales infrastructure. These five entities represent the competitive core, with OASIS Medical, FCI Ophthalmics, and Beaver-Visitec International sitting within mid-tier specialization brackets focused on practitioner familiarity and regional distribution density.
| Leading Market Players |
|---|
| Ocular Therapeutix |
| Corza Medical |
| OASIS Medical |
| Lacrimedics |
| Beaver-Visitec International |
| FCI Ophthalmics |
| Bausch & Lomb |
| Alcon |
| Innovia Medical |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone feedstock concentration among German and Japanese chemical processors anchors pricing power for downstream punctal plug manufacturers, with margin pools concentrating at the formulation and precision-molding tiers rather than raw material conversion. This upstream oligopoly forces device makers to absorb input volatility or pass through via contract renegotiation with hospital purchasing committees.
Pricing Analysis
United States ophthalmology clinics command 15-25% premiums over German corneal centers for identical silicone plug SKUs, reflecting reimbursement bundling advantages and direct-to-practitioner procurement bypassing group purchasing organization fees. Three-tier pricing structure across premium, standard, and economy levels stratifies by dwell time specification and biocompatibility certification grade, with FDA 510(k) predicate alignment commanding brand premiums. Pricing pressure stems from collagen temporary plug commoditization as manufacturing scale expands, squeezing mid-tier silicone permanent formats. Hospital outpatient departments exhibit highest price sensitivity due to bundled reimbursement constraints, while ambulatory surgical center networks prioritize throughput economics over per-unit cost.
Supply Chain Analysis
Upward feedstock flows draw from medical-grade silicone polymer production concentrated in Germany, Japan, and the United States, with collagen raw material sourcing anchored in New Zealand and Australian bovine processing facilities. Critical dependencies center on ISO 10993-certified elastomer formulations, precision micro-molding equipment, and sterilization validation services. Single-source vulnerability characterizes specialized injection molding cleanroom infrastructure capable of 0.3-0.7 mm dimensional tolerances. Distribution runs through specialty ophthalmic device distributors with sterile handling capabilities, displacing traditional hospital supply intermediaries as clinic direct procurement accelerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tear duct plugs market reads as a service-attach opportunity where removal logistics and sizing consultation subscriptions expand faster than hardware unit economics, rewarding manufacturers who bundle procedural training and patient monitoring platforms.
For Market Incumbents: Build regulatory data moats through EU MDR post-market clinical follow-up infrastructure that smaller portfolios cannot replicate. Consolidate manufacturing scale in Bavaria and Baden-Württemberg to capture German reimbursed procedure volume concentration. Counter pharmacologic substitution threats by embedding plug insertion within cataract surgery bundled protocols. Prioritize bioresorbable polymer R&D partnerships over geometric device innovation constrained by FDA predicate alignment requirements. For New Entrants and Emerging Players: India's tier-1 cities present the most penetrable white-space as CDSCO registration pathways simplify and cornea specialist training centers expand in Maharashtra and Karnataka. Target collagen temporary plug formats where manufacturing barriers sit lower than silicone micro-molding. Pursue direct-to-clinic distribution models bypassing entrenched group purchasing organization relationships in United States ambulatory surgical center networks. Anchor initial volume through research laboratory supply contracts demanding less brand recognition than clinical settings. For Investors and Strategic Acquirers: Capital is best deployed toward ISO 10993 testing infrastructure owners with multi-jurisdiction certification capabilities, as EU MDR and Japan PMDA evidence requirements elevate compliance barriers. Long-term viability over a 5-10 year horizon favors platform players with hydrogel and collagen material science expertise over pure silicone permanent plug portfolios facing resorbable displacement. Watch resorbable polymer convergence signals from adjacent drug-eluting stent and suture technology markets as inflection indicators for material science disruption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR Annex I compliance captures German reimbursed procedure volume concentration. |
| Bioresorbable Polymer R&D Partnership | Controlled degradation kinetics from stent technology hybridization expands temporary plug applications. |
| Direct-to-Clinic Distribution Buildout | Specialty distributor sterile handling expertise captures margin from GPO bypass in United States ASC networks. |
| Hospital System Partnership | Bundled reimbursement advantages for complex ocular surface disorders anchor silicone permanent plug volume. |
| Software Companion Development | Teleophthalmology pre-screening platforms expand punctal occlusion candidacy beyond traditional catchment areas. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with anterior segment specialists, ambulatory surgical center administrators, biomedical engineers, GPO contracts managers, and ophthalmic device distributors. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and ISO 10993 biocompatibility testing records. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue attribution across material type and end-user channel segmentation.
Calibration against historical regulatory approval timelines and reimbursed procedure adoption curves anchored growth projections across the modeling period. Segmentation dimensions modeled include product dwell time category, application indication, end-user facility type, delivery mode complexity, and regional regulatory cluster. CAGRs derived from slope-intercept analysis of procedure volume trajectories, adjusted for reimbursement policy shift probabilities and material substitution elasticity parameters specific to resorbable polymer innovation cycles.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement austerity measures or medical device excise tax regimes would shift the trajectory materially. Forecasts reflect assumptions around EU MDR implementation consistency and collagen supply chain stability from bovine source regions. Cross-checking against CMS Medicare procedure volume benchmarks and German statutory health insurance claims data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Powered Wheelchair Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market
Medical Devices
Surgical Loupes and Cameras Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Uterine Fibroid Embolization Devices Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Japan Contraceptive Devices Market
Medical Devices
Endodontic Devices Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
Bone Power Tools Market
Medical Devices
Knee Braces Market