
 Medical Electronics Market | 2026-2036
Medical Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Electronics Market Analysis
REACH compliance is decoupling European market access from legacy component sourcing strategies. Texas Instruments Incorporated leverages its analog portfolio to sustain design wins across patient monitoring architectures. STMicroelectronics specializes in MEMS sensors for wearable and diagnostic platforms, occupying a defensible niche in motion and pressure sensing.
Medical electronics encompasses electronic components, devices, and systems engineered for diagnostic, therapeutic, and patient monitoring applications, typically operating within stringent electromagnetic compatibility envelopes and ISO 13485 quality management protocols. These systems process physiological signals, control therapeutic energy delivery, and enable real-time clinical decision support across acute and ambulatory settings. Monitoring Devices leads product type revenue due to recurring sensor replacement cycles and telemetry subscription models. Wearable Tech within the technology dimension is expanding fastest as semiconductor miniaturization enables continuous glucose, cardiac, and respiratory tracking outside institutional walls. Diagnostics commands the largest application share, though Rehabilitation is gaining traction as aging populations drive demand for sensor-guided physical therapy systems.
The FDA governs premarket clearance and software validation for US-bound devices, while the EU Medical Device Regulation (MDR) and EMA oversight reshape conformity assessment timelines for European market entry. China's NMPA accelerates local approval pathways for AI-enabled diagnostic tools, compressing time-to-market for domestically manufactured imaging systems. Stakeholders must calibrate regulatory submission strategies across jurisdictions before committing to platform architectures that lock in component choices.
Market Dynamics
Decentralized patient monitoring is forcing manufacturers to redesign hardware architectures for home care environments, compressing device footprints while preserving clinical-grade signal fidelity.
Growth Catalysts
- Software-as-a-Medical-Device framework:The FDA's evolving guidance creates clearer pathways for algorithm-driven diagnostics, reducing premarket uncertainty for AI-enabled imaging tools.
- Home care migration:Patients with chronic conditions in Germany and Japan are demanding telemetry-enabled devices that transmit continuous glucose and cardiac data to remote care teams.
- MEMS miniaturization:Advances in microelectromechanical systems enable multi-sensor wearables that track respiratory patterns alongside traditional vital signs.
Market Restraints
- ISO 13485 certification timelines:Quality management audits for new manufacturing facilities routinely extend 18-24 months, delaying product launches regardless of technical readiness.
- Specialized analog component concentration:Precision signal conditioning chips for patient monitoring rely on a narrow supplier base concentrated in East Asian foundries.
- Electromagnetic compatibility testing:Devices must demonstrate immunity to interference from Wi-Fi, cellular, and surgical equipment in increasingly dense RF environments.
Strategic Opportunities
- Rural health networks:India's tier-two and tier-three cities lack diagnostic infrastructure, creating demand for portable ultrasound and ECG systems with cloud connectivity.
- EU MDR harmonization:The Medical Device Regulation's consolidated conformity assessment reduces fragmentation across member states for manufacturers holding CE marking.
- Sensor fusion architectures:Combining photoplethysmography with accelerometry and temperature sensing enables single-wearable multiparameter monitoring previously requiring multiple devices.
Industry Challenges
- Biomedical signal processing expertise:The scarcity of engineers trained in both analog circuit design and clinical physiology lengthens product development cycles.
- Legacy system integration:New wearable platforms must interface with hospital information systems running decades-old protocols, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Electronics Market |
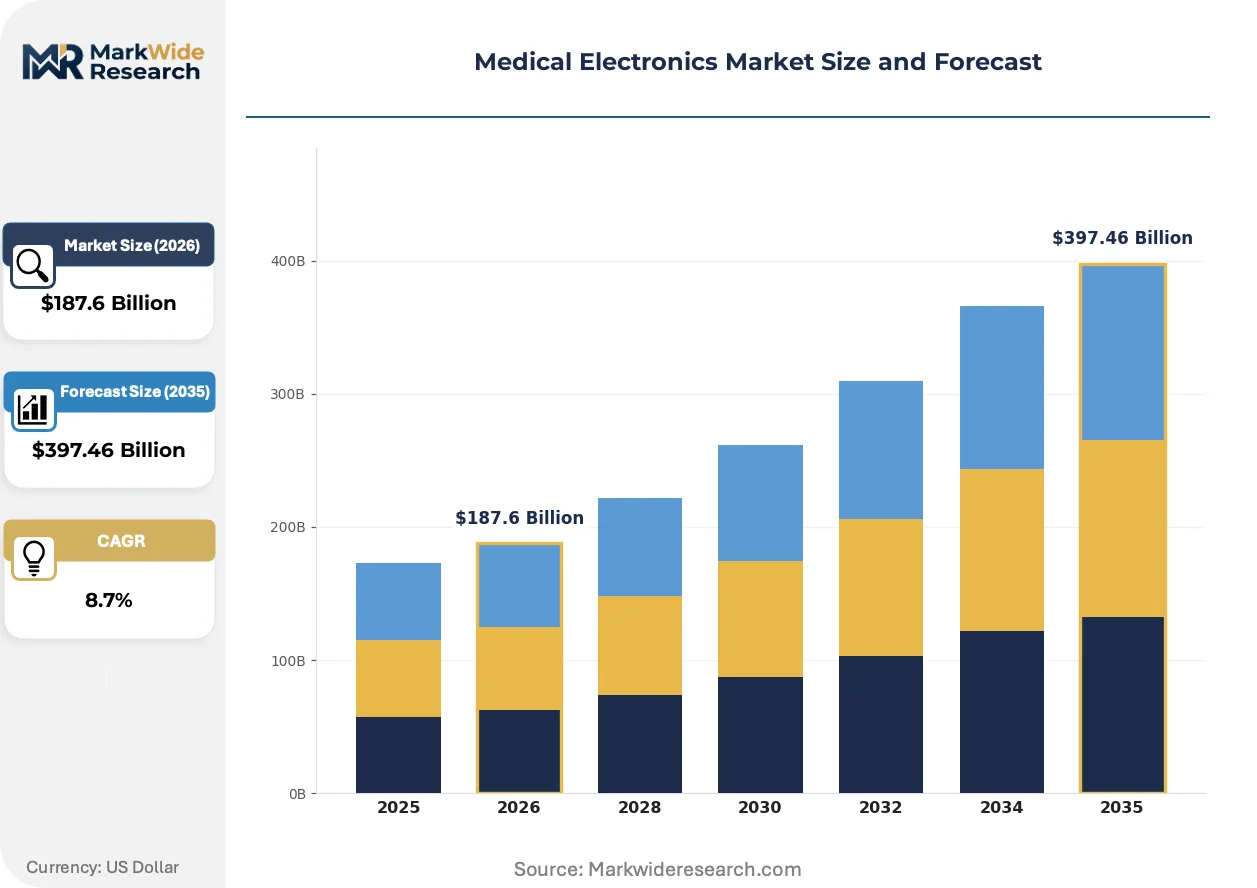
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Devices, Imaging Equipment, ECG Machines, Surgical Instruments End User: Hospitals, Clinics, Research Facilities, Home Care Technology: Wearable Tech, Telehealth Solutions, Diagnostic Imaging, Laboratory Devices Application: Diagnostics, Therapeutics, Patient Monitoring, Rehabilitation |
| Companies Covered | Analog Devices, Inc., Texas Instruments Incorporated, STMicroelectronics, NXP Semiconductors, Infineon Technologies AG, TE Connectivity, Samsung Electronics, Medtronic plc, Siemens Healthineers AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Electronics Market Emerging Trajectories
Semiconductor architectures are being reconfigured for intermittent operation and ultra-low power draw, enabling devices that function for weeks without patient intervention.
Edge computing is expanding into wearable form factors, allowing real-time arrhythmia detection without cloud dependency. Cardiology departments in Nordic countries are piloting these systems for post-discharge monitoring. This local processing capability is expanding into diagnostic workflows previously requiring hospital-grade servers.
REACH substance restrictions are forcing component suppliers to reformulate solders and coatings for European market access. Manufacturers with legacy supply chains face recertification costs that disadvantage smaller competitors. Diagnostic imaging equipment with extended service lifecycles represents the most exposed product category.
Hospital procurement departments are unbundling device purchases from multi-year service contracts, treating maintenance as a separately negotiated spend category. Original equipment manufacturers in the United States are responding with modular hardware designs that enable third-party servicing. This behavioral shift is compressing margins on the recurring revenue streams that historically subsidized upfront device pricing.
Medical Electronics Market Segmentation
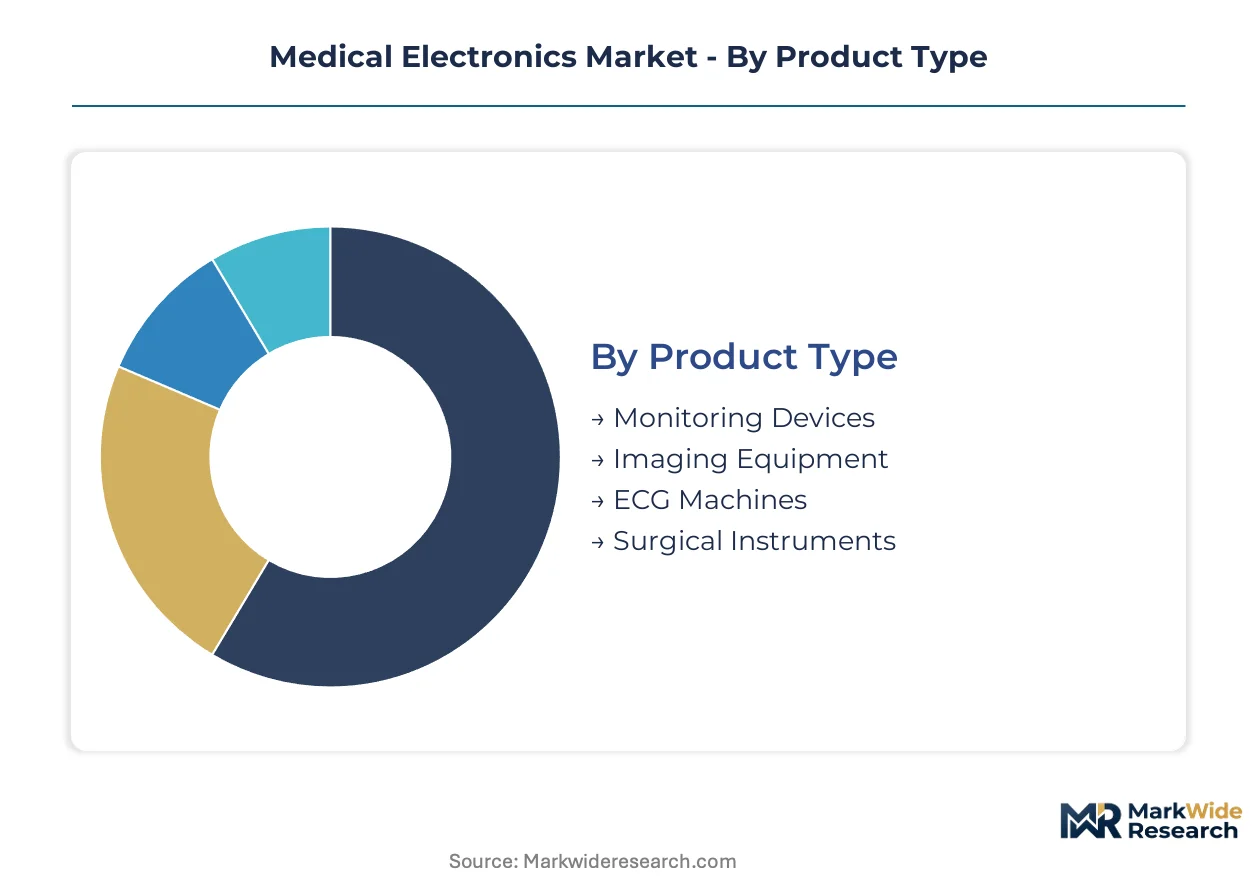
Medical electronics segmentation reveals how hardware architectures, care delivery models, and regulatory pathways intersect to create distinct competitive arenas. Component selection, certification requirements, and reimbursement codes vary dramatically across these boundaries, forcing manufacturers to prioritize specific segment combinations rather than pursuing horizontal coverage.
Product Type:
Monitoring Devices command premium pricing through recurring sensor replacement cycles, while Imaging Equipment concentrates revenue in capital-constrained hospital procurement departments. ECG Machines and Surgical Instruments occupy mid-tier volume positions shaped by regional reimbursement policies.
- Monitoring Devices:These systems process continuous physiological signals through wearable patches, bedside telemetry units, and implantable sensors. Demand concentrates in German home care networks where remote patient monitoring receives favorable reimbursement under statutory health insurance frameworks, though ISO 13485 certification timelines routinely delay product launches.
- Imaging Equipment:MRI, CT, and ultrasound platforms integrate high-voltage power electronics with precision analog front-ends for signal acquisition. China's NMPA accelerates local approval pathways for domestically manufactured systems, compressing time-to-market for AI-enabled diagnostic tools while REACH substance restrictions force European suppliers to reformulate solders and coatings.
- ECG Machines:Portable and stationary electrocardiography systems rely on specialized analog components for millivolt-level signal detection.
- Surgical Instruments:Electrosurgical generators and robotic-assisted platforms deliver controlled therapeutic energy with real-time feedback loops.
Today's leader: Monitoring Devices. Tomorrow's challenger: Imaging Equipment.
End User:
Hospital procurement departments unbundle device purchases from service contracts, compressing margins on recurring revenue streams. Clinics and Research Facilities face capital constraints that favor modular, upgradeable architectures, while Home Care demands telemetry-enabled devices with cloud connectivity.
- Hospitals:Acute care institutions operate the highest device densities, requiring electromagnetic compatibility testing against dense RF environments from Wi-Fi, cellular, and surgical equipment. Japanese cardiology departments pilot edge-computing wearables for post-discharge monitoring, establishing clinical validation pathways that manufacturers leverage for FDA submissions.
- Home Care:Patients with chronic conditions in Germany and Japan demand continuous glucose and cardiac data transmission to remote care teams. Semiconductor miniaturization enables multi-sensor wearables that function for weeks without intervention, though legacy hospital information system integration requires costly middleware development.
- Clinics:Outpatient facilities prioritize portable ultrasound and ECG systems with rapid deployment capabilities.
- Research Facilities:Academic medical centers drive early adoption of sensor fusion architectures combining photoplethysmography with accelerometry.
Hospital procurement now treats maintenance as separately negotiated spend, eroding the service-contract subsidies that historically supported upfront device pricing.
Technology:
Wearable Tech expands most quickly as MEMS miniaturization enables continuous tracking outside institutional walls, while Telehealth Solutions reshape reimbursement codes. Diagnostic Imaging and Laboratory Devices retain stable demand tied to capital equipment replacement cycles.
- Wearable Tech:Multi-sensor platforms integrate motion, pressure, temperature, and optical sensing in sub-millimeter semiconductor packages. Nordic cardiology departments validate real-time arrhythmia detection without cloud dependency, establishing clinical evidence for FDA software-as-a-medical-device submissions.
- Telehealth Solutions:Cloud-connected diagnostic platforms enable remote interpretation of imaging and physiological data. India's tier-two and tier-three cities lack diagnostic infrastructure, creating demand for portable systems with cellular backhaul.
- Diagnostic Imaging:AI-enabled reconstruction algorithms reduce scan times and radiation exposure in CT and MRI workflows.
- Laboratory Devices:Automated analyzers for hematology, chemistry, and immunoassay integrate precision fluidics with optical detection systems.
Edge computing migration into wearable form factors represents the steepest expansion trajectory, displacing hospital-grade server dependencies for real-time clinical decision support.
Application:
Diagnostics captures the largest revenue share through imaging and laboratory test volumes, while Rehabilitation gains traction from aging populations requiring sensor-guided physical therapy. Therapeutics and Patient Monitoring occupy intermediate positions shaped by procedure reimbursement rates.
- Diagnostics:Imaging equipment and laboratory analyzers process biological samples and physiological signals to detect disease states. REACH substance restrictions expose extended-service-lifecycle equipment to recertification costs that disadvantage smaller competitors in European markets.
- Rehabilitation:Sensor-guided physical therapy systems track range of motion, force application, and adherence metrics. Aging demographics in Japan and Germany drive demand for home-based recovery monitoring that reduces institutional readmission rates.
- Therapeutics:Drug delivery systems and energy-based treatment platforms require precise control electronics with fail-safe architectures.
- Patient Monitoring:Continuous surveillance of vital signs spans acute, sub-acute, and ambulatory care settings with varying signal fidelity requirements.
Diagnostics retains volume leadership through procedure-based reimbursement, while Rehabilitation climbs fastest as value-based care models reward outcome improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The medical electronics industry traces its modern foundations to post-war Germany, where Siemens pioneered precision diagnostic instrumentation and established quality protocols that shaped global manufacturing standards for patient monitoring and imaging systems.
United States
FDA's software-as-a-medical-device framework accelerates algorithm-driven diagnostic approvals, reducing premarket uncertainty for AI-enabled imaging tools. The agency's evolving guidance on continuous glucose monitors and cardiac telemetry reshapes compliance timelines for wearable manufacturers. Greater Boston anchors a dense cluster of biomedical signal processing startups alongside MIT's clinical engineering programs.
Germany
Siemens Healthineers anchors a precision engineering ecosystem where statutory health insurance frameworks reimburse remote patient monitoring for chronic disease management. The EU Medical Device Regulation's consolidated conformity assessment reduces fragmentation across member states for CE-marked manufacturers. Erlangen and Forchheim concentrate MRI and CT engineering talent alongside specialized analog component suppliers.
China
NMPA accelerates local approval pathways for domestically manufactured AI-enabled imaging systems, compressing time-to-market for CT reconstruction algorithms. The regulator's streamlined processes for class II diagnostic devices attract multinational joint ventures seeking manufacturing cost advantages. Shenzhen's electronics corridor integrates MEMS foundries with portable ultrasound assembly operations serving tier-two hospital networks.
Japan
PMDA validates edge-computing wearables for post-discharge cardiac monitoring, establishing clinical evidence pathways that manufacturers leverage for FDA submissions. METI funding for aging-in-place technologies drives demand for multi-sensor platforms tracking respiratory patterns alongside traditional vital signs. Tokyo and Osaka medical device districts concentrate electrosurgical generator engineering and precision analog front-end design.
India
CDSCO's accelerated approval pathways for portable diagnostic devices address infrastructure gaps in tier-two and tier-three cities lacking imaging equipment. The PLI scheme for medical device manufacturing attracts component suppliers to domestic assembly operations. Bengaluru's electronics corridor integrates semiconductor design houses with telehealth platform developers targeting rural health networks.
Medical Electronics Market Vendor Landscape
The competitive structure tilts toward diversified semiconductor conglomerates with analog and MEMS portfolios. Market concentration remains moderate, with component suppliers occupying defensible niches in signal conditioning and sensor miniaturization. Three archetypes dominate: precision analog specialists, integrated device manufacturers with healthcare verticals, and diversified electronics conglomerates leveraging scale. Consolidation through strategic acquisitions and technology licensing agreements characterizes recent competitive moves, alongside capacity expansion in East Asian MEMS foundries.
Within the precision analog tier, Texas Instruments Incorporated and Analog Devices, Inc. occupy positions defined by signal conditioning expertise for patient monitoring architectures. STMicroelectronics exemplifies the MEMS sensor specialist archetype, with its portfolio spanning motion and pressure sensing for wearable platforms. Siemens Healthineers AG anchors the integrated systems manufacturer category, representing the convergence of precision engineering heritage with software-enabled diagnostic workflows. These three entities collectively illustrate how competitive positioning depends on architectural control points across hardware, firmware, and regulatory validation capabilities.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| Texas Instruments Incorporated |
| STMicroelectronics |
| NXP Semiconductors |
| Infineon Technologies AG |
| TE Connectivity |
| Samsung Electronics |
| Medtronic plc |
| Siemens Healthineers AG |
| Others |
Supply Flow & Price Mechanics
Hospital procurement departments unbundle device purchases from multi-year service contracts, forcing original equipment manufacturers toward modular hardware designs and third-party service enablement. This behavioral shift compresses margins on recurring revenue streams that historically subsidized upfront device pricing, while REACH compliance costs and ISO 13485 certification timelines concentrate pricing power among diversified conglomerates with captive regulatory expertise.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates medical electronics, with differentiation driven by FDA clearance tier and after-sales service bundling. Cost compression in standard-tier monitoring devices intensifies as hospital procurement committees treat maintenance as separately negotiated spend, eroding cross-subsidy mechanisms. Tier-two cities in India exhibit highest price sensitivity due to capital constraints, while German statutory health insurance frameworks sustain premium-tier tolerance for remote patient monitoring systems.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Siemens Healthineers and Medtronic, while specialized distributors serve mid-tier manufacturers in India's medical device corridor. Precision analog components draw from Taiwan and South Korea, with MEMS sensors anchored in East Asian foundries. Single-source vulnerability in specialized signal conditioning chips creates exposure, as tariff exposure on semiconductor inputs from China compounds lead time uncertainty for European and North American assembly operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical electronics market functions as a regulatory compounder, where FDA's software-as-a-medical-device framework and EU MDR harmonization create accelerating compliance burdens that favor incumbents with established validation infrastructure. These regulatory milestones drive demand for algorithm-driven diagnostics while compressing time-to-market for prepared manufacturers.
For Market Incumbents: Anticipate margin compression from unbundled service contracts by deepening backward integration into MEMS foundry capacity in Taiwan and South Korea. Defensive consolidation through acquisition of biomedical signal processing startups in Greater Boston addresses scarcity of engineers trained in analog circuit design and clinical physiology. Certification investment in CE marking pathways under EU MDR consolidates fragmented conformity assessment timelines across member states. For New Entrants and Emerging Players: Enter via India's tier-two and tier-three cities, where diagnostic infrastructure gaps create penetrable white-space for portable ultrasound and ECG systems with cloud connectivity. Target home care settings in Germany and Japan, where statutory reimbursement frameworks favor telemetry-enabled chronic disease management. A software-as-a-medical-device go-to-market angle bypasses capital-intensive hardware manufacturing while leveraging FDA's clarified algorithm-driven diagnostic pathways. For Investors and Strategic Acquirers: Diversified semiconductor conglomerates with healthcare verticals represent the most active acquirer category in this space, seeking MEMS sensor specialists and precision analog portfolios. Long-term viability over a five-to-ten year window rests on architectural control across hardware, firmware, and regulatory validation capabilities. Watch for NMPA accelerated approval pathway expansions in China as inflection indicator for domestic manufacturing joint venture activity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Accelerates premarket clearance for AI-enabled cardiac telemetry algorithms under evolving FDA guidance. |
| CE Marking Pathway Consolidation | Reduces fragmentation across EU member states through MDR harmonized conformity assessment procedures. |
| Hospital System Partnership | Secures procurement committee access amid unbundling of device purchases from service contracts. |
| MEMS Foundry Capacity Expansion | Addresses single-source vulnerability in motion and pressure sensing for multi-sensor wearable platforms. |
| Reimbursement Strategy Development | Aligns product positioning with German statutory health insurance remote patient monitoring frameworks. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down component supply tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at FDA and notified bodies were combined with secondary validation from FDA 510(k) filings, EMA medical device registrations, CMS Medicare reimbursement databases, and hospital procurement contract disclosures. Triangulation across these sources ensures segmentation integrity across product type, technology, and application dimensions.
Input-output matrices connect semiconductor unit shipments to downstream device production across the projection horizon, with CAGRs derived from regression analysis against historical reimbursement code expansions and regulatory approval velocity. Segmentation dimensions modeled include product architecture, care delivery setting, certification tier, and regional regulatory cluster. Forecast inputs incorporate MEMS miniaturization curves, ISO 13485 certification pipeline data, and REACH substance restriction implementation timelines.
Inputs from FDA and EMA registration databases were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around pricing elasticity assumptions. Forecasts reflect documented assumptions regarding regulatory pathway stability and reimbursement code continuity. Periodic stress-testing of base assumptions is recommended, particularly around NMPA policy shifts and EU MDR implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Posture Correction Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
China Intrauterine Devices Market
Medical Devices
Video-Guided Pericardial Access Device Market
Medical Devices
Light Therapy Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market
Medical Devices
Mexican Intraocular Lens Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Robot Assisted PCI Market
Medical Devices
India Medical Devices Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Middle East and Africa Surgical Equipment Market
Medical Devices
Elderly and Disabled Assistive Devices Market
Medical Devices
Rectal Catheters Market