
 Cannula Market | 2026-2036
Cannula Market Size, Share, and Industry Trends Forecast 2026-2036
Cannula Market Intelligence
The substitution of traditional polyvinyl chloride with advanced polyurethane is broadening the application scope for flexible cannulas, particularly in long-term intravenous therapy. Becton Dickinson leverages its extensive distribution network to supply hospitals with a wide range of peripheral cannulas. Edwards Lifesciences Corporation specializes in arterial and central venous cannulas for critical care monitoring. Teleflex Incorporated competes through its focus on specialty cannulas designed for anesthesia and regional pain management.
A cannula is a medical tube inserted into the body, often into a vein, to administer medication, deliver fluids, or collect blood samples. These devices are manufactured from materials like polyurethane or silicone and are specified by gauge size, length, and tip design. By product type, peripheral cannulas for intravenous therapy constitute the largest segment by volume. Hospitals remain the dominant end-user, while ambulatory surgical centers represent the fastest-growing segment due to a procedural shift to outpatient care.
Market access is governed by stringent frameworks, including the US FDA's 510(k) clearance pathway and the European Union's Medical Device Regulation (MDR). These regulations impose strict requirements for material biocompatibility, sterilization validation, and labeling. The ISO 10555 standard further dictates the performance criteria for intravascular catheters. Navigating these varied international standards while managing material supply chain volatility is critical for manufacturers.
Market Dynamics
The cannula market's evolution is defined by the tension between material science advancements, particularly the shift to polyurethane, and the increasing stringency of regulatory frameworks like the EU's Medical Device Regulation, which demands higher biocompatibility and clinical evidence standards.
Growth Catalysts
- Procedural Volume Shift:The migration of surgical and therapeutic procedures from traditional hospitals to ambulatory surgical centers fuels demand for peripheral intravenous cannulas suitable for short-stay and outpatient settings.
- Material Innovation:The substitution of traditional polyvinyl chloride with advanced polyurethane and silicone enhances biocompatibility and flexibility, expanding cannula use in long-term and critical care therapies.
- Aging Demographics:An aging population in developed nations like Japan and Germany leads to a higher prevalence of chronic diseases, increasing the frequency of hospitalizations and medical procedures that require cannula use.
Market Restraints
- Regulatory Compliance Burden:Manufacturers face significant costs and extended timelines to secure approvals, navigating complex and divergent pathways such as the FDA's 510(k) process in the United States and the EU's MDR.
- Raw Material Price Volatility:The market is susceptible to price fluctuations in key raw materials like medical-grade polyurethane and silicone, which can compress manufacturer margins and impact product pricing.
- Sterilization Process Complexity:Validating sterilization methods to comply with international standards like ISO 10555 is a technically demanding and costly process, creating a barrier for new and smaller market entrants.
Strategic Opportunities
- Specialty Cannula Development:There is a clear opportunity in designing cannulas for niche, high-value applications, including cardioplegia, regional anesthesia, and specialized pediatric care, which command premium pricing.
- Biodegradable and Eco-Friendly Materials:Research into biodegradable polymers for cannula manufacturing presents a long-term opportunity to address healthcare sustainability goals and differentiate products in environmentally conscious markets.
- Expansion in Emerging Economies:As healthcare infrastructure improves in countries across Southeast Asia and Latin America, there is significant untapped demand for basic and advanced cannulas to support growing hospital systems.
Industry Challenges
- Supply Chain Volatility:Managing a global supply chain for specialized polymers and components is a primary operational challenge, with disruptions directly impacting production schedules and product availability for end-users.
- Extended Certification Timelines:The lengthy process for achieving and maintaining certifications, especially under the European Union's MDR, ties up significant resources and delays the introduction of new product innovations.
- Clinical Staff Training:The introduction of more complex cannulas, such as those for advanced monitoring, requires manufacturers to invest in comprehensive training programs for clinicians to ensure proper use and patient safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannula Market |
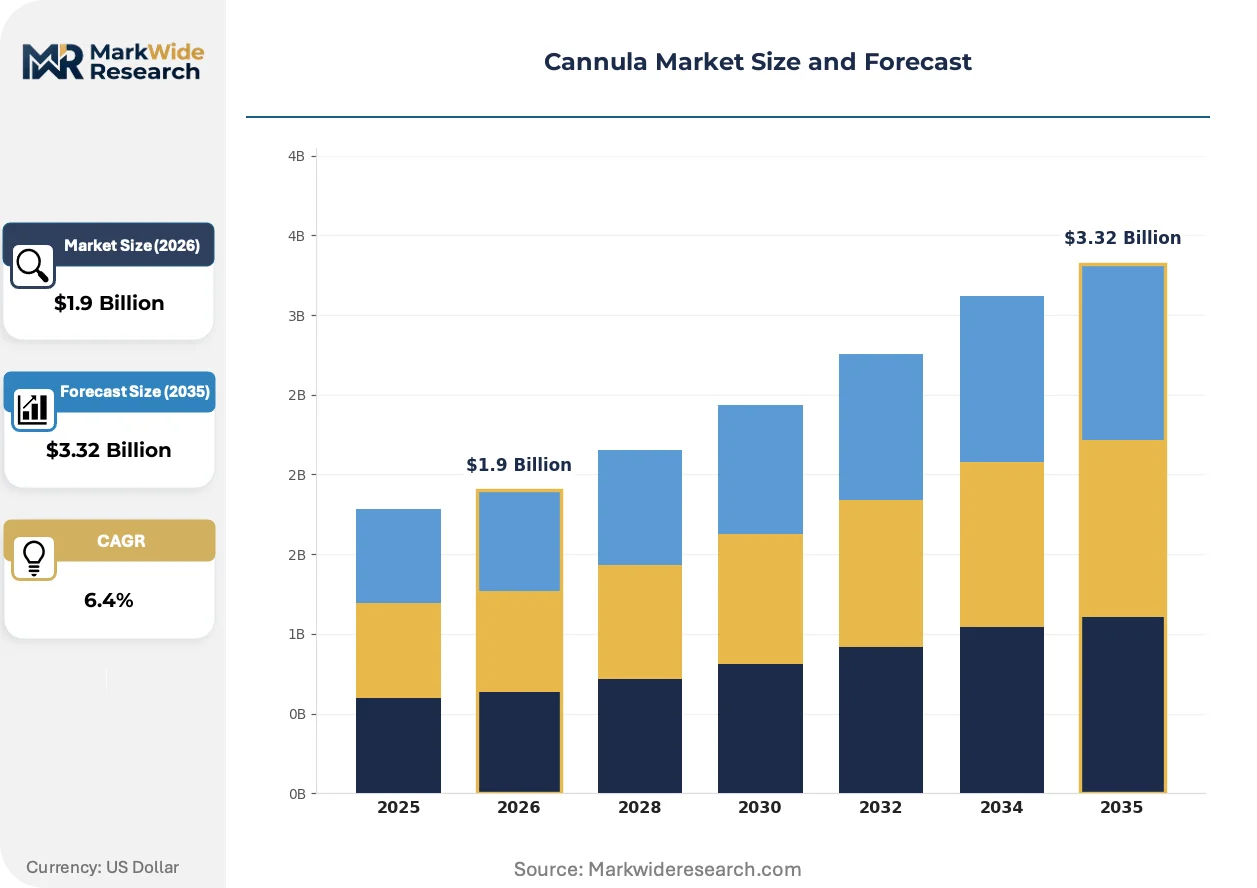
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.32 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peripheral Cannulas, Central Venous Cannulas, Arterial Cannulas, Epidural Cannulas, Others Material: Polyurethane, Silicone, Polyvinyl Chloride, Stainless Steel, Teflon, Others Application: Intravenous Therapy, Blood Sampling, Dialysis, Infusion Therapy, Anesthesia, Others End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Specialty Clinics, Blood Banks |
| Companies Covered | Medtronic, Becton Dickinson, Edwards Lifesciences Corporation, LivaNova PLC, Teleflex Incorporated, ICU Medical, Terumo Corporation, Boston Scientific Corporation, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannula Market Strategic Shifts & Innovations
The cannula market is advancing toward devices that offer enhanced patient safety and support specialized clinical procedures. This evolution is driven by a convergence of material science, stricter regulatory oversight, and a re-evaluation of how medical devices contribute to overall patient outcomes.
Advanced polyurethane provides superior flexibility, kink resistance, and biocompatibility compared to traditional materials. Hospitals and long-term care facilities are adopting these cannulas to reduce the risk of complications like phlebitis in extended intravenous therapy. As a result, polyurethane is overtaking conventional PVC in the manufacturing of flexible cannulas for critical and long-duration applications where patient safety and device longevity are paramount.
The European Union's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence, material biocompatibility, and post-market surveillance. This forces manufacturers to conduct new clinical studies and update technical files for existing products, a costly and time-consuming endeavor. The peripheral cannula segment, characterized by high volume and numerous product variations, is most affected as companies rationalize their portfolios to manage the heightened compliance burden.
A shift from pure unit-cost purchasing to value-based procurement is altering how cannulas are selected. Hospital systems increasingly favor devices that demonstrate a reduction in complication rates, such as catheter-related bloodstream infections, even if the initial purchase price is higher. This trend is most visible within large hospital networks in the United States, where reimbursement models are increasingly tied to patient outcomes.
Cannula Market Segmentation
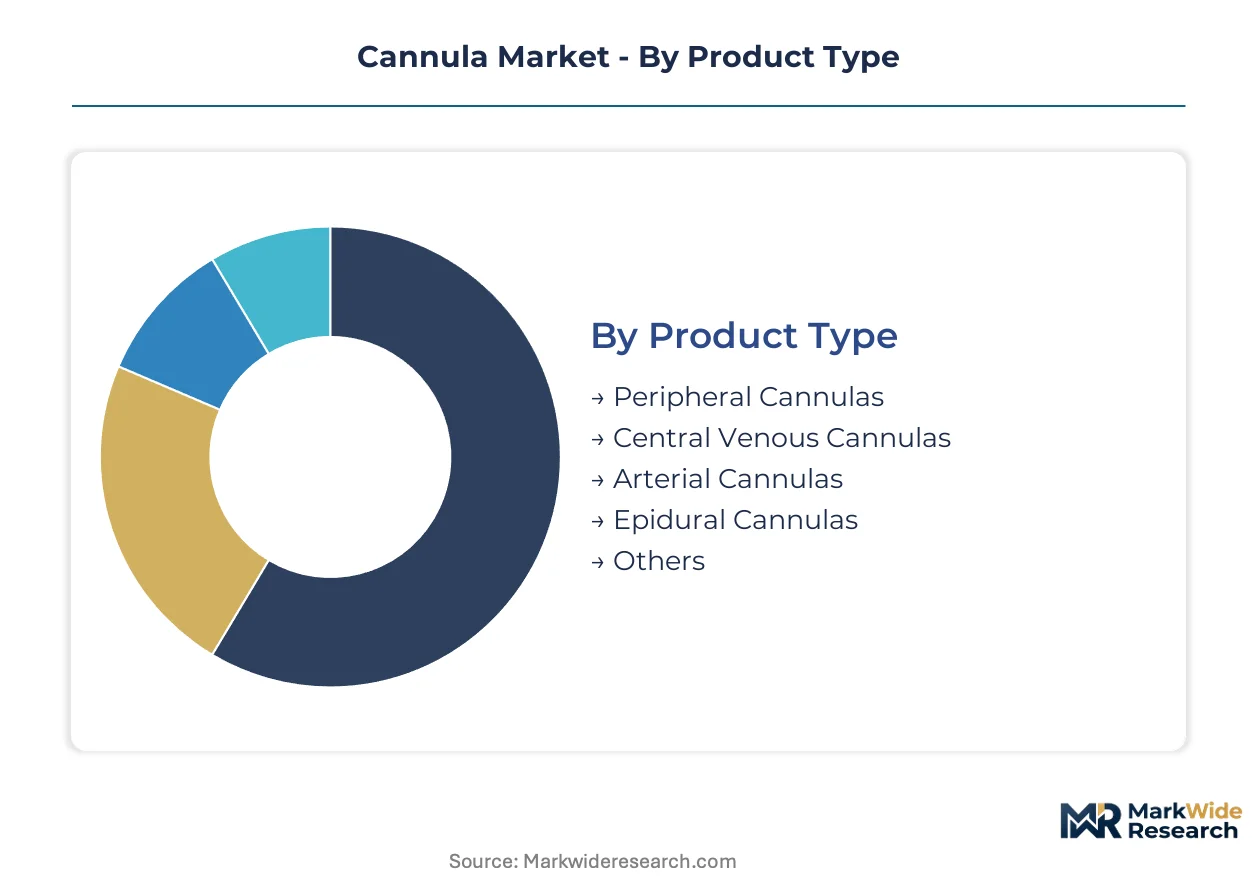
The cannula market segmentation provides a granular view of product utility and end-user requirements, crucial for manufacturers to align product development with clinical demand. Understanding these distinct segments helps identify specific growth pockets and specialized application areas within the broader market.
Product Type:
Buyers in the product type category differentiate their purchases based on specific clinical needs and insertion sites, influencing device design and material choice.
- Peripheral Cannulas:These devices are primarily used for short-term intravenous access, facilitating fluid administration and medication delivery into superficial veins. Demand concentrates in ambulatory surgical centers and outpatient settings due to the shift towards less invasive procedures.
- Central Venous Cannulas:Inserted into large veins near the heart, these cannulas are essential for long-term intravenous therapy, critical care monitoring, and administration of specific medications. Hospitals represent the primary end-user for these more complex and indwelling devices.
- Arterial Cannulas:These are specialized for continuous blood pressure monitoring and arterial blood gas sampling in critical care environments.
- Epidural Cannulas:Designed for regional anesthesia and pain management, these devices deliver medication directly into the epidural space.
- Others:This category encompasses highly specialized cannulas for applications like cardioplegia, ophthalmology, and various surgical drainage procedures.
Peripheral Cannulas lead volumes today; Central Venous Cannulas are gaining share fastest.
Material:
Material selection directly impacts device biocompatibility and flexibility for various clinical durations, influencing patient safety and device longevity.
- Polyurethane:This advanced polymer offers superior flexibility, kink resistance, and enhanced biocompatibility, making it ideal for long-term intravenous therapy and critical care applications. Its adoption is expanding in facilities focused on reducing complication rates.
- Polyvinyl Chloride:A traditional and cost-effective material, PVC cannulas are widely used for basic and short-term intravenous access due to their established manufacturing processes. However, regulatory pressures are driving a shift towards alternative materials.
- Silicone:Known for its excellent biocompatibility and softness, silicone is favored for pediatric and neonatal applications where tissue trauma must be minimized.
- Stainless Steel:Used primarily for rigid needle components and specialized arterial cannulas, stainless steel provides necessary structural integrity for precise insertion.
- Teflon:Valued for its low friction coefficient, Teflon facilitates smoother insertion and reduces the risk of vessel trauma during cannula placement.
- Others:This segment includes various specialized polymers and composite materials developed for specific performance characteristics or niche applications.
Polyurethane adoption is expanding due to enhanced patient safety features.
Application:
Application areas define the functional requirements and design specifications for cannula deployment across diverse medical procedures.
- Intravenous Therapy:This broad application involves the administration of fluids, medications, and nutrients directly into a patient's vein, constituting the largest use case for cannulas. Hospitals and ambulatory surgical centers drive consistent demand for these devices.
- Blood Sampling:Cannulas are routinely used to collect blood samples for diagnostic testing and laboratory analysis, a fundamental procedure in nearly all healthcare settings. Diagnostic laboratories and hospitals represent significant end-users for this application.
- Dialysis:Specialized cannulas provide vascular access for hemodialysis and peritoneal dialysis procedures, crucial for patients with kidney failure.
- Infusion Therapy:This application focuses on the long-term delivery of drugs, chemotherapy, or parenteral nutrition, often requiring more durable and biocompatible cannula designs.
- Anesthesia:Cannulas are critical for administering regional anesthesia and delivering anesthetic agents during surgical procedures, necessitating precise placement and secure fixation.
- Others:This category includes specialized applications such as cardioplegia delivery during cardiac surgery, aspiration, and various drainage procedures.
Intravenous Therapy applications currently dominate usage, with Anesthesia requiring specialized product designs.
End User:
End-user segments reflect diverse procurement patterns and clinical environments for cannula deployment, from high-volume hospital settings to specialized outpatient clinics.
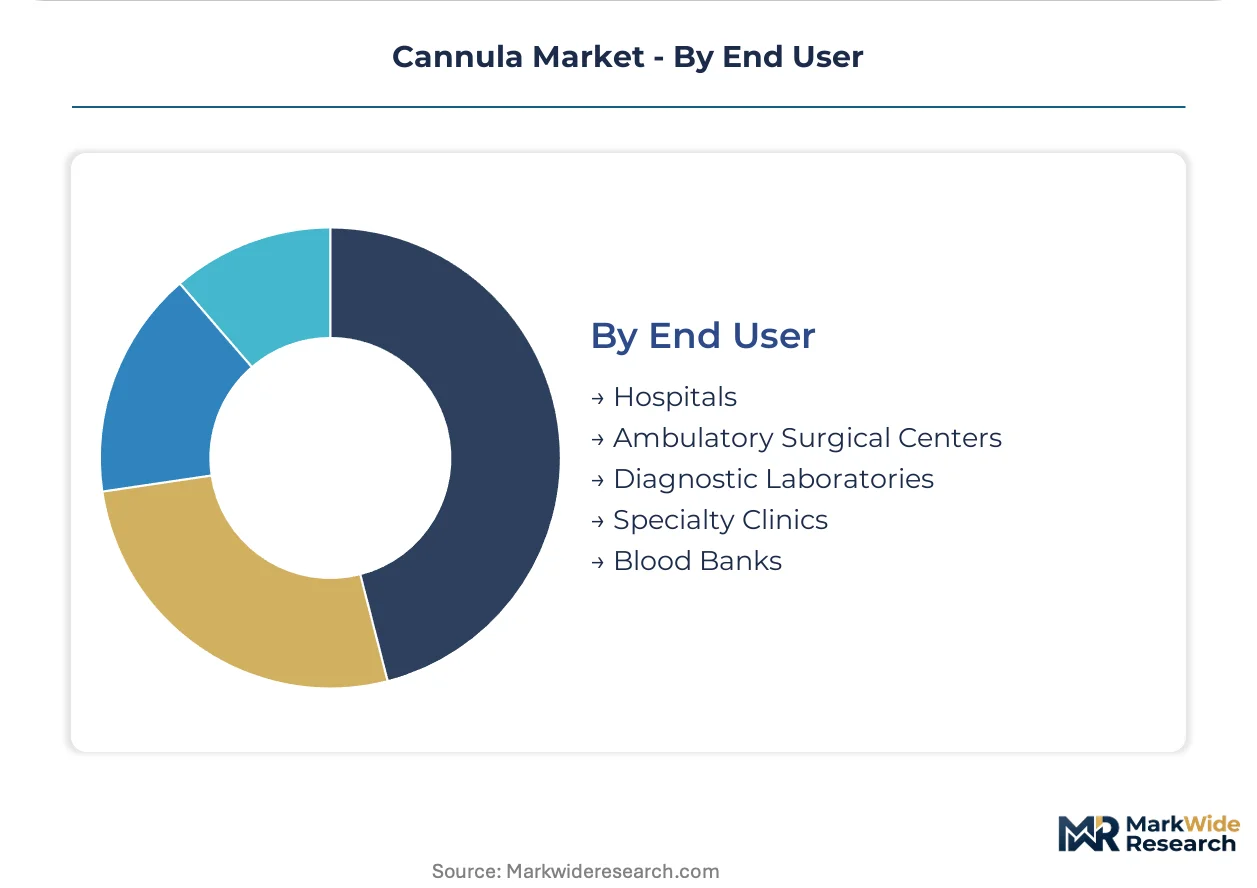
- Hospitals:As the primary end-users, hospitals utilize cannulas across a vast array of departments for critical care, surgical procedures, and general patient management. They demand a wide range of product types and material specifications.
- Ambulatory Surgical Centers:These centers focus on outpatient procedures and short-stay surgeries, driving demand for peripheral cannulas suitable for quick access and efficient patient turnover. The shift of procedures to these centers represents a significant growth area.
- Diagnostic Laboratories:These facilities primarily use cannulas for efficient and sterile blood collection, supporting a high volume of diagnostic testing. Accuracy and ease of use are key considerations for these end-users.
- Specialty Clinics:Clinics focusing on areas like cardiology, oncology, or pain management require specific types of cannulas tailored to their specialized therapeutic interventions.
- Blood Banks:Cannulas are essential for blood donation and transfusion services, ensuring safe and efficient collection and delivery of blood products.
Hospitals represent the largest end-user segment, while Ambulatory Surgical Centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States healthcare market drives significant demand for advanced cannulas, particularly in specialized surgical and critical care settings. This region benefits from robust medical device innovation and high procedural volumes. Strict regulatory oversight ensures product quality and safety across its diverse healthcare facilities.
United States
United States demand for cannulas stems from a high volume of hospital procedures and the shift towards ambulatory surgical centers. The US FDA's 510(k) clearance pathway governs market access, ensuring device safety and efficacy. Major medical device clusters in states like California and Massachusetts foster continuous innovation in cannula design.
Germany
German healthcare infrastructure requires a steady supply of cannulas for its extensive hospital network and aging population. The European Union's Medical Device Regulation (MDR) sets stringent standards for material biocompatibility and clinical evidence. Cities such as Tuttlingen, known as a medical technology hub, concentrate manufacturing and development efforts.
Japan
Japan's aging demographics and advanced healthcare system generate consistent demand for specialized cannulas for chronic disease management. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees product approvals, emphasizing patient safety and quality. Tokyo and Osaka host significant medical device companies and research institutions.
China
China's expanding healthcare access and increasing surgical volumes contribute to rising cannula consumption, especially in urban hospitals. The National Medical Products Administration (NMPA) regulates medical devices, focusing on domestic production and quality control. Shanghai and Shenzhen are key centers for medical device manufacturing and distribution.
India
India's growing medical tourism and improving healthcare infrastructure increase the need for cannulas across various applications. The Central Drugs Standard Control Organization (CDSCO) manages medical device regulations, promoting local manufacturing initiatives. Bengaluru and Hyderabad are emerging as significant hubs for medical technology development and production.
Cannula Market Key Industry Players
Portfolio diversification dominates the current landscape, as manufacturers seek to offer comprehensive solutions across various cannula types. The market structure exhibits a tiered consolidation, with a few large players holding significant share alongside numerous niche specialists. Strategic archetypes include diversified medical device giants, critical care specialists, and regional providers. Geographic expansion and technology licensing are also prevalent competitive moves.
On the premium-tier vector, Edwards Lifesciences Corporation exemplifies a focus on high-value, critical care applications, particularly with its arterial and central venous cannulas for advanced monitoring. Becton Dickinson, a diversified medical technology company, anchors the high-volume peripheral cannula segment, leveraging its extensive distribution network to hospitals and ambulatory centers. Teleflex Incorporated sits within the specialized segment, offering cannulas uniquely designed for anesthesia and regional pain management, catering to specific clinical needs. These companies collectively illustrate varied strategic approaches, from broad market penetration to highly specialized niche offerings that demand specific material science and regulatory expertise.
| Leading Market Players |
|---|
| Medtronic |
| Becton Dickinson |
| Edwards Lifesciences Corporation |
| LivaNova PLC |
| Teleflex Incorporated |
| ICU Medical |
| Terumo Corporation |
| Boston Scientific Corporation |
| CONMED Corporation |
| Others |
Cost & Logistics Intelligence
European Union's Medical Device Regulation (MDR) mandates stricter material biocompatibility standards, forcing manufacturers to invest in advanced materials. This regulatory pressure directly impacts production costs and subsequently influences market pricing strategies.
Pricing Analysis
Input-cost pass-through for medical-grade polyurethane and silicone significantly influences cannula pricing. The market primarily operates on a value-based procurement model, where device performance in reducing complications commands premium pricing. Price differentiation stems from material quality, such as advanced polyurethane, and the level of regulatory compliance. Pricing softness affects high-volume peripheral cannulas, while specialty cannulas for critical care maintain higher margins. Ambulatory surgical centers are more price-sensitive for basic devices, contrasting with hospitals prioritizing outcome-driven solutions.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke models characterize the cannula distribution network, ensuring timely delivery to diverse healthcare facilities. Geographic supply concentration for manufacturing is notable in the United States, Germany, and China. The supply chain relies on key raw materials like medical-grade polyurethane and silicone, along with stainless steel for rigid components. Raw material price volatility represents a significant structural risk for manufacturers. Distribution runs through established networks, particularly for high-volume peripheral cannulas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cannula market functions as a stable compounder, with steady growth driven by global aging demographics and the continuous need for medical procedures. This consistent demand underpins long-term market stability and investment appeal.
For Market Incumbents:Hedge against the escalating regulatory compliance burden by proactively investing in clinical evidence generation for existing product lines. Consolidate peripheral cannula portfolios to streamline certification processes, particularly under the EU's MDR, reducing operational complexity. Leverage extensive distribution networks to maintain market share against new entrants focusing on niche applications. Deepen vertical integration into specialized polymer production to mitigate raw material price volatility.
For New Entrants and Emerging Players:Specialty pediatric care providers represent an underserved buyer archetype, offering a white-space target for innovative, softer silicone cannulas. Focus on niche, high-value applications like cardioplegia or regional anesthesia where premium pricing is sustained. The most penetrable segment lies within emerging economies across Southeast Asia, where healthcare infrastructure is expanding. A go-to-market strategy emphasizing superior patient safety outcomes can differentiate products effectively.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized medical device firms developing next-generation cannulas for critical care and long-term applications. The market demonstrates consistent demand over the next decade, driven by an aging population and increasing procedural volumes. Acquisition targets should include niche specialists possessing strong intellectual property in advanced biocompatible materials or unique clinical application designs. The signal to watch is the accelerated adoption of biodegradable or eco-friendly materials by major hospital systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Biodegradable Polymers | Addresses healthcare sustainability goals and differentiates products in environmentally conscious markets. |
| Expand Specialty Cannula Portfolio | Captures premium pricing in niche applications like cardioplegia and regional anesthesia. |
| Strengthen EU MDR Compliance | Ensures market access and avoids costly delays in a critical regulatory region. |
| Develop Comprehensive Training Programs | Facilitates proper use of complex devices, enhancing patient safety and clinical adoption. |
| Target Emerging Economies | Taps into significant unmet demand as healthcare infrastructure improves in new regions. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Interviews engaged clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers to gather firsthand perspectives. Secondary data sources included FDA filings, EMA submissions, ISO standards documents, and hospital procurement databases. This approach facilitated bottom-up market sizing and top-down validation.
The forecast window was anchored to historical reference periods to establish a consistent baseline for projection. The analytical framework modeled segmentation dimensions including product type, material, application, end-user, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends and projected future demand drivers across the analysis window. Key inputs included anticipated procedural volume growth and material science advancements.
Inputs from regulatory bodies and industry associations were available through the study window; gaps in real-time hospital procurement data introduce uncertainty bands. Forecasts reflect underlying assumptions regarding regulatory changes and raw material supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Video Dermatoscope Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Cranial Implants Treatment Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
Cholecystectomy Devices Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Airway Management Devices Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
UK Artificial Organs and Bionic Implants Market