
 Biological Microscope Market | 2026-2036
Biological Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
Biological Microscope Market Outlook
Pharmaceutical companies are redrawing procurement priorities across the biological microscope landscape, shifting capital toward live cell imaging and high-content screening platforms. Carl Zeiss Microscopy leverages its optical heritage to dominate fluorescence imaging configurations for drug discovery workflows. Nikon Corporation anchors its position through specialized inverted microscope systems designed for long-term cellular observation. Leica Microsystems differentiates via integrated software-hardware ecosystems that streamline pathology digitization.
A biological microscope is an opto-mechanical instrument employing objective lenses with numerical apertures typically ranging from 0.1 to 1.4, coupled with eyepiece or digital camera systems, to magnify cellular and subcellular structures for scientific observation and documentation. Its primary commercial purpose spans diagnostic pathology, academic research, and pharmaceutical quality control where resolution below the diffraction limit determines experimental validity. Compound microscopes retain the largest installed base across research laboratories due to decades of protocol standardization, while digital microscopes capture the fastest expansion as healthcare facilities replace manual slide review with remote pathology consultation. Fluorescence imaging technology commands premium positioning among segments because fluorophore-specific filter sets and laser illumination modules create substantial aftermarket attachment revenue.
FDA medical device regulations govern digital pathology platforms deployed in diagnostic settings, requiring clinical validation studies that extend vendor time-to-market. ISO 10993 biocompatibility standards and IEC 60601 electrical safety frameworks constrain materials selection and instrument design for microscopes operating in clinical environments. Stakeholders must monitor how evolving reimbursement codes for digital pathology in the United States reshape capital allocation between hardware procurement and cloud-based image analysis subscriptions.
Market Dynamics
Pharmaceutical procurement of live cell imaging systems is redrawing competitive positioning across the biological microscope landscape, compressing vendor margins on standard compound configurations while elevating premium fluorescence platforms.
Growth Catalysts
- FDA Digital Pathology Reclassification:Updated medical device classification criteria for diagnostic platforms is expanding addressable market for vendors completing clinical validation studies in the United States.
- High-Content Screening Workflows:Automated image acquisition and analysis pipelines in drug discovery operations are pulling capital toward integrated microscope-software systems.
- German Manufacturing Clusters:Concentrated optical component production around Wetzlar and Jena sustains supply reliability for fluorescence filter sets and precision mechanical stages.
Market Restraints
- Specialized Optics Supply Concentration:German and Japanese suppliers dominate high-numerical-aperture objective lens production, creating single-source vulnerability for super-resolution configurations.
- Clinical Validation Burden:FDA premarket notification requirements for digital pathology platforms extend vendor time-to-market by 18-36 months versus research-use-only instruments.
- Fluorophore Cost Volatility:Rare earth elements in laser illumination modules and specialized filter coatings expose margins to commodity price swings.
Strategic Opportunities
- India Diagnostic Expansion:Central government health infrastructure programs are creating first-time demand for digital microscopy in tier-2 and tier-3 hospital networks.
- Cloud-Enabled Pathology Subscriptions:Reimbursement code evolution for remote diagnostic consultation is opening recurring revenue streams beyond hardware sales.
- AI-Image Analysis Convergence:Integration of machine learning classification algorithms with acquisition hardware creates differentiation in automated screening applications.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Vendors struggle to recruit professionals combining optical engineering, software development, and clinical regulatory expertise.
- Legacy System Integration Friction:Pathology laboratories face workflow disruption when connecting new digital platforms to established laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biological Microscope Market |
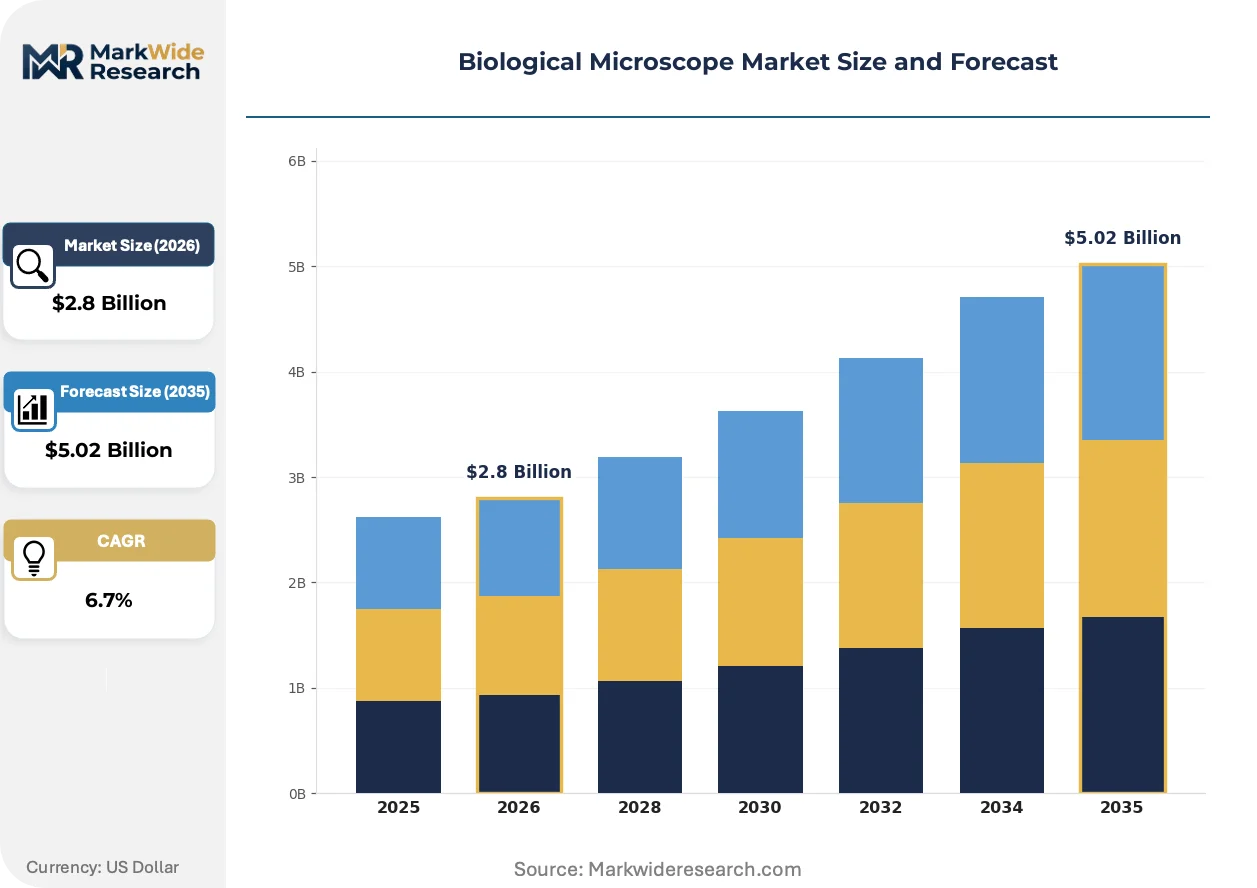
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compound Microscopes, Stereo Microscopes, Digital Microscopes, Inverted Microscopes Application: Cell Biology, Plant Research, Microbial Studies, Pathology End User: Research Laboratories, Educational Institutions, Healthcare Facilities, Pharmaceutical Companies Technology: Fluorescence Imaging, Phase Contrast, Dark Field, Live Cell Imaging |
| Companies Covered | JEOL Ltd., Carl Zeiss Microscopy, Olympus Corporation, Hitachi High-Technologies Corporation, Thermo Fisher Scientific, Nikon Corporation, Leica Microsystems, Evident, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biological Microscope Market Strategic Shifts
Computational imaging methods and regulatory digitization mandates are compressing the traditional divide between hardware performance and software-enabled diagnostic capability.
Super-resolution localization microscopy is fragmenting the high-end research segment as structured illumination and stochastic optical reconstruction techniques displace established confocal systems. Academic core facilities in the United States and Germany are prioritizing multi-modal platforms combining these methods with live cell environmental control. The technology is fragmenting vendor R&D budgets across competing technical approaches rather than consolidating behind single architectures.
EU Medical Device Regulation (MDR) implementation is tightening conformity assessment requirements for in-vitro diagnostic microscopy platforms. Manufacturers must now demonstrate clinical performance through notified body review, extending certification timelines. European pathology device vendors are responding by consolidating quality management systems and accelerating software-as-a-service offerings to reduce hardware recertification frequency.
Service unbundling is altering how research institutions acquire and maintain imaging infrastructure. Core facilities are separating instrument purchase from maintenance contracts and image analysis support, creating procurement complexity. This pattern is most pronounced in United States academic medical centers where shared resource grant structures favor operational expenditure over capital allocation.
Biological Microscope Market Segmentation
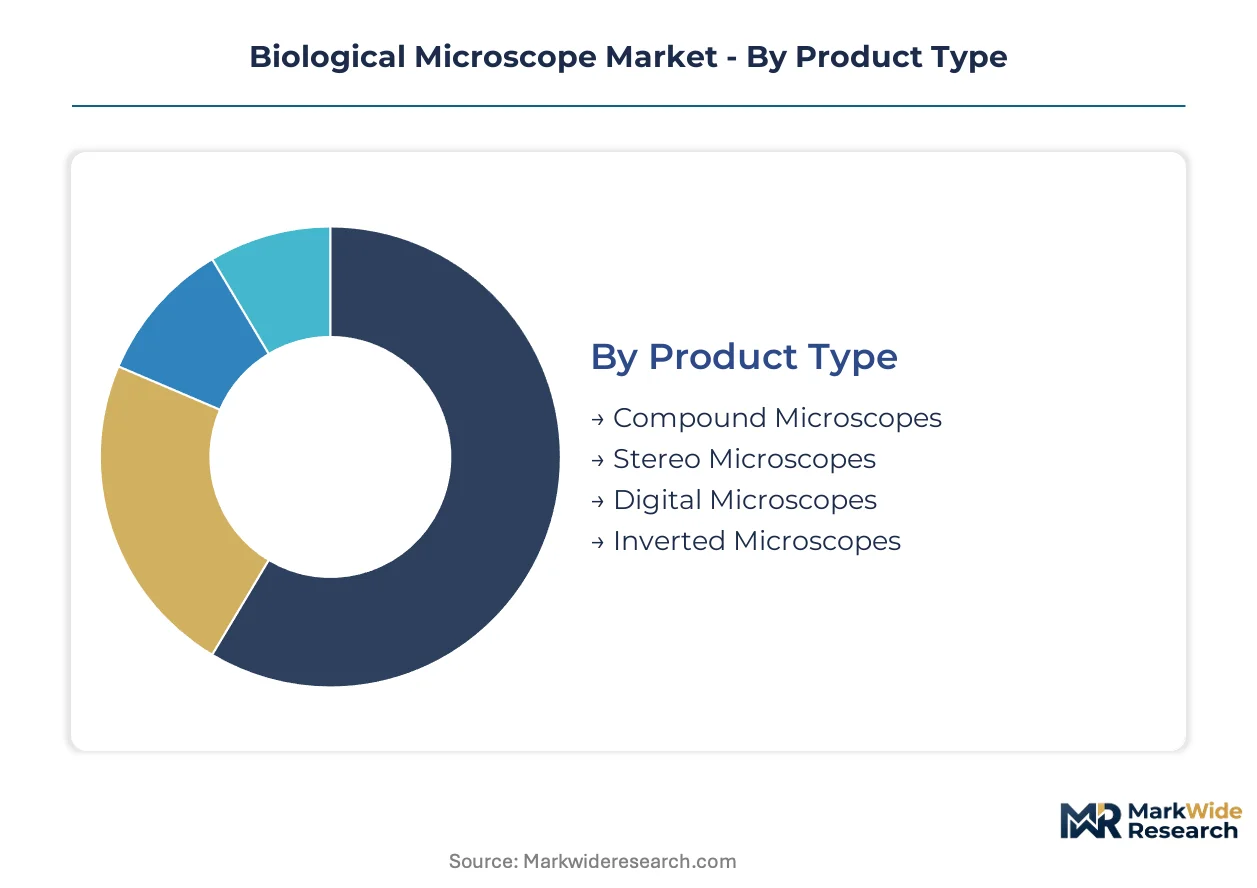
Segmentation in the biological microscope market reveals how capital allocation splits between established diagnostic workflows and emerging research methodologies. Each dimension exposes different pressure points: product types show hardware substitution patterns, applications reveal funding source dependencies, end users display procurement sophistication tiers, and technologies demonstrate where optical innovation commands premium positioning.
Product Type:
Substitution pressure concentrates most intensely on standard compound configurations as laboratories migrate toward integrated digital and live cell platforms that eliminate manual slide handling.
- Compound Microscopes:These instruments employ multiple objective lenses with rotating nosepieces to achieve sequential magnification levels from 40x to 1000x for fixed specimen examination. Pathology laboratories in the United States and Germany retain substantial installed bases due to decades of diagnostic protocol standardization, though replacement cycles are lengthening as facilities defer capital expenditure pending digital pathology reimbursement clarity. Compound configurations anchor the volume base while digital microscopes gain share at the steepest rate.
- Digital Microscopes:Integrated CMOS or CCD sensors replace eyepieces, enabling direct image capture, storage, and network transmission without intermediate optical components. Healthcare facilities in India and tier-2 hospital networks across developing markets are prioritizing these systems for remote consultation capabilities supported by central government infrastructure programs.
- Stereo Microscopes:Lower-magnification binocular systems with dual optical paths provide three-dimensional visualization for dissection and macroscopic specimen manipulation. Educational institutions and industrial quality control operations represent core demand clusters.
- Inverted Microscopes:Objective lenses positioned below the stage permit observation of living cells in culture vessels and multi-well plates. Pharmaceutical drug discovery operations in Germany and the United States drive specialized inverted system procurement with environmental control chambers.
Digital configurations capture procurement momentum as reimbursement frameworks evolve, while compound systems defend installed base through protocol inertia in established diagnostic laboratories.
Application:
Cost tier stratification separates capital-intensive live cell workflows from routine diagnostic screening, with pathology commanding the highest per-instrument expenditure and plant research operating at the lowest specification thresholds.
- Pathology:Diagnostic tissue examination requires high-resolution imaging with standardized color reproduction for clinical decision documentation. FDA medical device classification for digital platforms creates regulatory entry barriers that concentrate vendor participation among established optical manufacturers with clinical validation resources.
- Cell Biology:Subcellular structure visualization demands fluorescence filter sets, laser illumination modules, and environmental control systems for long-term observation. Academic core facilities in Germany and the United States prioritize multi-modal platforms combining super-resolution localization with live cell capabilities.
- Microbial Studies:Bacterial and fungal specimen examination utilizes bright field and phase contrast techniques with oil immersion objectives for high-numerical-aperture resolution. Food safety testing laboratories and environmental monitoring stations constitute steady replacement demand.
- Plant Research:Botanical specimen analysis employs lower-magnification stereomicroscopy and basic compound configurations for tissue section examination. Agricultural research stations and university biology departments operate on constrained equipment budgets with extended replacement cycles.
Pathology applications concentrate revenue per unit through regulatory certification requirements, whereas cell biology drives fluorescence attachment aftermarket sales.
End User:
Procurement sophistication tiers separate pharmaceutical capital expenditure from educational institutional purchasing, with healthcare facilities occupying an intermediate position shaped by reimbursement policy evolution.
- Pharmaceutical Companies:Drug discovery operations demand integrated high-content screening platforms combining automated stage control, multi-channel fluorescence acquisition, and image analysis software. These end users prioritize throughput and data reproducibility over initial capital cost.
- Research Laboratories:Academic and government facilities balance performance specifications against grant funding constraints, with core facility shared resource models favoring multi-user accessible platforms. Service unbundling trends separate instrument purchase from maintenance contracts in United States academic medical centers.
- Healthcare Facilities:Hospital pathology departments face workflow disruption when connecting digital platforms to established laboratory information systems, creating integration friction that slows procurement decisions. Cloud-enabled subscription models are emerging as alternatives to capital-intensive hardware acquisition.
- Educational Institutions:Undergraduate teaching laboratories prioritize durability and simplified operation over optical performance, with stereo microscopes and basic compound systems dominating procurement. Extended replacement cycles characterize this segment due to budget constraints.
Pharmaceutical end users anchor premium segment revenue while healthcare facilities represent the fastest-expanding addressable market as digital pathology reimbursement codes mature.
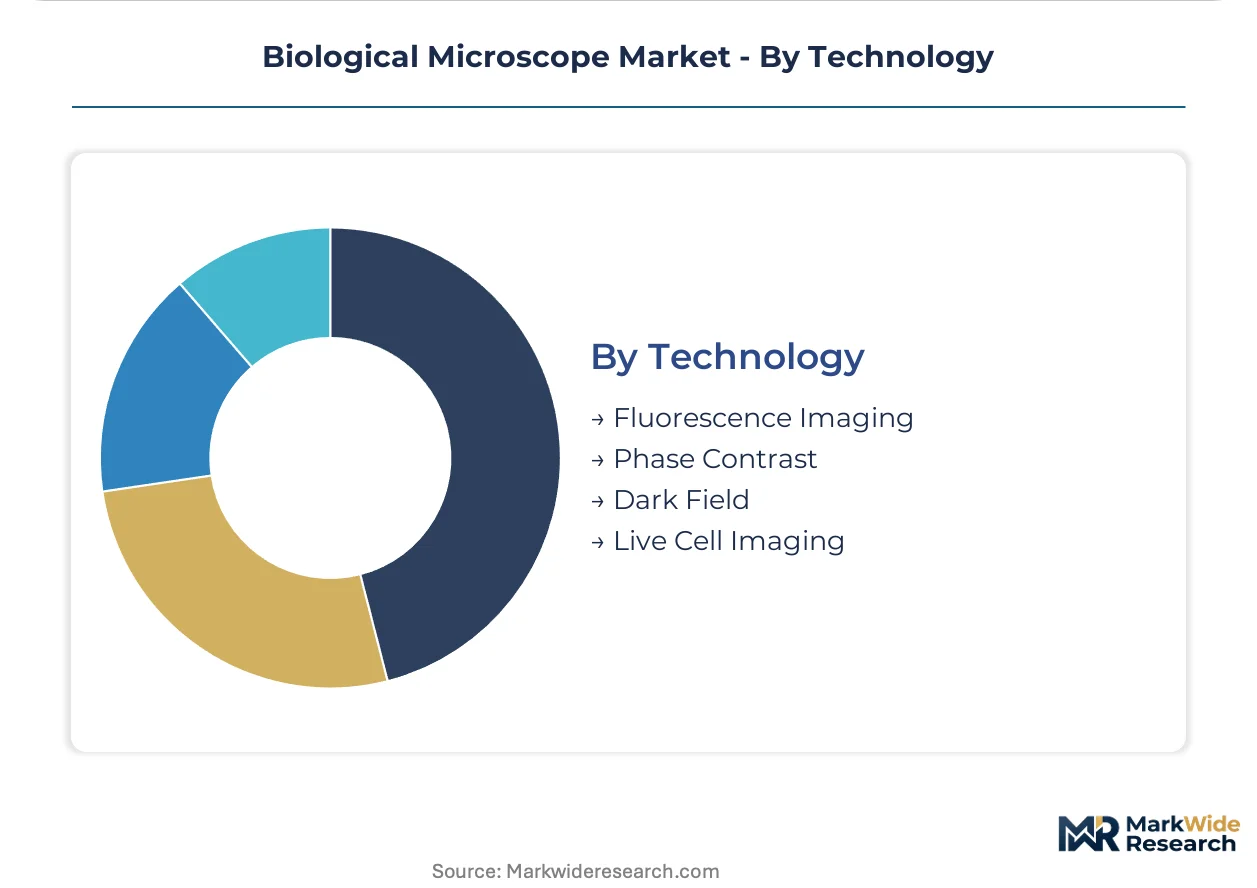
Technology:
Margin concentration follows technology complexity, with fluorescence imaging commanding substantial aftermarket revenue from specialized filter sets and laser modules while basic contrast methods compete on hardware cost.
- Fluorescence Imaging:Specific wavelength excitation and emission filtering enables visualization of labeled cellular structures against dark backgrounds. German optical component manufacturers around Wetzlar and Jena sustain supply reliability for precision filter sets, though rare earth element cost volatility exposes margin pressure.
- Live Cell Imaging:Environmental control chambers maintain temperature, humidity, and gas composition for extended observation of dynamic cellular processes. Pharmaceutical high-content screening workflows pull capital toward these integrated systems.
- Phase Contrast:Optical path manipulation converts refractive index variations into amplitude contrast for transparent specimen visualization without staining. Routine clinical and educational applications favor this cost-effective technique.
- Dark Field:Oblique illumination blocks direct light from entering the objective, scattering from specimen edges to create bright structures against dark backgrounds. Specialized microbiological and hematological applications retain niche demand.
Fluorescence imaging anchors aftermarket revenue through consumable attachment sales, while live cell imaging climbs fastest as pharmaceutical automation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Rhine-Main logistics corridor underwrites Germany's central role in European biological microscope distribution, connecting precision optical manufacturing clusters to research institutions across the continent.
United States
FDA digital pathology reclassification is expanding procurement channels for vendors completing clinical validation studies. The agency's updated medical device classification criteria alter certification requirements for diagnostic platforms. Boston and San Francisco anchor demand concentration where academic medical centers drive live cell imaging adoption.
Germany
EU Medical Device Regulation implementation tightens conformity assessment for in-vitro diagnostic microscopy platforms. Notified body review requirements extend certification timelines for hardware manufacturers. Wetzlar and Jena manufacturing clusters sustain supply reliability for fluorescence filter sets and precision mechanical stages.
Japan
PMDA regulatory frameworks govern diagnostic platform deployment in clinical settings, creating parallel validation requirements to FDA pathways. METI industrial policy supports advanced optical component manufacturing. Tokyo and Osaka metropolitan areas concentrate pharmaceutical research demand for high-content screening systems.
India
Central government health infrastructure programs create first-time demand for digital microscopy in tier-2 and tier-3 hospital networks. CDSCO medical device regulations establish conformity pathways for imported diagnostic platforms. Maharashtra and Karnataka states anchor procurement concentration where public hospital networks upgrade pathology capabilities.
China
NMPA medical device registration requirements extend market entry timelines for foreign digital pathology vendors. National biocompatibility standards constrain materials selection for clinical-grade instruments. Yangtze River Delta manufacturing bases expand domestic production capacity for optical components and CMOS sensors.
Biological Microscope Market Competitive Environment
Listed leaders compete with private specialists across certification capacity, where public company balance sheets absorb extended FDA validation timelines that strain private capital reserves. Market structure concentrates around optical heritage manufacturers with clinical regulatory infrastructure, compressing participation for research-only instrument vendors. Three archetypes dominate: diversified life science conglomerates with microscopy divisions, pure-play optical specialists with century-scale expertise, and analytical instrument vendors extending into imaging. Competitive moves center on strategic partnerships with AI-image analysis software developers and geographic expansion into India's diagnostic infrastructure programs.
Within the heritage optical tier, Carl Zeiss Microscopy and Leica Microsystems exemplify European precision manufacturing archetypes with integrated software-hardware ecosystems. Nikon Corporation represents Japanese specialist positioning in inverted microscope configurations for pharmaceutical workflows. Thermo Fisher Scientific occupies the diversified conglomerate position, leveraging life science distribution scale across research and clinical segments.
| Leading Market Players |
|---|
| JEOL Ltd. |
| Carl Zeiss Microscopy |
| Olympus Corporation |
| Hitachi High-Technologies Corporation |
| Thermo Fisher Scientific |
| Nikon Corporation |
| Leica Microsystems |
| Evident |
| Bruker Corporation |
| Others |
Value Chain & Pricing Dynamics
CMOS sensor substitution for legacy CCD imaging arrays is redrawing component sourcing maps from Japan toward Chinese Yangtze River Delta manufacturing bases while compressing price points for digital microscope configurations. This input transition simultaneously fragments optical supply relationships and intensifies cost competition across mid-tier instrument segments.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical procurement contracts from academic laboratory purchases, with the former commanding 15-25% unit price reductions on high-content screening platforms. Three-tier pricing structure across premium fluorescence, standard compound, and economy educational configurations anchors the market, with FDA certification tier and after-sales service bundling as primary differentiation drivers. Cost compression in standard compound segments is intensifying because Indian and Chinese domestic manufacturers are expanding export capacity. Educational institutions exhibit highest price sensitivity due to grant funding constraints, while pharmaceutical companies prioritize throughput specifications over capital cost.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port complexes influence landed pricing for precision optical components originating outside the European Union. Manufacturing gravity centers on Germany for fluorescence filter sets and precision mechanical stages, Japan for high-numerical-aperture objective lenses, and China for CMOS sensors and electronic subassemblies. Rare earth elements in laser illumination modules and specialized optical coatings create commodity price volatility exposure. Single-source vulnerability concentrates in super-resolution objective production, where German and Japanese suppliers dominate. Distribution runs through authorized dealer networks serving academic core facilities and direct sales teams addressing pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
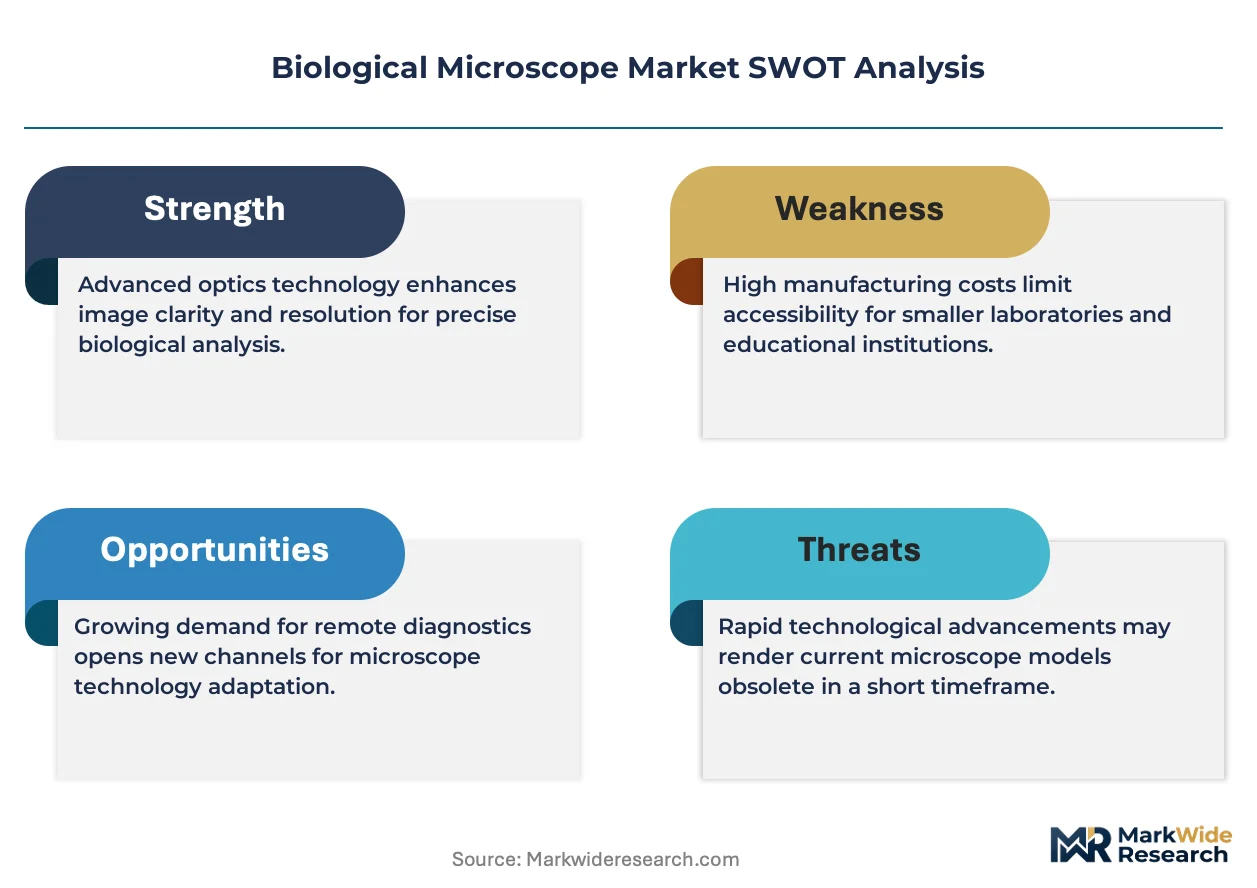
Fragmentation opportunity emerges as digital pathology reimbursement evolution splinters demand between cloud-enabled subscription services and capital-intensive hardware procurement, creating distinct vendor archetypes. Service unbundling in United States academic medical centers accelerates niche formation for specialized maintenance and image analysis providers.
For Market Incumbents: Secure fluorescence filter set supply through captive relationships with Wetzlar and Jena optical component manufacturers, insulating margins from rare earth price volatility. Deepen software-hardware integration to defend against modular competitors unbundling instrument purchase from analysis subscriptions. FDA premarket notification timelines favor incumbents with established clinical validation infrastructure over emerging entrants lacking regulatory resources. For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 hospital networks where central government health infrastructure programs create first-time digital microscopy demand with limited incumbent penetration. Target cloud-enabled pathology subscriptions as the most penetrable segment, bypassing capital-intensive hardware certification barriers. Pursue partnerships with AI-image analysis software developers to differentiate automated screening offerings without proprietary R&D investment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified life science conglomerates with microscopy divisions over pure-play optical specialists. Long-term viability over the next decade hinges on regulatory certification capacity and software ecosystem integration rather than optical heritage alone. Acquisition target archetype: mid-scale fluorescence imaging specialists with FDA 510(k) clearances and established pharmaceutical customer relationships. Signal to watch: CDSCO and NMPA regulatory pathway acceleration for foreign digital pathology vendors as inflection indicator for geographic expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Image Analysis Partnership | Machine learning classification integration with Carl Zeiss and Leica hardware creates automated screening differentiation. |
| India Distribution Expansion | Maharashtra and Karnataka public hospital network procurement opens first-time digital pathology access. |
| FDA Clinical Validation Investment | Premarket notification completion expands diagnostic platform addressable market versus research-use-only instruments. |
| Cloud-Enabled Subscription Launch | Reimbursement code evolution for remote consultation creates recurring revenue beyond capital hardware sales. |
| German Manufacturing Cluster Consolidation | Wetzlar and Jena precision optical production integration secures fluorescence filter set supply reliability. |
Study Parameters
Desk research of FDA 510(k) filings, EU MDR notified body documentation, and pharmaceutical company capital expenditure disclosures preceded structured interviews with pathology laboratory directors, biomedical equipment procurement managers, fluorescence imaging core facility managers, and regulatory affairs specialists at optical manufacturers. Secondary validation drew from CDSCO medical device registration databases, hospital procurement records, and academic shared resource grant structures. Bottom-up instrument shipment analysis triangulated against top-down pharmaceutical R&D expenditure allocation to microscopy platforms.
Variance decomposition across product type, application, end user, and technology segments structured the analytical framework over the projection horizon. Modeled dimensions included fluorescence versus bright field imaging modality, live cell environmental control capability, and digital pathology versus research-only regulatory classification. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated FDA digital pathology reimbursement code evolution pace and EU MDR implementation timeline for in-vitro diagnostic microscopy platforms.
Material uncertainties — reimbursement policy reversals, rare earth supply disruptions, and super-resolution technology obsolescence — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and pharmaceutical capital expenditure continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Dosing Units Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
EMG Biosensors Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Ocular Implants Market
Medical Devices
Subdural Electrodes Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Plethysmograph Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Anti-Snore Device Market