
 Spinal Laminoplasty Market | 2026-2036
Spinal Laminoplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Laminoplasty Market Outlook
Titanium alloy is repositioning traditional stainless steel in spinal laminoplasty plates and spacers, reducing implant weight and improving postoperative imaging clarity. Medtronic leverages its integrated spinal navigation platforms to anchor premium positioning in cervical decompression procedures. Zimmer Biomet competes through specialized plating systems designed for open-door and French-door techniques. Globus Medical differentiates via expandable laminoplasty devices that accommodate variable canal expansion.
Spinal laminoplasty is a posterior cervical decompression technique involving partial elevation and stabilization of the lamina to enlarge the spinal canal without fusion, typically using titanium miniplates, spacers, or suture anchors to maintain the expanded arch. The procedure preserves segmental motion while relieving cord compression from stenosis, ossification of the posterior longitudinal ligament, or tumor infiltration. Minimally invasive laminoplasty is gaining traction fastest among product types as surgeons pursue reduced paraspinal muscle dissection and shorter recovery profiles. Metal implants still dominate material revenue due to established biomechanical data and reimbursement familiarity, though biodegradable polymers are attracting development investment for younger patient cohorts.
The US FDA governs spinal implant premarket notifications under 510(k) and PMA pathways, while Japan's PMDA maintains distinct technical standards for cervical plating systems that influence design requirements for Asia-Pacific market access. The EU Medical Device Regulation mandates clinical evidence and notified body involvement for Class III spinal devices, extending approval timelines relative to prior directives. Stakeholders must monitor evolving health technology assessment criteria across major markets, as payer evidence requirements increasingly determine commercial traction regardless of regulatory clearance status.
Market Dynamics
The spinal laminoplasty market pivots on titanium alloy substitution for stainless steel implants, as surgeons demand lighter hardware and artifact-free postoperative MRI clarity. This materials transition compresses procurement cycles while elevating technical validation burdens for plating system manufacturers.
Growth Catalysts
- Aging Demographics in Japan:The world's oldest population sustains procedural volume for cervical decompression, with established open-door laminoplasty techniques embedded in standard surgical training curricula.
- FDA 510(k) Streamlining:Expedited premarket notification pathways for spinal implants accelerate commercialization timelines for novel plate and spacer designs in the United States.
- Minimally Invasive Technique Adoption:Reduced paraspinal muscle dissection protocols shorten hospital stays and expand addressable patient pools beyond traditional surgical candidates.
Market Restraints
- Titanium Price Volatility:Raw material cost fluctuations for aerospace-grade alloys compress implant margins and complicate long-term supply agreements with foundries.
- Biomechanical Validation Burden:Extensive fatigue testing requirements for cervical plating systems extend development timelines before regulatory submission.
- Fusion Surgery Substitution:Anterior cervical discectomy and fusion procedures compete for overlapping stenosis indications, particularly in single-level presentations.
Strategic Opportunities
- Expandable Device Platforms:Variable canal expansion mechanisms accommodate diverse patient anatomy without custom plate inventory, reducing hospital sterilization costs.
- Biodegradable Polymer Development:Resorbable implants for younger OPLL patients eliminate permanent foreign body retention and enable future revision flexibility.
- Navigation System Integration:Robotic guidance and intraoperative imaging convergence create premium positioning for laminoplasty-specific instrument kits.
Industry Challenges
- Specialized Surgeon Training:Open-door and French-door technique proficiency requires dedicated fellowship exposure, limiting addressable surgeon pools in secondary markets.
- Reimbursement Code Fragmentation:Variable CPT and DRG classifications across payers create prior authorization friction and payment uncertainty for hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Laminoplasty Market |
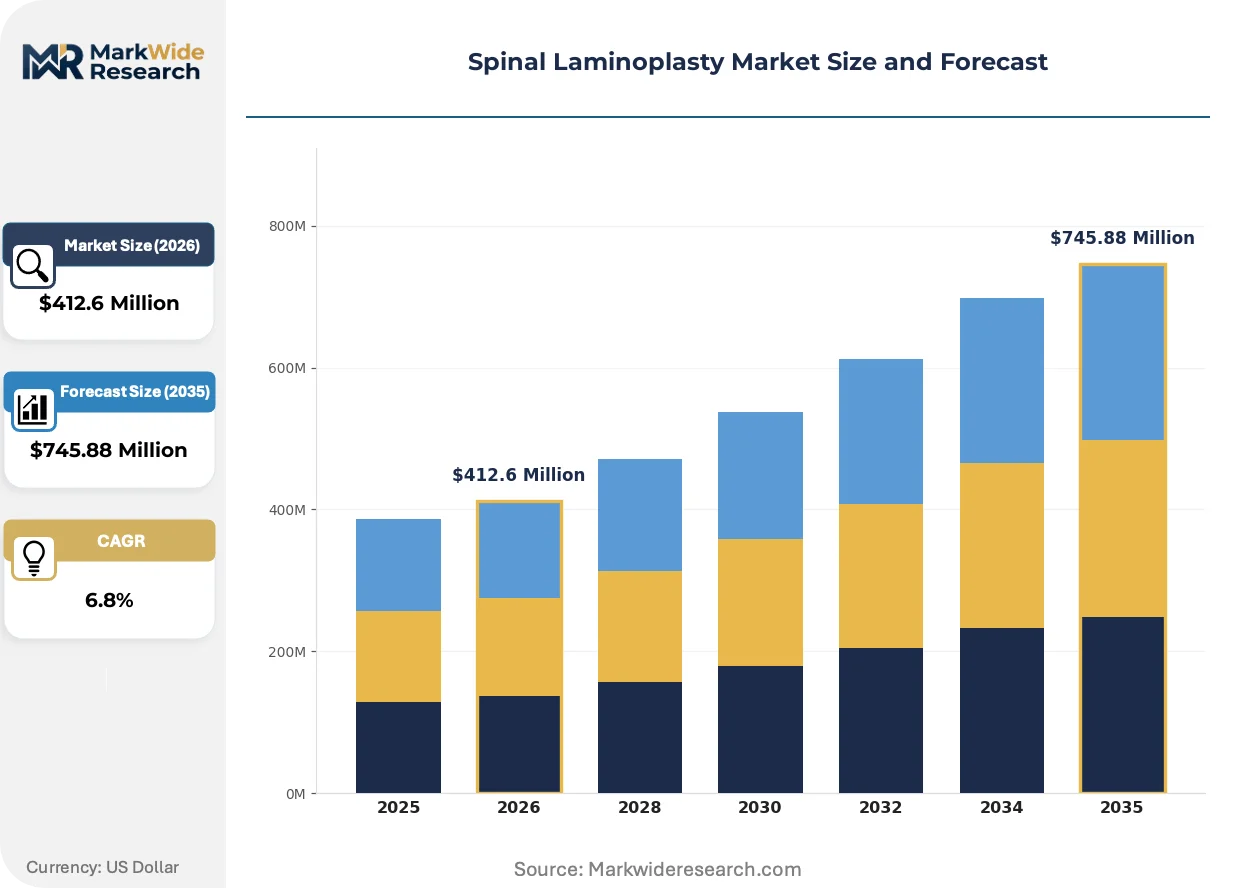
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Laminoplasty, Minimally Invasive Laminoplasty, Hybrid Laminoplasty, Expandable Laminoplasty End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Material: Metal, Biodegradable Polymers, Composite Materials, Ceramics Application: Spinal Stenosis, Degenerative Disc Disease, Trauma, Tumors |
| Companies Covered | DePuy Synthes, Zimmer Biomet, Medtronic, NuVasive, Globus Medical, Stryker, Pioneer Surgical Technologies, Orthofix, Aesculap Implant Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Laminoplasty Market Strategic Shifts
Digital surgical planning and patient-specific implant contouring are compressing the gap between diagnostic imaging and operative execution. These capabilities reshape how hospitals evaluate capital equipment partnerships.
Expandable laminoplasty devices with incremental height adjustment are unifying the previously separate plate and spacer categories into integrated systems. Academic medical centers in Japan and the United States are piloting these platforms for multilevel stenosis cases. The technology is unifying procurement decisions around single-vendor ecosystems rather than component sourcing.
The EU Medical Device Regulation's Class III clinical evidence requirements are extending approval timelines for cervical plating systems relative to the prior Medical Device Directive framework. Notified body capacity constraints in Germany and the Netherlands create submission backlogs. Manufacturers are responding by front-loading clinical data collection in Japanese and US sites to support parallel EU dossiers.
Hospital procurement committees are consolidating vendor relationships around integrated spinal navigation and implant platforms, displacing standalone laminoplasty product sourcing. Group purchasing organizations favor bundled contracts covering decompression instruments, plates, and intraoperative imaging. This concentration is most visible in North American health systems pursuing standardized supply chains across regional hospital networks.
Spinal Laminoplasty Market Segmentation
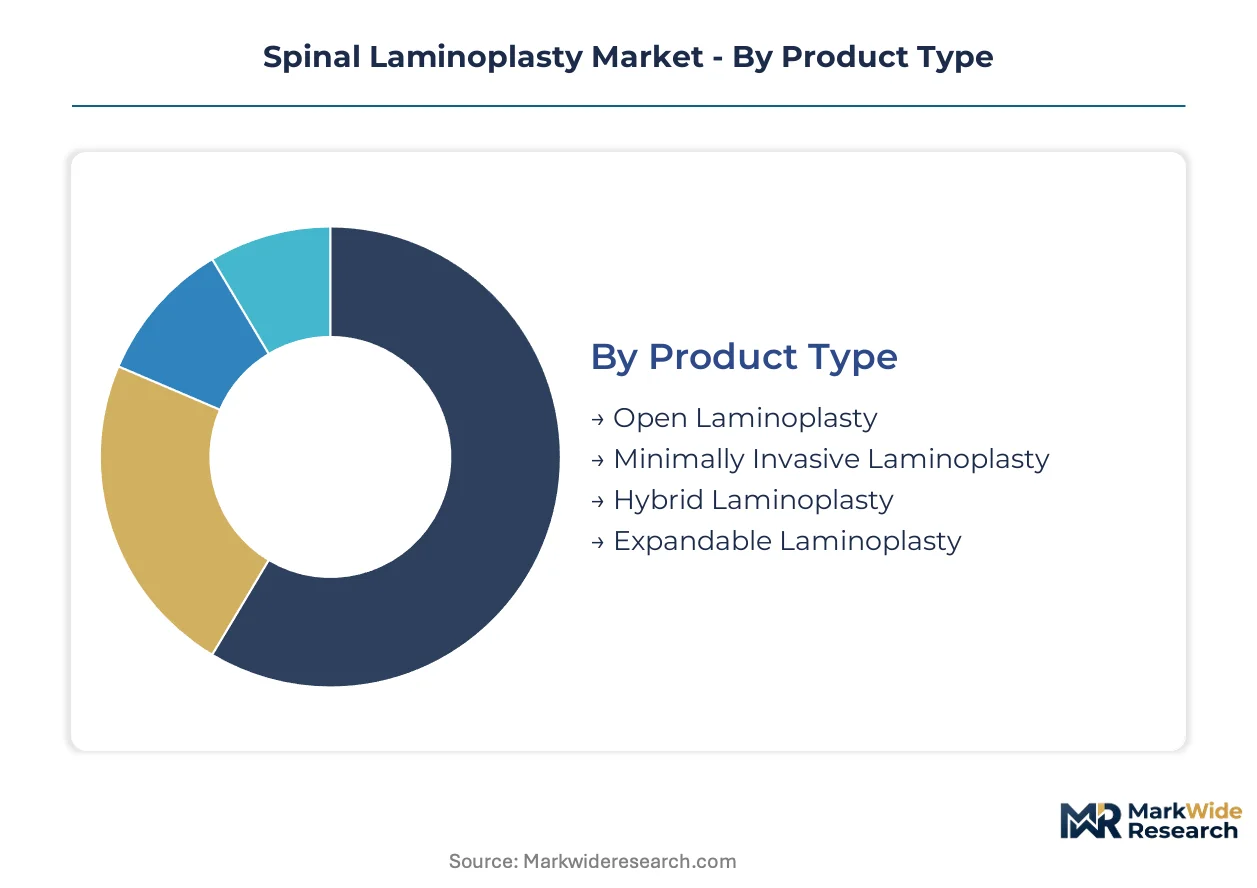
Spinal laminoplasty segmentation reveals distinct procurement patterns across surgical settings and implant specifications. Hospital systems evaluate product categories through distinct lenses: operative invasiveness, material biocompatibility, and reimbursement alignment.
Product Type:
Customization intensity varies sharply across this category, from standardized open techniques to patient-adaptive expandable systems.
- Open Laminoplasty:The conventional approach elevates and stabilizes the lamina using titanium miniplates or suture anchors. Japanese surgical training curricula embed this technique deeply, sustaining procedural volume in academic medical centers.
- Minimally Invasive Laminoplasty:Reduced paraspinal muscle dissection protocols shorten hospital stays and attract outpatient migration. Ambulatory surgical centers in the United States are expanding capacity for these procedures.
- Hybrid Laminoplasty:Combines elements of open and limited-access approaches for multilevel pathology. Hybrid configurations address anatomical complexity without full exposure.
- Expandable Laminoplasty:Integrated height-adjustment mechanisms unify plate and spacer functions. Variable canal expansion reduces custom inventory requirements for hospital sterilization departments.
Most installed capacity flows through open laminoplasty. Expansion is steepest in minimally invasive laminoplasty.
End User:
Volume concentration tilts toward inpatient facilities, though site-of-service economics are redistributing cases toward lower-acuity settings.
- Hospitals:Academic medical centers and community hospitals dominate complex multilevel procedures. Operating room block scheduling and bundled payment contracts anchor procurement decisions.
- Ambulatory Surgical Centers:Medicare reimbursement expansion for cervical decompression in ASC settings is accelerating capital investment. Specialized ASC chains are negotiating direct implant sourcing agreements.
- Orthopedic Clinics:Limited to diagnostic workup and postoperative monitoring. Clinic-based surgeons refer operative cases to affiliated hospital systems.
- Rehabilitation Centers:Postoperative recovery and neuromuscular retraining. Length-of-stay compression in hospitals shifts rehabilitation burden to skilled nursing and outpatient facilities.
Case complexity concentrates in hospitals. Volume growth is climbing fastest in ambulatory surgical centers.
Material:
Supply chain maturity separates established metal foundries from developmental polymer chemistry operations.
- Metal:Titanium alloys are displacing stainless steel in cervical plating systems. Aerospace-grade titanium supply agreements with Japanese and US foundries determine implant cost structures.
- Biodegradable Polymers:Resorbable implants for younger OPLL cohorts eliminate permanent foreign body retention. PMDA and FDA biocompatibility pathways require extended degradation profile validation.
- Composite Materials:Carbon fiber reinforced polymers offer radiolucency and modulus matching. Limited fatigue data restricts application to investigational settings.
- Ceramics:Bioinert oxide ceramics resist wear in high-motion segments. Brittleness concerns limit deployment to static stabilization roles.
Revenue concentration sits with metal implants. Biodegradable polymers are gaining share fastest.
Application:
Indication severity drives implant selection from standardized plates to expandable reconstruction systems.
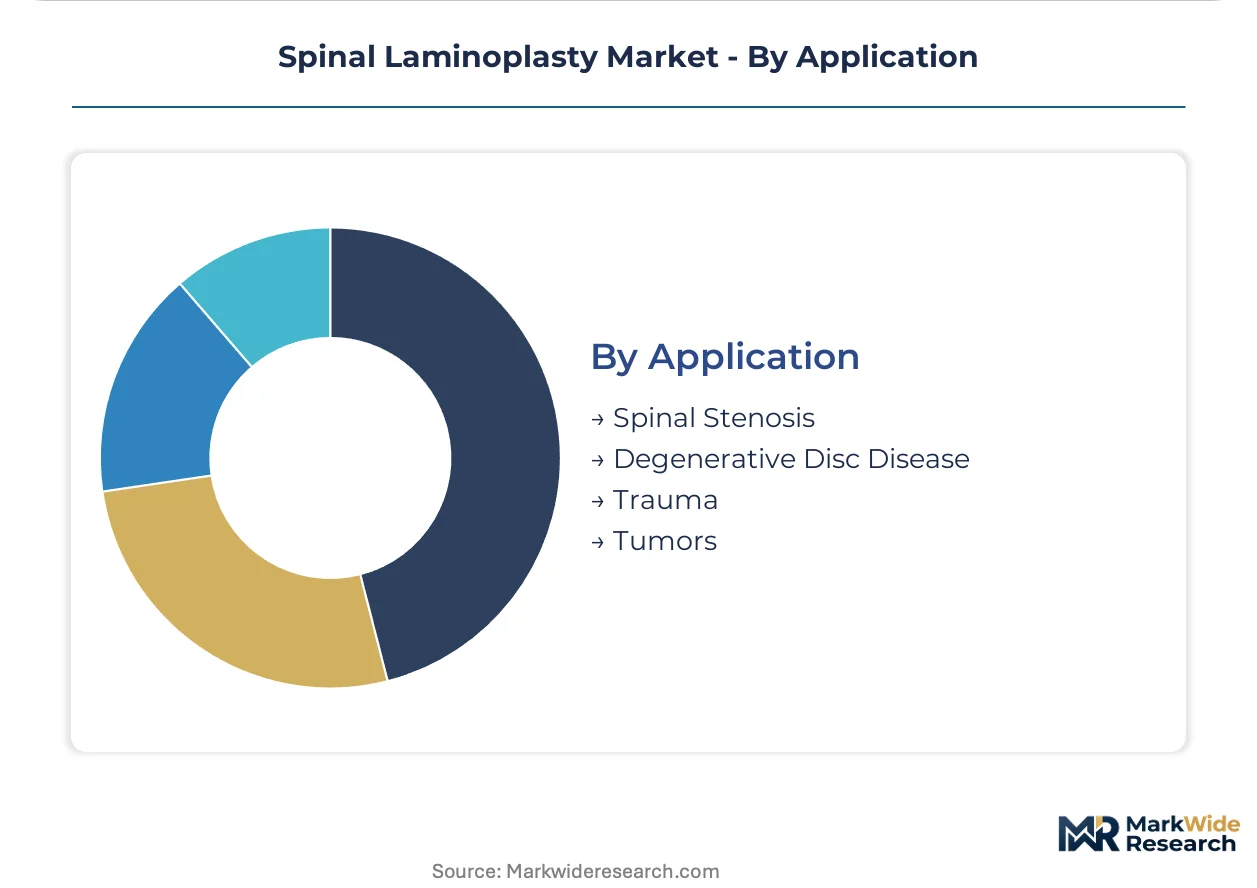
- Spinal Stenosis:Degenerative canal narrowing from ligamentum flavum hypertrophy or facet arthropathy. Multilevel presentations favor laminoplasty over fusion to preserve motion.
- Degenerative Disc Disease:Anterior pathology typically drives discectomy and fusion. Laminoplasty addresses posterior element compromise in select cases.
- Trauma:Fracture-dislocation with posterior arch instability requires decompression and stabilization. Trauma applications demand rapid implant availability.
- Tumors:Metastatic infiltration or primary spinal neoplasms requiring palliative decompression. Tumor cases often combine laminoplasty with adjuvant radiation planning.
Procedure volume clusters in spinal stenosis. Tumor applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Kanto region houses the highest concentration of cervical laminoplasty procedures worldwide, anchored by Tokyo's academic medical centers where open-door techniques remain embedded in surgical training curricula. The United States, Germany, China, and South Korea constitute the remaining core markets where titanium implant adoption and minimally invasive technique diffusion are reshaping procedural economics.
Japan
Aging demographics and ossification of the posterior longitudinal ligament sustain procedural volumes unmatched elsewhere. PMDA technical standards for cervical plating systems influence design requirements across Asia-Pacific market access strategies. Tokyo's Keio University Hospital and Osaka University Medical Hospital pilot expandable device platforms for multilevel stenosis cases.
United States
Medicare reimbursement expansion for cervical decompression in ambulatory surgical centers accelerates site-of-service migration. FDA 510(k) clearance pathways streamline premarket notification timelines for novel plate and spacer designs. Rochester, Minnesota and Cleveland, Ohio anchor hospital system procurement consolidation around integrated spinal navigation platforms.
Germany
EU Medical Device Regulation Class III clinical evidence requirements extend approval timelines for cervical plating systems relative to prior directives. Notified body capacity constraints in Germany and the Netherlands create submission backlogs. Munich and Berlin academic centers front-load clinical data collection to support parallel EU dossiers.
China
NMPA biocompatibility pathways for titanium alloys require extended fatigue testing validation before domestic market authorization. Aerospace-grade titanium supply agreements with state-owned foundries determine implant cost structures. Beijing and Shanghai municipal health commissions pilot bundled payment contracts for spinal decompression procedures.
South Korea
MFDS streamlined review pathways for predicate-based spinal implants accelerate commercialization timelines relative to full technical dossier submissions. Seoul National University Hospital and Asan Medical Center maintain high-volume cervical decompression centers. Busan-Ulsan manufacturing clusters supply precision-machined titanium components to regional plating system assemblers.
Spinal Laminoplasty Market Competitive Environment
Global majors compete with regional champions across integrated navigation and implant platform bundling. The vendor base concentrates around diversified orthopedic conglomerates with captive spinal divisions, while specialized laminoplasty-focused manufacturers occupy niche positioning in expandable device categories. Three archetypes dominate: full-line spinal platform vendors, cervical-focused plating specialists, and navigation-integrated system providers. M&A activity targets expandable device technology acquisitions, while strategic partnerships between implant manufacturers and robotic guidance developers reshape competitive boundaries.
Within the full-line spinal platform tier, Medtronic, Zimmer Biomet, and Globus Medical exemplify divergent strategic positioning. Medtronic occupies a position anchored by integrated spinal navigation ecosystems. Zimmer Biomet represents specialized plating system development across open-door and French-door technique configurations. Globus Medical sits within the expandable device innovation vector, accommodating variable canal expansion mechanisms that reduce hospital sterilization inventory burdens.
| Leading Market Players |
|---|
| DePuy Synthes |
| Zimmer Biomet |
| Medtronic |
| NuVasive |
| Globus Medical |
| Stryker |
| Pioneer Surgical Technologies |
| Orthofix |
| Aesculap Implant Systems |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement consolidation around integrated spinal navigation platforms is compressing standalone implant margins and forcing manufacturers to bundle hardware with software ecosystems, elevating total cost of ownership while reducing per-component pricing transparency. This buyer-side concentration reshapes supplier economics toward long-term service contracts and away from transactional plate and spacer sales.
Pricing Analysis
Aerospace-grade titanium spot pricing pass-through dominates implant cost structures, with Japanese and US foundry contracts resetting quarterly. Price differentiation hinges on FDA 510(k) clearance tier and volume scale through group purchasing organizations. Cost compression in standard plating systems intensifies as ASC chains negotiate direct sourcing agreements. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers prioritize navigation integration over unit cost.
Supply Chain Analysis
Freight cost volatility from precision-machined titanium component shipments between Busan-Ulsan manufacturing clusters and North American distribution centers elevates landed cost uncertainty. Supply concentrates in Japan, the United States, and South Korea for finished plating systems. Raw material dependencies include aerospace-grade titanium alloys, cobalt-chrome substrates, and biocompatible polymer feedstocks. Single-source vulnerability persists in Japanese PMDA-certified forging facilities. Distribution runs through orthopedic distributor networks and direct hospital contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spinal laminoplasty market functions as a stable compounder anchored by irreversible demographic aging in Japan and sustained Medicare reimbursement expansion for cervical decompression procedures.
For Market Incumbents: Deploy navigation-integrated platform bundling to lock hospital system procurement committees into captive ecosystems. Acquire expandable device specialists to neutralize French-door technique commoditization. Counter anterior cervical discectomy and fusion substitution threats by embedding laminoplasty-specific CPT coding advocacy within professional society relationships. For New Entrants and Emerging Players: Ambulatory surgical center chains represent the most penetrable buyer archetype, as Medicare site-of-service expansion creates capacity-constrained demand for streamlined implant sourcing. Target biodegradable polymer development for younger OPLL cohorts seeking revision flexibility. Pursue direct contracting models that bypass incumbent distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with expandable laminoplasty device platforms that unify plate and spacer categories into single-inventory solutions. Long-term viability rests on FDA 510(k) pathway expertise and Japanese PMDA technical standard navigation. Monitor MFDS streamlined review pathway utilization rates as inflection indicators for Asia-Pacific market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Expandable Device Platform Development | Variable canal expansion reduces hospital sterilization inventory burdens and procurement complexity. |
| Navigation System Integration Partnership | Robotic guidance convergence creates premium positioning for laminoplasty-specific instrument kits. |
| Biodegradable Polymer FDA Submission | Resorbable implants for younger OPLL patients eliminate permanent foreign body retention risks. |
| ASC Direct Contracting Channel | Medicare reimbursement expansion enables capital investment bypassing traditional distributor networks. |
| Japanese PMDA Technical Dossier Investment | Asia-Pacific market access requires distinct design validation beyond FDA 510(k) clearance pathways. |
Study Parameters
Multiple input streams — primary interviews with spine surgeons, hospital purchasing committee members, and biomedical engineers; secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and Japanese PMDA approval records; plus GPO contract analysis — were reconciled through bottom-up procedure volume modeling and top-down implant revenue triangulation.
Data-stream reconciliation across product type, material composition, end-user facility tier, and application indication generated segment-level projections over the analysis window. CAGRs were derived from installed base growth, replacement cycle dynamics, and technique diffusion curves. Procedure migration from inpatient to ambulatory settings and titanium alloy substitution rates served as key forecast inputs.
Underlying measurement precision varies by segment; metal implant revenue estimates carry tighter precision than biodegradable polymer development-stage projections. Forecasts reflect assumptions regarding FDA 510(k) clearance timelines, PMDA technical standard stability, and Medicare ASC reimbursement durability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Chile Neurology Devices Market
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
Aneurysmal Subarachnoid Hemorrhage Market
Neurology
China Neurology Devices Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
Mexico Neurology Devices Market
Neurology
Moyamoya Disease Market
Neurology
Neurology Software Market
Neurology
Intracranial Aneurysm Market
Neurology
Cognitive Neuroscience Market
Neurology
Grand Mal Seizure Treatment Market
Neurology
Neurological Biomarkers Market
Neurology
Amnestic Disorders Therapeutics Market
Neurology
AIDS Related Primary CNS Lymphoma Market
Neurology
Diabetic Neuropathy Market