
 Smart Lenses Market | 2026-2036
Smart Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Lenses Market Insights
Shortages of micro-optics engineers and MEMS fabrication specialists are redrawing competitive boundaries in smart lens development. Mojo Vision sustains leadership through vertical integration of its AR display architecture, while Samsung leverages semiconductor process expertise to anchor wireless charging subsystems. Sensimed AG differentiates through proprietary sensor calibration protocols for medical-grade intraocular pressure tracking.
Smart lenses integrate electronic components, photonic structures, and biocompatible polymers into wearable vision platforms capable of real-time physiological monitoring, augmented reality overlay, and autonomous refractive adjustment. Manufacturing requires sub-micron precision in depositing transparent conductive oxides onto hydrogel substrates, with yield rates heavily dependent on cleanroom particle control below ISO Class 5 standards. Photochromic and multifocal product types occupy established margin pools in prescription eyewear, while AR integration technology segments command premium positioning as gaming and military applications expand. Embedded sensors for medical use applications lead volume adoption through reimbursement pathways in regulated healthcare systems.
FDA breakthrough device pathways and EU MDR Class IIa certification requirements shape product development timelines and clinical evidence burdens for entrants. Japan's METI coordinates domestic standards alignment with IEC 60601 electrical safety benchmarks for ocular devices. Stakeholders must monitor evolving cybersecurity frameworks for wireless-enabled medical wearables as regulatory scope expands beyond biocompatibility into data governance and connectivity risk management.
Market Dynamics
Cleanroom particle control below ISO Class 5 standards is compressing yield rates for transparent conductive oxide deposition onto hydrogel substrates, concentrating production capability among semiconductor-grade fabrication facilities.
Growth Catalysts
- FDA Breakthrough Device Designations:Accelerated clinical trial timelines in the United States compress regulatory pathways for AR-integrated vision correction platforms, reducing time-to-market for novel optical architectures.
- METI-Funded Consortia:Japan's precision manufacturing clusters advance smart display miniaturization through coordinated R&D investment, anchoring consumer eyewear supply chains in domestic production networks.
- Intraocular Pressure Monitoring:Ophthalmology clinics in Germany expand adoption of sensor-embedded contact lenses, creating reimbursement-validated demand for medical-grade physiological tracking.
Market Restraints
- MEMS Fabrication Concentration:Shortages of micro-optics engineers and MEMS specialists limit production scaling, with talent pools concentrated in Taiwan and South Korea fabrication corridors.
- EU MDR Class IIa Certification Burden:Clinical evidence requirements for ocular devices extend development timelines and inflate regulatory compliance costs for European market entry.
- Wireless Charging Subsystem Cost Volatility:Semiconductor process inputs for inductive power transfer modules face pricing pressure from competing electric vehicle battery management chip demand.
Strategic Opportunities
- India's PLI Scheme for Wearable Electronics:Production-linked incentives for domestic manufacturing of electronic components create tariff-advantaged assembly capacity for export-oriented smart lens producers.
- Convergence of Photonic Structures and Biocompatible Polymers:Hybrid material platforms enable simultaneous refractive correction and real-time glucose monitoring, opening metabolic health applications beyond ophthalmology.
- Direct-to-Consumer Telehealth Channels:Remote prescription verification and virtual fitting workflows bypass traditional optical retail distribution, capturing margin from disintermediated lens dispensing.
Industry Challenges
- Sub-Micron Deposition Talent Scarcity:Cleanroom technicians capable of maintaining ISO Class 5 environments during transparent conductive oxide processing command premium wages, constraining workforce scaling.
- Cybersecurity Framework Compliance:Evolving wireless-enabled medical wearable standards expand regulatory scope beyond biocompatibility into data governance, requiring dedicated connectivity risk management infrastructure.
- Sensor Calibration Protocol Standardization:Proprietary medical-grade intraocular pressure tracking algorithms resist interoperability, fragmenting clinical data ecosystems and complicating multi-vendor hospital procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Lenses Market |
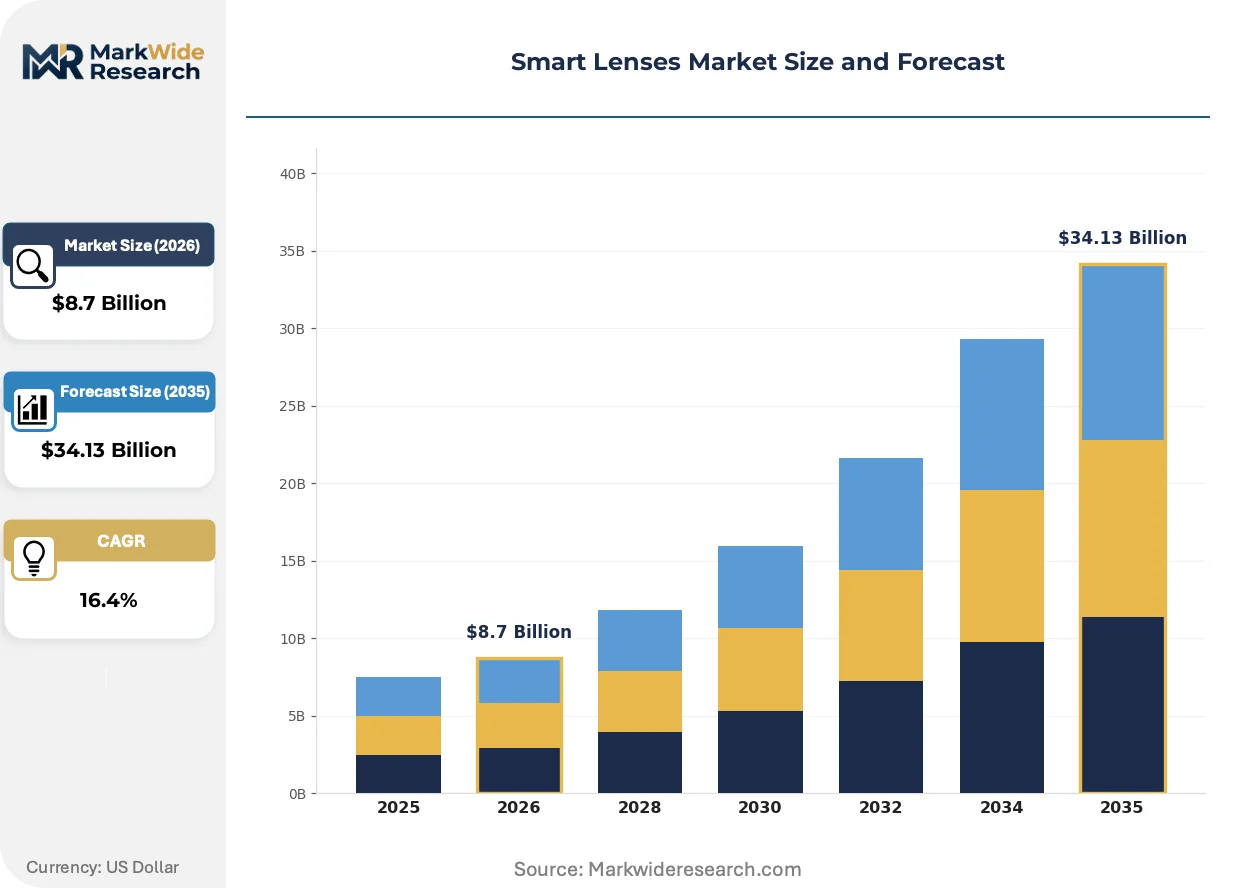
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustable Focus, Photochromic, Multifocal, Prescription Technology: AR Integration, Embedded Sensors, Wireless Charging, Smart Display Application: Medical Use, Gaming, Eyewear, Military End User: Consumers, Healthcare Professionals, Gaming Enthusiasts, Military Personnel |
| Companies Covered | Mojo Vision Inc., Innovega, Sensimed AG, Smartlens, Inc., Azalea Vision, SEED Co., Ltd., InWith Corp, XPANCEO, Samsung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Lenses Market Trends and Innovations
AR display architectures are fragmenting into modular component layers, enabling specialized suppliers to capture value from previously integrated optical systems while compressing development cycles for application-specific configurations.
Transparent conductive oxide deposition is decomposing monolithic electrode structures into patterned nanowire meshes, improving optical clarity while maintaining electrical conductivity. Military simulation trainers and gaming peripheral manufacturers are adopting these architectures at twelve-month refresh cycles. The technology is decomposing traditional indium tin oxide supply relationships, forcing materials vendors to qualify alternative silver nanowire and graphene formulations.
Japan's METI coordinates domestic standards alignment with IEC 60601 electrical safety benchmarks for ocular devices, preempting technical barriers to export market access. Japanese lens manufacturers are pre-certifying products against harmonized electromagnetic compatibility requirements, reducing duplicate testing burdens for FDA and PMDA submissions. Consumer eyewear segments with integrated biosensors face the steepest compliance cost inflation under this framework.
Hospital procurement committees are consolidating vendor relationships for connected medical devices, favoring suppliers offering integrated data governance and cybersecurity management. This concentration is displacing standalone sensor lens vendors who lack enterprise IT infrastructure partnerships. Germany's university hospital networks exhibit the most aggressive procurement consolidation, bundling intraocular pressure monitoring with electronic health record system contracts.
Smart Lenses Market Segmentation
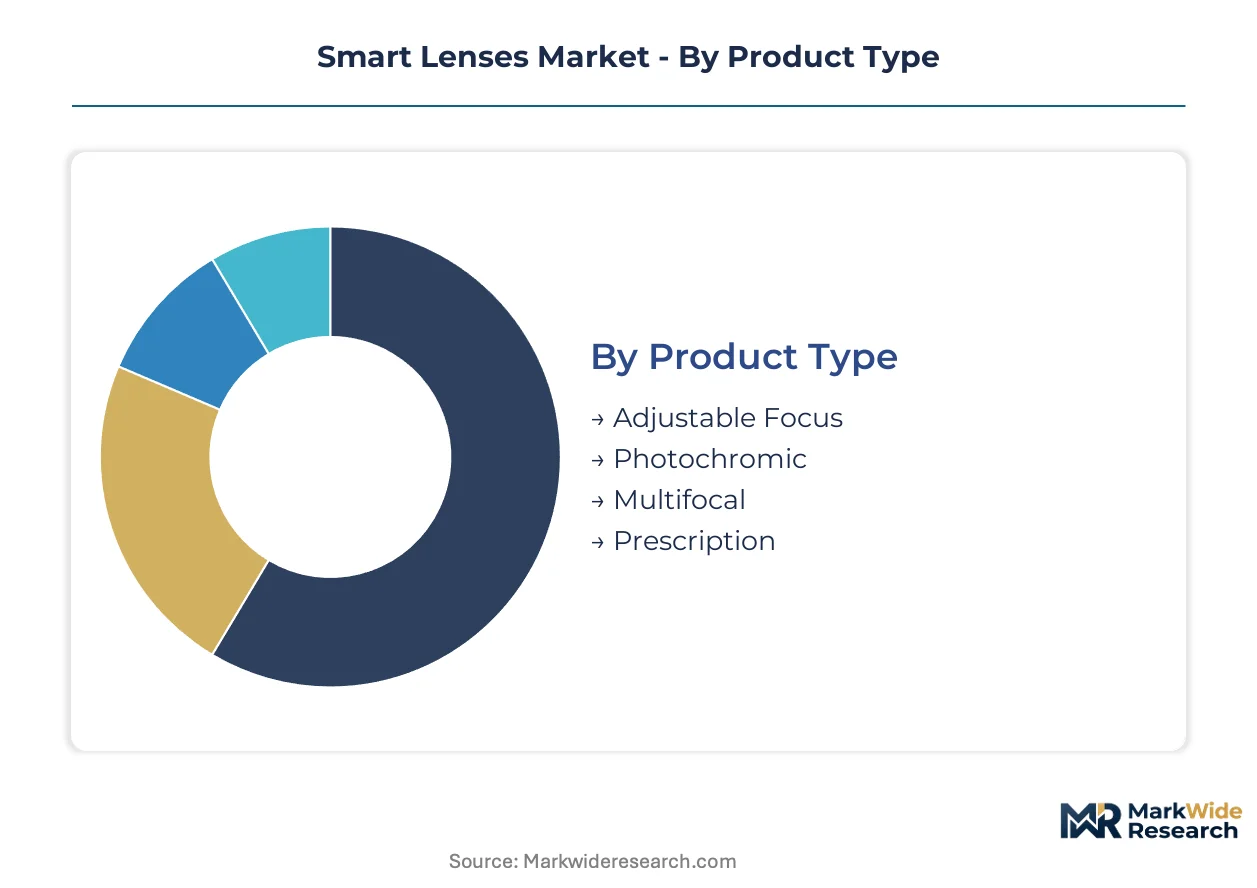
Smart lens architectures fragment across optical, electronic, and materials dimensions, with each segmentation axis revealing distinct margin structures and regulatory pathways. Product type configurations anchor established prescription eyewear revenue pools, while technology integration layers command premium positioning in emerging applications.
Product Type:
Domestic markets in Japan and Germany absorb photochromic and multifocal variants through established optical retail networks, while adjustable focus platforms target export-led medical device channels seeking FDA breakthrough designation pathways.
- Adjustable Focus:Liquid crystal or electrowetting elements enable real-time diopter modification through embedded micro-actuators. Demand concentrates in Germany's university hospital networks pursuing reimbursement for presbyopia correction without surgical intervention.
- Photochromic:Silver halide or naphthopyran compounds embedded in hydrogel matrices darken under UV exposure. Japanese consumers drive volume through METI-coordinated domestic standards that accelerate PMDA pre-certification against IEC 60601 benchmarks.
- Multifocal:Concentric ring or aspheric surface designs simultaneously correct near and distance vision. South Korean fabrication corridors supply the sub-micron precision tooling required for zonal refractive index patterning.
- Prescription:Conventional single-vision corrections with integrated sensor housing for future upgradeability. India's PLI scheme for wearable electronics attracts tariff-advantaged assembly investment for export markets.
Photochromic and multifocal configurations command the established base. The steepest expansion runs through adjustable focus platforms.
Technology:
Cost tiers stratify sharply between medical-grade sensor integration requiring ISO 13485 quality systems and consumer AR displays sourcing from smartphone component supply chains.
- AR Integration:Micro-LED or laser scanning projectors overlay digital imagery onto the visual field through waveguide couplers. Military simulation trainers in the United States refresh hardware at compressed twelve-month cycles.
- Embedded Sensors:MEMS strain gauges and capacitive elements track intraocular pressure or glucose levels through tear fluid analysis. Germany's ophthalmology clinics validate clinical utility for glaucoma progression monitoring.
- Wireless Charging:Inductive coils or RF harvesting circuits eliminate battery replacement in sealed lens housings. Samsung anchors supply through semiconductor process expertise competing with electric vehicle battery management chip demand.
- Smart Display:Transparent OLED or micro-LED matrices enable contextual information overlay without external eyewear. Japan's precision manufacturing clusters advance miniaturization through METI-funded consortia.
Embedded sensors capture the medical reimbursement channel. AR integration is climbing the fastest toward gaming and defense procurement volumes.
Application:
Volume concentration differs materially between regulated healthcare systems requiring clinical evidence and consumer segments prioritizing feature velocity.
- Medical Use:Continuous physiological monitoring for chronic disease management with FDA breakthrough device or EU MDR Class IIa certification. Hospital procurement committees consolidate vendor relationships favoring integrated data governance.
- Gaming:Immersive AR overlays and biometric feedback for peripheral control. Peripheral manufacturers adopt modular component layers at accelerated refresh cycles.
- Eyewear:Fashion-forward consumer lenses with ambient sensing and notification display. Direct-to-consumer telehealth channels bypass traditional optical retail distribution.
- Military:Tactical data overlay and physiological status monitoring for dismounted soldiers. Procurement runs through defense acquisition pathways with extended qualification timelines.
Medical use anchors the reimbursement-validated installed base. Gaming applications are expanding most quickly through twelve-month hardware refresh adoption.
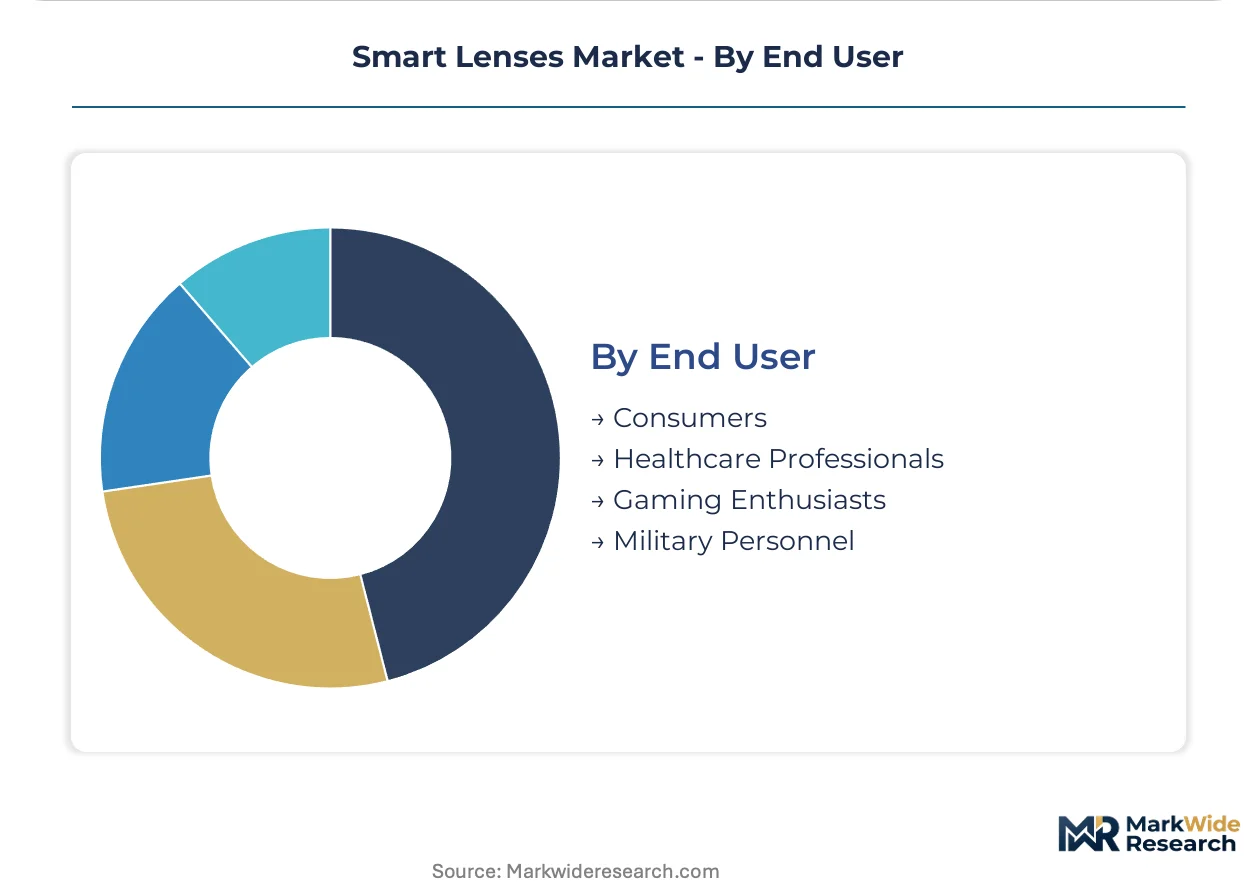
End User:
Customer type determines pricing architecture, with healthcare professionals requiring enterprise IT integration and consumers accepting feature-limited standalone configurations.
- Consumers:Self-directed purchasers through direct-to-consumer channels seeking prescription verification and virtual fitting workflows. Price sensitivity concentrates demand in standard-tier photochromic and multifocal configurations.
- Healthcare Professionals:Hospital systems and ophthalmology clinics requiring cybersecurity framework compliance and electronic health record integration. Germany exhibits the most aggressive procurement consolidation.
- Gaming Enthusiasts:Early adopters prioritizing immersion and biometric feedback over clinical-grade accuracy. Demand cycles track GPU and console release schedules.
- Military Personnel:Defense departments specifying electromagnetic compatibility and ruggedization beyond commercial standards. Procurement fragmentation across NATO allies complicates vendor scale economics.
Healthcare professionals command the premium tier through enterprise infrastructure requirements. Gaming enthusiasts are gaining share fastest as AR display costs compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device designations anchor the United States as the regulatory pace-setter, compressing clinical trial timelines for AR-integrated vision correction platforms while METI-funded consortia in Japan and ophthalmology networks in Germany validate parallel adoption pathways.
United States
Military simulation trainers and gaming peripheral manufacturers drive twelve-month hardware refresh cycles for AR display architectures. FDA breakthrough device pathways accelerate regulatory timelines for novel optical platforms. Boston and Austin fabrication clusters concentrate venture-backed startups pursuing waveguide miniaturization.
Germany
University hospital networks validate clinical utility for sensor-embedded intraocular pressure monitoring in glaucoma management. EU MDR Class IIa certification requirements shape product development timelines and evidence burdens. Stuttgart and Munich precision manufacturing corridors supply sub-micron tooling for hydrogel substrate processing.
Japan
Consumer eyewear segments absorb photochromic and multifocal variants through established optical retail networks. METI coordinates domestic standards alignment with IEC 60601 electrical safety benchmarks. Tokyo and Osaka precision manufacturing clusters advance smart display miniaturization through coordinated R&D investment.
South Korea
Semiconductor process expertise anchors wireless charging subsystem production competing with electric vehicle battery management chip demand. MFDS regulatory frameworks govern biocompatible polymer certification for ocular devices. Seoul and Suwon fabrication corridors concentrate MEMS fabrication specialists and micro-optics engineering talent.
India
Production-linked incentives for wearable electronics create tariff-advantaged assembly capacity for export-oriented producers. CDSCO medical device regulations govern sensor-embedded lens importation and clinical trial conduct. Karnataka and Telangana electronics manufacturing clusters attract component assembly investment from multinational lens producers.
Smart Lenses Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former controlling captive supply chains for transparent conductive oxide deposition and the latter concentrating on proprietary sensor calibration protocols. The market structure reflects semiconductor-grade fabrication requirements that exclude marginal players lacking ISO Class 5 cleanroom infrastructure. Three archetypes dominate: vertically integrated display architects, MEMS sensor specialists, and wireless power subsystem integrators. Competitive moves center on backward integration into hydrogel substrate production and strategic partnerships with hospital procurement committees seeking bundled data governance solutions.
Within the integrated display tier, Mojo Vision Inc. exemplifies vertical control over AR architecture development, while Samsung occupies a position leveraging semiconductor process expertise for power management subsystems. Sensimed AG represents the medical-grade sensor specialist archetype, anchoring proprietary calibration protocols for regulated healthcare applications. These three players illustrate how capability concentration in micro-optics engineering and MEMS fabrication redraws competitive boundaries across prescription eyewear, medical monitoring, and defense procurement segments.
| Leading Market Players |
|---|
| Mojo Vision Inc. |
| Innovega |
| Sensimed AG |
| Smartlens, Inc. |
| Azalea Vision |
| SEED Co., Ltd. |
| InWith Corp |
| XPANCEO |
| Samsung |
| Others |
Pricing and Supply Chain Analysis
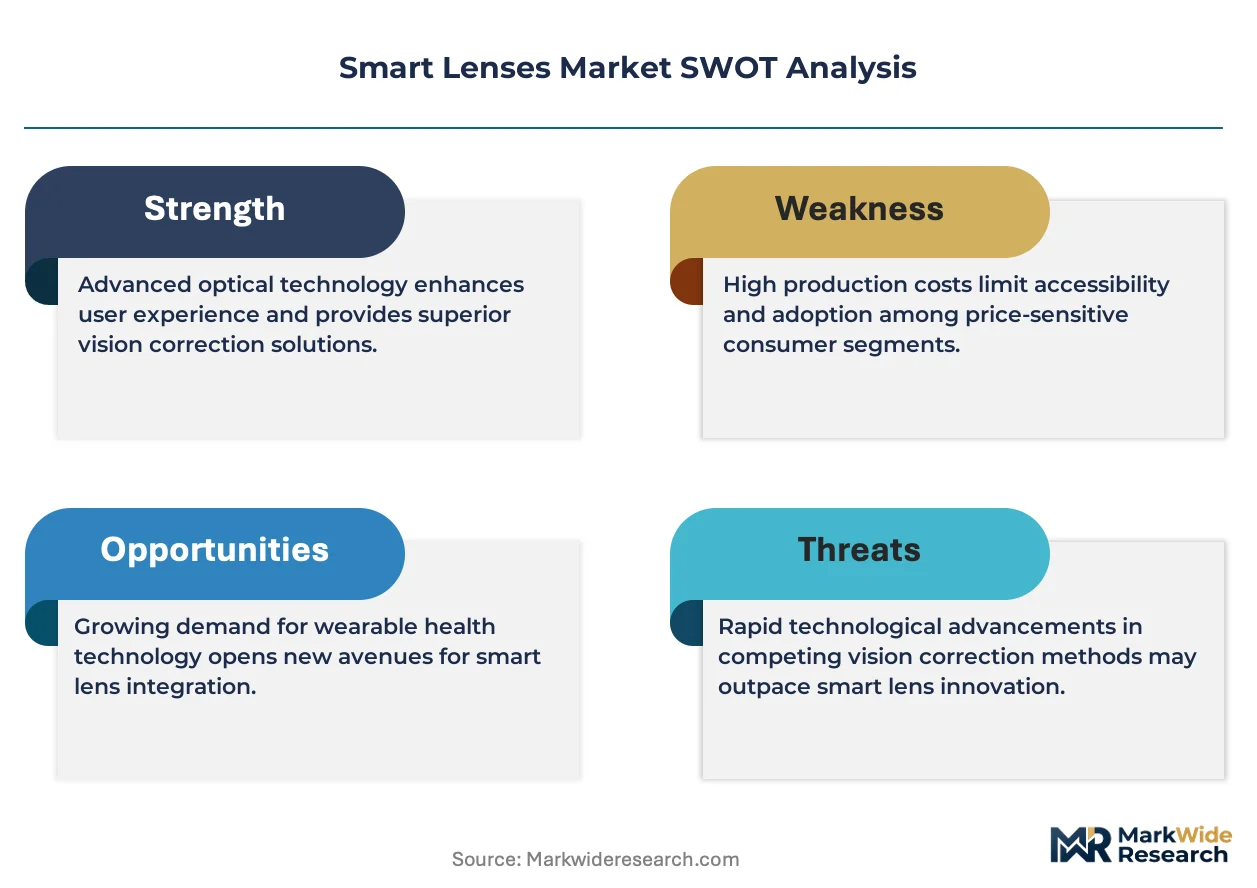
Ninety-day cleanroom qualification timelines for ISO Class 5 facilities compress available manufacturing slots and amplify pricing power for semiconductor-grade fabrication houses serving medical-grade smart lens producers. This lead-time rigidity concentrates margin capture among incumbent deposition specialists while forcing downstream assemblers into longer-term offtake commitments.
Pricing Analysis
Geographic price spreads between German university hospital procurement and Japanese consumer optical retail exceed three-to-one for comparable sensor-embedded configurations. Three-tier pricing structure across FDA breakthrough-designated, CE-marked, and uncertified consumer tiers anchors the dominant model. Price differentiation rests on certification grade and enterprise IT integration depth. Cost compression in standard photochromic segments intensifies due to India's PLI-subsidized assembly capacity. Healthcare professionals exhibit lowest price sensitivity; direct-to-consumer channels face highest.
Supply Chain Analysis
Taiwan and South Korea anchor MEMS fabrication and micro-optics engineering talent pools for transparent conductive oxide deposition. Japan and Germany supply sub-micron precision tooling and hydrogel substrate processing equipment. Raw material dependencies center on indium tin oxide, silver nanowire formulations, and biocompatible silicone hydrogels. Single-source vulnerability concentrates in ISO Class 5 cleanroom infrastructure. Distribution runs through hospital procurement committees in regulated markets and optical retail networks in consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart lenses sit in early-cycle expansion as FDA breakthrough device pathways compress clinical validation timelines and unlock reimbursement-validated medical adoption ahead of consumer AR maturation.
For Market Incumbents: Compound defensive moats through backward integration into hydrogel substrate production and captive certification infrastructure. Samsung's semiconductor process control and Mojo Vision's display architecture integration illustrate how upstream capability concentration repels modular component entrants. Prioritize hospital procurement committee relationships bundling data governance with sensor calibration protocols to displace standalone vendors lacking enterprise IT partnerships. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks compress regulatory timelines for presbyopia-focused adjustable focus platforms in Germany's reimbursement-validated university hospital networks. Target India's PLI-subsidized assembly corridors for tariff-advantaged export production of prescription-grade sensor housings. Pursue direct-to-consumer telehealth channels bypassing optical retail distribution to capture disintermediated margin pools in photochromic consumer segments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AR display miniaturization as METI-funded consortia accelerate R&D coordination requirements. Five-to-ten year viability favors vertically integrated specialists with captive cleanroom infrastructure and proprietary sensor calibration IP. Acquisition target archetype: MEMS fabrication specialists with medical-grade ISO 13485 quality systems and established glaucoma monitoring clinical evidence. Signal to watch: hospital procurement consolidation velocity in Germany bundling intraocular pressure monitoring with electronic health record contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogel Substrates | Captive supply of biocompatible polymers reduces dependency on Japanese specialty chemical suppliers. |
| FDA Breakthrough Device Pathway Pursuit | Accelerated clinical trial timelines compress time-to-market for AR-integrated vision correction platforms. |
| Hospital Procurement Committee Partnership | Bundled data governance contracts displace standalone sensor vendors lacking enterprise IT infrastructure. |
| ISO Class 5 Cleanroom Capacity Expansion | Semiconductor-grade fabrication slots command premium pricing as yield rates constrain supply availability. |
| Direct-to-Consumer Telehealth Channel Launch | Virtual fitting workflows bypass optical retail distribution and capture margin from disintermediated lens dispensing. |
Research Methodology
Desk research of FDA 510(k) and breakthrough device filings, EU MDR technical documentation, and METI-funded consortium disclosures preceded structured interviews with biomedical engineers, hospital procurement managers, ophthalmology clinic directors, and MEMS fabrication specialists. Secondary validation drew from PMDA pre-certification records, CDSCO medical device registration databases, and MFDS biocompatible polymer certification filings. Bottom-up demand modeling triangulated against top-down semiconductor process equipment capacity assessments.
Variance decomposition across product type, technology integration layer, application, and end-user segments structured the analytical framework over the projection horizon. CAGRs derived from installed base growth assumptions for intraocular pressure monitoring and replacement cycle compression for AR display architectures. Forecast inputs incorporated reimbursement pathway validation timelines and cleanroom capacity expansion schedules.
Underlying assumptions cover FDA breakthrough designation velocity, EU MDR Class IIa certification consistency, and ISO Class 5 cleanroom qualification throughput, with deviation risk concentrated in cybersecurity framework compliance cost inflation and wireless charging subsystem semiconductor allocation competition. Recalibration cycles align with material shifts in hospital procurement consolidation patterns and METI consortium R&D output commercialization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
3D Printed Implants Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
PET Injectors Market
Medical Devices
Bilirubin Meters Market
Medical Devices
Prefilled Syringes Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
Global Smart Biopsy Devices Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Bioimpedance Devices Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market