
 Global Infusion Pumps and Accessories Market | 2026-2036
Global Infusion Pumps and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Global Infusion Pumps and Accessories Market Foresight
Polycarbonate is decoupling from infusion pump housings as manufacturers migrate to Eastman Tritan copolyester for improved chemical resistance and reduced stress cracking. Becton, Dickinson and Company leverages backward integration into precision molding to control resin supply chains. Medtronic Plc anchors its position through proprietary smart pump software ecosystems. Baxter International differentiates via specialized intravenous sets designed for biologic drug compatibility.
Infusion pumps and accessories constitute electromechanical drug delivery systems that administer controlled volumes of therapeutic fluids through intravenous, subcutaneous, or epidural routes, typically operating at flow rates from 0.1 mL/hour to 999 mL/hour with occlusion pressure sensing and air-in-line detection. The primary purpose is to ensure precise dosing in settings where manual administration risks therapeutic error or infection. Smart pump technology with dose error reduction software captures the dominant margin pool as hospitals prioritize patient safety investments. Ambulatory pump demand accelerates fastest as oncology and pain management therapies shift toward outpatient administration. Elastomeric pumps remain a mature, cost-driven segment for post-surgical antibiotic delivery in emerging hospital systems.
The FDA enforces 510(k) premarket notification with escalating software documentation requirements, while the EU MDR mandates clinical evidence for reusable pump components and stricter post-market surveillance. Japan's PMDA imposes additional electromagnetic compatibility testing that shapes design priorities for Asia-bound product lines. Stakeholders must monitor evolving interoperability standards between pump data systems and electronic health records as connectivity becomes a regulatory gate for market access.
Market Dynamics
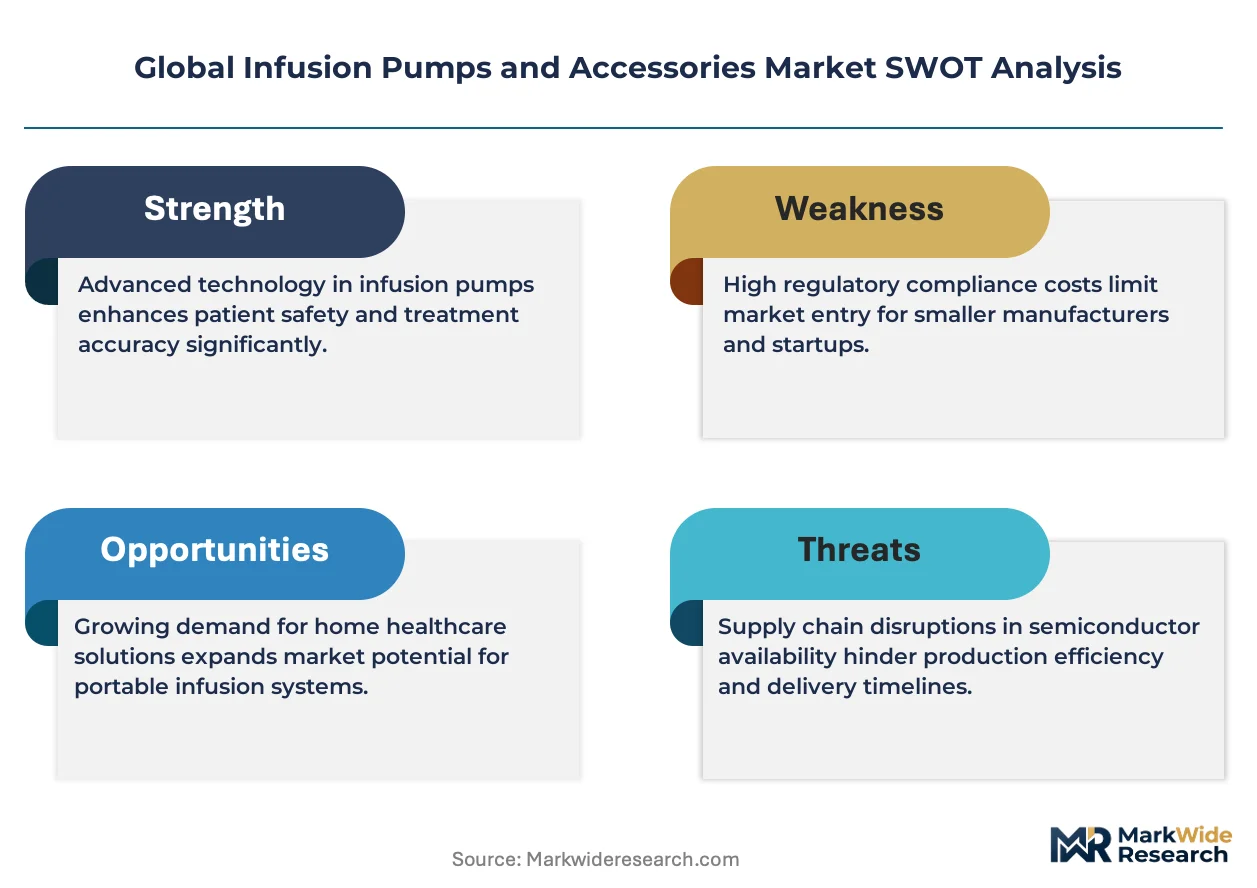
Smart pump software ecosystems are compressing hardware margins while elevating data interoperability requirements, forcing manufacturers to restructure R&D allocation toward embedded cybersecurity and cloud connectivity architectures.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter post-market surveillance for reusable pump components accelerates hospital replacement cycles and opens upgrade revenue streams for compliant suppliers.
- Home care settings:Oncology and pain management therapies migrate to outpatient administration, pulling ambulatory infusion systems into residential environments with remote monitoring capabilities.
- Eastman Tritan copolyester:Superior chemical resistance and reduced stress cracking versus polycarbonate drives material conversion in pump housing production, extending device service intervals.
Market Restraints
- Precision molding supply concentration:Backward integration by dominant players locks captive resin capacity, constraining mid-tier manufacturers' access to medical-grade polymer feedstocks.
- 510(k) software documentation escalation:FDA premarket notification requirements for connected pump platforms extend development timelines and inflate regulatory compliance costs disproportionately for smaller developers.
- Elastomeric pump commoditization:Mature mechanical technology faces price pressure in emerging hospital systems where basic antibiotic delivery dominates therapeutic protocols.
Strategic Opportunities
- Japan PMDA electromagnetic compatibility testing:Design prioritization for Asia-bound product lines creates first-mover positioning in high-specification hospital networks across East Asian markets.
- Biologic drug compatibility:Specialized intravenous sets for monoclonal antibody and cell therapy administration command premium positioning as biopharma pipelines mature.
- EHR interoperability standards:Pump data system integration with electronic health records becomes a regulatory gate for market access, rewarding early protocol adopters with preferred vendor status.
Industry Challenges
- Embedded cybersecurity talent scarcity:Connected pump platforms require specialized firmware engineering capabilities that medical device manufacturers compete for against technology sector employers.
- Legacy system integration friction:Hospital IT infrastructure heterogeneity complicates deployment of cloud-connected infusion management systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Infusion Pumps and Accessories Market |
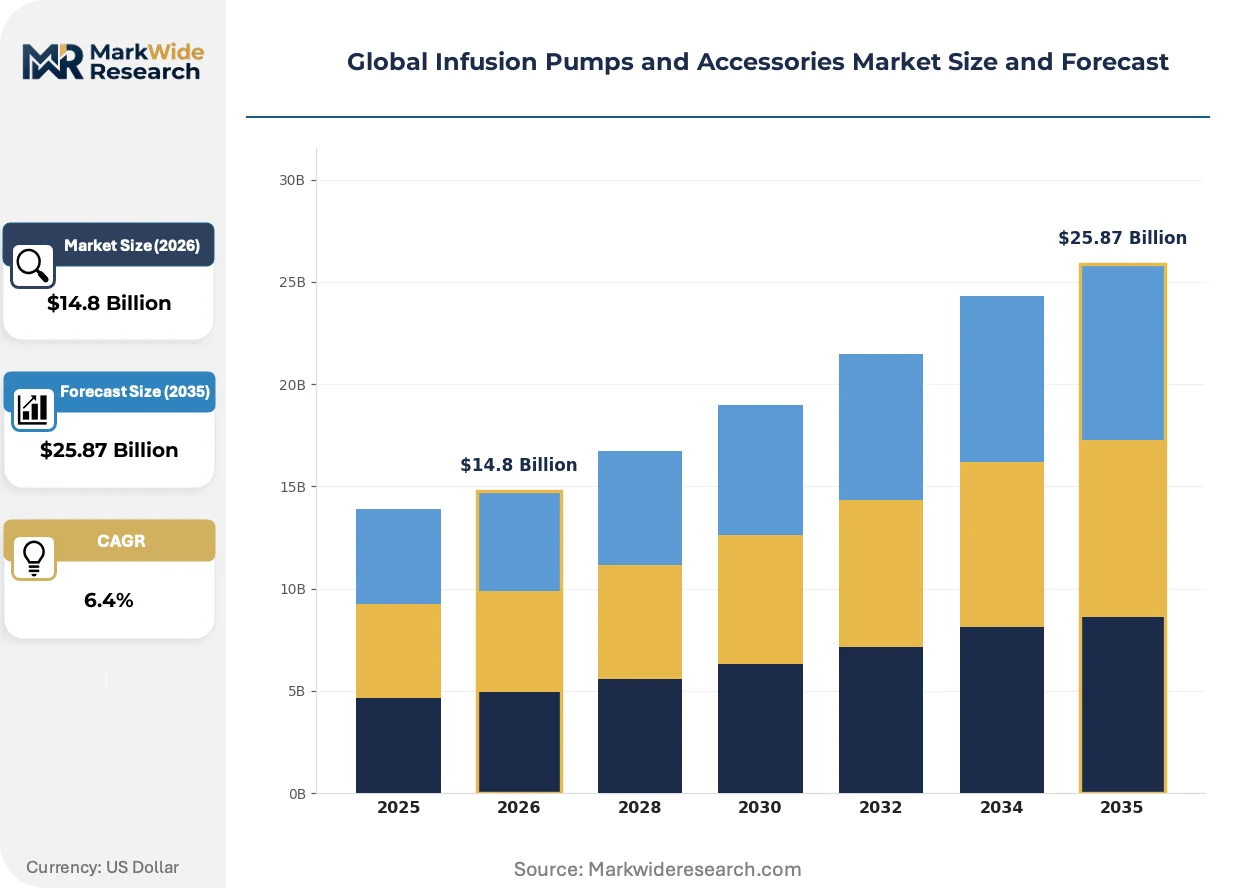
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCA Pumps, Syringe Pumps, Volumetric Pumps, Elastomeric Pumps, Ambulatory Pumps Therapy Area: Oncology, Anesthesia, Critical Care, Nutrition, Pain Management End User: Hospitals, Ambulatory Surgical Centers, Home Care, Specialty Clinics Technology: Wireless Connectivity, Programmable Infusion, Smart Pumps, Battery Operated, Mechanical Pumps |
| Companies Covered | Becton, Dickinson and Company, Medtronic Plc, Baxter International, B. Braun SE, Fresenius Kabi, Terumo Corporation, ICU Medical, Smiths Medical, Insulet Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Infusion Pumps and Accessories Market Shifts & Advancements
Dose error reduction software is migrating from safety feature to core purchasing criterion, reshaping competitive differentiation around algorithmic accuracy and clinical decision support integration rather than hardware specifications alone.
Closed-loop infusion control with real-time pharmacokinetic modeling is expanding into high-acuity care units where anesthesiology and intensive care teams demand automated titration for narrow-therapeutic-index medications. Academic medical centers in Germany and the United States pilot these systems for insulin and vasopressor delivery, compressing the window between prescription and physiological response while reducing nursing cognitive load.
Japan's PMDA electromagnetic compatibility testing requirements are filtering into design specifications for pump electronics destined for Asia-Pacific markets, forcing hardware architecture revisions that exceed baseline IEC 60601-1-2 standards. Manufacturers targeting Japanese hospital procurement channels must validate immunity against regional grid frequency variations and localized radiofrequency environments, creating compliance segmentation between product variants.
Hospital purchasing committees now unbundle after-sales service contracts from capital equipment procurement, treating preventive maintenance and software updates as separately negotiable line items. This disintermediation pressures traditional full-service vendors in the United States while creating entry points for third-party technical service specialists and independent software maintenance providers.
Global Infusion Pumps and Accessories Market Segmentation
Infusion pump procurement decisions fragment across clinical workflow requirements, reimbursement pathways, and regulatory compliance tiers. Manufacturers must align product architecture with specific therapy protocols and care settings rather than pursuing universal platform strategies.
Product Type:
Hospital capital allocation prioritizes interoperability with electronic health record systems and dose error reduction capabilities.
- PCA Pumps:Patient-controlled analgesia systems incorporate programmable lockout intervals and demand dosing limits for post-operative pain management. Demand concentrates in United States academic medical centers where opioid stewardship protocols mandate electronic documentation of every bolus request.
- Syringe Pumps:Compact electromechanical devices deliver precise low-volume infusions from 0.1 mL/hour for neonatal intensive care and anesthesia applications. Germany's university hospitals drive specification requirements for multi-channel stacking and drug library compatibility.
- Volumetric Pumps:Large-volume fluid delivery systems dominate emergency department and general ward installations where saline and electrolyte administration volumes exceed 500 mL per setting.
- Elastomeric Pumps:Disposable balloon reservoirs provide mechanical pressure-driven infusion without electronic components, serving cost-constrained antibiotic delivery protocols in emerging hospital systems.
- Ambulatory Pumps:Wearable devices with subcutaneous access ports enable continuous chemotherapy and pain management outside institutional settings; Japan's aging population and home care reimbursement expansion accelerate residential deployment.
Volumetric pumps lead on scale; ambulatory pumps lead on momentum.
Therapy Area:
Reimbursement intensity and drug cost structure determine equipment specification tiers across clinical specialties.
- Oncology:Chemotherapy administration requires precise control of vesicant and irritant agents with programmable tapering protocols. United States outpatient infusion centers purchase premium platforms with biologic drug compatibility certification.
- Anesthesia:Operating room environments demand rapid-response titration capabilities for propofol and remifentanil with pharmacokinetic modeling integration. German surgical suites specify closed-loop control systems for narrow-therapeutic-index medications.
- Critical Care:Intensive care units prioritize multi-channel capability and alarm management systems for vasopressor and sedation cocktails.
- Nutrition:Enteral and parenteral feeding protocols require dedicated pumps with occlusion sensitivity calibrated for higher-viscosity formulas.
- Pain Management:Epidural and peripheral nerve block applications favor programmable basal rates with patient-controlled bolus functionality.
Oncology commands premium pricing; anesthesia drives technology advancement.
End User:
Procurement authority and total cost of ownership calculations vary sharply across institutional settings.
- Hospitals:Integrated delivery networks negotiate enterprise-wide contracts bundling capital equipment, software licenses, and preventive maintenance across multiple facilities.
- Ambulatory Surgical Centers:Same-day procedure facilities prioritize compact footprint and rapid turnover capabilities for anesthesia and antibiotic delivery.
- Home Care:Residential reimbursement codes in Japan and the United States now cover connected pump platforms with remote monitoring, expanding addressable volume beyond institutional boundaries.
- Specialty Clinics:Independent oncology and pain management practices seek lease-based financing for ambulatory systems to align capital outlay with patient census fluctuations.
Hospitals anchor procurement volume; home care expands the addressable perimeter.
Technology:
Software architecture and connectivity infrastructure now determine competitive viability more than mechanical reliability alone.
- Smart Pumps:Dose error reduction software with drug libraries and hard/soft limit programming has become non-negotiable for United States hospital accreditation. FDA 510(k) clearance timelines for algorithm updates now shape vendor competitive cycles.
- Wireless Connectivity:Wi-Fi and cellular-enabled pumps transmit flow rate, occlusion, and reservoir data to central monitoring stations and electronic health records. EU MDR cybersecurity documentation requirements filter out undercapitalized developers.
- Programmable Infusion:Customizable delivery profiles support complex tapering protocols for chemotherapy and immunoglobulin administration.
- Battery Operated:Portable power systems enable intra-hospital transport and emergency backup for critical care applications.
- Mechanical Pumps:Gravity-fed and elastomeric systems persist where electronic infrastructure is unreliable or cost constraints dominate.
Smart pumps capture margin concentration; wireless connectivity enables platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's medical technology corridor concentrates European infusion pump engineering talent and regulatory expertise, drawing procurement decisions from hospital networks across Central Europe. FDA-cleared manufacturers in the United States capture premium pricing through dose error reduction software mandates. Japanese PMDA electromagnetic compatibility requirements filter into design specifications for Asia-bound product lines.
United States
Academic medical centers in Boston and the Research Triangle drive demand for closed-loop anesthesia systems with pharmacokinetic modeling integration. FDA 510(k) premarket notification requirements for connected pump platforms extend development timelines and inflate compliance costs disproportionately for smaller developers. The Minneapolis-St. Paul corridor anchors precision molding capacity serving Becton, Dickinson and Company's backward integration strategy.
Germany
University hospitals in Munich and Heidelberg specify multi-channel syringe pump stacking with drug library compatibility for neonatal and anesthesia applications. EU MDR clinical evidence mandates for reusable pump components accelerate hospital replacement cycles and open upgrade revenue streams for compliant suppliers. The Baden-Württemberg industrial cluster around Tuttlingen concentrates surgical equipment manufacturing expertise that spills into infusion system component sourcing.
Japan
Tokyo's aging population and expanding home care reimbursement codes pull ambulatory infusion systems into residential environments with remote monitoring capabilities. PMDA electromagnetic compatibility testing requirements shape design priorities for Asia-bound product lines, forcing hardware architecture revisions exceeding baseline IEC 60601-1-2 standards. The Kansai region around Osaka maintains precision electronics manufacturing capacity for pump control systems.
China
Tier-3 hospital expansion in the Yangtze River Delta generates volume demand for basic volumetric and elastomeric pump platforms. NMPA medical device registration requirements for imported infusion systems create compliance barriers favoring domestic manufacturers with established regulatory pathways. Shanghai's Zhangjiang Hi-Tech Park clusters medical device R&D operations serving both domestic and export markets.
India
CDSCO-regulated medical device manufacturing in Gujarat and Maharashtra targets cost-constrained antibiotic delivery protocols in emerging hospital systems. Government medical college hospitals in Delhi and Chennai drive procurement for mechanical elastomeric pumps where electronic infrastructure remains unreliable. The Andhra Pradesh MedTech Zone near Visakhapatnam attracts contract manufacturing investments from global pump suppliers seeking tariff-advantaged export platforms.
Global Infusion Pumps and Accessories Market Competitive Landscape
Global majors compete with regional champions across software ecosystem maturity and regulatory clearance breadth, creating tiered market access barriers. The vendor base stratifies between full-platform providers with proprietary drug libraries and component specialists serving private-label arrangements. Three archetypes dominate: integrated system houses controlling resin supply chains through backward integration, software-centric platforms monetizing dose error reduction algorithms, and disposable-focused manufacturers optimizing elastomeric balloon production costs. Competitive moves concentrate on M&A for cybersecurity talent and strategic partnerships for EHR interoperability certification.
Within the integrated system house tier, Becton, Dickinson and Company and Baxter International exemplify players leveraging captive precision molding capacity to control medical-grade polymer feedstocks. Medtronic Plc occupies a position anchoring the software-centric archetype through proprietary smart pump ecosystems that compress hardware margins while elevating data interoperability requirements. These three companies represent the dominant competitive vectors reshaping R&D allocation toward embedded cybersecurity and cloud connectivity architectures.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Medtronic Plc |
| Baxter International |
| B. Braun SE |
| Fresenius Kabi |
| Terumo Corporation |
| ICU Medical |
| Smiths Medical |
| Insulet Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into precision molding anchors supply positioning and pricing power for dominant manufacturers controlling captive resin capacity for medical-grade polymer feedstocks. This structural choice locks mid-tier competitors out of Eastman Tritan copolyester supply while enabling integrated system houses to command premium positioning through controlled input costs and quality assurance.
Pricing Analysis
Medical-grade polymer cost pass-through varies by certification tier, with FDA 510(k)-cleared smart pumps carrying resin premiums that commodity elastomeric devices cannot absorb. Pricing stratifies across premium smart pump platforms with dose error reduction software, standard volumetric systems for general wards, and economy elastomeric balloons for antibiotic delivery in emerging markets. Cost compression in the economy tier is intensifying because domestic manufacturers in India and China optimize balloon production costs for price-sensitive hospital procurement committees. Ambulatory oncology systems show least price sensitivity due to reimbursement coverage, while mechanical pumps for basic antibiotic protocols face maximum buyer pressure.
Supply Chain Analysis
Precision molding workforce availability in the Minneapolis-St. Paul corridor, the Baden-Württemberg cluster around Tuttlingen, and the Kansai region around Osaka shapes manufacturing location decisions for pump housings and control electronics. Raw material sourcing draws from Eastman Chemical for Tritan copolyester, specialized semiconductor foundries for pump control chipsets, and precision metalwork suppliers for occlusion pressure sensors. Single-source vulnerability concentrates in medical-grade resin supply where backward integration by Becton, Dickinson and Company and Baxter International constrains independent access. Distribution runs through integrated delivery network procurement offices in the United States, university hospital purchasing committees in Germany, and regional medical device distributors serving tier-3 hospitals in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Infusion Pumps and Accessories Market functions as a stable compounder where chronic disease prevalence and home care reimbursement expansion generate predictable replacement cycles and upgrade revenue streams.
For Market Incumbents: Hedge software ecosystem dominance against embedded cybersecurity talent scarcity by acquiring specialized firmware engineering capabilities before technology sector employers exhaust the talent pool. Deepen backward integration into precision molding capacity in the Minneapolis-St. Paul corridor to lock resin supply advantages as Eastman Tritan conversion accelerates. Fortify dose error reduction algorithm portfolios through FDA 510(k) pre-submission pathways that extend clearance timelines for competitors. For New Entrants and Emerging Players: The price-point gap between premium smart pump platforms and economy elastomeric systems creates entry space for mid-tier programmable infusion devices targeting ambulatory surgical centers and specialty clinics. Target India's government medical college hospitals with mechanical pump offerings where electronic infrastructure remains unreliable and CDSCO registration favors cost-optimized platforms. Pursue lease-based financing arrangements for independent oncology practices seeking capital-efficient ambulatory system deployment. For Investors and Strategic Acquirers: Consolidation pressure builds where cybersecurity firmware capabilities fragment across undercapitalized developers unable to satisfy EU MDR documentation requirements. Frame long-term viability around smart pump software monetization models that compress hardware margins while elevating recurring revenue from drug library updates and interoperability certification. Monitor FDA 510(k) clearance backlogs as an inflection indicator signaling regulatory capacity constraints that favor established players with pre-submission relationships.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Software documentation for connected pump platforms gates market access in the United States. |
| EU MDR Clinical Evidence Pathway | Post-market surveillance mandates for reusable components accelerate hospital replacement cycles. |
| Hospital System Partnership | Integrated delivery network contracts bundle capital equipment with preventive maintenance and software licenses. |
| Software Companion Development | Dose error reduction algorithms with EHR interoperability capture preferred vendor status in procurement decisions. |
| Reimbursement Strategy | Home care coding expansion in Japan and the United States enables residential ambulatory pump deployment. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market combining structured interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists with secondary validation. Secondary sources include FDA 510(k) clearance databases, EU MDR notified body certificates, hospital procurement records from integrated delivery networks, and precision molding capacity reports from medical-grade polymer suppliers. Bottom-up sizing of installed base and replacement cycles triangulates against top-down market value estimates from capital equipment expenditure surveys.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon, with analytical frameworks modeling product type, therapy area, end user setting, and technology tier as primary segmentation dimensions. CAGRs derive from regression analysis of historical replacement patterns, reimbursement trajectory assumptions, and regulatory compliance cost pass-through coefficients. Industry-specific forecast inputs include PMDA electromagnetic compatibility testing timelines for Asia-bound product lines and EU MDR clinical evidence generation costs for reusable pump components.
Caveats apply where FDA software documentation requirement escalations, EU MDR post-market surveillance enforcement intensity, or home care reimbursement code revisions could materially shift the outlook. Forecasts reflect assumptions about chronic disease prevalence trajectories, hospital capital allocation priorities, and polymer supply chain stability that warrant monitoring against actual procurement data. Material deviation in named triggers warrants pause and re-evaluation of volume and value projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Pancreas Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Global Capillary Blood Collection Devices Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
Aortic Cannula Systems Market
Medical Devices
Global Single-Use Medical Device Reprocessing Market
Medical Devices
Extremity Reconstruction Market
Medical Devices
Global Cast Saw Devices Market
Medical Devices
Suction Catheters Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Venous Procedure Devices Market