
 Pericardial Patches Market | 2026-2036
Pericardial Patches Market Size, Share, and Industry Trends Forecast 2026-2036
Pericardial Patches Market Outlook
Cardiac surgery is realigning toward complex valve reconstruction and pediatric congenital repair, pulling pericardial patch procurement away from routine adult procedures. Edwards Lifesciences Corporation dominates transcatheter valve platforms and extends that expertise into surgical patch adjacencies. Baxter International leverages its regenerative medicine portfolio to sustain hospital contracts across multiple tissue-based product lines. CryoLife, Inc. specializes in cryopreserved cardiac tissues and anchors a defensible position in biological patch processing.
Pericardial patches are implantable biomaterials derived from processed animal pericardium or engineered polymers, typically measuring 0.3 to 0.8 millimeters in thickness, designed to seal cardiac defects or reinforce suture lines during thoracic surgery. Their primary commercial purpose is to provide a biocompatible barrier that integrates with native tissue while maintaining tensile strength through the critical healing window. Biological patches command the largest revenue pool due to superior remodeling characteristics, while synthetic patches compete on consistent supply and lower viral transmission risk. Composite patches represent the fastest-growing material category as surgeons seek combined handling and integration properties.
FDA premarket notification requirements and CE marking under the EU Medical Device Regulation shape product development timelines and clinical evidence burdens for patch manufacturers. ISO 10993 biocompatibility testing and viral inactivation validation standards further filter which suppliers can access regulated markets. Stakeholders must monitor evolving MDR technical documentation requirements and FDA guidance on animal-derived medical devices to anticipate compliance costs and market access barriers.
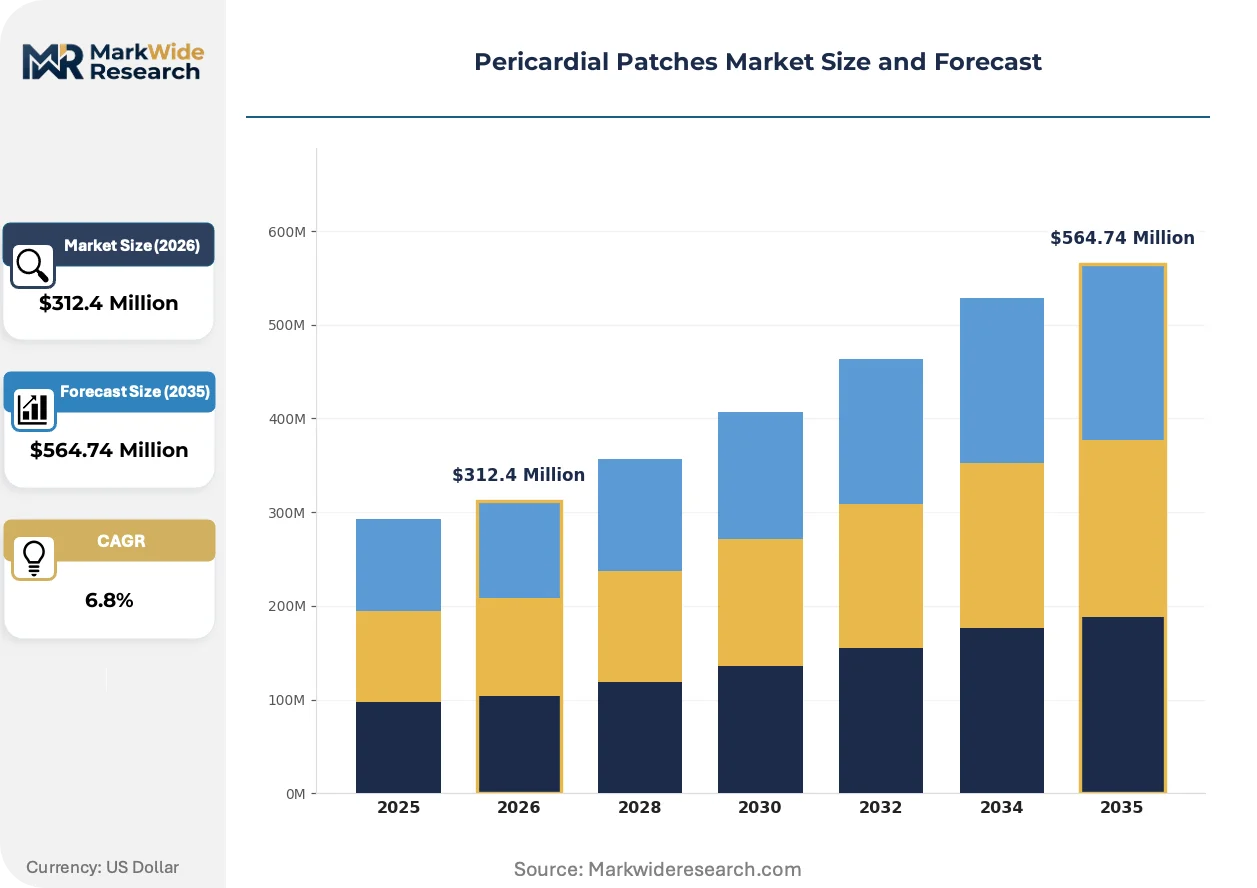
Market Dynamics
Biological patch manufacturers face mounting pressure from the EU Medical Device Regulation's tightened technical documentation requirements, which compress product development timelines while demanding more extensive clinical evidence for animal-derived cardiovascular implants.
Growth Catalysts
- MDR Compliance Acceleration:European manufacturers are fast-tracking biocompatibility testing protocols to meet CE marking deadlines, expanding validated supplier pools for cardiac surgery centers.
- Pediatric Congenital Repair:Tertiary hospitals in Germany and Japan are scaling valve reconstruction programs that specify pericardial patches over mechanical alternatives.
- Cryopreservation Advances:Automated processing systems are extending tissue viability windows, reducing wastage rates in biological patch supply chains.
Market Restraints
- Bovine Pericardium Supply Concentration:Raw material sourcing clusters in Argentina and Brazil, exposing processors to export restriction volatility and herd health crises.
- Viral Inactivation Validation Costs:FDA guidance on animal-derived devices requires redundant pathogen clearance studies that add eighteen to twenty-four months to approval timelines.
- Synthetic Polymer Substitution:Expanded polytetrafluoroethylene patches from integrated polymer manufacturers compete on supply consistency and lower batch-to-batch variability.
Strategic Opportunities
- Indian Cardiac Surgery Expansion:CDSCO regulatory harmonization with ISO 13485 standards is opening import pathways for processed pericardial tissues into Mumbai and Delhi hospital networks.
- Composite Patch Development:Hybrid biological-synthetic laminates are capturing interest among valve reconstruction specialists seeking handling precision plus remodeling capacity.
- Direct Hospital Contracting:Bypassing traditional distributor networks allows patch processors to capture margin and secure multi-year supply agreements with high-volume cardiac centers.
Industry Challenges
- Tissue Processing Technician Shortage:Specialized skills in decellularization and crosslinking chemistry remain scarce, constraining batch throughput at biological patch facilities.
- Legacy ERP Integration:New manufacturing execution systems for lot traceability must interface with hospital procurement platforms that lack standardized data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pericardial Patches Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biological Patches, Synthetic Patches, Composite Patches, Resorbable Patches Material: Porcine Tissue, Bovine Tissue, Polymers, Collagen Application: Cardiac Surgery, Trauma Surgery, Repair Procedures, Reconstruction End User: Hospitals, Surgical Centers, Cardiac Clinics, Research Institutions |
| Companies Covered | LeMaitre Vascular, Inc., CryoLife, Inc., Edwards Lifesciences Corporation, Labcor Laboratórios Ltda, W. L. Gore & Associates, Inc., Baxter International, ARTIVION, Inc., Collagen Solutions LLC, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pericardial Patches Market Strategic Shifts
Pericardial patch processing is converging with advanced manufacturing and digital quality systems, redefining how biological tissues transition from raw material to implantable device.
Electrospinning of decellularized pericardial matrix is automating the production of aligned fiber scaffolds that match native tissue anisotropy. Cardiovascular research institutes in Switzerland and the Netherlands are piloting these systems for patient-specific patch geometries. The technology is automating what previously required manual lamination, compressing production cycles from weeks to days while tightening thickness tolerances.
EU MDR Article 10 technical documentation mandates now require continuous post-market surveillance data streams that feed directly into notified body review cycles. Manufacturers must maintain living clinical evidence files rather than static approval dossiers. Biological patch suppliers with established European market presence are absorbing compliance costs faster than new entrants, consolidating access to cardiac surgery departments in France and Italy.
Hospital value analysis committees are consolidating vendor lists around dual-source biological patch suppliers who demonstrate redundant sterilization capabilities. Cardiac surgery procurement in the United States is favoring processors with validated gamma and electron beam alternatives. This concentration is visible most acutely in integrated delivery networks across Texas and Florida, where contracting officers are excluding single-technology vendors from multi-year agreements.
Pericardial Patches Market Segmentation
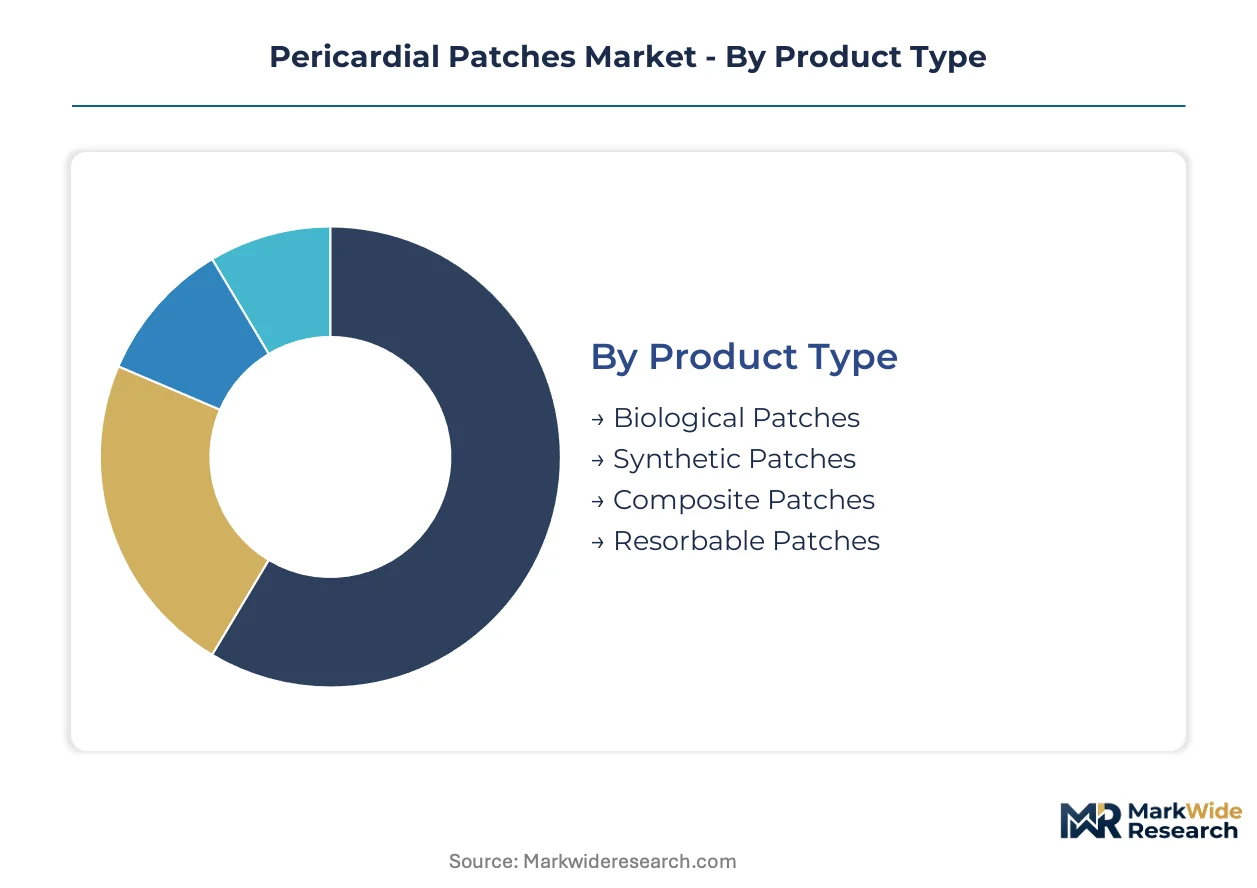
Pericardial patch procurement splits across material origin, surgical application, and care setting. Surgeons select patch categories based on remodeling requirements, viral safety profiles, and institutional sterilization capabilities.
Product Type:
Thickness specifications and crosslinking chemistry differentiate patch performance during the critical healing window.
- Biological Patches:Processed animal pericardium retains native collagen architecture that supports cellular infiltration and gradual remodeling. Tertiary cardiac centers in Germany and Japan specify biological patches for pediatric valve reconstruction where tissue integration outweighs supply consistency concerns.
- Composite Patches:Laminated biological-synthetic structures combine handling precision with remodeling capacity. Valve reconstruction specialists in Switzerland and the Netherlands are piloting patient-specific geometries manufactured through electrospun matrix alignment.
- Synthetic Patches:Expanded polytetrafluoroethylene formulations deliver batch-to-batch uniformity and eliminate viral transmission pathways. Polymer manufacturers compete on supply security for high-volume cardiac surgery networks.
- Resorbable Patches:Engineered degradation timelines match tissue ingrowth rates for temporary structural support. Research institutions evaluate resorbable platforms for trauma applications where permanent implants create long-term complications.
Mature deployment sits with biological patches. Newer deployment is concentrated in composite laminates.
Material:
Raw material sourcing geography and processing chemistry determine regulatory pathway complexity and batch economics.
- Bovine Tissue:Argentine and Brazilian herd supply dominates raw material flows. FDA viral inactivation guidance requires redundant pathogen clearance studies that extend approval timelines for bovine-derived processors.
- Porcine Tissue:Decellularized porcine pericardium offers alternative collagen architecture with distinct immunogenic profiles. CDSCO harmonization with ISO 13485 is opening import pathways into Mumbai and Delhi hospital procurement networks.
- Polymers:Synthetic polymer supply chains bypass biological tissue variability and export restriction volatility. Integrated polymer manufacturers capture margin through consistent specification delivery.
- Collagen:Purified collagen matrices support specialized applications requiring defined biochemical composition. Research institutions source collagen platforms for experimental tissue engineering protocols.
Established volume concentrates in bovine tissue. Emerging procurement is shifting toward porcine alternatives.
Application:
Surgical complexity and patient age demographics shape patch selection criteria across procedure categories.
- Cardiac Surgery:Valve reconstruction and congenital defect repair command premium biological patch specifications. Tertiary hospitals are scaling programs that specify pericardial patches over mechanical alternatives for complex pediatric cases.
- Repair Procedures:Suture line reinforcement and defect closure utilize standardized patch formats with validated tensile strength profiles. Surgical centers prioritize supply security for routine cardiac procedures.
- Trauma Surgery:Emergency thoracic repair demands immediate availability across multiple patch material categories. Hospital value analysis committees consolidate vendor lists around dual-source suppliers with redundant sterilization capabilities.
- Reconstruction:Structural restoration applications require patient-specific sizing and handling characteristics. Cardiac clinics in Texas and Florida integrated delivery networks favor processors with validated gamma and electron beam alternatives.
Procedure volume clusters in cardiac surgery. Reconstruction applications are expanding most quickly.
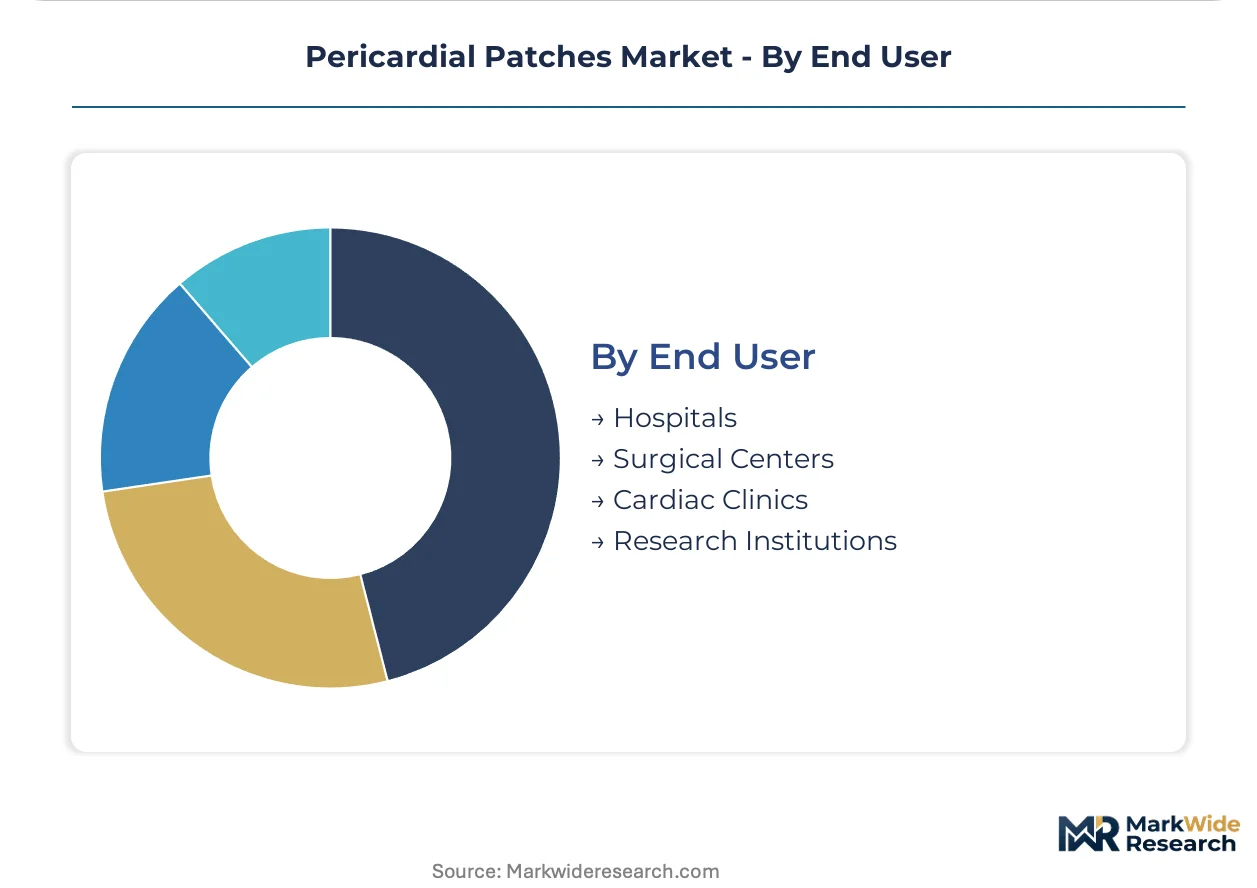
End User:
Procurement scale and clinical specialization determine contracting structures and supplier relationship intensity.
- Hospitals:High-volume cardiac surgery departments negotiate multi-year supply agreements with direct processor contracting. Automated processing systems are extending tissue viability windows and reducing wastage rates in hospital supply chains.
- Surgical Centers:Ambulatory settings prioritize standardized patch formats with simplified inventory management. Procurement officers exclude single-technology vendors from agreements.
- Cardiac Clinics:Specialized valve reconstruction programs demand premium biological patch specifications with documented remodeling outcomes. EU MDR Article 10 mandates require continuous post-market surveillance data streams.
- Research Institutions:Experimental protocols evaluate novel processing chemistries and patient-specific manufacturing platforms. Swiss and Dutch cardiovascular research institutes pilot electrospun scaffold systems.
Procurement concentration remains with hospitals. Research institutions are gaining procurement share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for medical device manufacturing in Costa Rica and Ireland concentrate pericardial patch processing capacity near major cardiac surgery markets. These zones offer accelerated FDA and CE marking pathways that attract biological tissue processors seeking dual-continent market access.
United States
Integrated delivery networks in Texas and Florida negotiate multi-year supply agreements with dual-source biological patch suppliers. FDA guidance on animal-derived devices mandates redundant pathogen clearance studies that extend approval timelines. The Greater Boston cluster anchors cryopreservation research for extending tissue viability windows.
Germany
Tertiary cardiac centers in Munich and Heidelberg scale valve reconstruction programs specifying pericardial patches for pediatric congenital repair. EU MDR Article 10 technical documentation requirements compress product development timelines while demanding extensive clinical evidence. The Baden-Württemberg region hosts automated electrospinning pilot facilities for patient-specific patch geometries.
Japan
Aging demographics sustain cardiac surgery volumes at Tokyo and Osaka university hospitals procuring advanced biological patch materials. PMDA harmonization with ISO 10993 biocompatibility standards streamlines import pathways for processed pericardial tissues. The Kansai region concentrates cryopreserved tissue distribution networks serving western Japan.
Switzerland
Swissmedic regulations enforce stringent viral inactivation validation for animal-derived cardiovascular implants entering the market. Cardiovascular research institutes in Zurich and Basel pilot electrospun decellularized matrix systems for aligned fiber scaffolds. The Basel metropolitan area anchors contract manufacturing for EU MDR-compliant biological patch processing.
India
CDSCO regulatory harmonization with ISO 13485 standards opens import pathways for processed pericardial tissues into Mumbai and Delhi hospital networks. Government medical device parks in Andhra Pradesh and Gujarat offer tax incentives for domestic biological tissue processing facilities. The Maharashtra cluster concentrates cardiac surgery volume at Mumbai tertiary centers driving procurement expansion.
Pericardial Patches Market Competitive Environment
Top-tier vendors anchor hospital contracting networks, while mid-tier processors compete on specialized cryopreservation and decellularization capabilities. The vendor base stratifies across integrated cardiovascular device conglomerates, dedicated biological tissue processors, and regional patch fabricators. Two strategic archetypes dominate: cryopreservation specialists leveraging automated tissue handling systems, and diversified cardiovascular platforms extending valve expertise into surgical adjacencies. Competitive moves concentrate on direct hospital contracting bypass and composite patch R&D partnerships.
Within the cryopreservation specialist tier, CryoLife, Inc. exemplifies automated biological tissue processing capabilities. Among diversified cardiovascular platforms, Edwards Lifesciences Corporation occupies a position representing transcatheter-to-surgical valve expertise extension. Baxter International sits within the integrated hospital supply conglomerate archetype, leveraging regenerative medicine portfolio breadth for multi-product line contracting.
| Leading Market Players |
|---|
| LeMaitre Vascular, Inc. |
| CryoLife, Inc. |
| Edwards Lifesciences Corporation |
| Labcor Laboratórios Ltda |
| W. L. Gore & Associates, Inc. |
| Baxter International |
| ARTIVION, Inc. |
| Collagen Solutions LLC |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Automated electrospinning systems for decellularized pericardial matrix are compressing production cycles from weeks to days while simultaneously shifting cost economics toward capital-intensive processors and away from manual lamination facilities. This manufacturing transition concentrates pricing power among suppliers with validated gamma and electron beam sterilization alternatives, particularly within integrated delivery networks across Texas and Florida that exclude single-technology vendors from multi-year agreements.
Pricing Analysis
Short lead-time premiums dominate patch procurement economics, with cardiac surgery departments paying significant markups for cryopreserved tissues with extended viability windows versus spot inventory with narrower usage windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by viral inactivation validation depth and crosslinking chemistry sophistication. Pricing pressure stems from synthetic polymer substitution by integrated manufacturers competing on batch-to-batch uniformity. Pediatric congenital repair programs exhibit lowest price sensitivity due to tissue integration requirements, while ambulatory surgical centers negotiate aggressively on standardized formats.
Supply Chain Analysis
Cold-chain logistics costs for cryopreserved tissues constitute a substantial delivered cost component, particularly for Brazilian and Argentine bovine pericardium routed through Costa Rican special economic zones. Raw material flows draw from South American herd clusters, processed collagen matrices, and synthetic polymer feedstocks. Single-source vulnerability concentrates in bovine tissue export restrictions and herd health crises. Distribution runs through direct hospital contracting networks bypassing traditional distributor markups, with tertiary cardiac centers in Germany and Japan securing multi-year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around cryopreservation specialists and diversified cardiovascular platforms, with EU MDR compliance costs forcing smaller regional patch fabricators toward acquisition or exit. Regulatory documentation burdens and viral inactivation validation timelines favor scaled processors with established notified body relationships.
For Market Incumbents: Deepen backward integration into Argentine and Brazilian raw material sourcing to secure herd supply against export volatility and capture margin from concentrated bovine pericardium flows. Invest in redundant sterilization capabilities—both gamma and electron beam—to satisfy hospital value analysis committees consolidating vendor lists. Defend against synthetic polymer substitution by emphasizing remodeling outcome documentation in pediatric valve reconstruction applications.
For New Entrants and Emerging Players: Capture procurement share in Indian cardiac surgery expansion as CDSCO harmonization with ISO 13485 opens import pathways into Mumbai and Delhi hospital networks. Target research institution partnerships for electrospun scaffold pilot programs in Switzerland and the Netherlands, where patient-specific manufacturing platforms command premium positioning. Lead with composite patch development combining biological handling precision with synthetic supply consistency.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated cardiovascular device conglomerates seeking surgical patch adjacencies to transcatheter valve platforms. Long-term viability favors processors with automated tissue handling systems and established EU MDR technical documentation capabilities. Watch for inflection in hospital value analysis committee vendor consolidation velocity across Texas and Florida integrated delivery networks.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR Article 10 compliance secures access to German and Italian cardiac surgery departments. |
| Hospital System Partnership | Direct contracting with Texas and Florida integrated delivery networks captures margin and volume commitment. |
| Backward Integration into Herd Supply | Argentine and Brazilian sourcing control mitigates raw material volatility and export restriction exposure. |
| Composite Patch R&D Partnership | Hybrid biological-synthetic laminates address valve reconstruction specialist demand for handling plus remodeling. |
| Reimbursement Strategy | Documented pediatric congenital repair outcomes support premium positioning against mechanical alternatives. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cardiac surgeons, hospital procurement managers, biomedical engineers, and GPO contracts managers. FDA 510(k) databases, EMA notified body documentation, CDSCO import records, and hospital procurement databases provided validation points. Bottom-up patch volume estimates by material category and application triangulated against top-down cardiac surgery procedure counts across the analysis window.
Granularity-level modeling distinguished biological, composite, synthetic, and resorbable patch categories by thickness specification and crosslinking chemistry. Segmentation dimensions included material origin, surgical application complexity, and care setting procurement scale. CAGRs derived from procedure volume trajectories, material substitution elasticities, and regulatory approval timeline impacts. Cryopreservation automation adoption curves and EU MDR compliance cost absorption rates informed processor margin projections throughout the forecast period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bovine pericardium supply disruptions, synthetic polymer substitution acceleration, and EU MDR enforcement variability. Forecasts reflect documented assumptions regarding cardiac surgery volume sustainability, viral inactivation validation standard stability, and hospital vendor consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Root Canal Irrigators Market
Medical Devices
Tattoo Removal Devices Market
Medical Devices
Global Positive Airway Pressure Devices Market
Medical Devices
Global Blood Processing Devices and Consumables Market
Medical Devices
Laser BPH Devices Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Germany Spinal Surgery Devices Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Breast Cancer Core Needle Biopsy Market
Medical Devices
Distraction Osteogenesis Devices Market
Medical Devices
Oxygen Generator Market
Medical Devices
Cervical Retractors Market
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Implantable Drug Delivery Devices Market