
 Smart Medical Devices Market | 2026-2036
Smart Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Medical Devices Market Analysis
Hospital procurement departments are unwinding their traditional reliance on standalone diagnostic equipment in favor of integrated remote patient monitoring ecosystems. Abbott Laboratories leverages its FreeStyle Libre platform to anchor continuous glucose monitoring within hospital-at-home programs. Medtronic competes through deep specialization in implantable cardiac devices with embedded Bluetooth telemetry. Philips Healthcare sustains geographic dominance across European homecare settings through its IntelliVue patient monitoring architecture.
Smart medical devices comprise sensor-integrated hardware coupled with embedded software algorithms that collect, transmit, and analyze physiological data in real time, typically operating through wireless protocols with power consumption below 100 milliwatts to enable portable or implantable form factors. These systems serve to automate clinical decision support, reduce acute care utilization, and enable proactive intervention outside traditional facility settings. Wearable devices occupy the largest revenue pool as consumer-grade fitness trackers migrate toward clinical-grade validation, while implantable devices capture the fastest expansion trajectory driven by miniaturized neurostimulation and drug delivery systems. Home monitoring devices concentrate margin pools among Medicare Advantage plans seeking to reduce hospital readmission penalties.
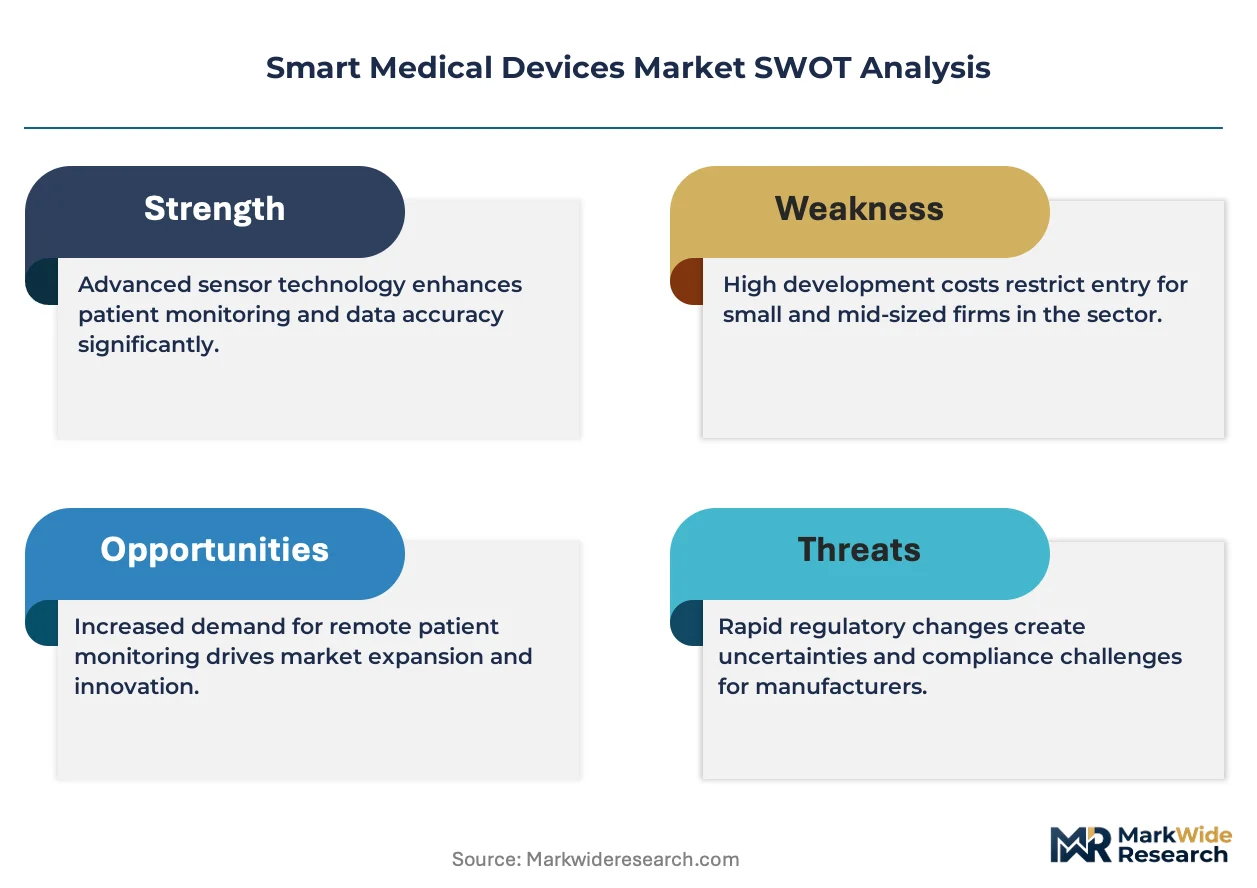
FDA premarket notification pathways and the EU Medical Device Regulation shape product development timelines, with the former accelerating software-as-a-medical-device approvals and the latter imposing stricter post-market surveillance obligations on Bluetooth-connected diagnostics. HIPAA security rules and GDPR data localization requirements constrain cloud computing architectures, forcing vendors to deploy regional data residency for patient telemetry. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring as payors determine which connected device categories warrant sustained fee-for-service or value-based compensation.
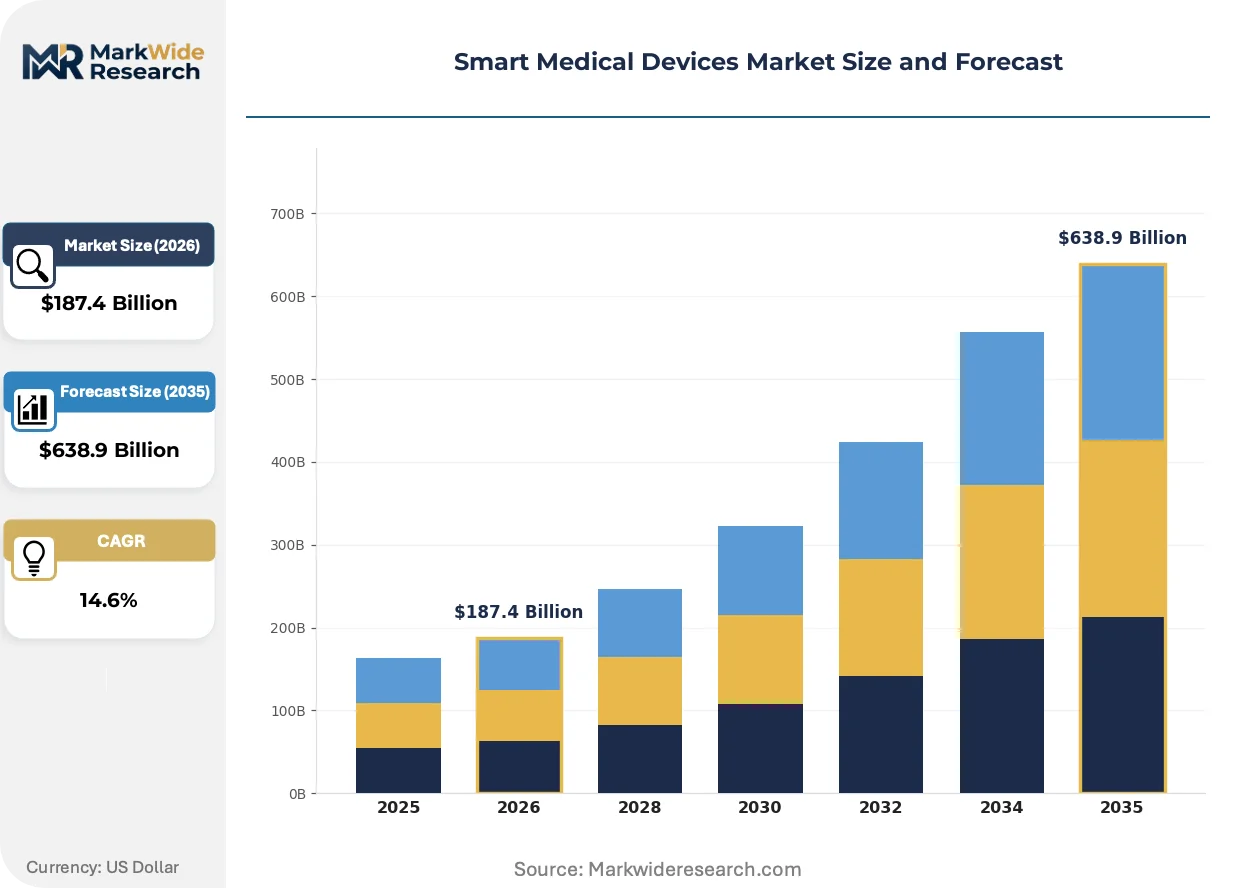
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around integrated remote patient monitoring ecosystems, compressing purchasing cycles for standalone diagnostic equipment while expanding long-term service contracts for connected device platforms.
Growth Catalysts
- FDA premarket notification pathways:The FDA's streamlined 510(k) clearance process for software-as-a-medical-device accelerates time-to-market for Bluetooth-enabled diagnostics, reducing regulatory friction for algorithm-driven monitoring tools.
- Medicare Advantage reimbursement expansion:Remote therapeutic monitoring codes now cover continuous glucose monitoring and cardiac telemetry, creating direct revenue streams for home monitoring device deployments.
- Miniaturized neurostimulation systems:Advances in sub-100 milliwatt wireless power consumption enable implantable drug delivery and neural modulation devices to operate without transcutaneous charging.
Market Restraints
- GDPR data localization mandates:European cloud computing architectures face mandatory regional data residency requirements for patient telemetry, fragmenting vendor infrastructure investments across multiple sovereign jurisdictions.
- Semiconductor foundry concentration:Advanced sensor fabrication relies on Taiwan-based capacity for sub-40nm process nodes, exposing supply chains to geopolitical disruption risk.
- Lithium-ion battery chemistry constraints:Implantable device longevity remains capped by energy density limitations, forcing trade-offs between device size and replacement interval.
Strategic Opportunities
- Japan's national digital health infrastructure:METI's Hospital at Home initiative creates procurement demand for continuous monitoring platforms in aging rural prefectures with limited acute care access.
- AI-driven predictive analytics convergence:Machine learning algorithms trained on continuous physiological streams enable preemptive clinical intervention before symptom onset.
- Direct-to-employer distribution channels:Self-insured corporations bypass traditional payor networks to deploy workforce wellness monitoring as preventive health expenditure.
Industry Challenges
- Embedded systems cybersecurity talent scarcity:HIPAA security rule compliance for wireless medical devices requires specialized firmware engineering expertise that outpaces current workforce supply.
- EU MDR post-market surveillance timelines:Bluetooth-connected diagnostics face extended clinical follow-up obligations that compress product refresh cycles and strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Medical Devices Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Devices, Implantable Devices, Home Monitoring Devices, Diagnostic Equipment Application: Chronic Disease Management, Remote Patient Monitoring, Rehabilitation, Surgical Assistance End User: Hospitals, Homecare Settings, Ambulatory Surgical Centers, Clinics Technology: Bluetooth, NFC, Wi-Fi, Cloud Computing |
| Companies Covered | Abbott Laboratories, Medtronic, Roche Diagnostics, Dexcom Inc., GE HealthCare, Siemens Healthineers, Philips Healthcare, Apple Inc., Masimo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Medical Devices Market Emerging Trajectories
Wireless protocol standardization and edge computing migration are compressing latency thresholds for real-time clinical decision support, enabling diagnostic-grade accuracy outside traditional facility settings.
Ultra-wideband positioning technology is fragmenting legacy Bluetooth Low Energy dominance in asset tracking and patient location systems. Hospital systems in Germany are deploying sub-meter accuracy infrastructure for operating room workflow optimization. This spatial precision is compressing capital equipment utilization gaps and enabling automated compliance logging for Joint Commission standards.
The EU Medical Device Regulation's software classification rules are redefining product development roadmaps for algorithm-enabled diagnostics. Manufacturers must now submit clinical evidence packages for machine learning updates that previously qualified as maintenance releases. Cardiology monitoring platforms face the steepest compliance burden, with notified body backlogs extending clearance timelines by eight to fourteen months.
Consolidated purchasing agreements are displacing unit-based procurement for connected monitoring hardware. United States health systems now negotiate enterprise-wide telemetry subscriptions spanning multiple device categories and care settings. This contractual bundling concentrates vendor selection authority within centralized supply chain functions, marginalizing departmental autonomy in equipment specification.
Smart Medical Devices Market Segmentation
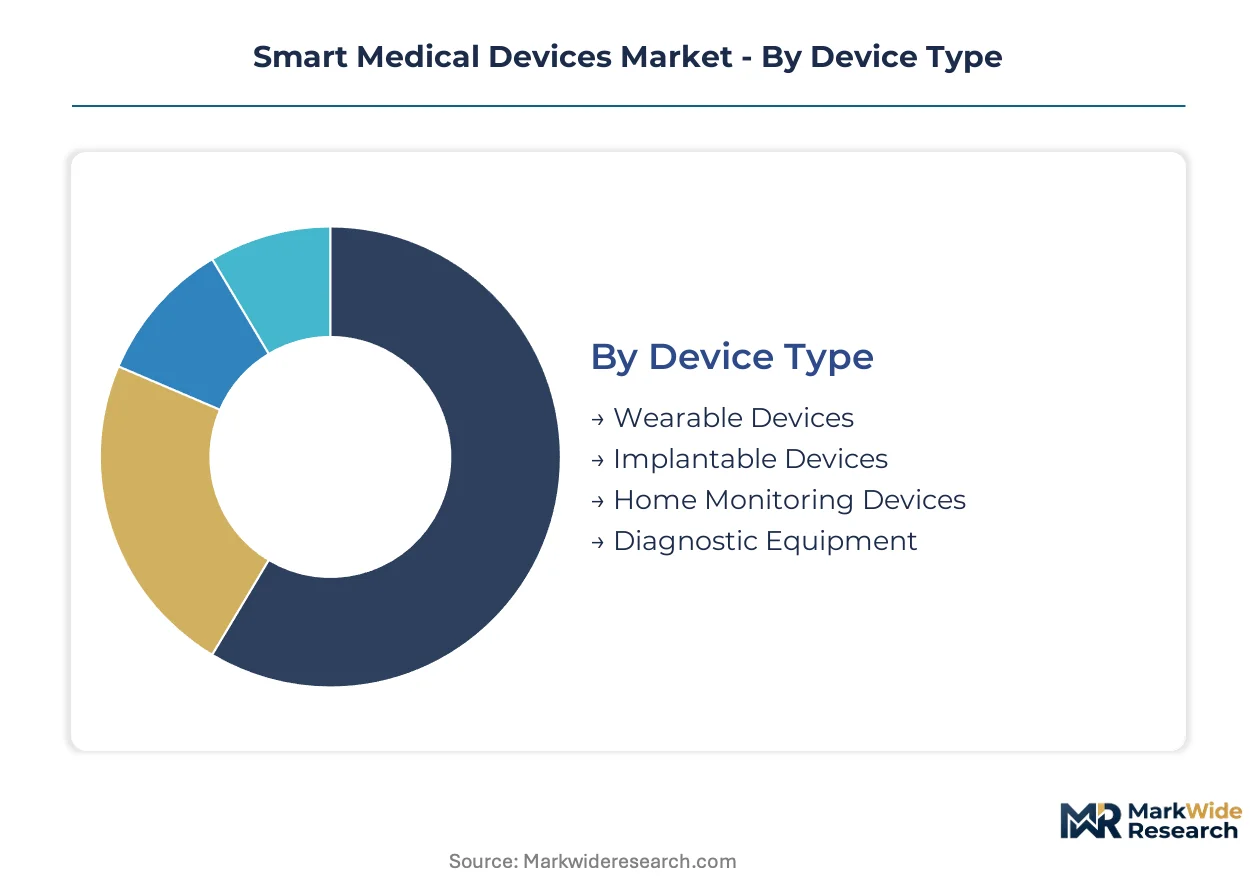
Segmentation in smart medical devices reveals divergent commercial architectures across hardware form factors, clinical use cases, and connectivity protocols. Procurement patterns and reimbursement pathways fragment sharply between implantable systems requiring surgical placement and consumer-adjacent wearables sold through retail channels.
Device Type:
Wearable devices dominate domestic consumption in the United States and Germany, while implantable systems generate concentrated export revenue to Japan's aging prefectures. Home monitoring equipment splits between Medicare Advantage direct procurement and European hospital-at-home program tenders.
- Wearable Devices:Sensor-integrated wristbands and patches operating below 100 milliwatts transmit continuous glucose and cardiac telemetry via Bluetooth Low Energy. United States hospital procurement departments anchor demand through remote patient monitoring subscriptions, though FDA 510(k) clearance timelines compress vendor margins.
- Implantable Devices:Miniaturized neurostimulation and drug delivery systems with embedded wireless telemetry require transcutaneous power transfer or sub-100 milliwatt internal cells. Japanese METI infrastructure spending in rural prefectures with limited acute care access concentrates the fastest-growing demand pool for these systems.
- Home Monitoring Devices:Blood pressure cuffs and pulse oximeters with cellular or Wi-Fi backhaul serve Medicare Advantage readmission reduction programs.
- Diagnostic Equipment:Bluetooth-enabled handheld ultrasound and ECG units bridge clinical-grade accuracy with point-of-care portability.
Wearable devices command the established base. The steepest expansion runs through implantable devices.
Application:
Application segmentation tracks reimbursement code availability and clinical workflow integration depth. Chronic disease management and remote patient monitoring attract venture funding and strategic acquisitions, while surgical assistance remains tethered to capital equipment refresh cycles.
- Chronic Disease Management:Continuous glucose monitoring and cardiac telemetry platforms automate insulin dosing and arrhythmia detection. United States Medicare Advantage plans and German statutory health insurers concentrate procurement authority for these systems.
- Remote Patient Monitoring:Cloud-connected vital sign streams enable hospital-at-home discharge protocols. Japan's METI Hospital at Home initiative in aging rural prefectures drives concentrated public tender activity for integrated monitoring platforms.
- Rehabilitation:Motion-sensing wearables track recovery metrics post-orthopedic surgery.
- Surgical Assistance:AR-enabled visualization and haptic feedback systems augment operative precision.
Chronic disease management commands the established base. Remote patient monitoring climbs the fastest.
End User:
End user segmentation reflects divergent purchasing authority and contract structures. Hospital systems consolidate vendor relationships around enterprise-wide telemetry subscriptions, while homecare settings fragment across direct-to-consumer and payor-sponsored distribution.
- Hospitals:Integrated patient monitoring architectures with centralized telemetry stations and wireless bedside devices dominate capital expenditure. German hospital systems deploy ultra-wideband positioning infrastructure for operating room workflow optimization.
- Homecare Settings:Discharged patients and aging-in-place populations receive continuous monitoring through Medicare Advantage-sponsored device deployments. United States reimbursement codes for remote therapeutic monitoring now cover cardiac and glucose telemetry.
- Ambulatory Surgical Centers:Same-day procedure facilities require portable diagnostic equipment with rapid sterilization protocols.
- Clinics:Primary care and specialty practices adopt handheld connected diagnostics for point-of-care decision support.
Hospitals command the established base. Homecare settings gain share fastest.
Technology:
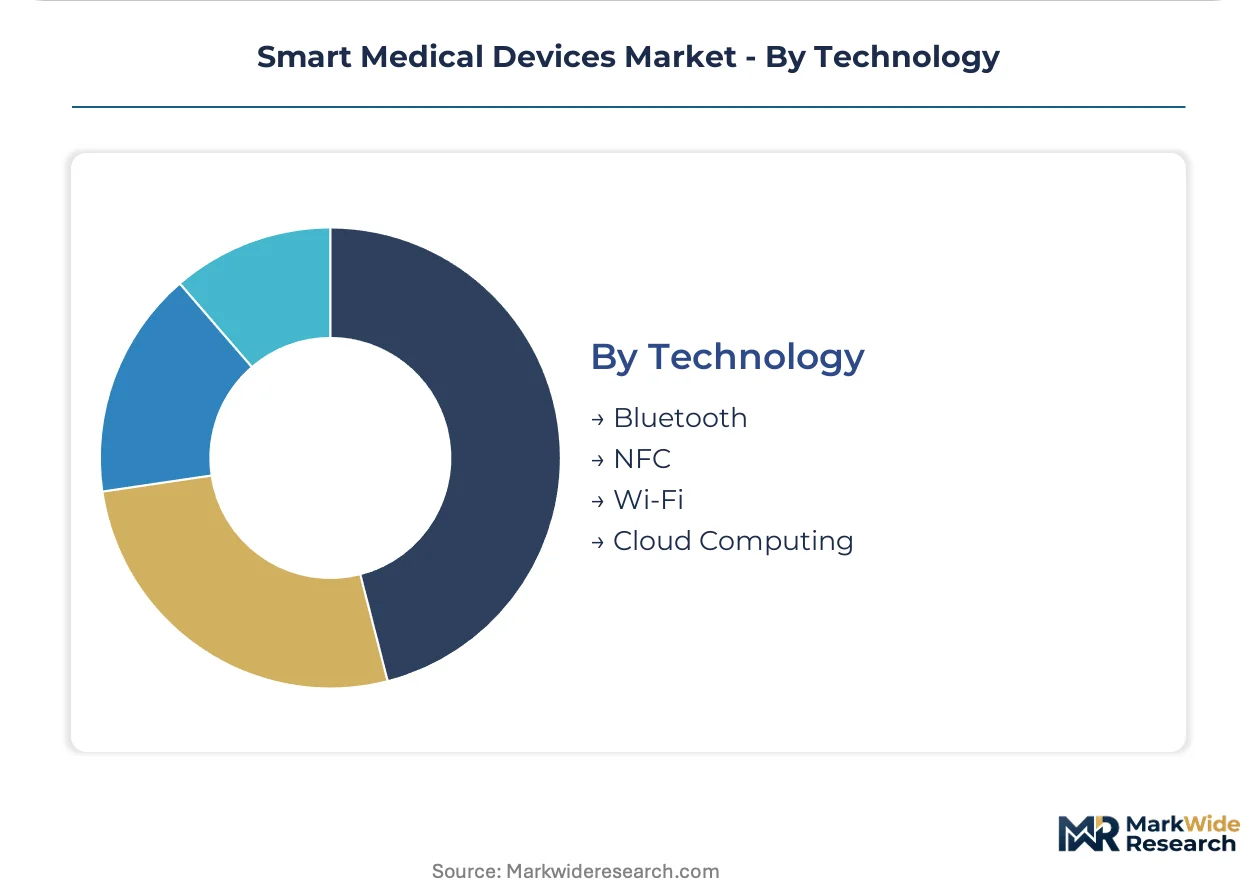
Technology segmentation tracks power consumption constraints, data security architecture, and interoperability standards. Bluetooth dominates near-field patient-worn applications, while cloud computing infrastructure faces GDPR data localization mandates fragmenting vendor deployment strategies.
- Bluetooth:Low Energy and Classic protocols enable sub-100 milliwatt operation for wearable and implantable form factors. FDA 510(k) premarket notification pathways accelerate clearance for Bluetooth-enabled diagnostics, compressing time-to-market for algorithm-driven monitoring tools.
- Cloud Computing:Real-time physiological data aggregation and machine learning inference require regional data residency to satisfy GDPR mandates in Europe and HIPAA security rules in the United States.
- Wi-Fi:Higher bandwidth protocols support diagnostic imaging transmission and firmware over-the-air updates.
- NFC:Near-field communication enables passive sensor activation and secure device pairing for implantable systems.
Bluetooth commands the established base. Cloud computing expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity for miniaturized sensors and wireless telemetry modules concentrates in Taiwan and South Korea, with advanced packaging facilities serving medical device OEMs across three continents. Regulatory clearance velocity and reimbursement policy divergence now determine where vendors prioritize commercial deployment.
United States
Medicare Advantage plans and hospital-at-home programs drive procurement for continuous glucose monitors and cardiac telemetry systems. FDA 510(k) premarket notification pathways compress clearance timelines for Bluetooth-enabled diagnostics. The Minneapolis medical technology corridor anchors implantable device R&D and clinical trial infrastructure.
Germany
Statutory health insurance funds expand reimbursement for remote patient monitoring to reduce acute care utilization. EU Medical Device Regulation post-market surveillance obligations extend clinical follow-up timelines for algorithm-enabled diagnostics. The Munich-Stuttgart medical technology belt concentrates notified body expertise and precision manufacturing for implantable neurostimulation systems.
Japan
METI's Hospital at Home initiative generates public tender demand for integrated monitoring platforms in aging rural prefectures. PMDA streamlined review pathways accelerate approval for software-as-a-medical-device with predicate device equivalence. The Kobe-Osaka medical device cluster specializes in miniaturized drug delivery systems with embedded wireless telemetry.
China
NMPA innovation review channels and provincial digital health infrastructure spending concentrate demand for home monitoring devices. Domestic semiconductor foundry investments in 28nm and 40nm nodes reduce import dependency for sensor fabrication. The Suzhou-Wuxi medical device manufacturing corridor scales production of Bluetooth-enabled diagnostic equipment for regional hospital procurement.
Switzerland
Swissmedic's reliance on EU notified body assessments synchronizes regulatory timelines with German and French market entry. Precision engineering clusters in the Lake Geneva region specialize in ultra-low-power wireless modules for implantable applications. Basel's pharmaceutical-device convergence ecosystem supports combined drug-delivery and monitoring platform development.
Smart Medical Devices Market Vendor Landscape
Concentration sits with diversified health technology conglomerates that span diagnostic hardware, embedded software, and clinical service contracts. The vendor base separates into three tiers: integrated platform providers with hospital system relationships, specialized sensor manufacturers with component supply agreements, and consumer electronics entrants leveraging retail distribution scale. Competitive positioning depends on FDA clearance velocity, Medicare reimbursement code alignment, and enterprise telemetry subscription conversion rates. M&A activity targets algorithm developers with clinical validation datasets, while strategic partnerships concentrate around cloud infrastructure and cybersecurity compliance.
Among diversified medical technology conglomerates, Abbott Laboratories and Medtronic exemplify platform-centric strategies anchored in continuous monitoring ecosystems. Dexcom Inc. occupies a specialized position within glucose-focused telemetry, representing the pure-play archetype against vertically integrated competitors. Siemens Healthineers and GE HealthCare sit within the imaging-to-monitoring convergence tier, leveraging installed base relationships for telemetry subscription attach.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Roche Diagnostics |
| Dexcom Inc. |
| GE HealthCare |
| Siemens Healthineers |
| Philips Healthcare |
| Apple Inc. |
| Masimo Corporation |
| Others |
Supply Flow & Price Mechanics
Ninety-day sensor wafer lead times from Taiwan-based foundries concentrate procurement leverage among hospital systems with enterprise-scale telemetry subscriptions, compressing margins for mid-tier vendors while amplifying pricing power for integrated platform providers with captive semiconductor allocation agreements.
Pricing Analysis
FDA 510(k) clearance tiering dictates the pricing tier structure across Bluetooth-enabled diagnostics, separating predicate-device premium subscriptions from de novo standard licenses and economy-grade consumer-wearable bundles. Price differentiation rests on clinical validation depth and Medicare reimbursement code alignment, with hospital procurement committees exhibiting lowest sensitivity due to bundled enterprise contracts and retail channels absorbing maximum pressure from direct-to-consumer fitness tracker commoditization.
Supply Chain Analysis
Taiwan and South Korea anchor sub-40nm sensor wafer fabrication for implantable neurostimulation systems, while China scales 28-40nm Bluetooth module production for home monitoring devices. Raw material dependencies span lithium-ion battery cells, medical-grade silicone encapsulants, and ultra-low-power wireless chipsets. Single-source vulnerability concentrates in Taiwan semiconductor foundry capacity. Distribution runs through hospital GPO procurement networks, direct-to-employer wellness channels, and retail pharmacy partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote therapeutic monitoring reimbursement expansion constitutes a structural inflection, transforming connected diagnostics from capital expenditure into recurring revenue infrastructure and compressing competitive differentiation around FDA clearance velocity.
For Market Incumbents: Consolidate vendor relationships through multi-year telemetry subscription bundling that locks hospital systems into integrated monitoring ecosystems. Acquire algorithm developers with validated clinical datasets to defend against software-as-a-medical-device entrants. Expand backward integration into regional cloud infrastructure to satisfy GDPR data residency mandates without third-party dependency. For New Entrants and Emerging Players: Cybersecurity firmware gaps in legacy implantable devices expose attack surfaces that hospital biomedical engineering teams cannot remediate independently. Target direct-to-employer wellness monitoring channels bypassing traditional payor network complexity. Pursue FDA 510(k) predicate pathway acceleration through established device equivalence rather than de novo classification. For Investors and Strategic Acquirers: Long-term, this sits as a data-monetization play because continuous physiological streams enable preemptive clinical intervention algorithms with recurring SaaS economics. Acquisition targets cluster around machine learning developers with multi-site hospital validation and notified body relationships. Watch Medicare Advantage readmission penalty adjustments as reimbursement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines for Bluetooth diagnostics reduce competitive entry barriers for algorithm-enabled monitoring tools. |
| Hospital System Partnership | Enterprise telemetry subscriptions with GPO contract anchoring displace unit-based procurement and departmental autonomy. |
| Software Companion Development | AI-driven predictive analytics trained on continuous glucose and cardiac streams enable preemptive clinical intervention. |
| Reimbursement Strategy | Remote therapeutic monitoring code alignment with Medicare Advantage plans creates direct revenue streams for home deployments. |
| CE Marking Pathway | EU MDR post-market surveillance compliance extends clinical follow-up obligations for algorithm updates in European markets. |
Methodological Framework
The analysis maps wearable glucose monitors, implantable cardiac telemetry, home monitoring devices, and diagnostic imaging systems, each validated through hospital procurement committees, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads. Primary fieldwork combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body assessments. Bottom-up device shipment modeling and top-down healthcare expenditure allocation triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by device form factor, clinical application, connectivity protocol, and end-user setting, with CAGRs derived from reimbursement code expansion trajectories and hospital-at-home program adoption curves. Forecast inputs incorporated semiconductor foundry capacity constraints, regulatory clearance velocity differentials, and payor policy evolution.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR surveillance timelines, and Medicare Advantage reimbursement structures; material policy shifts in HIPAA security rule enforcement or GDPR data localization mandates would require re-modeling. Recalibration cycles align with material shifts in reimbursement code coverage and semiconductor supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Canes and Crutches Market
Medical Devices
Global Vein Finders Market
Medical Devices
Organ Care Market
Medical Devices
Argentina Ultrasound Devices Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Electric Heated Eye Mask Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Non-Invasive Brain Stimulation System Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Morcellators Market