
 Global Surgical Microscopes Market | 2026-2036
Global Surgical Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Microscopes Market Foresight
The gap between premium fluorescence-enabled platforms and standard optical configurations is broadening as hospitals separate capital budgets for advanced neurosurgery suites from general operating room upgrades. Carl Zeiss Meditec AG leverages its fluorescence module integration to anchor the high-performance tier across European university hospitals. Leica Microsystems sustains competitive positioning through in-house optics manufacturing and deep specialization in ENT and neurosurgical workflows. Olympus Corporation competes on imaging sensor architecture, extending its endoscopy-derived sensor technology into surgical microscope platforms for the Japanese and North American markets.
Surgical microscopes are precision optical instruments combining stereoscopic eyepieces, motorized focusing mechanisms, and integrated illumination systems to deliver magnified, three-dimensional visualization of anatomical structures during operative procedures. Modern platforms incorporate LED light sources, digital image capture, and augmented reality overlays to support real-time navigation and documentation. Optical microscopes retain the largest installed base, though digital microscopy systems are capturing accelerated replacement cycles as hospitals prioritize connectivity and remote consultation readiness. Neurosurgery and ophthalmic surgery represent the most technically demanding application segments, where margin pools concentrate around fluorescence-guided resection and vitreoretinal visualization systems.
FDA 510(k) clearance pathways and EU MDR conformity assessment shape product development timelines and commercial access for manufacturers targeting the United States and European Union. ISO 13485 quality management certification and IEC 60601 electrical safety standards govern production systems and post-market surveillance obligations across major jurisdictions. Stakeholders must monitor evolving reimbursement codes for image-guided surgery and digital pathology integration to align R&D investment with hospital procurement criteria.
Market Dynamics
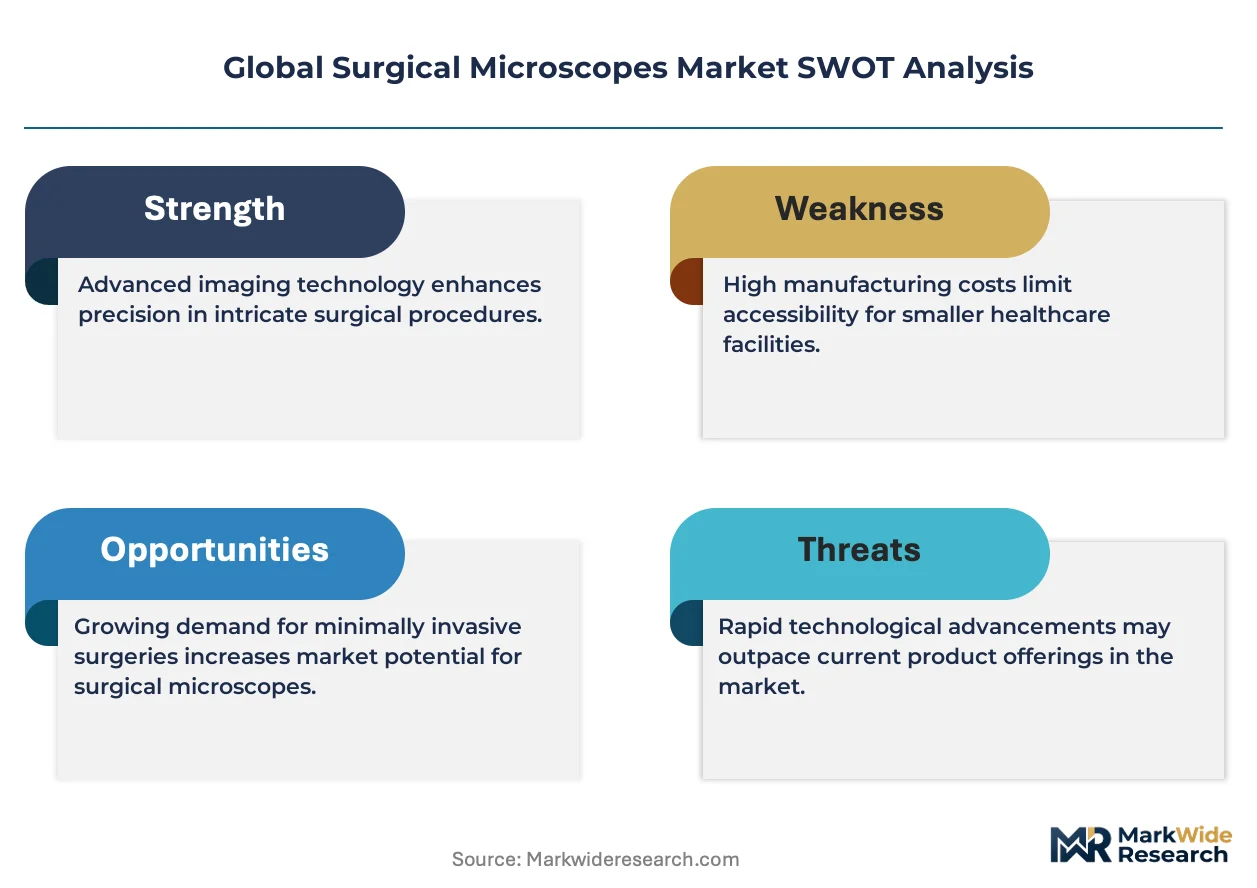
Fluorescence-guided visualization systems are fragmenting hospital capital allocation, forcing procurement teams to separate neurosurgery suite investments from general operating room equipment cycles. This bifurcation concentrates margin pools around modular platforms while compressing standard optical configurations into commodity procurement channels.
Growth Catalysts
- EU MDR conformity requirements:Tighter quality system mandates for Class IIa and IIb optical surgical devices are accelerating replacement of legacy microscopes in German and French university hospitals.
- Neurosurgical workflow digitization:Academic medical centers in Japan and the United States are prioritizing integrated image capture and augmented reality navigation for complex tumor resections.
- LED illumination architecture:Solid-state light sources with tunable spectral output are displacing halogen systems in ophthalmic and ENT procedures, reducing thermal tissue damage.
Market Restraints
- Precision optics supply concentration:German and Japanese optical component suppliers control critical lens grinding and coating capacity, creating bottleneck risk for microscope OEMs.
- Fluorophore reagent cost volatility:Indocyanine green and sodium fluorescein supply fluctuations inflate per-procedure costs for fluorescence-guided neurosurgery.
- FDA 510(k) pathway complexity:Substantial equivalence determinations for digital microscopy platforms with AI overlays extend premarket review timelines.
Strategic Opportunities
- India hospital infrastructure expansion:Government medical college upgrades and private tertiary care construction create first-time demand for mid-tier surgical microscopes.
- Telepathology integration:Digital microscopy platforms with real-time remote consultation capabilities address specialist scarcity in rural United States health systems.
- PLI scheme alignment:India's production-linked incentive framework for medical devices offers cost advantages for domestic assembly of optical surgical equipment.
Industry Challenges
- Optical engineer talent scarcity:Specialized expertise in stereoscopic lens design and precision mechanical alignment is concentrating at legacy German and Japanese manufacturers.
- ISO 13485 certification timelines:Quality management system audits for fluorescence module integration add 8-14 months to product launch schedules.
- Legacy OR integration complexity:New digital platforms must interface with existing surgical navigation systems and hospital PACS infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Microscopes Market |
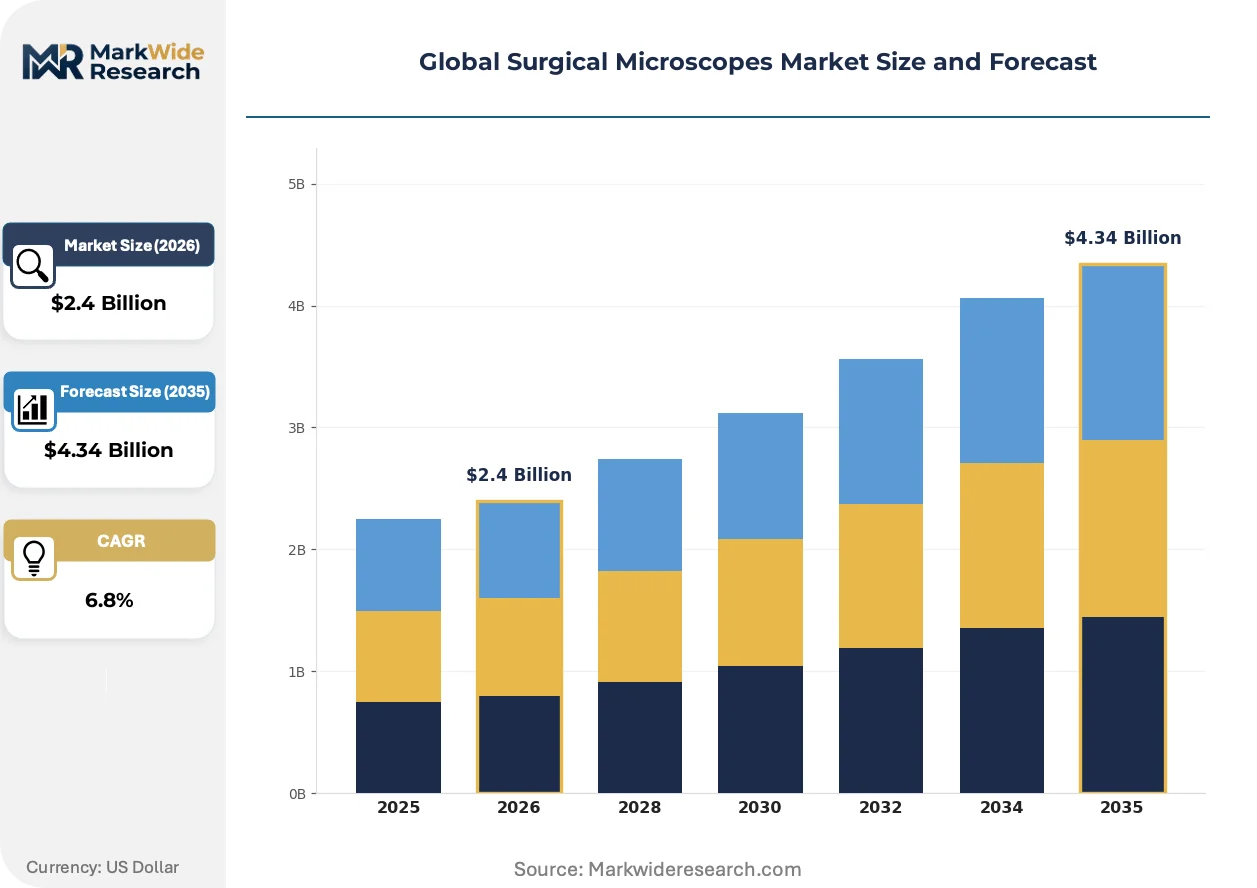
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Microscopes, Digital Microscopes, Stereo Microscopes, Fluorescence Microscopes, Confocal Microscopes Application: Neurosurgery, Ophthalmic Surgery, Dental Surgery, ENT Surgery, Orthopedic Surgery End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutes, Diagnostic Centers Technology: 3D Visualization, LED Illumination, Motorized Focus, Image Fusion, Autofocus Systems |
| Companies Covered | Haag-Streit Group, Topcon Corporation, Carl Zeiss Meditec AG, Seiler Instrument Inc., Alltion (Wuzhou) Co., Ltd., Leica Microsystems, Olympus Corporation, Global Surgical Corporation, Alcon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Microscopes Market Shifts & Advancements
Computational imaging and sensor fusion are displacing purely optical architectures, compressing the distinction between microscope hardware and surgical navigation software. Vendors now compete on algorithmic enhancement of visual data rather than optical specification alone.
Hyperspectral imaging is rewriting surgical margin assessment by capturing tissue autofluorescence signatures across 16-32 discrete wavelength bands. Neurosurgery departments at Massachusetts General Hospital and Heidelberg University Hospital are piloting these systems for glioblastoma resection guidance. The technology is compressing the timeline between tumor visualization and pathological confirmation, enabling more aggressive resection strategies.
EU MDR Article 10 technical documentation requirements are forcing manufacturers to revalidate clinical evidence for legacy optical microscope platforms. German notified bodies are demanding extended post-market surveillance data for fluorescence modules classified as active therapeutic devices. Japanese PMDA alignment with MDR technical standards is creating convergent compliance burdens for multinational suppliers serving both markets.
Hospital procurement teams are unbundling after-sales service contracts from capital equipment purchases, pressuring OEMs to compete on standalone maintenance pricing. German university hospitals are leading this shift, negotiating multi-vendor service agreements through centralized purchasing consortia. The model is displacing traditional full-service contracts in North American academic medical centers seeking operational expenditure flexibility.
Global Surgical Microscopes Market Segmentation
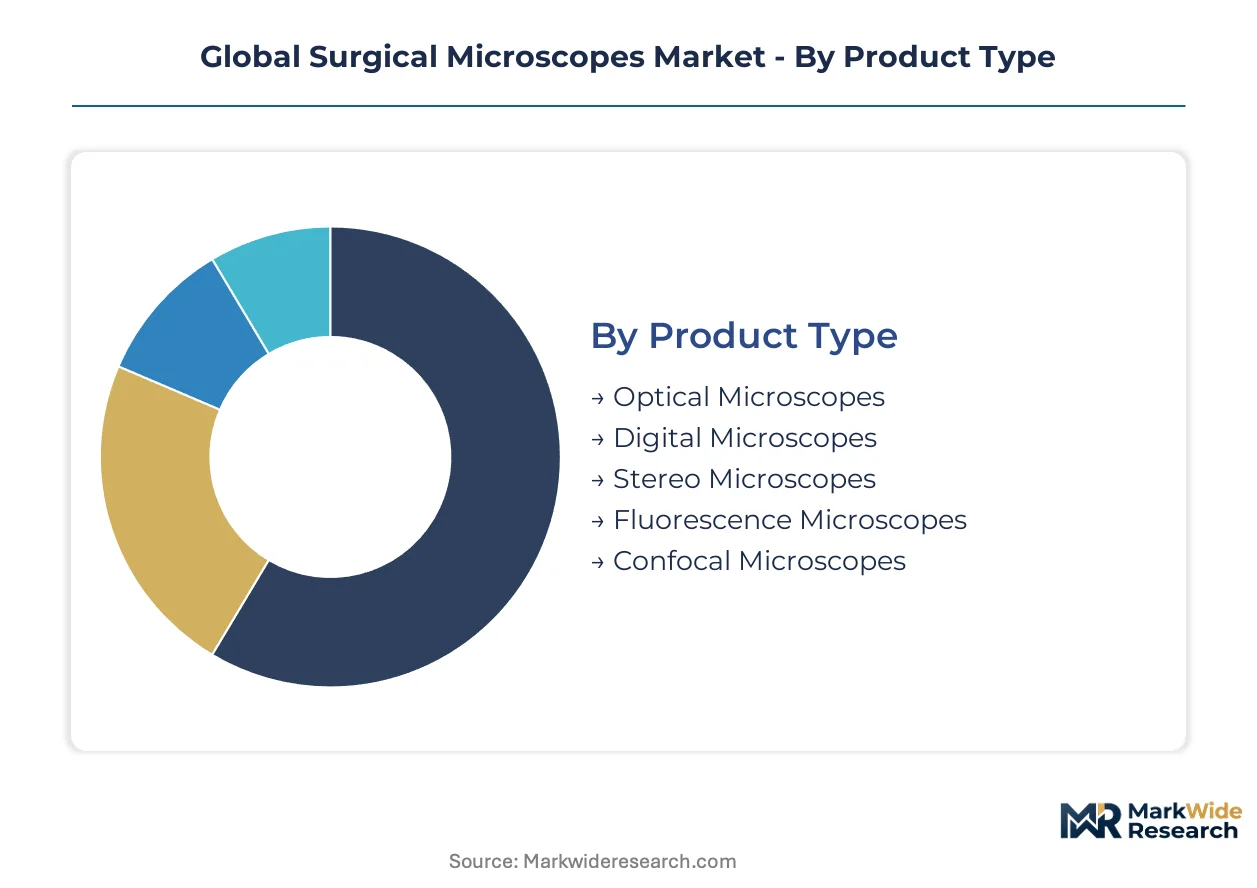
Surgical microscope segmentation reveals how capital allocation bifurcates between premium fluorescence-enabled platforms and standard optical configurations. Procurement teams increasingly separate neurosurgery suite investments from general operating room equipment cycles, fragmenting vendor pricing power across distinct budget lines.
Product Type:
Capital intensity concentrates in fluorescence and confocal architectures, where modular imaging systems demand dedicated infrastructure and specialized training protocols.
- Optical Microscopes:Conventional stereoscopic designs with halogen or LED illumination retain the largest installed base across general surgery suites. Demand concentrates in Indian government medical colleges and Southeast Asian district hospitals where procurement prioritizes durability over advanced imaging capabilities.
- Digital Microscopes:Sensor-based platforms with integrated image capture and PACS connectivity are capturing accelerated replacement cycles in United States academic medical centers. Hospital capital expenditure here prioritizes remote consultation readiness and surgical workflow documentation.
- Stereo Microscopes:Entry-level configurations serve dental and minor ENT procedures in ambulatory settings.
- Fluorescence Microscopes:Indocyanine green and sodium fluorescein integration enables real-time vascular and tumor margin visualization in complex neurosurgery.
- Confocal Microscopes:Optical sectioning technology delivers cellular-resolution imaging for research-intensive university hospital pathology departments.
Most installed capacity flows through Optical Microscopes. Expansion is steepest in Digital Microscopes.
Application:
Technical complexity and reimbursement rates concentrate margin pools in neurosurgical and ophthalmic visualization systems, separating premium procurement from commodity equipment cycles.
- Neurosurgery:Fluorescence-guided resection systems with augmented reality navigation command the highest capital allocations in German and Japanese university hospitals. Massachusetts General Hospital and Heidelberg University Hospital are piloting hyperspectral imaging for glioblastoma margin assessment, compressing timelines between tumor visualization and pathological confirmation.
- Ophthalmic Surgery:Vitreoretinal visualization demands precise stereoscopic optics with tunable LED spectral output to minimize thermal tissue damage. Japanese and United States specialty eye hospitals prioritize motorized focusing mechanisms for macular procedures.
- Dental Surgery:Compact stereo configurations serve implantology and endodontic procedures in private practice settings.
- ENT Surgery:Leica Microsystems maintains deep specialization here, with workflows optimized for otologic and laryngeal microsurgery.
- Orthopedic Surgery:Spine and hand procedures utilize mid-tier optical platforms with portable mounting systems.
Neurosurgery commands the premium tier of capital expenditure. Ophthalmic Surgery is gaining share fastest as aging populations drive cataract and retinal procedure volumes.
End User:
Procurement authority and service contract structures vary sharply between centralized hospital purchasing consortia and fragmented ambulatory settings.
- Hospitals:Academic medical centers in Germany, the United States, and Japan dominate demand for fluorescence-enabled platforms with integrated navigation. German university hospitals are unbundling after-sales service contracts from capital purchases, negotiating multi-vendor maintenance agreements through centralized purchasing consortia.
- Specialty Clinics:Ophthalmology and ENT-focused facilities prioritize compact digital systems with streamlined documentation workflows.
- Ambulatory Surgical Centers:United States outpatient facilities favor lease-based procurement models for standard optical configurations.
- Research Institutes:Confocal and hyperspectral systems serve translational oncology and neurobiology applications.
- Diagnostic Centers:Digital pathology integration drives demand for remote consultation-ready microscopy platforms.
Hospitals account for the dominant share of installed base. Specialty Clinics are climbing the fastest as procedure migration accelerates.
Technology:
Algorithmic enhancement of visual data is displacing pure optical specification as the primary competitive dimension, compressing hardware-software boundaries.
- 3D Visualization:Stereoscopic display systems with augmented reality overlays support real-time navigation during complex tumor resections in Japanese academic medical centers.
- LED Illumination:Solid-state architectures with tunable spectral output are displacing halogen across ophthalmic and ENT procedures.
- Motorized Focus:Precision mechanical alignment systems enable hands-free depth adjustment during microvascular anastomosis.
- Image Fusion:Preoperative MRI and CT integration with live microscopic views is rewriting surgical planning workflows in United States neurosurgery departments.
- Autofocus Systems:Computational tracking algorithms maintain sharpness during dynamic tissue manipulation.
LED Illumination represents the most mature installed base. Image Fusion is expanding most quickly as navigation software converges with optical hardware.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical engineering talent concentrates in German and Japanese industrial clusters, anchoring precision manufacturing capacity for surgical visualization systems. Hospital capital expenditure patterns diverge sharply between established markets with replacement cycles and emerging economies building first-time infrastructure.
United States
Academic medical centers in Boston and Baltimore drive fluorescence-guided neurosurgery adoption, prioritizing augmented reality navigation for complex tumor resections. FDA 510(k) clearance pathways for digital microscopy platforms with AI overlays extend premarket review timelines. Massachusetts General Hospital pilots hyperspectral imaging systems, compressing timelines between tumor visualization and pathological confirmation.
Germany
University hospitals in Heidelberg and Munich anchor European demand for modular fluorescence-enabled platforms with integrated surgical navigation. EU MDR Article 10 technical documentation requirements force manufacturers to revalidate clinical evidence for legacy optical microscope platforms. German notified bodies demand extended post-market surveillance data for fluorescence modules classified as active therapeutic devices.
Japan
Specialty eye hospitals in Tokyo and Osaka prioritize vitreoretinal visualization systems with motorized focusing mechanisms for macular procedures. METI and PMDA alignment with MDR technical standards create convergent compliance burdens for multinational suppliers. Japanese academic medical centers in the Kanto region lead 3D visualization adoption with stereoscopic display systems for real-time navigation.
India
Government medical college upgrades in Maharashtra and Karnataka create first-time demand for mid-tier surgical microscopes as tertiary care infrastructure expands. India's production-linked incentive framework for medical devices offers cost advantages for domestic assembly of optical surgical equipment. Private hospital construction in Delhi-NCR and Hyderabad concentrates procurement activity for standard optical configurations.
Switzerland
Research-intensive university hospital pathology departments in Zurich and Geneva drive confocal and hyperspectral system adoption for translational oncology applications. Swissmedic maintains stringent quality system requirements for Class IIa and IIb optical surgical devices. The Basel pharmaceutical corridor generates specialized demand for cellular-resolution imaging in drug development workflows.
Global Surgical Microscopes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the surgical microscope landscape, with in-house optics manufacturing anchoring premium positioning while modular assemblers capture mid-tier volume. The vendor base stratifies into three tiers: integrated optical specialists controlling lens grinding capacity, diversified medical technology conglomerates leveraging imaging sensor architectures, and regional fabricators serving price-sensitive procurement channels. Dominant competitive moves include backward integration into precision optical component supply and strategic partnerships with surgical navigation software developers.
Among German-integrated specialists, Carl Zeiss Meditec AG and Leica Microsystems exemplify the optical engineering archetype with captive lens manufacturing capacity. Olympus Corporation represents the diversified imaging conglomerate model, extending endoscopy-derived sensor technology into surgical visualization platforms. These three anchors illustrate how competitive positioning depends on controlling critical supply chain stages rather than final assembly alone.
| Leading Market Players |
|---|
| Haag-Streit Group |
| Topcon Corporation |
| Carl Zeiss Meditec AG |
| Seiler Instrument Inc. |
| Alltion (Wuzhou) Co., Ltd. |
| Leica Microsystems |
| Olympus Corporation |
| Global Surgical Corporation |
| Alcon Inc. |
| Others |
Supply & Pricing Matrix
Family-owned German optical specialists anchor the precision lens grinding tier, their captive manufacturing capacity translating into pricing discipline that resists commoditization pressure from modular assemblers in lower tiers. This ownership structure concentrates supply-side bargaining power while forcing procurement teams to navigate divergent service bundling strategies across vendor tiers.
Pricing Analysis
The bundled-versus-unbunded service split now defines transaction structures, with German university hospitals leading the shift toward standalone maintenance contracts negotiated through centralized purchasing consortia. Three-tier pricing stratification separates fluorescence-enabled neurosurgery platforms from standard optical configurations and economy dental stereo systems. Cost compression in mid-tier digital microscopy intensifies as Indian government medical colleges prioritize first-time procurement over performance specifications. Ambulatory surgical centers in the United States exhibit highest price sensitivity, while Japanese academic medical centers absorb premium positioning for integrated navigation systems.
Supply Chain Analysis
ISO 13485 certification gating restricts component sourcing to qualified optical houses in Germany, Japan, and Switzerland, where specialized lens grinding and coating capacity concentrates. Supply chains draw from precision glass substrates, rare-earth doped optical coatings, and high-resolution CMOS sensors as critical inputs. Single-source vulnerability around German-engineered stereoscopic objective assemblies creates bottleneck exposure for microscope OEMs lacking backward integration. Distribution runs through hospital capital equipment committees and specialized surgical device distributors serving academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical microscope market functions as a regulatory compounder, with EU MDR Article 10 technical documentation requirements forcing replacement cycles that accelerate demand for compliant platforms.
For Market Incumbents: Acquire fluorescence module engineering teams to secure active therapeutic device classification expertise before notified bodies extend surveillance mandates. Lock in multi-year service contracts with German purchasing consortia to defend against unbundling pressure. Prioritize ISO 13485 certification investment for integrated software overlays as FDA 510(k) pathways lengthen for AI-augmented platforms. For New Entrants and Emerging Players: Indian state government medical colleges represent the most penetrable buyer archetype, with PLI scheme alignment offering cost advantages for domestic assembly partnerships. Target mid-tier optical configurations for first-time infrastructure builds in Maharashtra and Karnataka. Deploy lease-based procurement models to bypass upfront capital constraints in Southeast Asian district hospitals. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators lacking captive lens manufacturing but holding CDSCO registrations for Indian market access. Five-to-ten year viability hinges on regulatory navigation capability rather than optical specification alone. Watch for PMDA-MDR technical standard convergence as the inflection signal triggering multinational consolidation of Japanese mid-tier assets.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Revalidation of legacy platforms unlocks continued access to German and French university hospital procurement channels. |
| Fluorescence Module Backward Integration | In-house indocyanine green integration capabilities reduce per-procedure cost volatility and supply reagent dependency. |
| Indian PLI Scheme Alignment | Domestic assembly cost advantages position mid-tier entrants for Maharashtra government medical college upgrades. |
| Telepathology Platform Development | Real-time remote consultation capabilities address specialist scarcity in rural United States health systems. |
| Hyperspectral Imaging Partnership | Collaboration with Massachusetts General Hospital and Heidelberg University Hospital pilots accelerates glioblastoma margin assessment adoption. |
Research Methodology
Direct dialogue with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and fluorescence-guided surgery specialists grounded qualitative insights across German, United States, and Japanese academic medical centers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body guidance documents, hospital procurement records, and CMS reimbursement code filings. Bottom-up and top-down triangulation reconciled equipment shipment data with capital expenditure disclosures from public health systems.
Bottom-up modeling aggregated segment-level demand across product type, application, and technology dimensions, while top-down approaches cross-checked aggregate market scale against macro healthcare infrastructure investment patterns. The analytical framework incorporated neurosurgical procedure volume trajectories, ophthalmic surgery demographic drivers, and digital pathology integration adoption curves throughout the forecast period. CAGRs derived from regression analysis of replacement cycle timing, regulatory compliance deadlines, and fluorescence module penetration rates.
Underlying measurement precision varies by segment; fluorescence-enabled platforms and confocal systems carry tighter precision than economy optical configurations due to concentrated vendor disclosure. Forecasts reflect assumptions around EU MDR implementation timelines, PLI scheme continuity, and fluorophore reagent supply stability. A model refresh is warranted upon material change in FDA digital pathology reimbursement determinations or Japanese PMDA technical standard alignment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
South Korea Massage Equipment Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Advanced Infusion Systems Market
Medical Devices
Next Generation Nebulizers Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
France Ultrasound Devices Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Spinal Fusion Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Syringeless Injector Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market