
 Active Implantable Devices Market | 2026-2036
Active Implantable Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Active Implantable Devices Market Intelligence
Swiss and German precision electronics manufacturers is realigning supply chains for bioresorbable substrates and miniaturized power management circuits. Medtronic leverages vertically integrated manufacturing across cardiac rhythm management to sustain leadership in implantable defibrillators. Abbott Laboratories anchors its competitive position through leadless pacemaker platforms that eliminate transvenous lead complications. Boston Scientific Corporation differentiates via deep specialization in neuromodulation systems for chronic pain and movement disorders.
Active implantable devices are electromechanical systems surgically placed within the human body to monitor, regulate, or restore physiological functions through continuous energy delivery and closed-loop feedback control, typically incorporating hermetically sealed titanium enclosures, platinum-iridium electrodes, and lithium-iodine batteries rated for multi-year service life. Their primary purpose is therapeutic intervention in conditions where pharmacological treatment proves inadequate or where permanent structural correction requires embedded instrumentation. Implantable defibrillators and cardiac pacemakers command the largest revenue pools given established reimbursement infrastructure and aging demographics requiring arrhythmia management. Neurostimulators represent the fastest-expanding category as leadless systems and wireless charging reduce surgical revision rates and expand candidacy for pain management and movement disorder treatment. Cochlear implants maintain mature, predictable growth trajectories concentrated in pediatric segments within otolaryngology centers.
FDA premarket approval pathways and EU MDR technical documentation requirements enforce stringent biocompatibility, electromagnetic compatibility, and long-term reliability standards that extend development timelines but erect substantial barriers against unqualified entrants. Japan's PMDA and South Korea's MFDS impose additional clinical evidence requirements for novel technologies such as retinal implants and Bluetooth-enabled remote monitoring systems, fragmenting market access procedures across jurisdictions. Stakeholders must monitor evolving cybersecurity guidance from FDA and IEC for connected implantable devices, as wireless connectivity becomes standard and remote patient monitoring shifts from optional feature to reimbursement prerequisite.
Market Dynamics
Leadless cardiac pacing architectures and wireless energy transfer systems are compressing surgical revision rates while expanding patient candidacy pools beyond traditional transvenous constraints.
Growth Catalysts
- Medicare Reimbursement Expansion:CMS coverage determinations for leadless pacemakers and cochlear implants in the United States eliminate prior authorization barriers for eligible patients.
- EU MDR Compliance Deadlines:Manufacturers accelerating technical documentation submissions for legacy device recertification create temporary procurement windows for compliant suppliers.
- Bluetooth-Enabled Remote Monitoring:Cardiac rhythm management systems with continuous telemetry reduce in-person follow-up burdens for electrophysiology centers.
Market Restraints
- Platinum-Iridium Electrode Supply Concentration:Specialty metallurgical processing for biocompatible electrode materials concentrates among Swiss and German precision manufacturers.
- EU MDR Clinical Evidence Requirements:Stricter equivalence pathways for implantable defibrillators extend recertification timelines and documentation costs.
- Pharmacological Arrhythmia Management:Antiarrhythmic drug protocols and catheter ablation techniques retain first-line status for paroxysmal atrial fibrillation.
Strategic Opportunities
- Underpenetrated Pediatric Cochlear Implantation:Early intervention programs in India and Brazil remain below OECD penetration rates for congenital sensorineural hearing loss.
- Bioresorbable Substrate Convergence:Temporary cardiac pacing and neurostimulation applications combining magnesium alloys with thin-film electronics eliminate explantation surgeries.
- Japan PMDA Sakigake Pathway:Priority review designation for novel retinal implants and closed-loop insulin delivery systems accelerates market entry timelines.
Industry Challenges
- Cybersecurity Validation for Connected Devices:FDA premarket submission requirements for wireless implantable systems demand specialized firmware auditing capabilities scarce among traditional quality assurance teams.
- Multi-Jurisdictional Clinical Trial Design:Divergent evidence standards between FDA, PMDA, and MFDS fragment pivotal study protocols for novel neuromodulation indications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Implantable Devices Market |
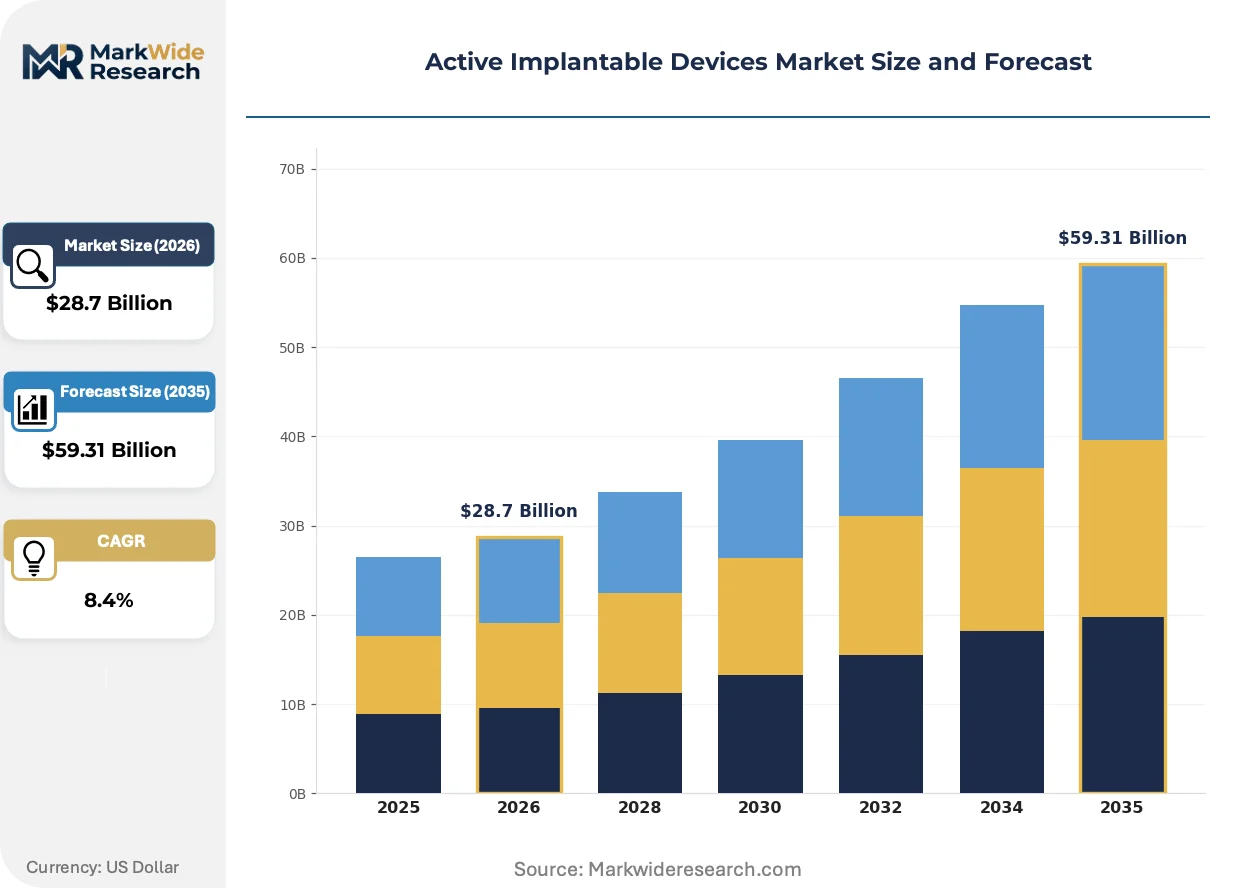
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Pacemakers, Cochlear Implants, Neurostimulators, Implantable Defibrillators, Retinal Implants Technology: Bioresorbable Electronics, Wireless Charging, Leadless Systems, Bluetooth Connectivity, Miniaturized Components Application: Arrhythmia Management, Hearing Restoration, Pain Management, Vision Enhancement, Movement Disorder Treatment End User: Cardiac Clinics, Otolaryngology Centers, Neurology Institutes, Ophthalmology Practices, Specialty Hospitals |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, BIOTRONIK, LivaNova PLC, Cochlear Limited, Sonova Holding AG, Nurotron Biotechnology Co. Ltd., MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Implantable Devices Market Strategic Shifts & Innovations
Wireless power transfer and closed-loop feedback algorithms are transforming implantable device architectures from fixed-output systems toward adaptive therapeutic platforms.
Leadless pacemaker technology is overtaking transvenous systems in electrophysiology center procurement decisions. Specialty hospitals in Germany and Japan now prioritize devices eliminating lead fracture and extraction risks. This transition is compressing service revenue models built around generator replacement and lead revision procedures.
EU MDR technical documentation requirements for implantable active devices enforce granular biocompatibility and electromagnetic compatibility testing protocols. Manufacturers must submit comprehensive clinical evaluation reports even for legacy product lines. Cardiac rhythm management portfolios face the steepest compliance burdens given device longevity claims and post-market surveillance obligations.
Electrophysiology departments increasingly bundle device procurement with long-term remote monitoring service agreements. Traditional distributor relationships give way to direct manufacturer partnerships covering implantation, follow-up, and data analytics. This restructuring concentrates procurement authority within integrated delivery networks in the United States and university hospital chains in Germany.
Active Implantable Devices Market Segmentation
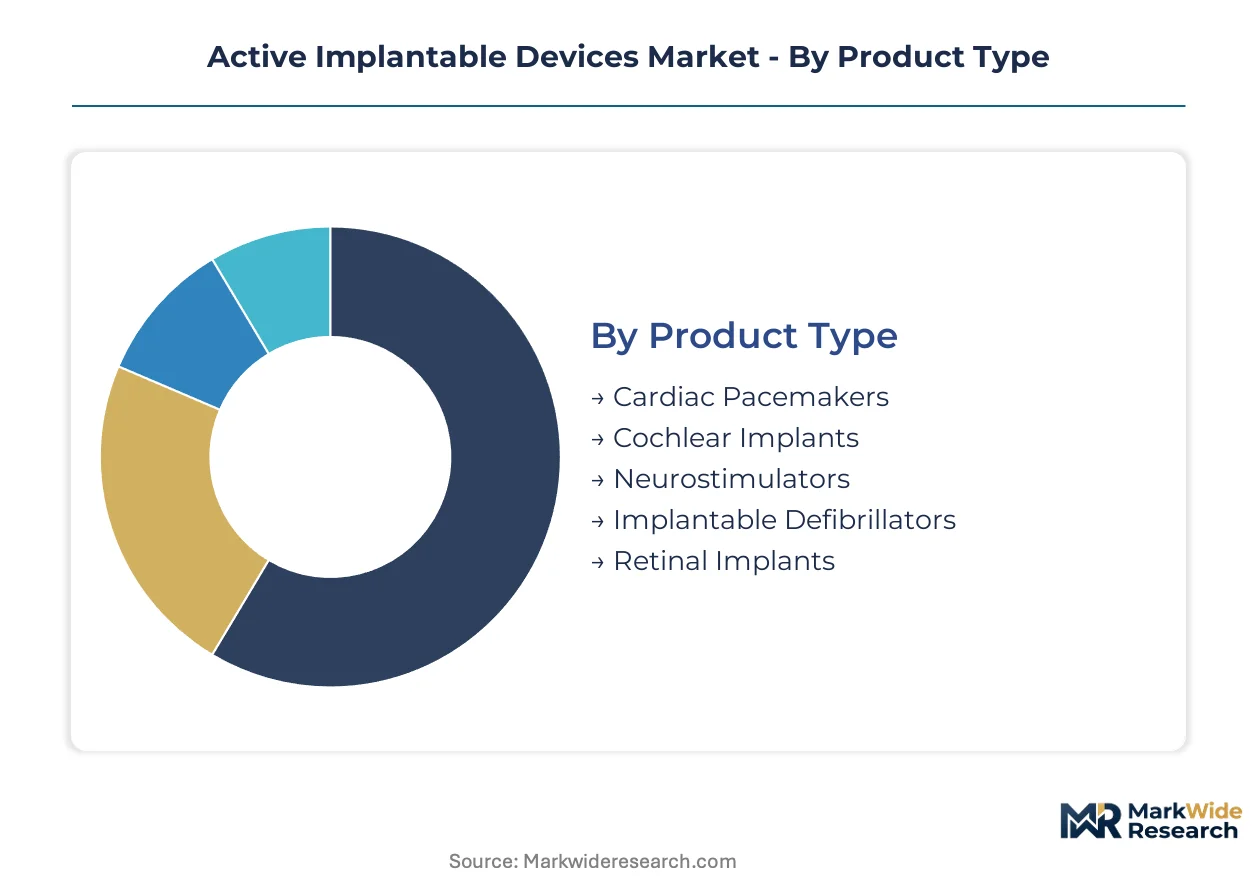
Segmentation in active implantable devices reveals how procurement authority, reimbursement pathways, and clinical workflow requirements fragment demand across distinct customer configurations. Understanding these divides exposes where technology differentiation commands premium positioning versus where standardization dominates purchasing decisions.
Product Type:
Purchasing committees weight device longevity claims against surgical revision risks when allocating capital across therapeutic categories.
- Cardiac Pacemakers:Electromechanical systems with lithium-iodine power cells and hermetic titanium enclosures restore sinus rhythm through transvenous or leadless electrode delivery. Specialty hospitals in Germany and the United States concentrate procurement of leadless architectures that eliminate lead extraction morbidity.
- Implantable Defibrators:High-voltage capacitors and sophisticated arrhythmia detection algorithms terminate ventricular fibrillation through tiered energy delivery. Medicare reimbursement pathways in the United States accelerate clinical uptake for primary prevention indications in ischemic cardiomyopathy patients.
- Neurostimulators:Closed-loop pulse generators with rechargeable power management address chronic pain and movement disorders through targeted neural modulation.
- Cochlear Implants:Multi-channel electrode arrays bypass damaged cochlear hair cells to restore auditory signal transduction for sensorineural hearing loss.
- Retinal Implants:Epiretinal or subretinal microelectrode arrays interface with remaining retinal ganglion cells for degenerative retinal disease intervention.
Cardiac pacemakers lead on scale; neurostimulators lead on momentum.
Technology:
Engineering architecture choices determine surgical invasiveness, device service intervals, and regulatory validation burdens.
- Leadless Systems:Self-contained pacing or sensing units anchor directly to endocardial tissue without transvenous conductor pathways. Electrophysiology centers in Japan prioritize these platforms to reduce long-term lead-related complications.
- Wireless Charging:Transcutaneous inductive power transfer eliminates percutaneous charging ports and extends rechargeable device longevity. FDA cybersecurity guidance for wireless energy transfer protocols complicates premarket submission timelines.
- Bluetooth Connectivity:Continuous telemetry streams enable remote patient monitoring and algorithm-based arrhythmia prediction.
- Bioresorbable Electronics:Magnesium alloy substrates with thin-film circuitry enable temporary pacing or neural stimulation without explantation surgery.
- Miniaturized Components:Advanced packaging of power management integrated circuits and hermetic feedthroughs enables smaller form factors.
Leadless systems dominate current procurement cycles; bioresorbable platforms show steepest expansion trajectory.
Application:
Clinical indication severity and alternative treatment availability shape reimbursement generosity and addressable patient pools.
- Arrhythmia Management:Sustained therapeutic intervention for bradyarrhythmias, tachyarrhythmias, and conduction disorders through electrical pacing or defibrillation. The United States concentrates demand given established electrophysiology infrastructure and favorable CMS coverage determinations.
- Pain Management:Spinal cord stimulation and peripheral nerve targeting for chronic intractable pain refractory to pharmacological intervention. EU MDR clinical evidence requirements for novel neuromodulation indications extend development timelines.
- Hearing Restoration:Cochlear implantation for congenital or acquired sensorineural deafness.
- Movement Disorder Treatment:Deep brain stimulation for Parkinson's disease, essential tremor, and dystonia.
- Vision Enhancement:Retinal prosthesis implantation for retinitis pigmentosa and age-related macular degeneration progression.
Arrhythmia management commands largest revenue concentration; pain management gains share fastest.
End User:
Facility type determines case volume thresholds, capital equipment requirements, and long-term service relationship structures.
- Specialty Hospitals:Dedicated cardiac, neurological, or otolaryngological institutions with high-volume implantation programs and integrated electrophysiology or surgical suites. Germany and Japan anchor procurement concentration for leadless pacemakers and neurostimulators.
- Cardiac Clinics:Outpatient electrophysiology centers focused on arrhythmia diagnosis, ablation, and device implantation. Bluetooth-enabled remote monitoring agreements increasingly bundle device procurement with longitudinal follow-up services.
- Neurology Institutes:Academic and clinical centers specializing in movement disorders, epilepsy, and chronic pain intervention.
- Otolaryngology Centers:Dedicated auditory and vestibular facilities performing cochlear implantation and auditory rehabilitation.
- Ophthalmology Practices:Retinal surgery specialists managing degenerative retinal disease progression.
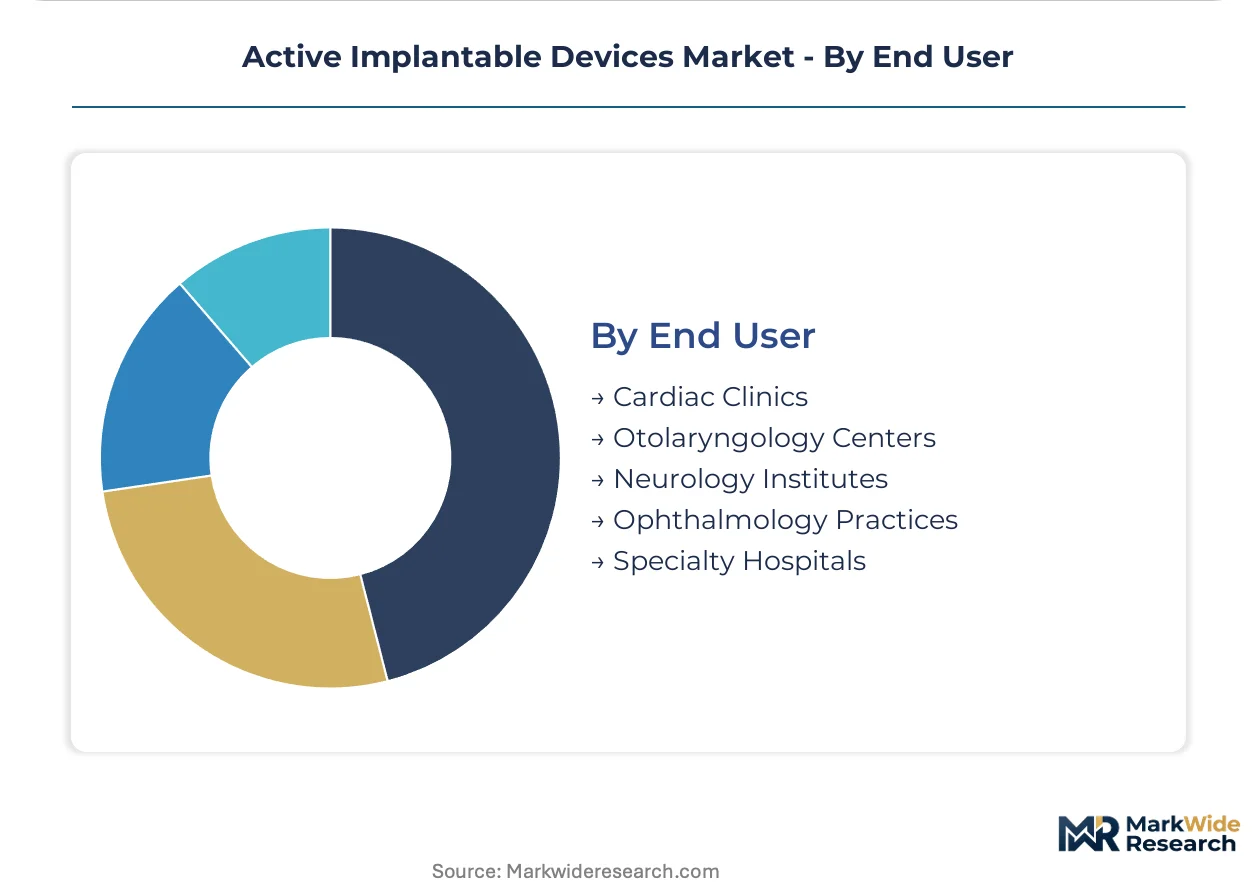
Specialty hospitals anchor volume; cardiac clinics drive technology transition velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers migrate production toward jurisdictions where FDA and EU MDR compliance costs diverge from domestic reimbursement premiums, creating arbitrage opportunities for Swiss precision metallurgy and German electronics packaging clusters serving both regulatory regimes.
United States
CMS coverage determinations for leadless pacemakers and cochlear implants compress prior authorization timelines. FDA breakthrough device designation pathways accelerate market entry for novel neurostimulation platforms. Minneapolis and Boston anchor electrophysiology device development, with integrated delivery networks consolidating procurement authority.
Germany
Specialty hospitals in Bavaria and Baden-Württemberg expand leadless pacemaker procurement to reduce long-term lead extraction morbidity. EU MDR technical documentation deadlines compress recertification timelines for legacy cardiac rhythm management portfolios. Erlangen and Berlin concentrate precision electronics manufacturing for biocompatible electrode substrates.
Japan
PMDA Sakigake priority review designation accelerates market entry for retinal implants and closed-loop insulin delivery systems. Aging demographics expand arrhythmia management candidacy pools beyond traditional transvenous constraints. Tokyo and Osaka electrophysiology centers prioritize wireless charging architectures to minimize surgical revision rates.
Switzerland
Specialty metallurgical processing for platinum-iridium electrodes concentrates among precision manufacturers serving both EU MDR and FDA submission requirements. Swissmedic maintains alignment with EU regulatory frameworks while preserving domestic clinical trial infrastructure. Zurich and Geneva anchor bioresorbable substrate research converging magnesium alloys with thin-film electronics.
China
NMPA clinical evidence requirements for novel implantable devices extend development timelines but create procurement windows for domestically manufactured cardiac pacemakers. Provincial hospital procurement reforms concentrate authority within tier-three cardiovascular centers. Shanghai and Shenzhen electronics clusters advance miniaturized power management circuit packaging.
Active Implantable Devices Market Key Industry Players
United States producers anchor the premium-tier device segment; German and Swiss specialists hold precision component supply positions. The vendor base concentrates around vertically integrated cardiac rhythm management portfolios and neuromodulation-focused technology licensors. Three archetypes dominate: diversified medical technology conglomerates with electrophysiology divisions, pure-play neuromodulation developers, and precision electronics subcontractors serving hermetic packaging requirements. Competitive moves center on backward integration into biocompatible electrode metallurgy and exclusive long-term remote monitoring service agreements with integrated delivery networks.
Within the diversified conglomerate tier, Medtronic and Abbott Laboratories occupy positions exemplifying vertical control across cardiac rhythm management value chains. Boston Scientific Corporation represents the neuromodulation specialization archetype, with its portfolio weighted toward chronic pain and movement disorder applications. These three entities anchor competitive dynamics through differentiated approaches to leadless architecture deployment and wireless connectivity integration.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| BIOTRONIK |
| LivaNova PLC |
| Cochlear Limited |
| Sonova Holding AG |
| Nurotron Biotechnology Co. Ltd. |
| MicroPort Scientific Corporation |
| Others |
Cost & Logistics Intelligence
Platinum-iridium electrode metallurgy anchors cost structures from Swiss and German precision processors through to cardiac rhythm management OEMs, with biocompatible substrate pricing stratifying across FDA breakthrough designation tiers and EU MDR compliance grades downstream.
Pricing Analysis
Distributor margins compress as direct manufacturer partnerships with integrated delivery networks displace traditional channel relationships. Three-tier pricing structure across premium, standard, and economy levels separates leadless pacemaker platforms with wireless charging from transvenous legacy systems and commodity-priced basic pacing units. Pricing pressure stems from Medicare reimbursement compression for generator replacement procedures. Cardiac clinics exhibit highest price sensitivity due to bundled service agreement economics, while specialty hospitals in Germany prioritize device longevity over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements for hermetic titanium enclosures and lithium-iodine power cells mandate qualified suppliers in both Switzerland and Germany for cardiac rhythm management portfolios. Raw material dependencies center on platinum-iridium electrode alloys, bioresorbable magnesium substrates, and miniaturized power management integrated circuits. Single-source vulnerability concentrates in specialty metallurgical processing for biocompatible electrodes. Distribution runs through direct manufacturer partnerships with hospital systems and GPO contracts rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU MDR recertification deadlines and FDA breakthrough device pathways accelerate procurement windows for compliant suppliers.
For Market Incumbents: To counter leadless pacemaker technology displacement of transvenous service revenue models, Medtronic and Abbott Laboratories should deepen backward integration into platinum-iridium electrode metallurgy and secure exclusive long-term remote monitoring agreements with integrated delivery networks. Capacity addition in Swiss precision electronics clusters preserves supply security for bioresorbable substrate convergence. For New Entrants and Emerging Players: Specialty hospitals in India and Brazil present the most penetrable channel partner type for pediatric cochlear implantation platforms, given underpenetration rates versus OECD benchmarks. Targeting otolaryngology centers with early intervention program partnerships offers lower competitive density than saturated arrhythmia management segments. Japan PMDA Sakigake pathway acceleration for retinal implants provides regulatory fast-track differentiation. For Investors and Strategic Acquirers: Roll-up economics work for neuromodulation-focused technology licensors because pain management and movement disorder applications fragment across pure-play developers lacking wireless charging or closed-loop algorithm capabilities. Five-to-ten year viability hinges on FDA cybersecurity validation for connected devices becoming standard reimbursement prerequisite. Watch for Bluetooth-enabled remote monitoring shifting from optional feature to mandatory coverage determination as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates market entry timelines for novel neurostimulation platforms ahead of standard PMA pathways. |
| EU MDR Technical Documentation Submission | Creates temporary procurement windows for compliant suppliers as legacy device recertification deadlines compress. |
| Hospital System Partnership | Bundles device procurement with longitudinal remote monitoring services, displacing traditional distributor relationships. |
| Backward Integration into Electrode Metallurgy | Captures margin from Swiss precision manufacturers while securing supply for bioresorbable substrate development. |
| Reimbursement Strategy | CMS coverage determinations for leadless pacemakers eliminate prior authorization barriers and accelerate clinical uptake. |
Research Approach
Multiple input streams — electrophysiology center purchasing committee interviews, precision electronics manufacturer technical documentation, and CMS Medicare reimbursement database analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged cardiac device development executives, hospital GPO contracts managers, biomedical engineers, and regulatory affairs specialists across the United States, Germany, and Japan. Secondary validation drew from FDA PMA filings, EU MDR technical documentation databases, hospital procurement records, and specialty hospital capital expenditure disclosures.
Historical volume trajectories were cross-referenced against panel input from device manufacturers and purchasing committees to model expansion across product type, technology architecture, clinical application, and end-user facility categories. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EU MDR compliance timeline acceleration, Medicare reimbursement pathway evolution, and Bluetooth-enabled remote monitoring adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA cybersecurity guidance finalization and platinum-iridium supply concentration disruptions. Deviation in EU MDR equivalence pathway strictness for implantable defibrillators would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Video Dermatoscope Market
Medical Devices
ADA Substitute Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Ultrasonic Nebulizers Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
Disposable Medical Devices Sensors Market