
 Global Surgical/Operating Microscopes Market | 2026-2036
Global Surgical/Operating Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical/Operating Microscopes Market Foresight
Market Context with Strategic Players
German precision optics manufacturing is consolidating as the anchor supply base for high-end surgical microscopy. Carl Zeiss Meditec AG leverages its Oberkochen fabrication complex to sustain captive lens grinding and coating capabilities that competitors struggle to replicate. Leica Microsystems anchors its position through Wetzlar-based engineering teams specializing in neurosurgical fluorescence integration. Olympus Corporation competes from Tokyo by controlling endoscope-to-microscope workflow bundles sold into Asian academic medical centers.
Technical Definition and Structural Segments
Surgical and operating microscopes are precision optical instruments combining stereoscopic eyepieces, motorized zoom objectives, and coaxial illumination systems to deliver magnified, illuminated views of anatomical structures during invasive procedures. These devices typically achieve magnification ranges of 4x to 40x with working distances of 200-400 millimeters, enabling surgeons to execute microvascular anastomoses and neural dissections with submillimeter accuracy. Ceiling-mounted systems dominate installed base value in tertiary hospitals where OR utilization rates justify permanent infrastructure investment, while portable configurations represent the fastest-expanding category as ambulatory surgery centers seek flexible equipment deployment across multi-procedure suites. Fluorescence imaging technology commands disproportionate margin pools because indocyanine green angiography modules require proprietary dye delivery systems and software-locked consumable protocols.
Regulatory Framework and Forward Outlook
The FDA enforces 21 CFR 892.1900 classification for diagnostic microscope accessories while the EU Medical Device Regulation mandates notified body oversight for surgical microscopes under Class IIa or higher risk tiers. Japan's PMDA requires QMS conformity assessments and clinical efficacy documentation for fluorescence-enhanced surgical optics prior to market authorization. Stakeholders must monitor evolving software-as-medical-device interpretations as AI-guided image enhancement modules trigger additional premarket scrutiny across multiple jurisdictions.
Market Dynamics
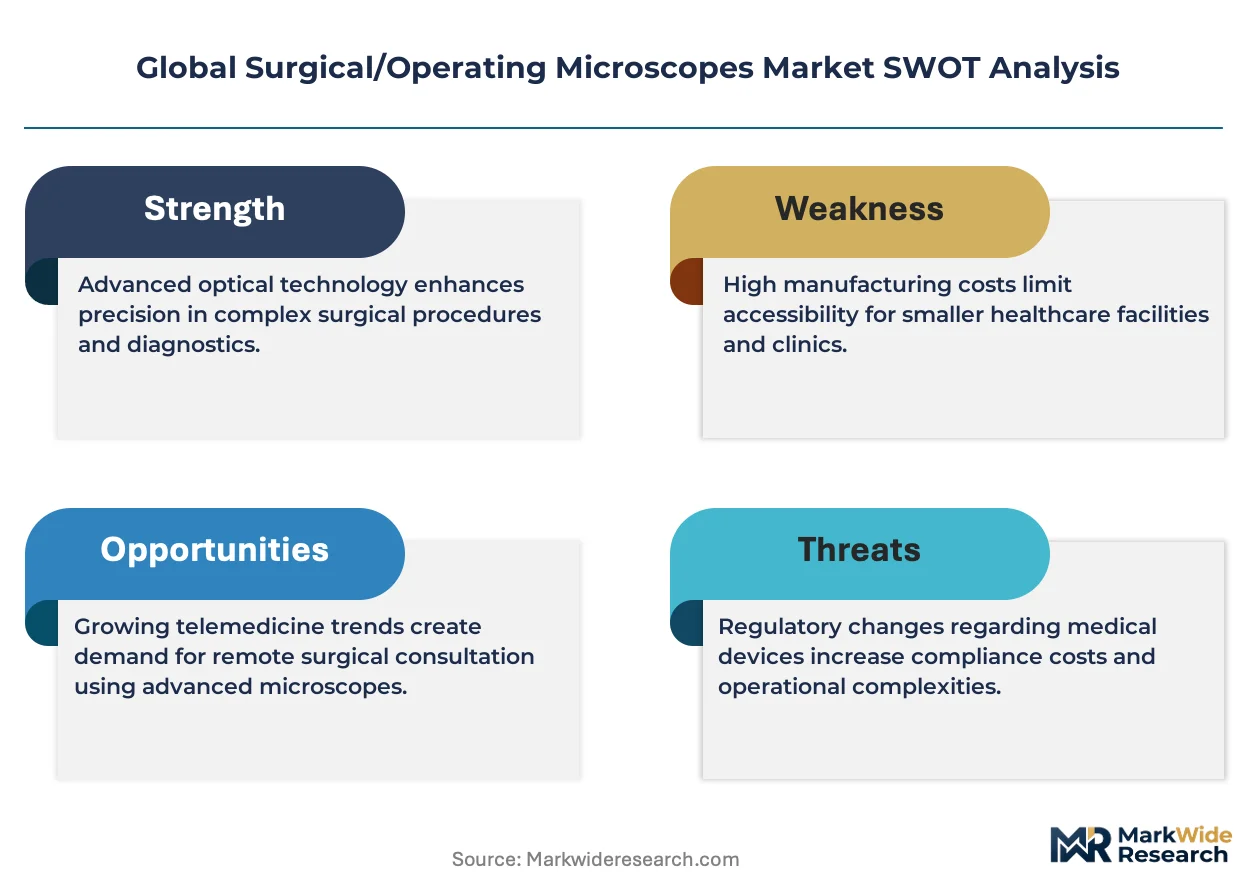
Fluorescence-guided surgical workflows are compressing replacement cycles for legacy optical systems, forcing capital allocation toward modular upgrade architectures rather than full-platform swaps.
Growth Catalysts
- EU Medical Device Regulation:MDR Class IIa oversight mandates for surgical optics are accelerating hospital procurement of certified fluorescence-enabled systems to preempt compliance gaps.
- Neurosurgical fluorescence integration:Indocyanine green angiography modules enable real-time vascular perfusion assessment, driving demand from academic medical centers performing cerebrovascular bypass procedures.
- German precision optics cluster:Oberkochen and Wetzlar fabrication ecosystems sustain captive lens grinding capabilities that shorten supply lead times for high-NA objective assemblies.
Market Restraints
- Rare-earth coating materials:Lanthanum and fluorite lens element supply concentrates in Chinese processing facilities, exposing cost volatility to German and Japanese microscope assemblers.
- Technical limitation in deep-tissue penetration:Near-infrared fluorescence signal attenuation beyond 10 millimeters restricts functional utility in oncologic resection margins.
- FDA 510(k) pathway congestion:Software-as-medical-device reclassifications for AI-enhanced image processing modules extend premarket review timelines for fluorescence algorithm updates.
Strategic Opportunities
- India tertiary hospital expansion:Government-funded medical college upgrades under the PLI scheme for medical devices create first-time demand for ceiling-mounted neurosurgical microscopes in Delhi and Mumbai clusters.
- Augmented reality-fluorescence convergence:Heads-up display overlays integrating ICG signal projection with anatomical navigation are enabling surgeon workflow consolidation in hybrid OR installations.
- Ambulatory surgery center channel:Portable microscope configurations with rapid sterilization cycles penetrate multi-procedure suites seeking equipment utilization flexibility across ophthalmology and plastic surgery service lines.
Industry Challenges
- Optomechatronics engineering scarcity:Specialized talent pools capable of integrating motorized zoom kinematics with thermal-stable optical benches remain concentrated in southern Germany and Tokyo metropolitan zones.
- Legacy OR infrastructure retrofit:Ceiling suspension load ratings and HVAC filtration specifications in 1990s-era operating theaters require structural reinforcement before fluorescence-enabled system installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical/Operating Microscopes Market |
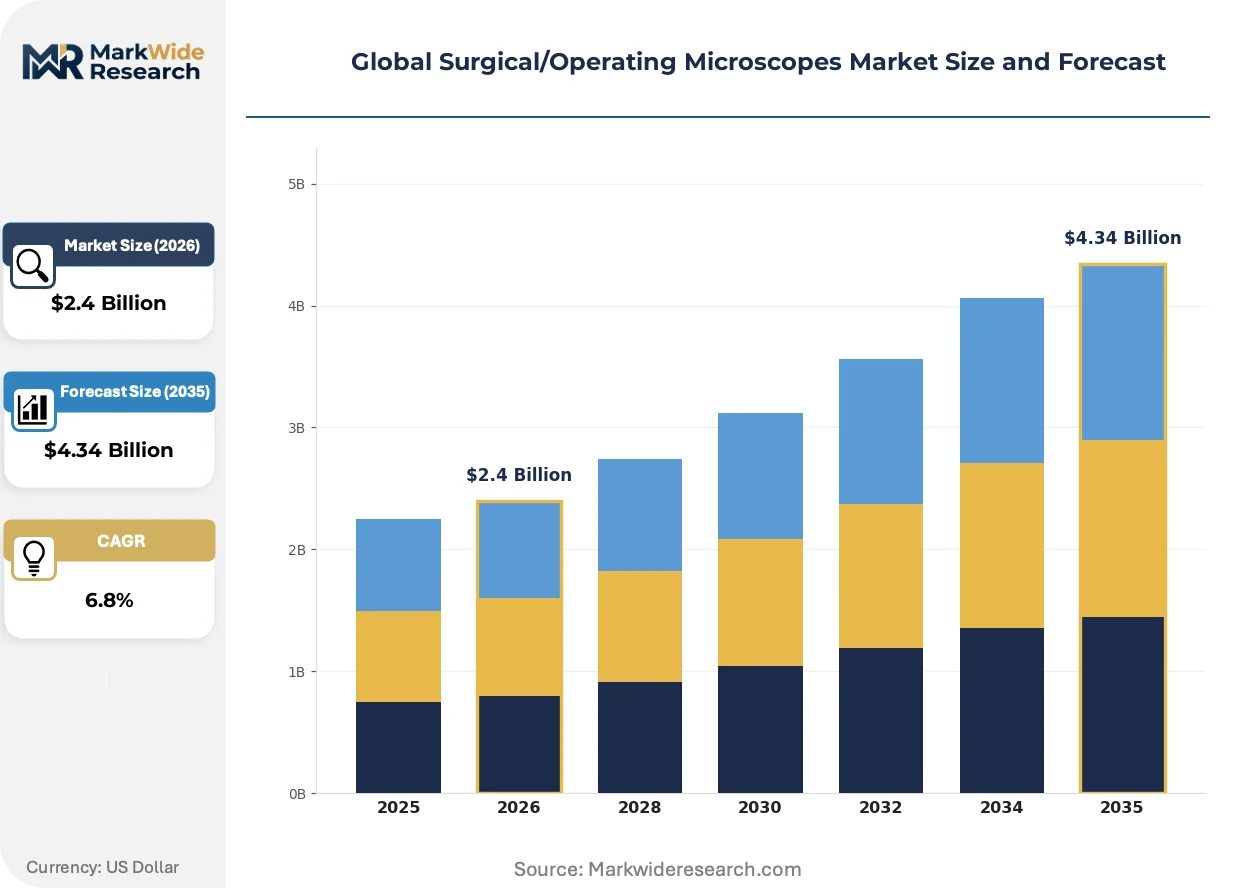
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Microscopes, Cart-Based Microscopes, Ceiling-Mounted Microscopes, Portable Microscopes Technology: Optical Zoom, Digital Zoom, Fluorescence Imaging, LED Illumination, 3D Visualization Application: Neurosurgery, Ophthalmic Procedures, ENT Surgeries, Dentistry, Reconstructive Surgery End User: Specialty Clinics, Ambulatory Surgery Centers, Academic Medical Centers, Private Surgical Suites |
| Companies Covered | Haag-Streit Group, Topcon Corporation, Carl Zeiss Meditec AG, Takagi Seiko Co., Ltd., Alltion (Wuzhou) Co., Ltd., Leica Microsystems, Olympus Corporation, Karl Kaps GmbH & Co. KG, Alcon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical/Operating Microscopes Market Shifts & Advancements
Digital image processing architectures are displacing purely optical signal paths, creating pressure on incumbent suppliers to restructure R&D allocation toward software-defined functionality.
Integrated 4K-3D video exoscopy systems are unifying the roles of surgical microscopes and rigid endoscopes into single-platform configurations. Academic medical centers in Japan and the United States are piloting these hybrid instruments for skull-base approaches previously requiring microscope-endoscope alternation. This convergence is unifying capital budgeting decisions that previously separated optical and endoscopic procurement committees.
Japan's PMDA has tightened clinical efficacy documentation requirements for fluorescence-enhanced surgical optics under revised QMS ordinance interpretations. Manufacturers must now submit prospective validation data for indocyanine green pharmacokinetic correlation with tissue perfusion outcomes. High-complexity neurosurgical centers in Osaka and Tokyo are experiencing delayed market authorization timelines for next-generation angiography modules.
Service contract unbundling is fragmenting traditional after-sales revenue streams. Hospital procurement teams in Germany and the United States are negotiating à la carte maintenance coverage excluding proprietary dye delivery system servicing. This behavioral shift concentrates vendor risk onto consumable protocol lock-in rather than hardware reliability guarantees.
Global Surgical/Operating Microscopes Market Segmentation
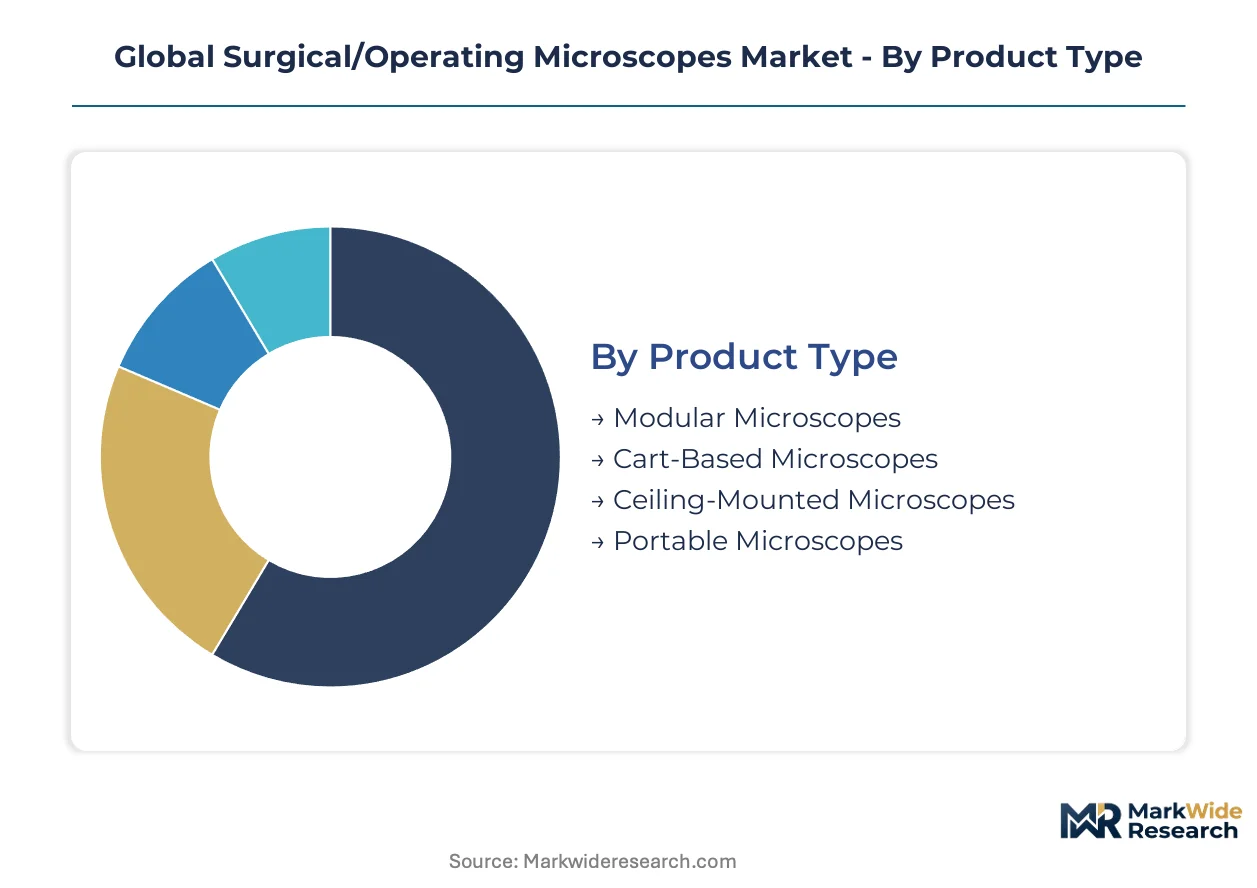
Segmentation in surgical microscopy reveals how capital deployment, clinical workflow integration, and regulatory complexity fragment procurement decisions across healthcare systems. Each dimension—product architecture, imaging technology, surgical discipline, and facility type—creates distinct margin pools and competitive dynamics for suppliers.
Product Type:
Integration depth varies sharply: ceiling-mounted systems embed permanently into OR infrastructure while portable configurations enable cross-suite mobility without structural modification.
- Ceiling-Mounted Microscopes:Permanent suspension systems integrate motorized arms, balanced counterweights, and coaxial illumination into hospital infrastructure. Demand clusters in German and Japanese academic medical centers where high-volume neurosurgical services justify dedicated OR capital investment and where fluorescence-ready configurations preempt EU MDR compliance requirements.
- Portable Microscopes:Compact floor-standing units with rapid-sterilization surfaces deploy across multi-procedure suites in US ambulatory surgery centers. These configurations sacrifice maximum optical resolution for deployment flexibility, penetrating ophthalmology and plastic surgery service lines where procedure volumes fluctuate seasonally.
- Modular Microscopes:Upgradeable platforms allowing field-installed fluorescence modules and camera attachments.
- Cart-Based Microscopes:Wheeled configurations with integrated power and video routing for temporary OR installations.
Volume placements concentrate in ceiling-mounted infrastructure; the faster expansion belongs to portable configurations.
Technology:
Cost tiering separates commodity illumination from proprietary imaging protocols that lock consumable revenue streams.
- Fluorescence Imaging:Near-infrared angiography modules using indocyanine green dye delivery require proprietary software-locked protocols and calibrated illumination sources. Academic medical centers in Osaka and Tokyo drive demand for cerebrovascular bypass applications where real-time perfusion assessment reduces postoperative complication rates.
- 3D Visualization:Stereoscopic camera arrays with surgeon-facing displays reduce ocular strain during prolonged microvascular procedures. German neurosurgical departments prioritize these systems for skull-base approaches exceeding six hours, integrating them with navigation platforms for augmented reality overlays.
- Optical Zoom:Traditional motorized objective assemblies with mechanical magnification control.
- Digital Zoom:Sensor-cropped image enlargement without optical path modification.
- LED Illumination:Solid-state lighting with tunable color temperature for tissue differentiation.
Revenue margins peak in fluorescence imaging; the steepest expansion trajectory sits with 3D visualization.
Application:
Customer type determines specification intensity: academic centers demand multimodal imaging while private suites prioritize throughput-optimized simplicity.
- Neurosurgery:Cerebrovascular and skull-base procedures require submillimeter resolution with fluorescence angiography for aneurysm clipping and bypass graft assessment. Tertiary referral networks in the United States consolidate these cases into high-volume centers where procedure economics justify premium system procurement.
- Ophthalmic Procedures:Cataract extraction and retinal detachment repair utilize compact microscopes with lower working distances and specialized patient positioning interfaces. Indian medical college hospitals under government-funded upgrade programs represent emerging demand concentration for these configurations.
- ENT Surgeries:Otologic and skull-base approaches requiring angled optics for sinus and temporal bone access.
- Dentistry:Endodontic and periodontal microsurgery with reduced magnification ranges and integrated documentation.
- Reconstructive Surgery:Microvascular free tissue transfer with lymphaticovenous anastomosis capabilities.
Capital allocation tilts toward neurosurgery; ophthalmic applications are gaining share fastest in emerging tertiary clusters.
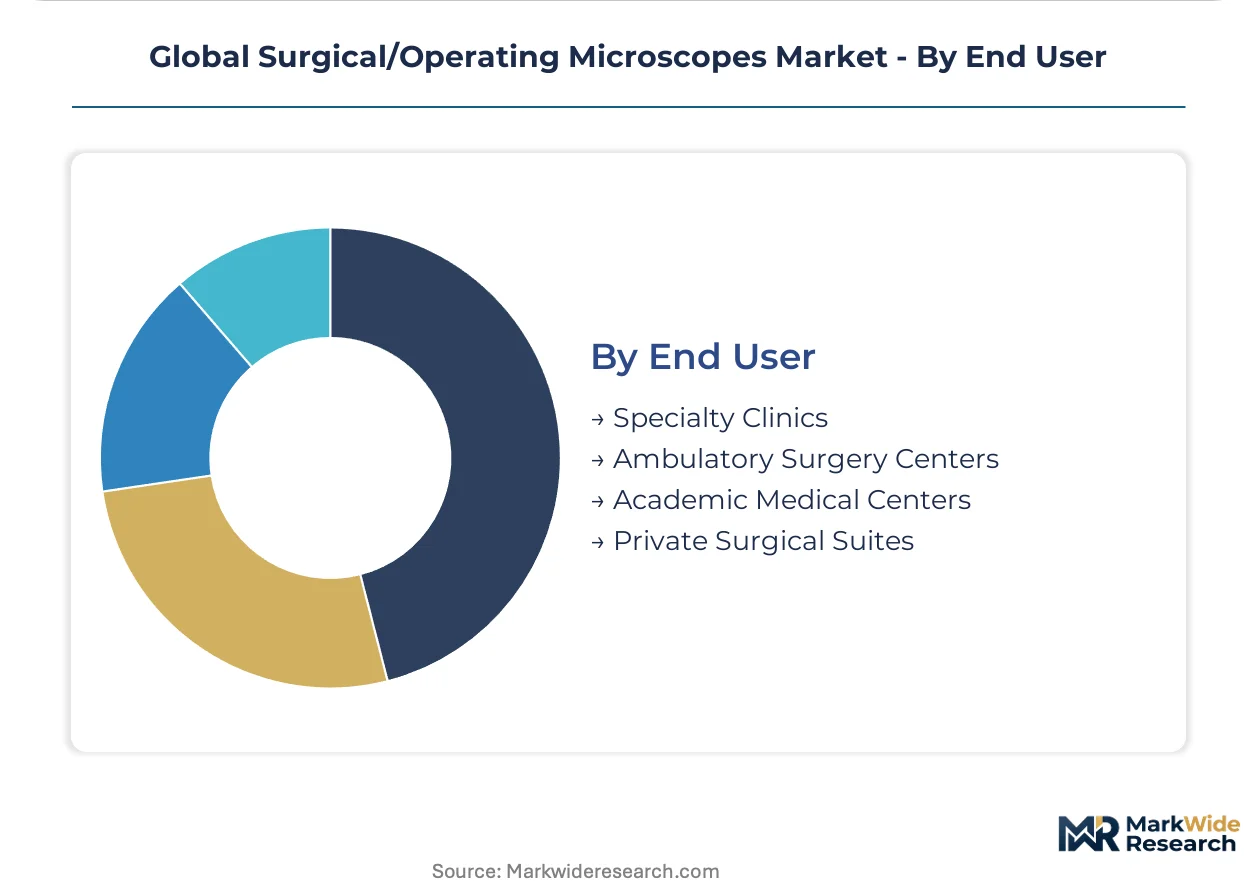
End User:
Maturity gradients separate established academic procurement patterns from ambulatory center volume sensitivity.
- Academic Medical Centers:Research-active institutions combine clinical service with training mandates, requiring documentation systems, multi-user ergonomics, and fluorescence protocols for prospective trials. These facilities in Germany, Japan, and the United States anchor premium pricing tiers through bundled service contracts and technology refresh cycles.
- Ambulatory Surgery Centers:Investor-owned multi-specialty facilities prioritize equipment utilization rates across ophthalmology, ENT, and plastic surgery lines. Procurement teams negotiate à la carte maintenance excluding proprietary consumables, concentrating vendor risk onto dye delivery system lock-in rather than hardware reliability.
- Specialty Clinics:Single-discipline practices with focused procedure volumes and limited capital budgets.
- Private Surgical Suites:Physician-owned facilities with premium patient positioning and throughput optimization.
Installed value concentrates in academic medical centers; ambulatory surgery centers are expanding most quickly in the United States and Western Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lanthanum and fluorite lens element supply concentrates in Chinese processing facilities, exposing German and Japanese microscope assemblers to cost volatility while anchoring regional manufacturing strategies.
United States
Tertiary referral networks in Boston, Houston, and San Francisco consolidate high-complexity neurosurgical cases where procedure economics justify premium fluorescence-enabled system procurement. FDA 510(k) pathway congestion for AI-enhanced image processing modules extends premarket review timelines. Academic medical centers in the Greater Boston cluster drive demand for augmented reality-fluorescence convergence in hybrid OR installations.
Germany
Oberkochen and Wetzlar fabrication ecosystems sustain captive lens grinding capabilities that shorten supply lead times for high-NA objective assemblies. EU Medical Device Regulation Class IIa oversight mandates accelerate hospital procurement of certified fluorescence-enabled systems. Carl Zeiss Meditec AG and Leica Microsystems anchor the precision optics cluster with vertically integrated manufacturing complexes.
Japan
Academic medical centers in Osaka and Tokyo drive demand for cerebrovascular bypass applications where real-time perfusion assessment reduces postoperative complication rates. PMDA tightened clinical efficacy documentation requirements for fluorescence-enhanced surgical optics under revised QMS ordinance interpretations. Olympus Corporation competes from Tokyo by controlling endoscope-to-microscope workflow bundles.
India
Government-funded medical college upgrades under the PLI scheme for medical devices create first-time demand for ceiling-mounted neurosurgical microscopes in Delhi and Mumbai clusters. CDSCO regulatory pathways for Class IIa optical surgical devices require quality management system conformity assessments. Indian medical college hospitals represent emerging demand concentration for ophthalmic procedure configurations.
Switzerland
Swissmedic oversight for surgical optics under EU MDR-aligned risk classification frameworks ensures streamlined market access for fluorescence-enabled systems. Precision engineering capabilities in the Zurich and Basel regions support specialized optomechatronics component supply to German microscope assemblers. Research-active institutions in Geneva and Lausanne anchor premium pricing tiers through bundled technology refresh cycles.
Global Surgical/Operating Microscopes Market Competitive Landscape
Global majors compete with regional champions across precision optics fabrication, fluorescence integration, and workflow bundling. The vendor base concentrates around German and Japanese fabrication clusters where captive lens grinding capabilities create defensive moats. Three strategic archetypes dominate: vertically integrated precision optics conglomerates, specialized neurosurgical fluorescence integrators, and endoscope-to-microscope workflow bundlers. Competitive dynamics center on modular upgrade architectures versus full-platform replacement cycles, and on consumable protocol lock-in versus à la carte maintenance unbundling.
Within the vertically integrated tier, Carl Zeiss Meditec AG and Leica Microsystems exemplify German precision optics manufacturing consolidation through captive Oberkochen and Wetzlar fabrication complexes. Among Asia-Pacific workflow bundlers, Olympus Corporation occupies a position integrating endoscopic and microscopic platforms for academic medical center procurement committees. These three entities anchor the competitive structure through differentiated supply chain control and regional market access patterns.
| Leading Market Players |
|---|
| Haag-Streit Group |
| Topcon Corporation |
| Carl Zeiss Meditec AG |
| Takagi Seiko Co., Ltd. |
| Alltion (Wuzhou) Co., Ltd. |
| Leica Microsystems |
| Olympus Corporation |
| Karl Kaps GmbH & Co. KG |
| Alcon Inc. |
| Others |
Supply & Pricing Matrix
EU MDR Class IIa quality management system mandates gate qualified supply access and premium-tier pricing authorization for fluorescence-enabled surgical microscopes. German and Japanese assemblers leverage captive lens grinding capabilities to defend margin pools against cost volatility in rare-earth coating materials.
Pricing Analysis
Warranty and service contract bundling separates premium vendor positioning from à la carte procurement patterns spreading through US ambulatory surgery centers. Three-tier pricing structure across premium fluorescence-integrated, standard optical, and economy portable configurations reflects certification grade and after-sales coverage depth. Cost compression in portable configurations intensifies as Indian medical college hospitals negotiate volume procurement under government-funded upgrade programs. Academic medical centers in Germany and Japan exhibit lowest price sensitivity due to bundled technology refresh cycles and research-active procurement mandates.
Supply Chain Analysis
Direct-to-hospital channels handle academic medical center demand in Germany, Japan, and the United States while distributor networks serve ambulatory surgery center and specialty clinic segments. Lanthanum and fluorite lens element supply concentrates in Chinese processing facilities, exposing German and Japanese microscope assemblers to commodity price volatility. High-NA objective assembly production hinges on Oberkochen and Wetzlar fabrication ecosystems with limited alternative sourcing. Distribution runs through authorized service organizations with field engineering capabilities for fluorescence module calibration and installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around precision optics fabrication scale as EU MDR compliance costs force weaker regional assemblers toward exit or acquisition.
For Market Incumbents: Hedge against consumable protocol unbundling by deepening backward integration into proprietary dye delivery system manufacturing. Secure captive supply of rare-earth coating materials through long-term offtake agreements with Chinese processing facilities. Defend fluorescence module installed base through accelerated modular upgrade architectures rather than full-platform replacement cycles. For New Entrants and Emerging Players: Begin with portable microscope configurations targeting Indian medical college hospitals under PLI scheme-funded upgrade programs. Concentrate initial market development on ophthalmic procedure applications where specification intensity remains lower than neurosurgical fluorescence integration. Pursue channel partnerships with established distributor networks rather than direct hospital contracting. For Investors and Strategic Acquirers: PMDA delayed market authorization timelines for next-generation angiography modules is the leading indicator that regulatory capability—not manufacturing scale—will determine acquisition premiums. Target mid-cap specialists with validated QMS documentation and existing fluorescence protocol clinical efficacy datasets. Watch for service contract unbundling acceleration in German and US hospital procurement as signal of vendor risk concentration onto consumable lock-in strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fluorescence Upgrade Architecture | Enables field-installed ICG angiography modules without full-platform replacement at German academic centers. |
| Proprietary Dye Delivery System Integration | Concentrates recurring revenue onto software-locked consumable protocols resisting à la carte unbundling. |
| CE Marking Pathway Acceleration | Preempts EU MDR Class IIa compliance gaps ahead of notified body oversight mandates for optical surgical devices. |
| Hospital System Partnership | Secures multi-year technology refresh cycles through bundled service contracts with US tertiary referral networks. |
| Software Companion Development | Positions AI-guided image enhancement modules for regulatory navigation amid FDA 510(k) pathway congestion. |
Research Methodology
FDA 510(k) premarket notification databases, EU MDR notified body certification registries, and Japanese PMDA QMS ordinance interpretation documents formed the secondary backbone for regulatory pathway mapping. Primary interviews with neurosurgical department heads, hospital biomedical engineers, GPO contracts managers, and precision optics manufacturing executives validated procurement pattern assumptions. Bottom-up demand modeling across product type, technology, application, and end user segments triangulated against top-down market sizing from installed base analysis.
Historical trendline analysis of fluorescence module penetration rates and replacement cycle compression informed projection methodology across the modeling period. Segmentation dimensions modeled include product architecture, imaging technology modality, surgical discipline intensity, and facility type maturity gradient. CAGRs derived from weighted average of procedure volume growth, equipment replacement elasticity, and premium technology adoption curves. Forecast inputs incorporated indocyanine green pharmacokinetic validation requirements and AI-enhanced image processing regulatory reclassification risks.
Underlying measurement precision varies by segment; fluorescence imaging and academic medical center end use carry tighter precision than portable configurations and ambulatory surgery center demand. Forecasts reflect assumptions regarding EU MDR implementation timelines, rare-earth material supply continuity, and software-as-medical-device interpretation evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
Printed Electronics in Healthcare Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
Dermal Allograft Market
Medical Devices
Breast Cancer Core Needle Biopsy Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Global Vascular Access Devices Market
Medical Devices
Electrosurgical Devices Market