
 Global Glaucoma Surgery Devices Market | 2026-2036
Global Glaucoma Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glaucoma Surgery Devices Market Foresight
Subscription-based maintenance and software-defined laser calibration is hardening into a core revenue layer alongside hardware sales. Alcon Inc. leverages its installed base of surgical systems to lock in recurring service contracts across ophthalmic clinics. Glaukos Corporation anchors its growth trajectory on proprietary micro-stent technology with tightly controlled proprietary instrumentation. Carl Zeiss Meditec AG competes through integrated imaging-to-surgery workflows that reduce operative variability.
Glaucoma surgery devices encompass precision instruments designed to reduce intraocular pressure through trabecular meshwork modification, aqueous humor diversion, or ciliary body ablation, typically operating within pressure tolerances of 10-21 mmHg and incorporating biocompatible materials such as silicone, polypropylene, or nitinol. These devices serve the primary clinical purpose of halting optic nerve damage progression when pharmaceutical management proves insufficient. Minimally Invasive Glaucoma Surgery now captures the fastest expansion trajectory as surgeons shift toward lower-risk outpatient alternatives to conventional filtration surgery. Laser Systems retain mature, stable demand in established markets where SLT and ALT protocols enjoy deep reimbursement integration. Drainage Implants concentrate margin pools in complex secondary glaucoma cases requiring durable pressure control.
FDA 510(k) and PMA pathways govern device approval in the United States, while the EU MDR and CE marking framework impose strengthened clinical follow-up obligations on implantable ocular devices. Japan's PMDA maintains distinct biocompatibility testing protocols that extend market entry timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement codes for MIGS procedures across national health systems to anticipate volume inflection points.
Market Dynamics
Minimally invasive glaucoma surgery is compressing the addressable market for conventional trabeculectomy as outpatient clinics prioritize lower-risk procedures with faster recovery windows.
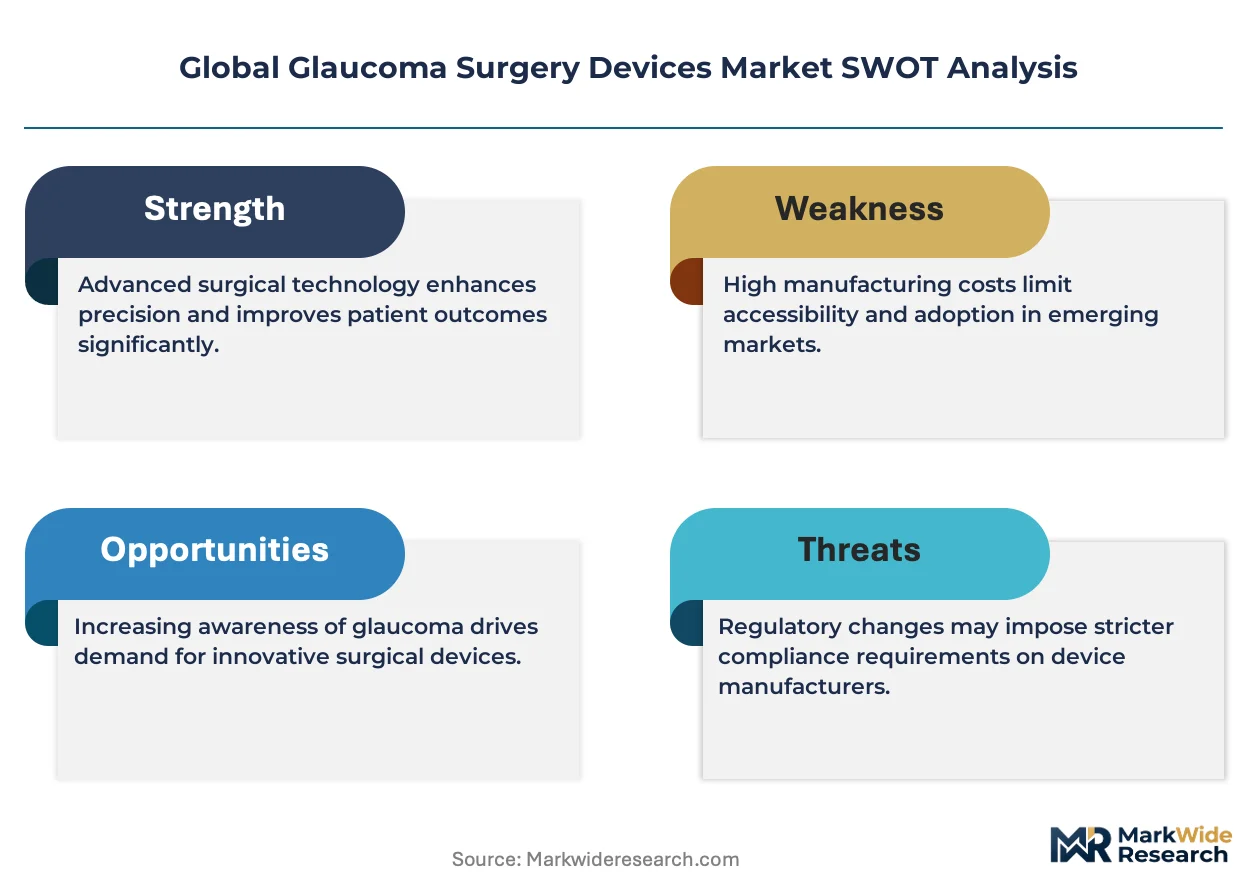
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearances for predicate-based MIGS devices are shortening commercialization timelines for novel trabecular meshwork bypass systems.
- Ambulatory surgical center expansion:United States-based outpatient facilities are scaling dedicated ophthalmology suites to capture shifting procedure volumes from hospital settings.
- Polymeric biocompatibility advances:Next-generation silicone-nitinol composites are reducing fibrotic encapsulation rates in drainage implants.
Market Restraints
- Raw material concentration:Medical-grade silicone supply chains cluster in Germany and Japan, exposing manufacturers to regional production disruptions.
- EU MDR clinical follow-up obligations:Extended post-market surveillance requirements for implantable ocular devices are extending certification cycles by 18-24 months.
- Pharmaceutical substitution:Fixed-dose combination eye drops are capturing early-stage glaucoma cases before surgical intervention becomes necessary.
Strategic Opportunities
- India's tier-two city penetration:Underserved ophthalmology infrastructure in cities like Pune and Ahmedabad offers first-mover positioning for MIGS training programs.
- AI-guided surgical planning:Integration of optical coherence tomography analytics with femtosecond laser platforms is enabling personalized trabecular targeting.
- Japan's PMDA harmonization initiatives:Mutual recognition agreements with FDA are creating streamlined dual-market entry pathways for drainage implant manufacturers.
Industry Challenges
- Microsurgical skill scarcity:MIGS proficiency requires specialized training in gonioscopic anatomy that exceeds standard ophthalmology residency curricula.
- Interoperability friction:Proprietary instrument-tethering by dominant laser system vendors limits third-party stent compatibility in integrated surgical suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glaucoma Surgery Devices Market |
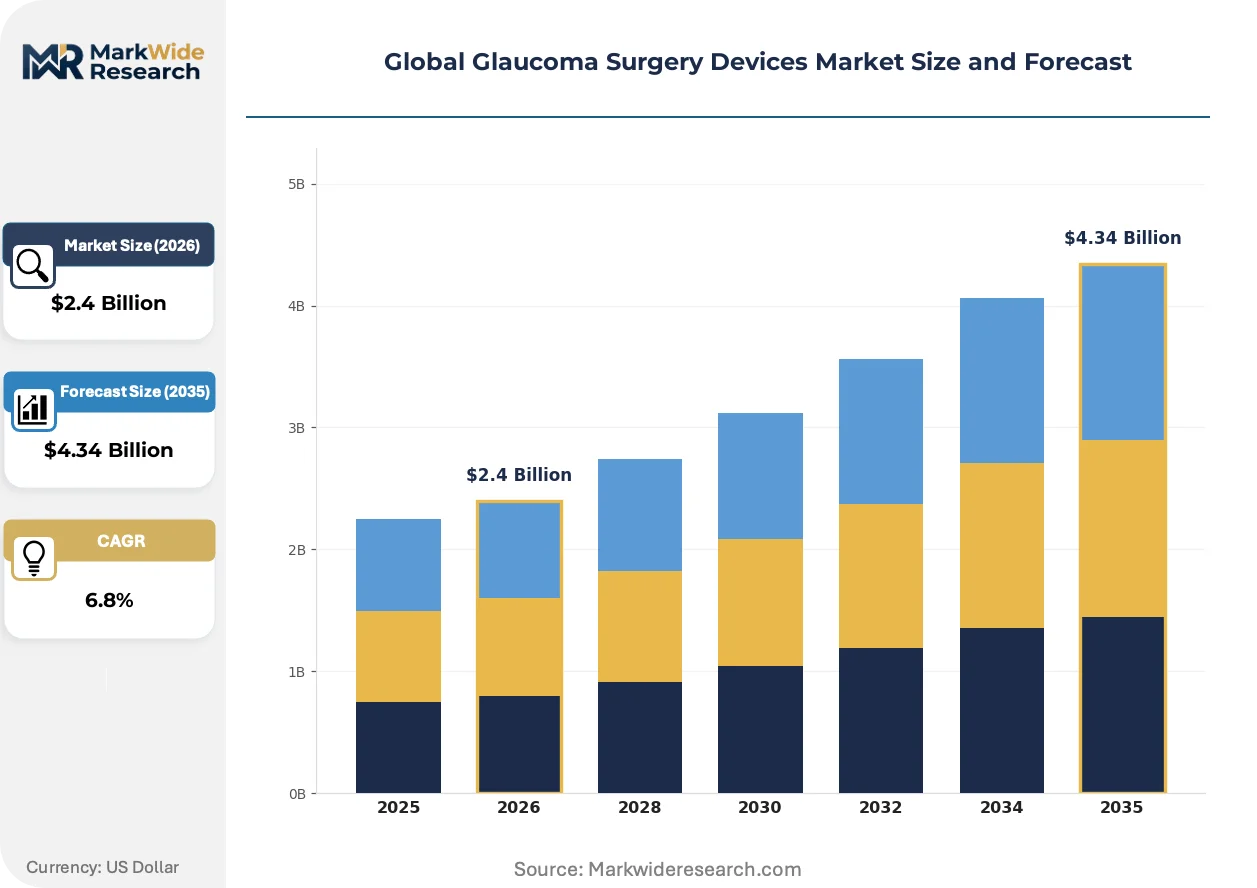
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trabeculectomy Devices, Drainage Implants, Laser Systems, Canaloplasty Instruments, Micro-Stents Technology: Trabeculectomy, Minimally Invasive Glaucoma Surgery, Laser, Aqueous Shunt, Gonioscopy-Assisted Procedures Application: Open-Angle Glaucoma, Angle-Closure Glaucoma, Normal-Tension Glaucoma, Secondary Glaucoma End User: Ophthalmic Clinics, Eye Hospitals, Ambulatory Surgical Centers, Specialty Eye Care Units |
| Companies Covered | AbbVie Inc., Lumenis Ltd., Alcon Inc., Iridex Corporation, Ziemer Ophthalmic Systems AG, Glaukos Corporation, Carl Zeiss Meditec AG, Santen Pharmaceutical Co. Ltd., Johnson & Johnson Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glaucoma Surgery Devices Market Shifts & Advancements
Device manufacturers are embedding software-defined functionality into hardware platforms to capture recurring revenue streams beyond initial capital sales.
Extended-release drug-eluting stents are electrifying the competitive landscape by combining mechanical pressure reduction with sustained pharmaceutical delivery. Glaucoma specialists in United States academic medical centers are adopting these hybrid platforms for moderate-stage patients. The convergence is compressing the traditional boundary between device and drug therapy paradigms.
EU MDR post-market clinical follow-up requirements are forcing manufacturers to rebuild vigilance systems for implantable drainage devices. The regulation mandates systematic collection of real-world safety data across all member states. German notified bodies are applying the strictest interpretation, delaying CE marking renewals for legacy product lines.
Subscription-based service unbundling is reshaping how ambulatory surgery centers acquire laser maintenance and calibration support. United States-based clinics are shifting from bundled capital-plus-service contracts to standalone software access fees. The model is most visible in large multi-site ophthalmology groups seeking operational expenditure predictability.
Global Glaucoma Surgery Devices Market Segmentation
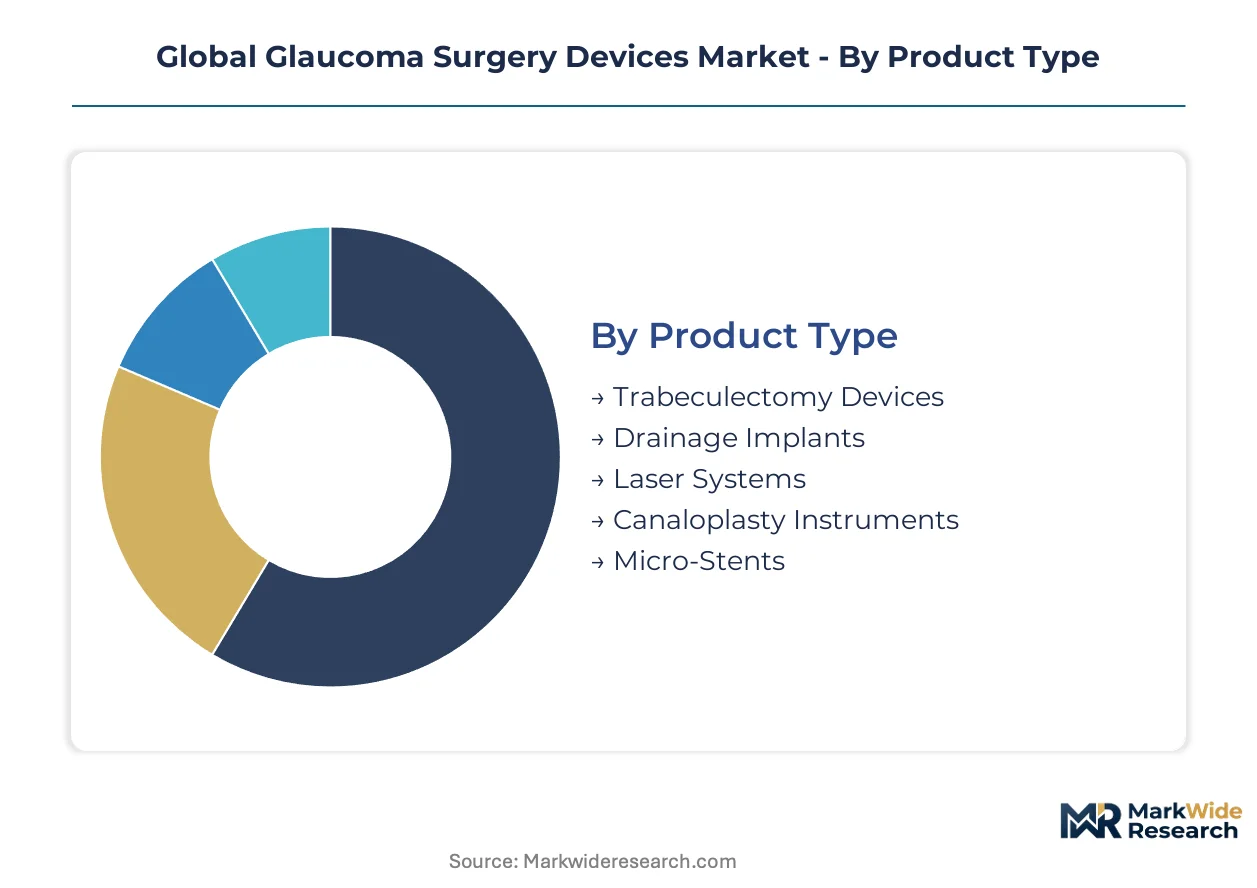
Device segmentation in glaucoma surgery reveals how procedural economics and reimbursement pathways reshape competitive positioning. Manufacturers calibrate portfolio depth across standalone capital equipment and disposable implantables to capture divergent margin profiles.
Product Type:
Standalone capital platforms anchor installed-base strategies, while single-use implants drive recurring revenue through procedure volume.
- Trabeculectomy Devices:Scleral punch systems and guarded filtration sets utilize titanium micro-instruments with 50-100 micron precision tolerances. Demand concentrates in United States academic medical centers where complex case referrals sustain filtration surgery volumes despite MIGS displacement.
- Drainage Implants:Silicone plate-valve assemblies and non-valved tube shunts incorporate polypropylene or silicone elastomer construction with 350-500 mmHg flow resistance specifications. German and Japanese tertiary centers favor these for refractory secondary glaucoma where aqueous production exceeds conventional outflow capacity.
- Laser Systems:Frequency-doubled Nd:YAG and diode platforms for selective laser trabeculoplasty.
- Canaloplasty Instruments:Viscoelastic delivery systems and microcatheters for Schlemm's canal dilation.
- Micro-Stents:Nitinol or polyimide trabecular bypass devices.
Laser Systems lead volumes today; Micro-Stents are gaining share fastest.
Technology:
Cost tier stratification separates premium integrated platforms from modular point solutions.
- Trabeculectomy:Conventional guarded filtration with antimetabolite adjuncts represents the historical standard. United States safety-net hospitals and rural India maintain reliance on this lowest-cost surgical option where device procurement budgets face institutional constraints.
- Minimally Invasive Glaucoma Surgery:Trabecular meshwork bypass and supraciliary shunting techniques employ ab-interno approaches through clear corneal incisions. Ambulatory surgical centers in Germany and Japan are scaling MIGS suites to capture outpatient migration from hospital-based filtration.
- Laser:SLT and ALT photocoagulation protocols.
- Aqueous Shunt:Tube-shunt diversion to equatorial plate reservoirs.
- Gonioscopy-Assisted Procedures:Direct visualization techniques for angle-based surgery.
Trabeculectomy retains the highest procedure count; Minimally Invasive Glaucoma Surgery shows the steepest expansion trajectory.
Application:
Clinical indication segmentation tracks disease severity progression and corresponding intervention thresholds.
- Open-Angle Glaucoma:Primary trabecular dysfunction with preserved anterior chamber anatomy dominates surgical caseloads. United States Medicare reimbursement for MIGS in mild-to-moderate open-angle disease has accelerated procedural migration from pharmaceutical management.
- Angle-Closure Glaucoma:Peripheral iris-lens apposition requiring lens extraction or iridotomy. Japanese surgical volumes concentrate here given the ethnic predisposition to pupillary block mechanisms.
- Normal-Tension Glaucoma:Optic neuropathy with statistically normal pressure ranges.
- Secondary Glaucoma:Neovascular, traumatic, or steroid-induced etiologies.
Open-Angle Glaucoma leads volumes today; Secondary Glaucoma is climbing fastest as diabetes prevalence expands neovascular case referrals.
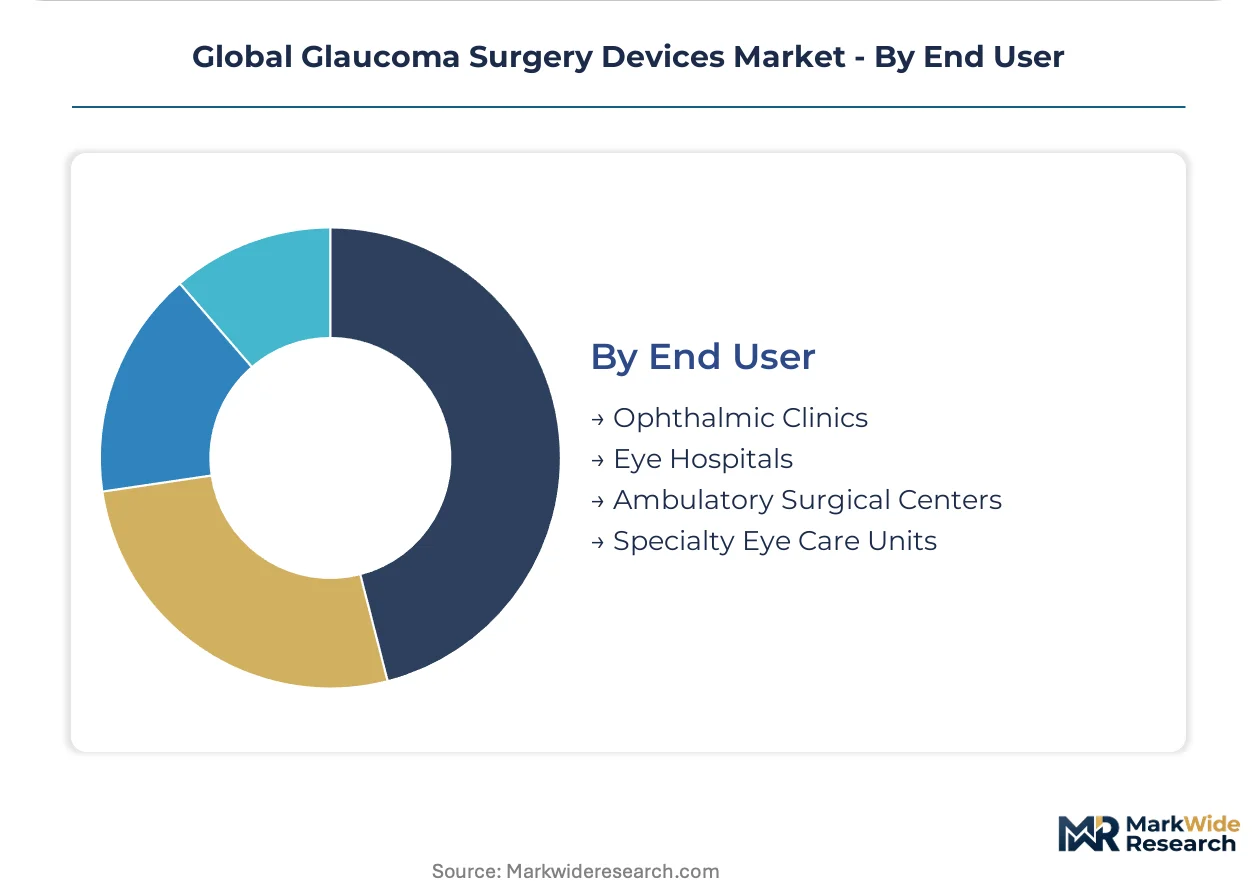
End User:
Customer type determines capital intensity requirements and service contract structures.
- Ophthalmic Clinics:Private practice settings with 1-3 surgeons prioritize portable laser platforms and disposable stent inventory. United States suburban markets show concentration of solo practitioners adopting MIGS to retain patients who would otherwise refer to academic centers.
- Ambulatory Surgical Centers:Dedicated ophthalmology facilities with streamlined anesthesia protocols achieve 15-20 minute MIGS turnaround times. German outpatient chains are consolidating procurement to extract volume discounts on micro-stent consignment arrangements.
- Eye Hospitals:Multi-specialty institutions with residency programs.
- Specialty Eye Care Units:Hospital-embedded glaucoma divisions.
Ophthalmic Clinics lead volumes today; Ambulatory Surgical Centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating final assembly to jurisdictions with streamlined medical device pathways, exploiting gaps between FDA PMA timelines and CE marking acceleration under notified body consolidation in Germany.
United States
Medicare reimbursement clarity for MIGS procedures sustains procedure volume expansion across ambulatory surgical centers. FDA 510(k) streamlining for predicate-based trabecular meshwork devices shortens commercialization cycles. The Dallas-Fort Worth metroplex anchors a cluster of ophthalmology-focused outpatient chains scaling dedicated glaucoma suites.
Germany
Tertiary centers in Baden-Württemberg and Bavaria favor drainage implants for refractory secondary glaucoma cases. EU MDR post-market surveillance obligations extend certification cycles for implantable ocular devices. The Stuttgart-Tübingen corridor concentrates silicone-nitinol composite R&D for next-generation shunt materials.
Japan
Ethnic predisposition to angle-closure mechanisms concentrates surgical volumes in Kanto and Kansai regions. PMDA biocompatibility testing protocols extend market entry timelines for foreign drainage implant manufacturers. Osaka-based academic medical centers lead adoption of gonioscopy-assisted procedures with integrated imaging workflows.
India
Tier-two cities including Pune and Ahmedabad present first-mover positioning for MIGS training programs amid underserved ophthalmology infrastructure. CDSCO medical device rules impose quality management system requirements on imported laser platforms. The Hyderabad-Chennai corridor attracts contract manufacturing for polypropylene tube shunts serving price-sensitive institutional buyers.
United Kingdom
NHS England commissioning frameworks prioritize cost-per-QALY thresholds that favor micro-stent adoption over conventional filtration in mild-to-moderate open-angle disease. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR for implantable devices. The London-Oxford-Cambridge golden triangle anchors health technology assessment bodies influencing procurement across Commonwealth markets.
Global Glaucoma Surgery Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated laser-imaging platforms commanding premium positioning against modular point solutions. The vendor base organizes around three strategic archetypes: diversified ophthalmology conglomerates with installed-base leverage, pure-play MIGS innovators with proprietary stent-instrument ecosystems, and precision laser OEMs with software-defined service layers. Capacity expansion and strategic partnerships dominate competitive moves, while technology licensing agreements bridge gaps between imaging analytics and femtosecond delivery systems.
Among diversified ophthalmology conglomerates, Alcon Inc. and Johnson & Johnson Vision occupy positions defined by surgical system installed bases and recurring service contract penetration. Glaukos Corporation exemplifies the pure-play MIGS archetype through tightly controlled proprietary instrumentation. Carl Zeiss Meditec AG anchors the integrated imaging-to-surgery workflow tier, representing convergence between optical coherence tomography analytics and laser platform precision.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Lumenis Ltd. |
| Alcon Inc. |
| Iridex Corporation |
| Ziemer Ophthalmic Systems AG |
| Glaukos Corporation |
| Carl Zeiss Meditec AG |
| Santen Pharmaceutical Co. Ltd. |
| Johnson & Johnson Vision |
| Others |
Supply & Pricing Matrix
Device-class bifurcation between FDA PMA-track implants and 510(k) predicate-based systems manifests in divergent pricing architectures and supply chain configurations across the glaucoma surgery devices landscape. Premium drainage implants command consignment-based inventory arrangements through hospital-embedded specialty units, while commoditized laser platforms flow through distributor networks serving ambulatory surgical centers with compressed margin structures.
Pricing Analysis
Distributor markup layers for disposable micro-stents typically run 35-50% above manufacturer invoice, reflecting specialized cold-chain handling and surgeon-training bundling. The dominant pricing structure operates on a hybrid per-procedure consignment plus capital lease model for laser systems. Price differentiation hinges on FDA PMA tier certification and proprietary instrument-locking ecosystems. Pricing pressure stems from Medicare reimbursement compression for MIGS procedures in United States outpatient settings. Ambulatory surgical centers exhibit the highest price sensitivity, while academic medical centers prioritize clinical outcome data over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States operate hub-and-spoke patterns for silicone-nitinol composite implants, with Stuttgart and Osaka anchoring upstream material synthesis. Medical-grade silicone elastomer and nitinol shape-memory alloy constitute critical input dependencies. Supply chain risk concentrates in single-source vulnerability for medical-grade silicone feedstock from German chemical specialists. Distribution runs through GPO-negotiated contracts for United States hospital systems and direct-manufacturer relationships for German outpatient chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glaucoma surgery devices market functions as a regulatory compounder where EU MDR post-market surveillance mandates are accelerating replacement demand for legacy implant portfolios. FDA 510(k) pathway streamlining for predicate-based trabecular meshwork systems reinforces incumbent positioning while creating entry friction for novel device architectures.
For Market Incumbents: Extend service contract penetration across installed laser bases to capture recurring revenue streams as hardware sales mature. Deepen backward integration into medical-grade silicone compounding to defend margin position against raw material concentration in German supply chains. Alcon and Johnson & Johnson Vision should prioritize proprietary instrument-tethering strategies that limit third-party stent compatibility in integrated surgical suites. For New Entrants and Emerging Players: Telemedicine-enabled surgeon training platforms offer the lowest-friction route to penetrate India's tier-two ophthalmology infrastructure in Pune and Ahmedabad. Target MIGS training program partnerships with regional hospital networks as the most penetrable entry vector. Pursue white-label manufacturing arrangements with Hyderabad-based contract manufacturers to circumvent CDSCO quality management system barriers for imported laser platforms. For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary stent-instrument ecosystems face interoperability friction from dominant laser system vendors. The 5-10 year viability window favors pure-play MIGS innovators with FDA PMA-track pipelines over commoditized laser OEMs. Acquisition target archetypes include canaloplasty instrument specialists with CE marking under EU MDR and software-defined laser calibration capabilities. Monitor FDA 510(k) clearance velocity for trabecular meshwork bypass systems as the primary inflection signal for MIGS procedure volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA PMA Submission Pathway | PMA-track drainage implants command premium pricing through hospital-embedded specialty units in United States academic centers. |
| CE Marking Renewal Investment | EU MDR post-market surveillance compliance extends certification cycles for implantable ocular devices in German notified body jurisdictions. |
| Hospital System Partnership | GPO contract consolidation with United States ambulatory surgical center chains secures volume commitments for micro-stent consignment arrangements. |
| Software Companion Development | AI-guided surgical planning integration with optical coherence tomography analytics enables personalized trabecular targeting in femtosecond laser platforms. |
| Reimbursement Strategy | Medicare code alignment for MIGS procedures in mild-to-moderate open-angle disease accelerates procedural migration from pharmaceutical management. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market cluster combining structured interviews with glaucoma surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation. Secondary sources include FDA 510(k) and PMA filing databases, EU MDR notified body documentation, PMDA biocompatibility testing protocols, CMS Medicare reimbursement code records, and hospital procurement databases. Bottom-up procedure volume estimates triangulate against top-down manufacturer revenue disclosures.
Granularity-level modeling operates at the intersection of technology type, product class, application severity, and end-user facility tier across the projection horizon. Segmentation dimensions include MIGS versus conventional filtration technology, capital equipment versus disposable implant product economics, open-angle versus angle-closure versus secondary glaucoma indications, and ambulatory surgical center versus ophthalmic clinic versus eye hospital customer archetypes. CAGRs derive from procedure volume trajectory analysis calibrated to reimbursement code expansion patterns and surgeon adoption curve modeling for gonioscopy-assisted techniques.
The model assumes a particular technology adoption path; alternative pathways for drug-eluting stent convergence would alter the outlook through pharmaceutical substitution effects. Forecasts reflect documented assumptions regarding EU MDR implementation timelines, FDA 510(k) streamlining continuity, and Medicare reimbursement stability for MIGS procedures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Contrast Injection Lines Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Clot Management Devices Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Steroid Releasing Implant Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Consumer Grade EEG Device Market
Medical Devices
Collateral Ligament Stabilizers Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Global Advanced Bipolar Direct Energy Device Market
Medical Devices
Medical Radiation Detectors Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
Foot and Ankle Allograft Market
Medical Devices
Global Lithotripsy Device Market