
 Cervical Retractors Market | 2026-2036
Cervical Retractors Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Retractors Market Outlook
Multi-source procurement of cervical retractor systems is broadening as hospital supply chains diversify beyond single-vendor spine portfolios. Stryker Corporation leverages its integrated operating-room ecosystem to sustain bundled instrument contracts across IDN networks. Globus Medical differentiates through specialized expandable retractor designs that reduce operative footprint in anterior cervical approaches. Zimmer Biomet anchors its position via manufacturing scale across stainless steel and titanium instrument lines serving high-volume orthopedic surgery centers.
Cervical retractors are mechanical surgical instruments designed to hold back soft tissue and maintain operative exposure during anterior or posterior cervical spine procedures, typically constructed from medical-grade stainless steel or titanium with blade widths ranging from 12 mm to 40 mm and ratcheting or friction-based locking mechanisms. These devices enable direct visualization of the vertebral bodies, nerve roots, and spinal cord while minimizing assistant fatigue and tissue trauma during prolonged discectomy, corpectomy, or fusion operations. Self-retaining retractor configurations dominate procedural volume in hospital settings due to their hands-free stability and compatibility with table-mounted fixation arms, while titanium material segments command premium positioning where repeated sterilization cycles and magnetic resonance imaging compatibility are prioritized. Ambulatory surgical centers represent the fastest-growing end-user channel as cervical decompression cases migrate to outpatient settings under bundled payment models.
FDA 510(k) premarket notification requirements govern cervical retractor clearance in the United States, while the EU Medical Device Regulation mandates notified-body conformity assessment and unique device identification for European market access. Japan's PMDA enforces QMS ministerial ordinances that shape sterilization validation and biocompatibility testing protocols for imported instruments. Stakeholders must monitor evolving MDR technical documentation requirements and CMS outpatient procedure reimbursement determinations to align product development with shifting site-of-care economics.
Market Dynamics
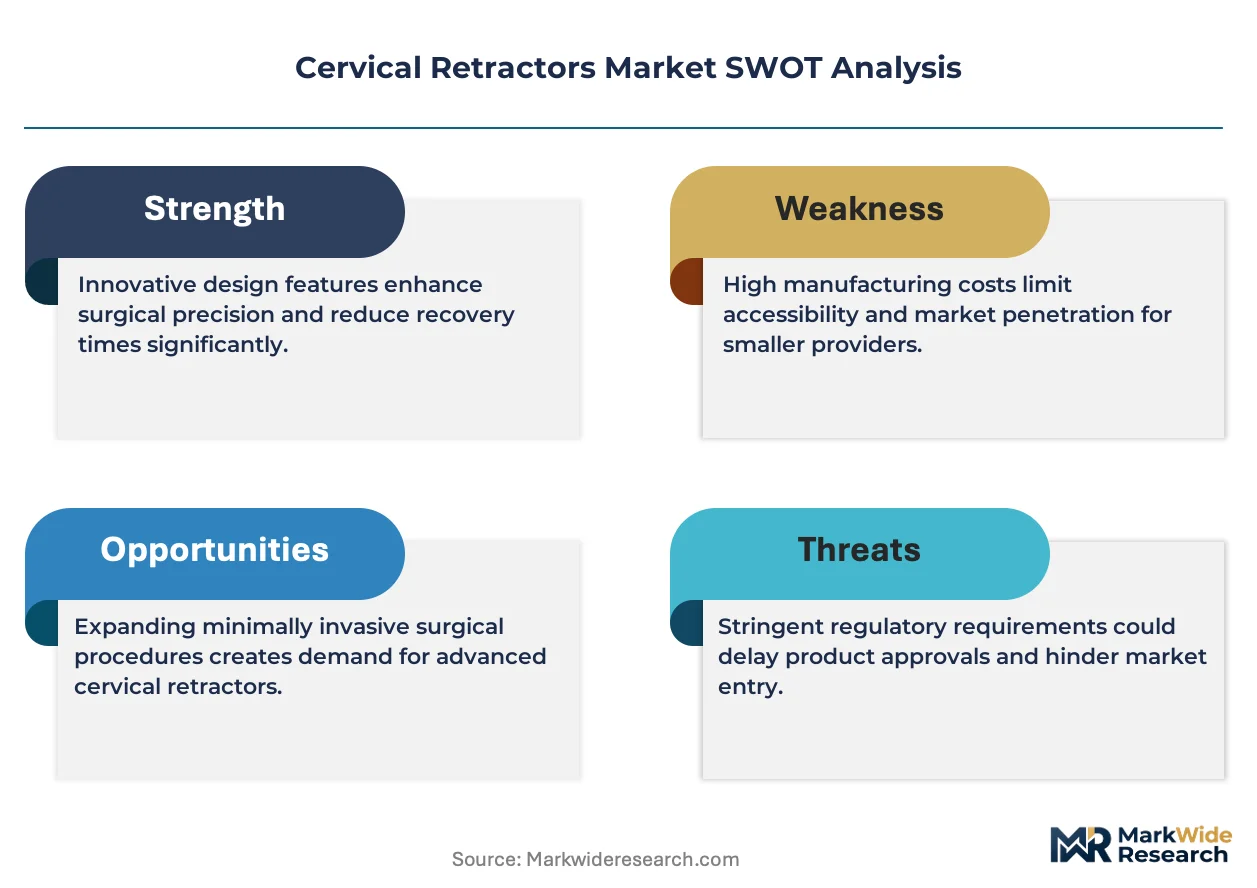
Hospital procurement of minimally invasive spine systems is accelerating as surgeons prioritize reduced tissue trauma and faster patient recovery, while tightening FDA 510(k) and EU MDR documentation standards force manufacturers to recalibrate compliance investments against margin pressure.
Growth Catalysts
- Aging Demographics:Rising cervical fusion volumes among patients over 65 in the United States, Germany, and Japan sustain instrument replacement cycles and drive demand for premium titanium retractors with enhanced durability.
- FDA 510(k) Pathway Efficiency:Streamlined premarket notification processes for Class II surgical instruments accelerate time-to-market for incremental blade design improvements and locking mechanism refinements.
- Ambulatory Surgical Center Migration:Bundled payment models under CMS reimbursement determinations are pulling cervical decompression cases into outpatient settings, expanding addressable volume for compact, self-retaining retractor configurations.
Market Restraints
- Medical-Grade Titanium Price Volatility:Fluctuations in aerospace and industrial titanium demand create input cost instability for manufacturers serving high-volume orthopedic surgery centers with MRI-compatible instrument lines.
- EU MDR Technical Documentation Burden:Expanded notified-body conformity assessment requirements and unique device identification mandates lengthen approval timelines and inflate regulatory compliance overhead for European market entry.
- Reusable Instrument Durability:Repeated sterilization cycles degrade ratcheting mechanisms and blade edges in stainless steel configurations, compressing replacement intervals and threatening vendor pricing power.
Strategic Opportunities
- Expandable Retractor Design White Space:Specialized anterior cervical approaches with reduced operative footprint remain underpenetrated, offering differentiation potential against conventional fixed-blade systems.
- Japan PMDA QMS Alignment:Ministerial ordinances governing sterilization validation and biocompatibility testing create first-mover advantages for manufacturers investing in dedicated Japanese regulatory infrastructure.
- Table-Mounted Fixation Arm Integration:Convergence between retractor locking mechanisms and robotic surgical positioning systems enables premium positioning in integrated operating-room ecosystems.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization protocols require extended validation timelines that delay product launches and strain R&D resource allocation.
- Surgeon Training Standardization:Variability in anterior versus posterior cervical approach techniques across residency programs complicates instrument design optimization and limits economies of scale in educational support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Retractors Market |
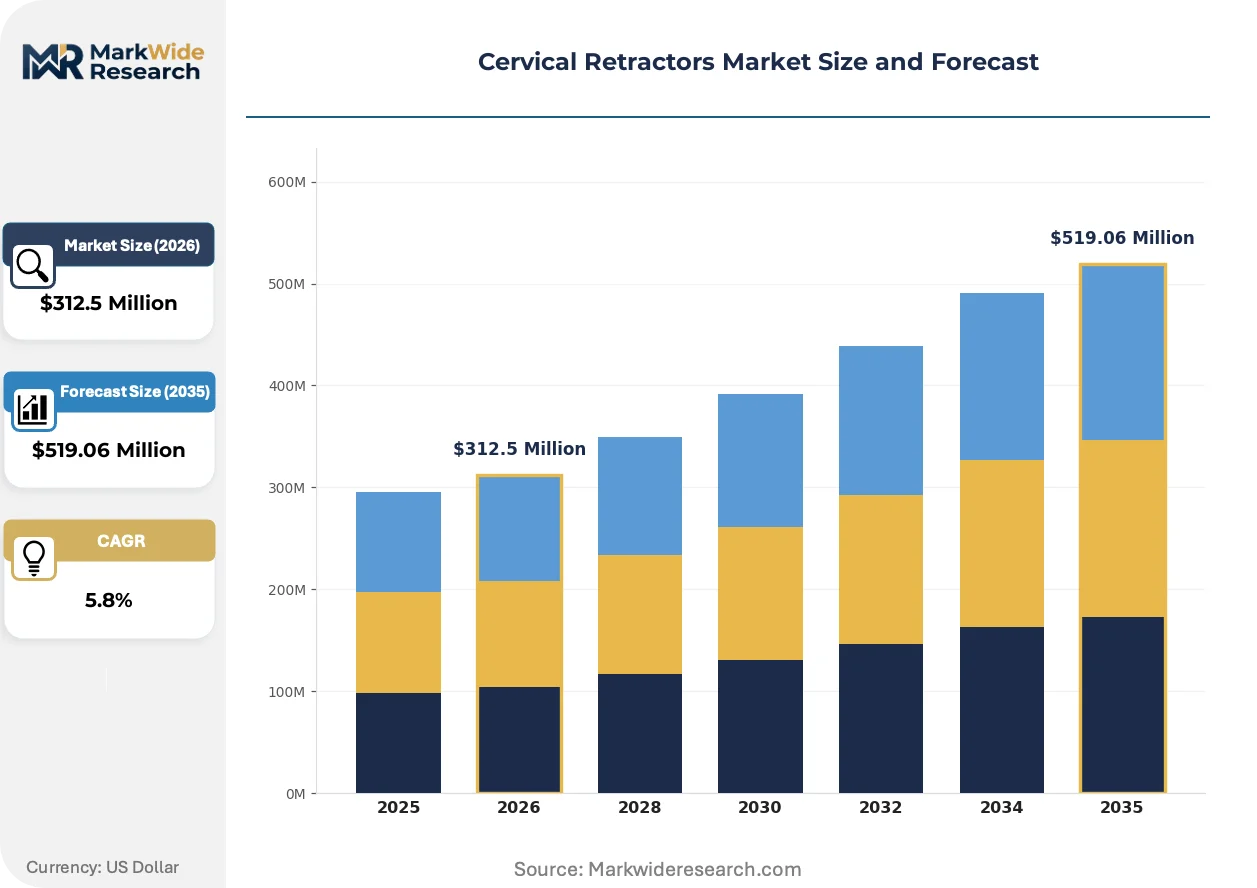
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Retaining, Hand-Held, Fixed, Adjustable Material: Stainless Steel, Plastic, Titanium, Composite End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Laboratories Application: Orthopedic Surgery, Neurosurgery, Rehabilitation, Diagnostic Procedures |
| Companies Covered | Medtronic, Stryker Corporation, Globus Medical, Zimmer Biomet, Johnson & Johnson, Aesculap Implant Systems, TeDan Surgical Innovations, Boston Scientific Corporation, Thompson Surgical Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Retractors Market Strategic Shifts
Instrument design is converging with digital surgical workflows as manufacturers embed compatibility layers for navigation systems and robotic arms, while regulatory documentation automation and procurement analytics reshape how hospitals evaluate retractor lifetime costs.
Modular blade systems with interchangeable widths and angulations are replacing fixed-configuration retractors in high-volume spine centers. Hospital materials management departments are standardizing on platforms that accommodate 12 mm to 40 mm blade swaps without full instrument replacement. This flexibility is modularizing vendor relationships, allowing procurement teams to unbundle blade supply from handle and locking mechanism contracts.
The EU Medical Device Regulation's unique device identification mandate is forcing manufacturers to restructure technical documentation and post-market surveillance systems. European notified bodies are rejecting legacy sterilization validation data, compelling resubmission of biocompatibility studies for titanium instruments with revised processing histories. Stainless steel retractor lines face the steepest compliance cost inflation, pushing some suppliers to discontinue economy-tier SKUs rather than absorb MDR-driven overhead.
Hospital value-analysis committees are unbundling after-sales service from capital equipment contracts, forcing retractor vendors to price sterilization case carts, instrument tracking, and blade resharpening as discrete line items. IDN supply chains in the United States are piloting consignment inventory models where vendors retain ownership until point-of-use, transferring working capital burden upstream. This disintermediation of traditional distributor warehousing is most visible in southeastern and midwestern health systems consolidating orthopedic service lines under single vendor agreements.
Cervical Retractors Market Segmentation
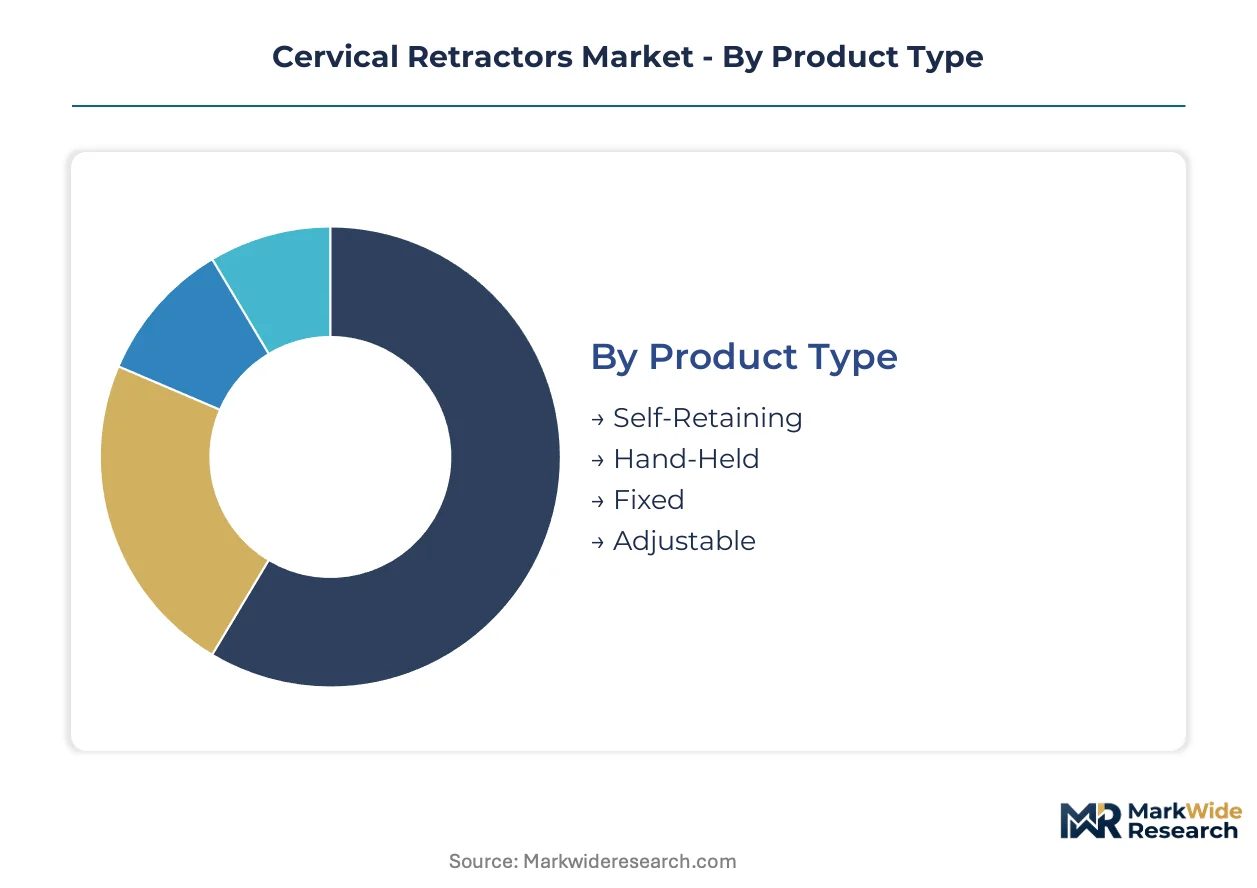
Cervical retractor segmentation reveals how procurement priorities diverge across surgical settings and material specifications. Understanding these splits enables manufacturers to align blade geometries, locking mechanisms, and sterilization protocols with distinct buyer economics and procedural requirements.
Product Type:
Surgeons select retractor configurations based on procedural duration, assistant availability, and table-mounted system compatibility.
- Self-Retaining:Ratcheting or friction-lock designs free surgical assistants from manual holding during lengthy anterior cervical fusions. Hospital systems in the United States prioritize these configurations for high-volume spine centers where OR efficiency metrics determine capital allocation.
- Hand-Held:Direct surgeon or assistant control suits brief posterior decompressions and teaching cases where tactile feedback matters. German university hospitals maintain these instruments for resident training programs despite slower procedural throughput.
- Fixed:Non-adjustable blade angles serve standardized anterior approaches with predictable anatomical exposure. Japanese orthopedic surgery centers deploy fixed configurations for routine discectomy volumes.
- Adjustable:Modular blade positioning accommodates variable patient anatomy and multi-level procedures. Ambulatory surgical centers in Florida and Texas are adopting adjustable systems to handle diverse case mixes without instrument redundancy.
Self-retaining configurations dominate hospital procurement volumes today; adjustable designs are gaining share fastest as outpatient cervical cases expand.
Material:
Material selection trades acquisition cost against sterilization durability and imaging compatibility.
- Stainless Steel:Standard-grade instruments withstand repeated autoclave cycles at lowest unit cost. High-volume orthopedic surgery centers in Germany and Japan standardize on stainless steel for instrument replacement programs where budget predictability outweighs premium features.
- Titanium:Non-ferrous composition eliminates MRI artifact and resists corrosion across extended service life. United States hospital networks with dedicated spine institutes specify titanium for cases requiring intraoperative magnetic resonance navigation.
- Plastic:Single-use polymer retractors eliminate reprocessing overhead for outpatient settings. Ambulatory surgical centers in California and New York pilot plastic instruments under bundled payment contracts.
- Composite:Hybrid metal-polymer constructions balance rigidity with reduced weight. Research laboratories in Massachusetts evaluate composite prototypes for next-generation minimally invasive platforms.
Stainless steel retains the largest installed base; titanium commands the steepest price premiums and strongest replacement pull.
End User:
Site-of-care economics reshape retractor specifications from capital equipment to disposable alternatives.
- Hospitals:Integrated delivery networks negotiate multi-year instrument service contracts spanning sterilization, tracking, and blade refurbishment. CMS reimbursement determinations for inpatient cervical fusion sustain replacement cycles at academic medical centers.
- Ambulatory Surgical Centers:Outpatient decompression cases under bundled payments favor compact, self-retaining systems with rapid turnover. Southeastern United States ASC chains are consolidating procurement under single-vendor spine portfolios.
- Clinics:Limited procedure volumes drive rental and consignment models for occasional cervical interventions. Pain management clinics in Texas utilize clinic-grade retractors for diagnostic injections and minor decompressions.
- Research Laboratories:Preclinical and biomechanical studies demand instrument platforms compatible with imaging and robotic integration. Massachusetts and California research institutes prototype next-generation retractor mechanisms.
Hospitals absorb the majority of current procurement value; ambulatory surgical centers are climbing the fastest as site-of-care migration accelerates.
Application:
Procedural specialization dictates blade width, angulation, and fixation arm compatibility.
- Orthopedic Surgery:Anterior cervical discectomy and fusion procedures require 12 mm to 40 mm blade spans with deep tissue reach. United States orthopedic surgery centers specify retractors compatible with interbody cage insertion systems.
- Neurosurgery:Posterior cervical laminectomy and foraminotomy demand precise nerve root visualization without dural compression. German neurosurgical departments prioritize low-profile blade designs for posterior approaches.
- Rehabilitation:Postoperative motion preservation and hardware removal cases utilize lighter retractor configurations. Japanese rehabilitation hospitals employ specialized instruments for secondary procedures.
- Diagnostic Procedures:Biopsy and exploratory cervical access require minimal tissue disruption. Outpatient diagnostic centers in Florida deploy compact hand-held systems for rapid patient throughput.
Orthopedic surgery anchors current demand; neurosurgery applications are expanding most quickly as posterior minimally invasive techniques mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating final assembly and sterilization validation operations toward jurisdictions with streamlined medical device pathways, exploiting gaps between FDA 510(k) efficiency and EU MDR documentation burdens to preserve margin structures.
United States
Aging demographics sustain cervical fusion volumes among patients over 65, driving instrument replacement cycles at academic medical centers. FDA 510(k) premarket notification pathways for Class II surgical instruments accelerate clearance timelines for incremental design improvements. Texas and Florida ASC chains pilot consignment inventory models that transfer working capital burden upstream to vendors.
Germany
University hospitals maintain hand-held retractor configurations for resident training programs despite slower procedural throughput. EU MDR notified-body conformity assessment requirements and unique device identification mandates inflate regulatory compliance overhead for European market entry. Bavarian orthopedic surgery centers standardize on stainless steel instruments where budget predictability outweighs premium features.
Japan
PMDA QMS ministerial ordinances governing sterilization validation and biocompatibility testing shape protocols for imported instruments. METI industrial policy supports domestic production of medical-grade titanium components to reduce import dependency. Tokyo metropolitan spine institutes specify MRI-compatible titanium retractors for cases requiring intraoperative magnetic resonance navigation.
China
NMPA medical device registration reforms are compressing approval timelines for Class II surgical instruments below historical averages. MIIT industrial upgrading programs channel capital toward precision manufacturing of medical-grade stainless steel instrument lines. Yangtze River Delta medical device clusters are absorbing contract sterilization work previously routed through European facilities.
India
CDSCO medical device rules are converging toward global harmonization, though notified-body capacity constraints lengthen import clearance timelines. PLI scheme incentives for medical device manufacturing are attracting contract assembly operations for export-oriented instrument lines. Maharashtra orthopedic surgery centers are standardizing on modular blade systems that accommodate 12 mm to 40 mm swaps without full instrument replacement.
Cervical Retractors Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue expandable retractor configurations and ASC-compatible compact designs. The vendor base stratifies across three archetypes: integrated operating-room ecosystem providers, specialized expandable instrument designers, and scale-driven stainless steel manufacturers. Dominant competitive moves include bundled instrument contracts across IDN networks and backward integration into medical-grade titanium sourcing.
Among integrated delivery network suppliers, Stryker Corporation and Zimmer Biomet exemplify the ecosystem-anchored archetype, leveraging manufacturing scale and service infrastructure to sustain multi-year contracts. Globus Medical occupies a position within the specialized tier, with its corporate identity signaling focus on expandable instrument configurations. Johnson & Johnson represents the diversified health conglomerate model, sitting within portfolios where spine instruments complement broader surgical device offerings.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Globus Medical |
| Zimmer Biomet |
| Johnson & Johnson |
| Aesculap Implant Systems |
| TeDan Surgical Innovations |
| Boston Scientific Corporation |
| Thompson Surgical Instruments |
| Others |
Value Chain & Pricing Dynamics
Modular blade system adoption is compressing procurement economics across hospital supply chains while simultaneously redistributing manufacturing value toward precision-machining centers in Germany and Japan. This technology transition elevates titanium forging capacity as the binding constraint on premium-tier supply, forcing vendors to absorb sterilization validation costs or surrender margin to specialized component suppliers.
Pricing Analysis
Distributor margins on stainless steel instrument lines have compressed to single-digit percentages as IDN procurement teams unbundle blade supply from handle contracts. Three-tier pricing structure across premium titanium, standard stainless steel, and economy polymer levels reflects MRI compatibility certification and sterilization cycle durability. Pricing pressure stems from EU MDR compliance cost inflation that vendors cannot fully pass to German university hospitals. Ambulatory surgical centers exhibit highest price sensitivity due to bundled payment caps, while United States academic medical centers prioritize lifetime cost over acquisition price.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume retractor demand from integrated delivery networks, bypassing traditional distributor warehousing in southeastern United States health systems. Manufacturing concentration rests in Germany, Japan, and United States for medical-grade titanium forging and precision blade machining. Raw material dependencies center on aerospace-grade titanium sponge, surgical stainless steel bar stock, and medical polymer feedstocks. Single-source vulnerability characterizes titanium sponge supply from specialized metallurgical facilities. Distribution runs through vendor-managed inventory programs and consignment models that transfer working capital burden upstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cervical retractors market functions as a regulatory compounder where EU MDR unique device identification mandates and FDA 510(k) pathway efficiencies simultaneously expand compliance overhead and accelerate premium product clearance timelines.
For Market Incumbents: To counter margin compression from MDR-driven documentation costs, Stryker Corporation and Zimmer Biomet should deepen backward integration into medical-grade titanium sourcing and expand sterilization validation capacity in Yangtze River Delta clusters. Hospital system partnership consolidation represents the priority defensive lever.
For New Entrants and Emerging Players: Begin with expandable retractor configurations for anterior cervical approaches, the most penetrable white space against fixed-blade incumbents. Target ambulatory surgical center procurement committees in Florida and Texas with compact, self-retaining systems priced for bundled payment economics. Pursue direct-to-ASC distribution bypassing traditional hospital supply chain intermediaries.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized expandable instrument designers with limited regulatory infrastructure. Long-term viability hinges on 5-10 year site-of-care migration toward outpatient settings. Watch CMS reimbursement determinations for cervical decompression procedures as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Automation | Reduces notified-body resubmission costs for titanium instrument lines under EU conformity assessment. |
| ASC Consignment Inventory Partnership | Transfers working capital burden to vendors while securing exclusive procurement relationships in Texas and Florida. |
| Titanium Forging Backward Integration | Captures margin from aerospace-grade sponge processing and insulates against raw material price volatility. |
| Table-Mounted Robotic Arm Compatibility | Positions retractor systems within integrated operating-room ecosystems dominated by Stryker and Zimmer Biomet. |
| Japan PMDA QMS Infrastructure Investment | Creates first-mover advantage for sterilization validation protocols under ministerial ordinances governing imported instruments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR notified-body submission databases, CMS Medicare reimbursement determinations, and hospital procurement contract records. Bottom-up instrument shipment estimates and top-down market sizing triangulated across manufacturer disclosures and distributor channel checks.
Segment-weighting applied product type, material specification, end-user channel, and application splits across the projection horizon, with titanium versus stainless steel material mix and hospital versus ASC site-of-care migration serving as primary forecast drivers. CAGRs derived from procedural volume elasticity to aging demographics and reimbursement policy shifts, stress-tested against regulatory approval timeline scenarios and raw material cost assumptions.
Several conditions sit outside the modeled scope, including disruptive surgical robotics adoption, novel biomaterial substitutions, and radical CMS payment model reforms. Forecasts reflect documented assumptions regarding MDR implementation pace and ASC case migration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Gastric Electrical Stimulators Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Indian Laparoscopy Devices Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Pedicle Screw Systems Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Subcutaneous Injection Ports Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Deaver Retractor Market
Medical Devices
Digital X-Ray Devices Market
Medical Devices
Japan Hemostats Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market