
 Infrared Heating Pad Market | 2026-2036
Infrared Heating Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Heating Pad Market Foresight
The infrared heating pad category is restructuring around a sharp split between clinical-grade devices with calibrated wavelength output and mass-market units competing on price alone. Therasage leverages proprietary gemstone-infused ceramic technology to command premium positioning in wellness channels. Beurer GmbH sustains broad European distribution through standardized CE-marked product lines. UTK Technology anchors its position in North America with jade and tourmaline composite pads targeting physical therapy clinics.
Infrared heating pads are therapeutic devices that emit far-infrared radiation, typically through carbon fiber, ceramic, or jade/tourmaline composite elements operating at wavelengths between 5 and 15 microns, designed to penetrate tissue depths of several centimeters for localized thermal therapy. Product type segmentation shows portable pads capturing the fastest volume growth as consumers prioritize home-based treatment flexibility, while electric blankets remain the most mature sub-category with compressed margins and consolidated retail shelf space. Application segmentation reveals pain relief as the dominant revenue pool, though injury recovery protocols in sports medicine settings are generating disproportionate margin contribution per unit sold.
FDA Class II medical device regulations govern therapeutic claims in the United States, while CE marking under the EU MDR framework controls market access across European member states, with both regimes intensifying scrutiny of electromagnetic compatibility and thermal safety thresholds. The EU F-Gas Regulation indirectly shapes component sourcing for heating element manufacturing, pushing suppliers toward fluorocarbon-free production processes. Stakeholders must monitor evolving electrical safety standards and reimbursement code developments for thermal therapy modalities to anticipate which product configurations will retain channel access.
Market Dynamics
The infrared heating pad market is splitting between clinical-grade devices with calibrated wavelength output and mass-market units competing solely on price, as FDA intensifies documentation requirements for thermal output claims on Class II medical devices.
Growth Catalysts
- Aging demographics in the United States:The 65-plus population drives demand for home-based pain management solutions, pulling volume toward premium ceramic and carbon-fiber models through direct-to-consumer channels.
- F-Gas Regulation in Europe:The EU framework pushes heating element suppliers toward fluorocarbon-free production processes, accelerating adoption of ceramic composite technologies that bypass restricted inputs.
- Sports medicine protocols:Post-injury recovery programs in physical therapy clinics are standardizing far-infrared units as core thermal therapy modalities, creating institutional pull-through for calibrated devices.
Market Restraints
- Input cost volatility in rare earth elements:Jade and tourmaline sourcing concentrates in limited mining jurisdictions, exposing manufacturers to price swings in gemstone-infused ceramic supply chains.
- Electromagnetic compatibility thresholds:FDA and CE marking regimes impose divergent testing protocols, forcing dual certification investments that compress margins for mid-tier producers.
- Substitution by low-cost electric blankets:Mature heating pad alternatives dominate mass retail with compressed pricing, limiting penetration of far-infrared technology in price-sensitive segments.
Strategic Opportunities
- Underpenetrated physical therapy networks in Germany:CE-marked product lines face less saturation than US clinical channels, offering first-mover positioning for standardized European distribution.
- Reimbursement code development:Evolving thermal therapy modality classifications in US insurance frameworks could unlock institutional purchasing for FDA-cleared devices.
- Convergence with wearable biosensors:Integration of temperature monitoring and infrared delivery creates closed-loop therapy systems for remote patient management platforms.
Industry Challenges
- Calibration technician scarcity:Clinical-grade wavelength verification requires specialized electromagnetic testing expertise that outpaces vocational training pipeline output.
- Legacy retail shelf consolidation:Electric blanket incumbents command fixed retail space allocations, constraining point-of-sale visibility for differentiated infrared products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Heating Pad Market |
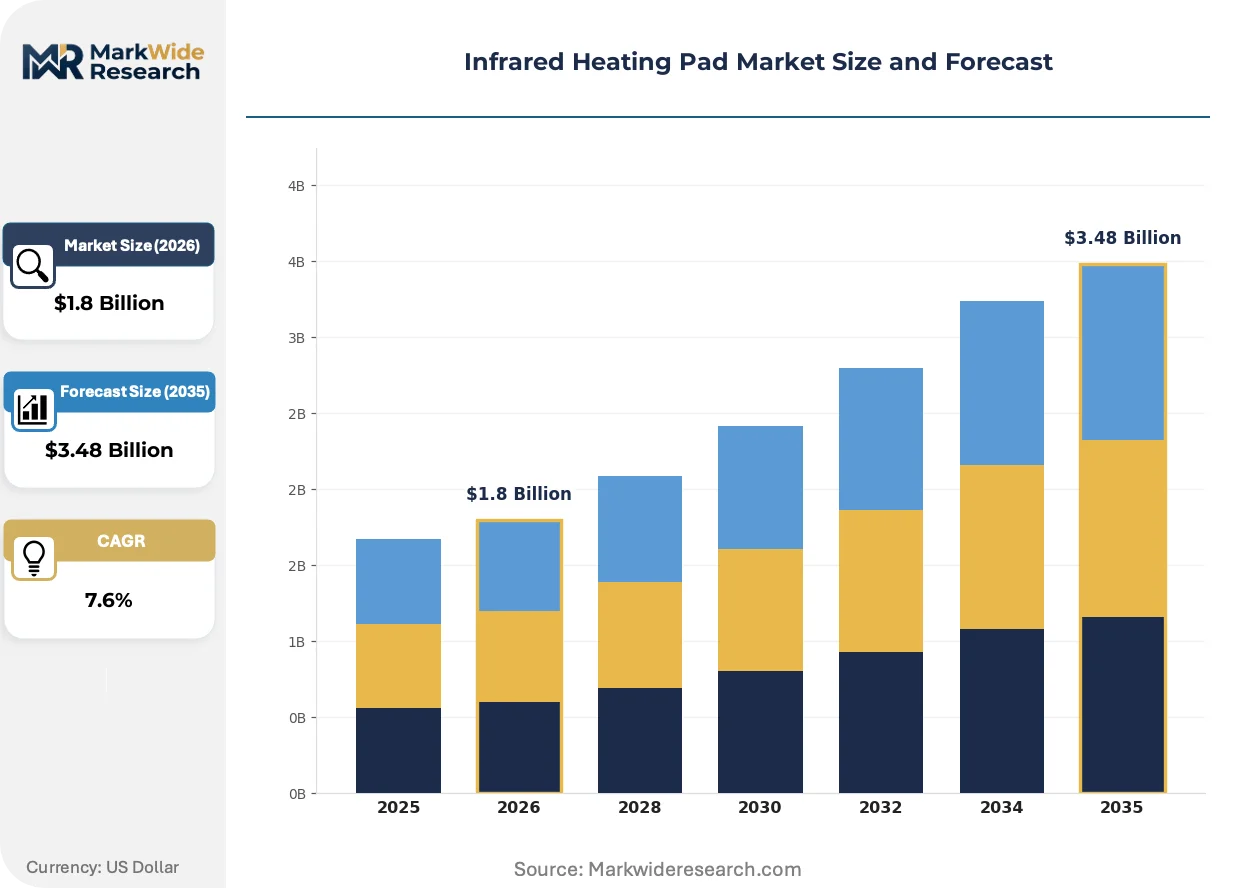
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Pads, Electric Blankets, Wraps, Massage Mats Application: Therapeutic Use, Pain Relief, Muscle Relaxation, Injury Recovery End User: Households, Professional Therapists, Sports Clinics, Rehabilitation Centers Distribution Channel: Online Stores, Retail Outlets, Wholesale Distributors, Pharmacies |
| Companies Covered | BodyMed, Therasage, Daiwa Felicity Inc., UTK Technology, Beurer GmbH, Sunbeam Products Inc., Drive DeVilbiss Healthcare, Medtronic, PureRelief, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Heating Pad Market Shifts & Advancements
Product architecture is pivoting from standalone heating elements toward integrated therapy systems, with wavelength precision and connectivity emerging as the primary axes of differentiation.
Gemstone-infused ceramic emitters are expanding into calibrated therapeutic applications. These composites leverage jade and tourmaline to deliver targeted far-infrared output between 5 and 15 microns. Physical therapy clinics in the United States are adopting these units at accelerating pace for post-injury protocols. The technology is expanding into premium positioning that separates clinical-grade devices from mass-market alternatives.
MDR intensifies scrutiny of thermal safety thresholds across European member states. The framework mandates updated electromagnetic compatibility documentation for all CE-marked therapeutic devices. Manufacturers face compressed certification timelines and expanded technical file requirements. Portable pad segments targeting home-use channels are responding by front-loading compliance investments before 2025 transitional deadlines.
Direct-to-consumer channels are displacing traditional retail distribution for premium infrared devices. Wellness-focused buyers now research wavelength specifications and FDA clearance status before purchase, bypassing big-box intermediaries. This pattern concentrates in United States suburban markets where aging homeowners prioritize home-based treatment flexibility over clinic visits.
Infrared Heating Pad Market Segmentation
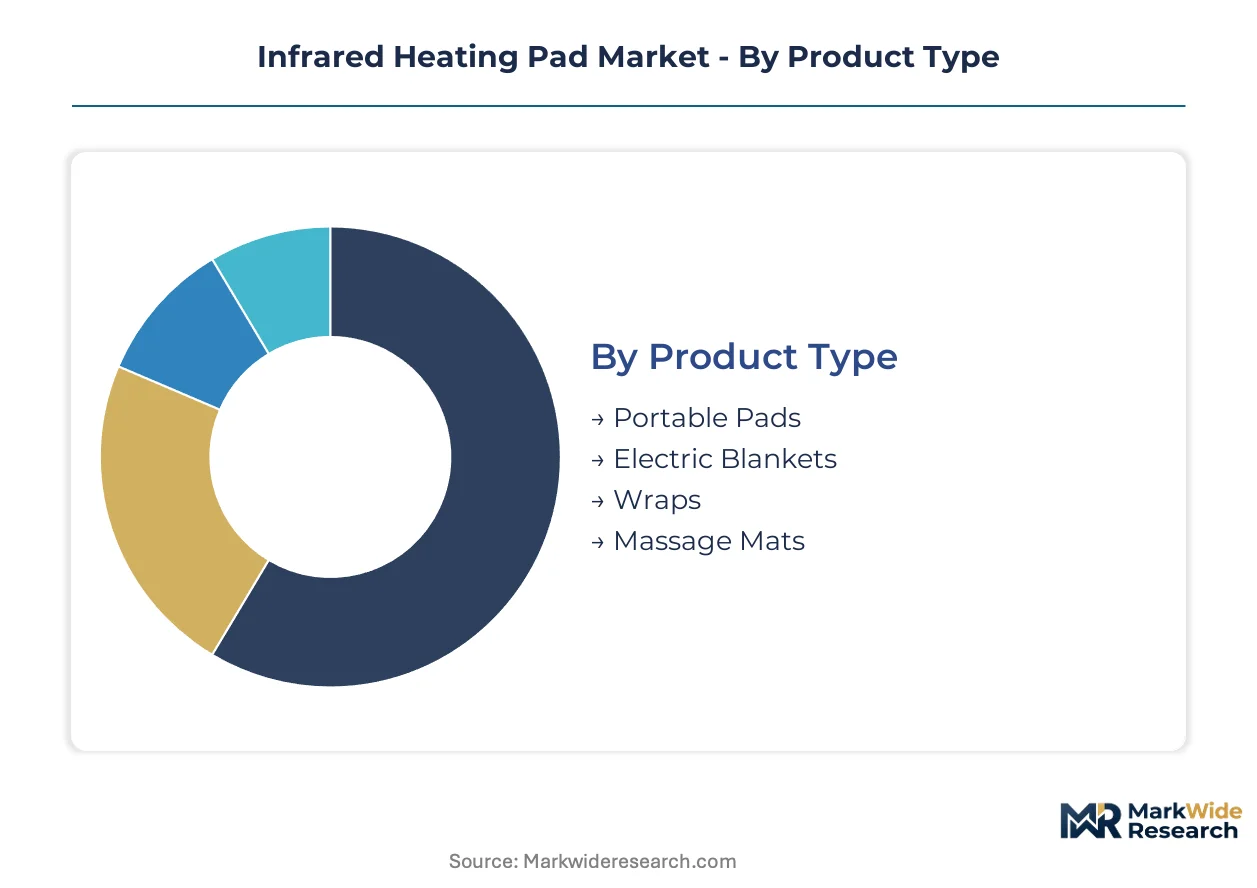
Infrared heating pad manufacturers face divergent engineering and certification requirements across use cases. Product specifications, wavelength calibration standards, and distribution economics vary sharply between home-use and clinical deployments.
Product Type:
Buyers prioritize portability against treatment surface area when selecting form factors.
- Portable Pads:Carbon-fiber and ceramic composite elements power lightweight units designed for home-based therapy flexibility. Demand concentrates in United States suburban markets where aging homeowners seek clinic-equivalent treatment without travel overhead.
- Electric Blankets:Mature heating wire technology dominates mass retail with standardized voltage systems and compressed margin structures. Legacy shelf space allocations at big-box retailers constrain visibility for differentiated infrared alternatives.
- Wraps:Targeted joint and limb coverage through flexible gemstone-infused fabrics. Physical therapy clinics in Germany are standardizing these for post-operative protocols.
- Massage Mats:Full-body surface arrays combining infrared emission with mechanical vibration elements. Wellness channel distributors in Japan favor these for premium home spa positioning.
Volume sits with Electric Blankets; growth tilts toward Portable Pads.
Application:
Therapeutic claims determine regulatory pathway and reimbursement eligibility.
- Pain Relief:Dominant revenue pool targeting chronic condition management through localized thermal therapy. United States direct-to-consumer channels drive premium ceramic model adoption among Medicare-eligible populations.
- Injury Recovery:Sports medicine protocols demand calibrated wavelength output between 5 and 15 microns for tissue penetration verification. FDA Class II documentation requirements intensify for thermal output claims in this segment.
- Therapeutic Use:Broad wellness positioning without specific pathology targeting. CE marking under EU MDR governs market access for general health maintenance claims.
- Muscle Relaxation:Fitness and athletic recovery applications favor rapid-heat carbon-fiber elements. Gym chains in South Korea are piloting rental programs for member recovery zones.
Revenue concentrates in Pain Relief; steepest expansion trajectory appears in Injury Recovery.
End User:
Procurement authority separates institutional specification from consumer discretion.
- Households:Individual purchasers researching wavelength specifications and FDA clearance status before direct-to-consumer acquisition. United States aging demographics pull volume toward premium jade and tourmaline composite models.
- Sports Clinics:Institutional procurement standardizing far-infrared units for post-injury thermal therapy protocols. Physical therapy networks in the United States generate disproportionate margin contribution per unit through calibrated device requirements.
- Professional Therapists:Licensed practitioners requiring electromagnetic compatibility documentation for clinical liability coverage. CE-marked product lines face less saturation in German clinical channels than United States equivalents.
- Rehabilitation Centers:Post-acute care facilities integrating infrared therapy into multidisciplinary recovery programs. Reimbursement code developments for thermal therapy modalities could unlock institutional purchasing volumes.
Unit economics favor Sports Clinics; household penetration offers scale expansion.
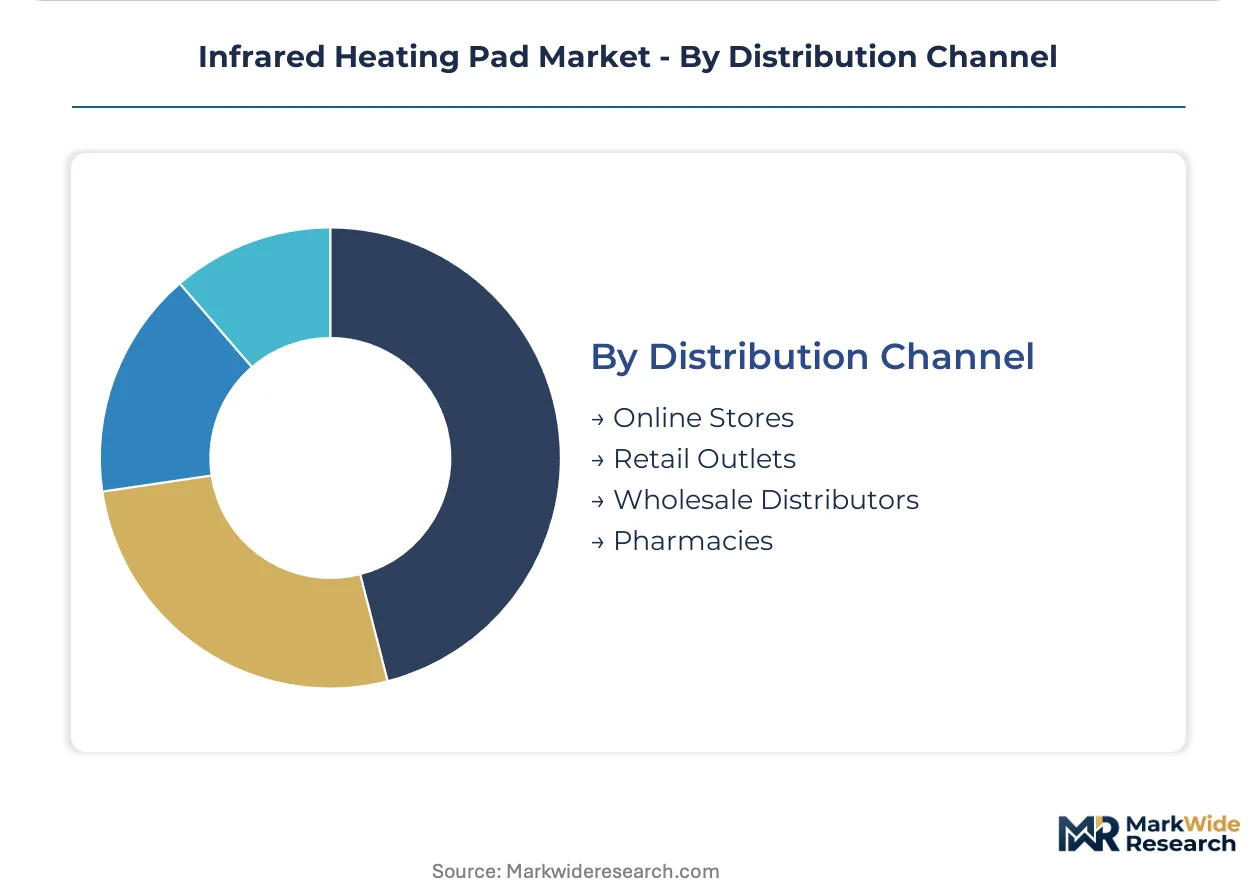
Distribution Channel:
Channel selection determines margin structure and buyer education depth.
- Online Stores:Wellness-focused buyers bypass retail intermediaries to research technical specifications directly. Direct-to-consumer growth concentrates in United States markets where suburban homeowners prioritize home-based treatment flexibility.
- Retail Outlets:Big-box and specialty wellness chains provide tactile evaluation for first-time purchasers. Electric blanket incumbents command fixed shelf space allocations that constrain point-of-sale visibility for differentiated infrared products.
- Wholesale Distributors:Institutional procurement channels serving physical therapy and rehabilitation networks. Calibration technician scarcity complicates post-sale support requirements for clinical-grade wavelength verification.
- Pharmacies:Trusted health retail positioning for pain relief applications. FDA clearance status drives placement decisions for therapeutic claim eligibility.
Transaction volume flows through Retail Outlets; margin expansion concentrates in Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors infrared heating pad component sourcing, with ceramic emitter and carbon-fiber element suppliers clustering in Guangdong Province's Pearl River Delta industrial zone.
United States
Aging suburban homeowners in Florida and Arizona drive direct-to-consumer demand for portable jade-composite units. FDA Class II medical device documentation requirements intensify for thermal output claims on therapeutic devices. Physical therapy networks in Phoenix and Tampa standardize calibrated far-infrared protocols for post-injury rehabilitation programs.
Germany
Professional therapist networks in Bavaria and North Rhine-Westphalia underutilize CE-marked infrared devices relative to United States saturation levels. EU MDR electromagnetic compatibility documentation mandates compress certification timelines for market entrants. Medical device distributors in Munich accelerate fluorocarbon-free ceramic composite sourcing to align with F-Gas Regulation compliance pathways.
Japan
Wellness channel distributors in Tokyo and Osaka favor full-body massage mat configurations combining infrared emission with mechanical elements. METI energy efficiency standards shape heating element specifications for residential therapeutic devices. Prefecture-level rehabilitation centers in Kanagawa pilot institutional procurement programs for post-acute thermal therapy integration.
South Korea
Fitness chain operators in Seoul Capital Area test rental-based recovery zone models featuring rapid-heat carbon-fiber pads. MFDS medical device classification rules govern therapeutic claim eligibility for institutional sales channels. Busan-Ulsan manufacturing clusters supply ceramic emitter components to regional original equipment manufacturers.
Canada
Household purchasers in Ontario and British Columbia research FDA-cleared device specifications through cross-border e-commerce channels. Health Canada medical device licensing requirements create parallel certification obligations for United States manufacturers seeking northern market access. Vancouver wellness retailers stock gemstone-infused models targeting premium home spa positioning.
Infrared Heating Pad Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as ceramic foundry operators maintain in-house emitter manufacturing while wellness brands outsource carbon-fiber element fabrication. The vendor base splits between integrated ceramic composite specialists and assembly-focused marketers. Three archetypes dominate: gemstone-infused premium positioning, standardized CE-marked European distribution, and direct-to-consumer wavelength specification transparency. Competitive moves concentrate on dual certification investments for FDA and CE marking alignment, plus direct-to-consumer channel displacement of traditional retail intermediaries.
Within the premium gemstone-composite tier, Therasage and UTK Technology exemplify North American positioning built on proprietary ceramic formulations and jade-tourmaline emitter architectures. Beurer GmbH represents the standardized European distribution archetype, leveraging GmbH structure and broad CE-marked product lines across less saturated clinical channels in Germany. These three anchors illustrate how geographic origin and corporate form signal divergent strategic postures without requiring specific operational claims.
| Leading Market Players |
|---|
| BodyMed |
| Therasage |
| Daiwa Felicity Inc. |
| UTK Technology |
| Beurer GmbH |
| Sunbeam Products Inc. |
| Drive DeVilbiss Healthcare |
| Medtronic |
| PureRelief |
| Others |
Supply & Pricing Matrix
Rare earth element indices for jade and tourmaline feed directly into ceramic emitter cost structures, compressing margins for gemstone-infused premium tiers while carbon-fiber alternatives capture price-sensitive volume through standardized Guangdong sourcing.
Pricing Analysis
Calibrated wavelength output serves as the value-based pricing anchor, with FDA-cleared clinical units commanding substantial premiums over uncertified home-use alternatives. Three-tier pricing structure across premium, standard, and economy levels separates gemstone-composite clinical devices from ceramic home units and basic carbon-fiber mass-market pads. Pricing pressure stems from electric blanket substitution in big-box retail, squeezing visibility for differentiated infrared products. Household direct-to-consumer buyers show lowest price sensitivity when researching FDA clearance status, while mass retail channels face acute compression from legacy heating wire incumbents.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Dongguan coordinate hub-and-spoke patterns for ceramic emitter components before final assembly in United States and European packaging facilities. Manufacturing gravity centers on China for carbon-fiber elements and ceramic substrates, with Germany and Japan contributing precision calibration equipment. Raw material flows draw from Myanmar jade deposits, Brazilian tourmaline mines, and Guangdong carbon-fiber weaving operations. Single-source vulnerability concentrates in gemstone-infused ceramic supply chains where limited mining jurisdictions expose producers to export restriction risks. Distribution runs through wholesale medical device distributors for clinical channels and direct-to-consumer platforms for premium home units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration technician scarcity props pricing for clinical-grade devices, as electromagnetic testing expertise outpaces vocational training pipeline output across United States and European markets.
For Market Incumbents: Cement channel control through exclusive wholesale distributor agreements for physical therapy networks, while accelerating backward integration into ceramic foundry operations to secure gemstone-infused emitter supply. Low-cost electric blanket substitution threatens mass-market positioning, requiring defensive certification investments in FDA Class II pathways to maintain therapeutic claim eligibility. Capacity addition in fluorocarbon-free ceramic production aligns with EU F-Gas Regulation compliance timelines. For New Entrants and Emerging Players: Professional therapist networks in Germany represent an underserved buyer archetype with less saturation than United States clinical channels, offering first-mover positioning for standardized CE-marked product lines. Wrap configurations targeting post-operative protocols in Bavaria and North Rhine-Westphalia present the most penetrable segment, with direct-to-consumer wavelength specification transparency as the primary go-to-market angle bypassing retail intermediaries. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated ceramic composite specialists with captive gemstone sourcing in Guangdong Province, as input cost volatility squeezes asset-light assembly marketers. Long-term viability over the next decade hinges on reimbursement code development unlocking institutional purchasing volumes for thermal therapy modalities. Watch FDA clearance timeline acceleration for portable pad segments as the inflection indicator signaling competitive consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous FDA and CE marking alignment opens United States and German clinical channels while compressing competitor certification timelines. |
| Direct-to-Consumer Channel Expansion | Bypassing big-box retail intermediaries captures aging suburban homeowners researching wavelength specifications before purchase. |
| Gemstone Sourcing Integration | Captive supply of Myanmar jade and Brazilian tourmaline insulates against rare earth element price volatility in ceramic emitter production. |
| Calibration Technician Training Programs | Internal electromagnetic testing expertise development addresses vocational pipeline gaps constraining clinical-grade device verification capacity. |
| Wearable Biosensor Convergence | Temperature monitoring integration creates closed-loop therapy systems for remote patient management platforms in sports medicine settings. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation databases, and customs trade records for ceramic emitter components formed the secondary backbone, supplemented by primary interviews with biomedical engineers, physical therapy clinic procurement managers, GPO contracts specialists, and wellness channel distributors. Bottom-up and top-down triangulation validated shipment volumes against therapeutic device registration counts across United States and European markets.
Bottom-up modeling built from product-level specifications and channel pricing through calibrated wavelength tiers, while top-down analysis anchored aggregate demand in aging demographic projections and sports medicine protocol adoption rates. Segmentation dimensions included product type, application, end user, and distribution channel across the analysis window. CAGRs derived from regression against historical medical device reimbursement trends and thermal therapy modality code development trajectories, with ceramic composite technology cost curves and F-Gas Regulation compliance timelines as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA documentation requirement intensification, rare earth element export restrictions, and electromagnetic compatibility threshold revisions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Europe C-Arms Market
Medical Devices
Recanalization System Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Corneal Implants Market
Medical Devices
Advanced Infusion Systems Market
Medical Devices
Global Capillary Blood Collection Devices Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Global Otoscopes Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Penile Prosthesis Market
Medical Devices
Europe Breast Implant Market
Medical Devices
3D-Printed Prosthetic Implants Market