
 Ultrasound Biometry Devices Market | 2026-2036
Ultrasound Biometry Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Biometry Devices Market Analytics
High-frequency transducer miniaturization is narrowing the performance gap between compact handheld units and cart-based diagnostic systems. Siemens Healthineers leverages its deep R&D pipeline in acoustic beamforming to sustain technology leadership across premium cart-based installations. Mindray Medical International Limited anchors its competitive position through manufacturing scale and aggressive penetration of mid-tier hospital networks across Asia. Canon Medical Systems Corporation differentiates via proprietary image reconstruction algorithms that reduce measurement variability in axial length determination.
Ultrasound biometry devices employ piezoelectric crystal arrays operating at 10-20 MHz to generate acoustic pulses for precise ocular axial length measurement, with automated IOL power calculation representing the primary commercial purpose in cataract surgical planning. Portable ultrasound systems capture expanding share in ambulatory settings where space constraints and patient throughput demands favor mobile form factors over fixed installations. Digital ultrasound technology dominates the installed base while contrast-enhanced modalities attract investment from research institutions pursuing novel anterior segment imaging protocols. The obstetrics application segment remains mature with stable replacement cycles, whereas musculoskeletal biometry applications demonstrate the fastest adoption trajectory among emerging clinical use cases.
The FDA maintains stringent acoustic output limits under the 510(k) framework while ISO 13485 quality system certification governs manufacturing standards for international market access. The European Medical Device Regulation imposes enhanced clinical evidence requirements that extend approval timelines but elevate barriers against lower-tier competitors. China's National Medical Products Administration accelerates domestic innovation through prioritized review pathways for indigenously developed biometry platforms. Stakeholders must monitor evolving reimbursement thresholds for optical biometry versus ultrasound-based alternatives as payors recalibrate coverage policies based on comparative effectiveness evidence.
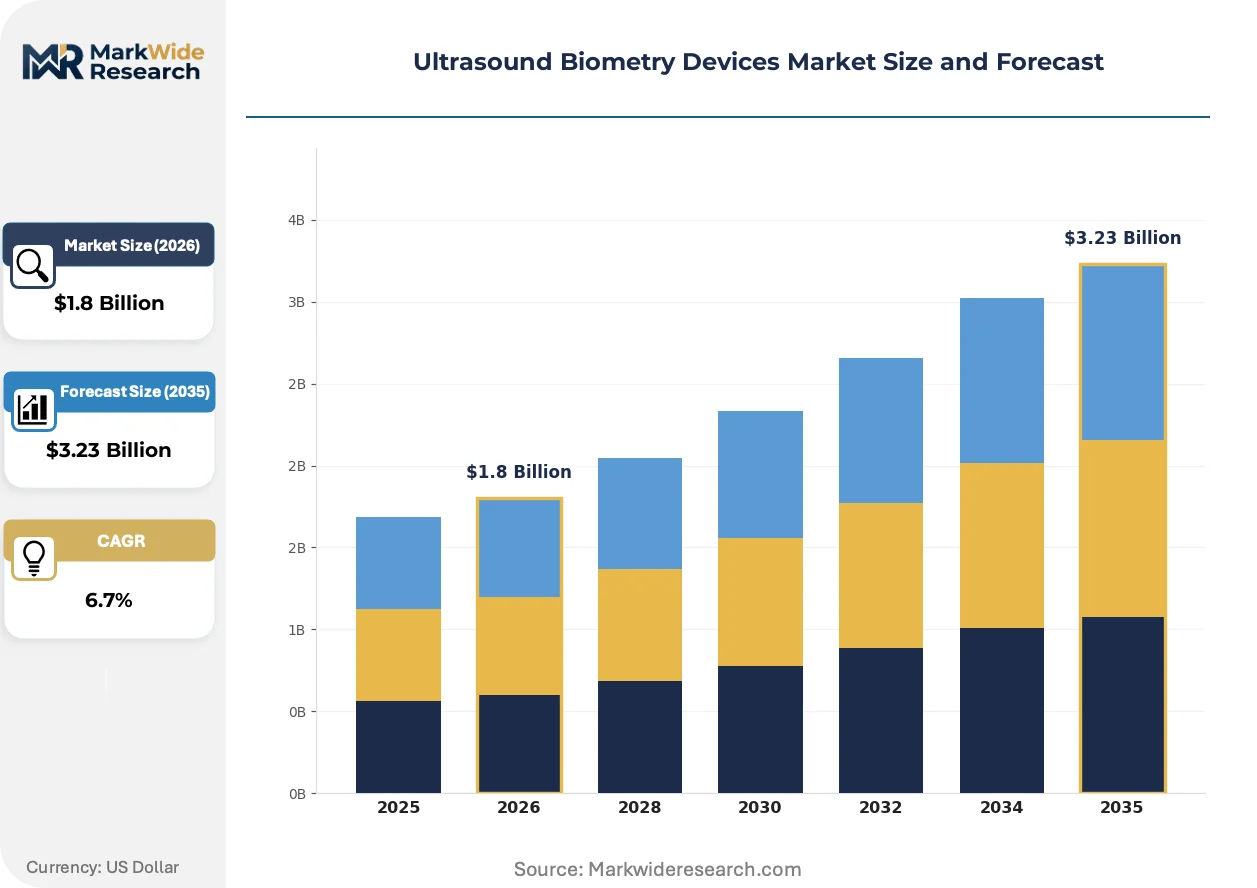
Market Dynamics
High-frequency transducer miniaturization is compressing the performance differential between handheld portable units and premium cart-based diagnostic systems, forcing incumbent manufacturers to defend installed base positions through software differentiation and service bundling rather than hardware specifications alone.
Growth Catalysts
- 510(k) Clearance Acceleration:The FDA's streamlined diagnostic ultrasound pathway compresses commercialization timelines for manufacturers pursuing biometry platform launches. Device developers leverage this regulatory efficiency to iterate acoustic beamforming algorithms faster.
- Ophthalmology Clinic Modernization:Practices across China execute replacement cycles for legacy A-scan systems under provincial hospital network tenders. Swept-source optical coherence biometry integration drives equipment refresh decisions.
- Piezoelectric Crystal Arrays:Advances in 10-20 MHz transducer fabrication yield improved axial length measurement precision. Automated IOL power calculation functionality anchors cataract surgical planning workflows.
Market Restraints
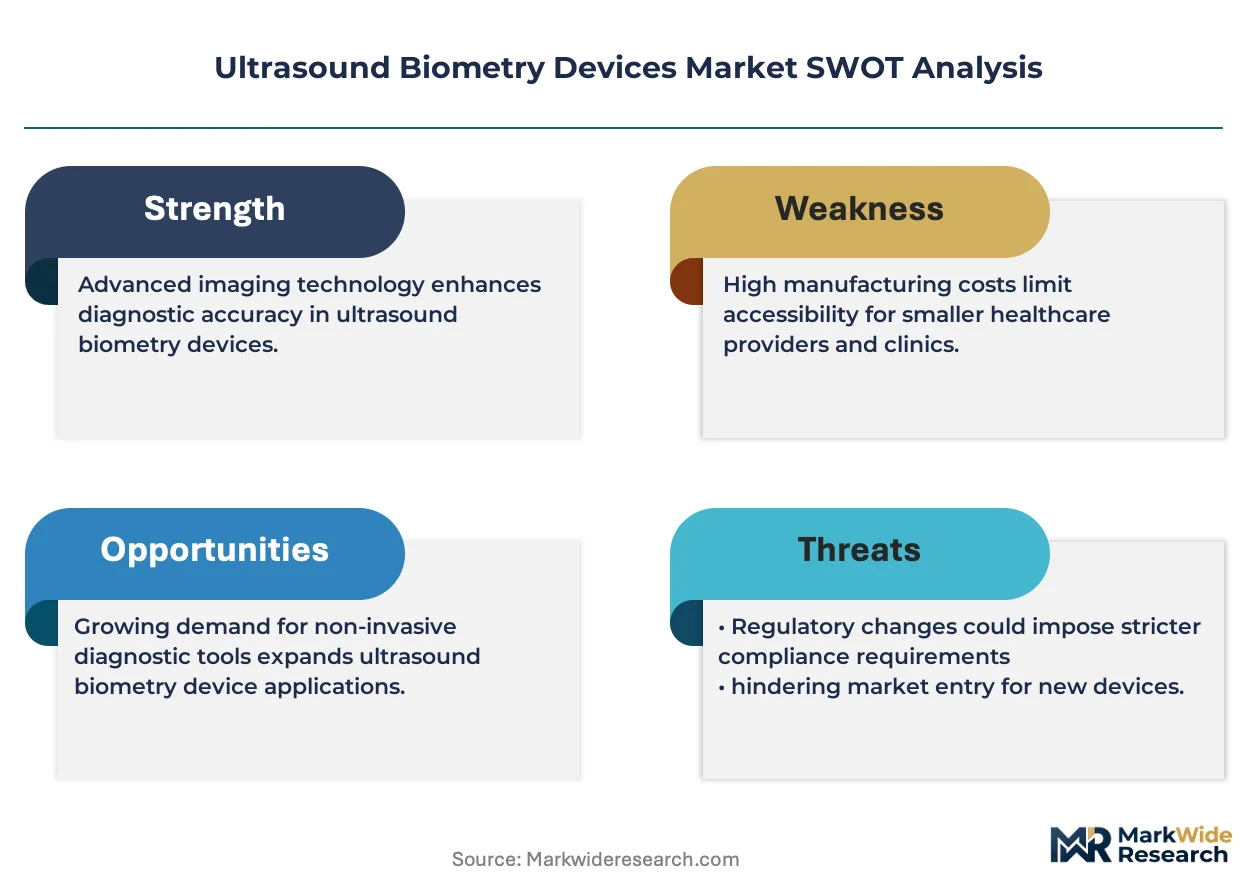
- Optical Biometry Substitution:Partial coherence interferometry and swept-source OCT platforms capture share in premium cataract surgery settings. Ultrasound-based alternatives face reimbursement compression as payors recalibrate coverage thresholds.
- European MDR Compliance Burden:Enhanced clinical evidence requirements extend approval timelines for manufacturers targeting EU markets. ISO 13485 certification alone proves insufficient for market access under the new framework.
- Input Concentration Risk:Specialized piezoelectric ceramic supply concentrates among Japanese and Chinese material processors. Acoustic lens fabrication capabilities remain geographically clustered.
Strategic Opportunities
- Musculoskeletal Biometry Expansion:Orthopedic clinics and sports medicine practices represent underpenetrated demand for portable ultrasound systems. Tendon and ligament measurement protocols drive application development.
- China NMPA Prioritized Review:Domestic manufacturers of indigenously developed biometry platforms receive accelerated regulatory assessment. National healthcare infrastructure mandates concentrate procurement through centralized hospital network tenders.
- Contrast-Enhanced Anterior Segment Imaging:Research institutions pursue novel protocols combining microbubble contrast with high-frequency biometry. Academic medical centers fund pilot programs for corneal and ciliary body visualization.
Industry Challenges
- Acoustic Physicist Talent Scarcity:Specialized expertise in high-frequency beamforming and acoustic lens design concentrates among aging specialists. Training pipelines fail to replenish technical depth at required velocity.
- Legacy System Integration Complexity:Hospital information systems and electronic health record platforms require customized middleware for biometry data exchange. IT security protocols complicate device connectivity deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Biometry Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Portable Ultrasound, Handheld Ultrasound, Diagnostic Ultrasound, 3D/4D Ultrasound End User: Hospitals, Clinics, Imaging Centers, Research Institutions Technology: Digital Ultrasound, Analog Ultrasound, Electromagnetic Imaging, Contrast Ultrasound Application: Obstetrics, Cardiology, Urology, Musculoskeletal |
| Companies Covered | General Electric, Koninklijke Philips N.V., Siemens Healthineers, Canon Medical Systems Corporation, Mindray Medical International Limited, FUJIFILM Corporation, Hitachi Medical, Esaote S.p.A., Konica Minolta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Biometry Devices Market Evolving Landscape
Acoustic signal processing advances and regulatory pathway modernization are converging to reshape competitive positioning across portable and cart-based biometry platforms. Three developments warrant particular attention.
Swept-source optical coherence tomography is virtualizing the core measurement function historically performed by ultrasound biometry devices. Premium ophthalmology practices in Germany and Japan adopt these platforms for cataract surgical planning. The technology is virtualizing hardware requirements by embedding biometry within comprehensive anterior segment imaging workflows, compressing standalone ultrasound unit demand in high-end settings.
The European Medical Device Regulation imposes post-market surveillance obligations and clinical evidence standards that extend approval timelines beyond legacy medical device directive requirements. Manufacturers targeting EU markets must strengthen quality management systems and invest in real-world performance data collection. Mid-tier Asian exporters face particular pressure as notified bodies apply enhanced scrutiny to acoustic output safety documentation.
Hospital procurement departments increasingly unbundle device acquisition from multi-year service contracts that historically subsidized capital equipment pricing. Buyers in China's provincial hospital networks negotiate separate maintenance agreements and software subscription terms. This purchasing pattern shift compresses vendor margin structures and accelerates transparency in total cost of ownership calculations.
Ultrasound Biometry Devices Market Segmentation
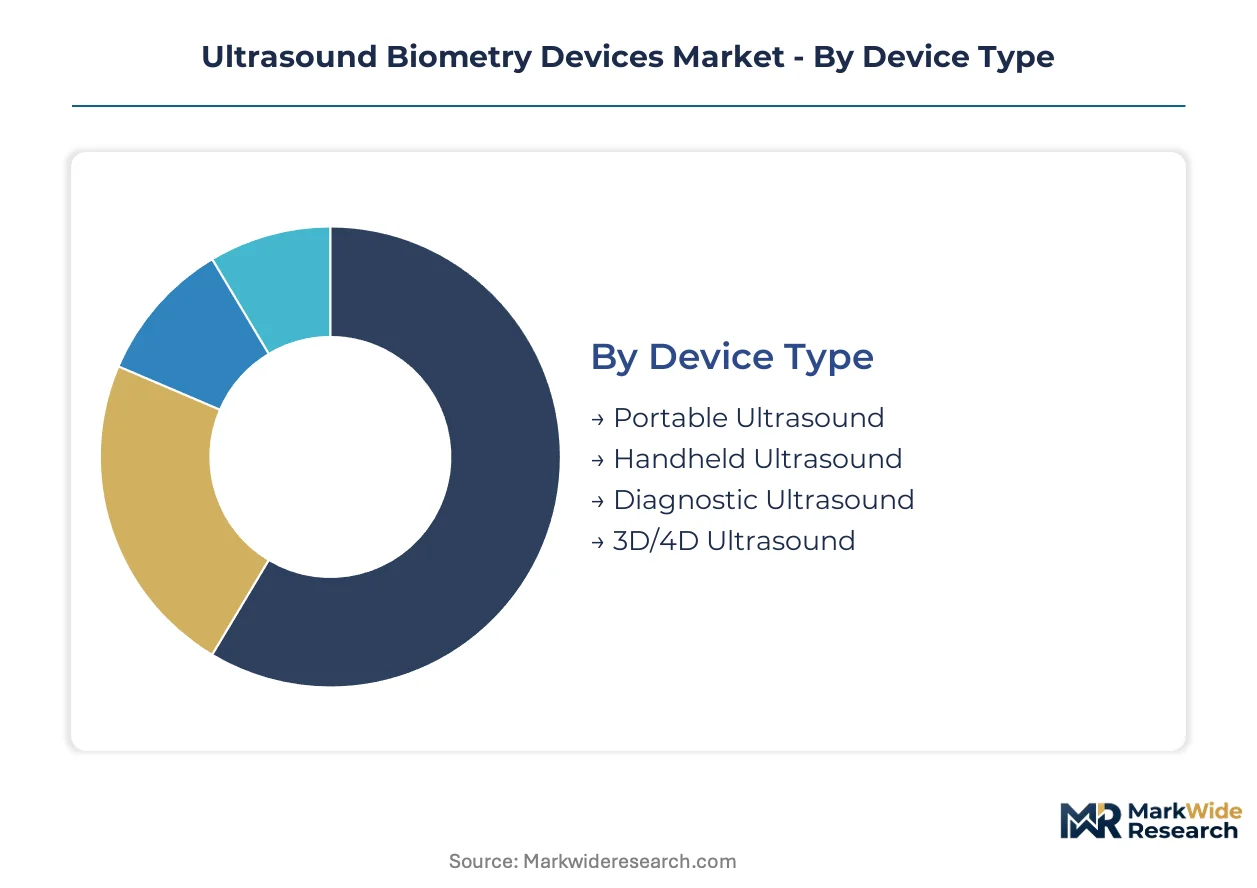
Ultrasound biometry devices serve distinct clinical workflows where form factor, throughput requirements, and measurement precision demands create natural purchase segmentation. Equipment refresh cycles vary dramatically across these dimensions, with portable systems turning over every 3-4 years versus 7-10 year lifespans for cart-based diagnostic installations.
Device Type:
Replacement velocity diverges sharply across this dimension, with compact mobile units cycling fastest due to battery degradation and sensor wear in high-mobility deployments.
- Portable Ultrasound:Battery-powered cart-based systems with integrated displays serve ambulatory surgical centers and satellite clinic networks. Demand concentrates in China's tier-2 city hospital expansions where space constraints and patient volume favor mobile configurations over fixed installations.
- Handheld Ultrasound:Smartphone-connected probe formats weighing under 300 grams enable point-of-care biometry in bedside and field settings. Sports medicine practices and veterinary ophthalmology represent emerging demand pockets for these ultra-compact units.
- Diagnostic Ultrasound:Full-featured cart systems with 10-20 MHz transducer arrays deliver reference-standard axial length precision for cataract surgical planning.
- 3D/4D Ultrasound:Volumetric acquisition systems with motorized transducer positioning support complex anterior segment reconstruction protocols.
Diagnostic ultrasound anchors the volume base while handheld ultrasound gains share at the steepest rate.
End User:
Capital allocation authority and procurement sophistication create tiered purchasing patterns across institutional buyer types.
- Hospitals:Integrated delivery networks with centralized biomedical engineering departments favor multi-year service contracts and enterprise fleet standardization. China's provincial hospital network tenders concentrate volume for high-frequency biometry platforms under national infrastructure mandates.
- Clinics:Independent ophthalmology practices and ambulatory surgery centers prioritize acquisition cost and footprint minimization. German and Japanese premium clinics drive displacement of legacy A-scan systems with swept-source OCT-integrated biometry workflows.
- Imaging Centers:Dedicated diagnostic facilities balance equipment utilization rates across mixed-modality service menus.
- Research Institutions:Academic medical centers fund pilot programs for contrast-enhanced anterior segment protocols and novel musculoskeletal measurement applications.
Hospitals anchor the volume base while clinics expand most quickly as independent practices modernize surgical planning capabilities.
Technology:
Manufacturing cost structures and intellectual property intensity separate premium digital platforms from legacy analog alternatives.
- Digital Ultrasound:Software-defined beamforming with FPGA-based signal processing dominates current installed base refresh decisions. FDA 510(k) pathway acceleration enables faster algorithm iteration for manufacturers with established quality management systems.
- Analog Ultrasound:Discrete component architectures persist in price-sensitive emerging market segments and secondary equipment markets.
- Electromagnetic Imaging:Non-acoustic modalities compete for select biometry applications where tissue penetration depth requirements exceed ultrasound limits.
- Contrast Ultrasound:Microbubble-enhanced imaging attracts research funding for corneal and ciliary body visualization protocols.
Digital ultrasound anchors the volume base while contrast ultrasound climbs the fastest as academic centers pioneer novel anterior segment applications.
Application:
Clinical evidence maturity and reimbursement stability create divergent expansion trajectories across specialty use cases.
- Obstetrics:Fetal biometry for gestational age estimation represents the most mature application with stable replacement demand. Established CPT coding and universal insurance coverage sustain predictable procurement patterns in US hospital systems.
- Cardiology:Echocardiography-derived measurements support structural heart intervention planning and device sizing.
- Urology:Prostate volume estimation and bladder wall thickness measurement drive urology clinic adoption.
- Musculoskeletal:Tendon thickness and ligament length protocols expand fastest among orthopedic and sports medicine practices seeking non-radiation alternatives to CT-based measurement.
Obstetrics anchors the volume base while musculoskeletal gains share fastest as orthopedic clinics adopt tendon and ligament measurement protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered acoustic transducer arrays to Japan's ophthalmology equipment manufacturers, establishing the primary trade-flow corridor in high-frequency biometry components.
United States
Academic medical centers in Massachusetts and California fund contrast-enhanced anterior segment imaging research. The FDA's streamlined 510(k) clearance pathway compresses commercialization timelines for domestic biometry platform developers. Minneapolis and Boston anchor clusters where hospital procurement departments unbundle device acquisition from multi-year service contracts.
Germany
Premium ophthalmology practices in Bavaria and Baden-Württemberg displace legacy A-scan systems with swept-source OCT-integrated biometry workflows. The European Medical Device Regulation imposes enhanced clinical evidence requirements that extend approval timelines for manufacturers targeting EU markets. The Stuttgart-Munich corridor concentrates acoustic lens fabrication capabilities serving cart-based diagnostic system producers.
China
Provincial hospital networks in Jiangsu and Guangdong execute centralized tenders for high-frequency biometry systems under national healthcare infrastructure mandates. The National Medical Products Administration accelerates domestic innovation through prioritized review pathways for indigenously developed platforms. Shanghai and Shenzhen anchor manufacturing scale for mid-tier hospital network penetration across Asia.
Japan
Specialized piezoelectric ceramic supply concentrates among material processors in Osaka and Nagoya serving global transducer manufacturers. METI standards govern acoustic output safety documentation for domestic and export markets. The Tokyo-Yokohama corridor hosts aging acoustic physicist specialists whose expertise in high-frequency beamforming remains critical to industry technical depth.
India
Tier-2 city hospital expansions in Karnataka and Tamil Nadu favor mobile ultrasound configurations over fixed installations due to space constraints. CDSCO quality system certification governs manufacturing standards for international market access. Hyderabad and Bangalore emerge as service hubs supporting software-defined beamforming algorithm development for digital ultrasound platforms.
Ultrasound Biometry Devices Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers defined by manufacturing scale, software differentiation, and geographic focus. Siemens Healthineers leverages deep R&D pipelines in acoustic beamforming to sustain technology leadership across premium cart-based installations. Mindray Medical International Limited anchors competitive positioning through manufacturing scale and aggressive penetration of mid-tier hospital networks. Strategic moves concentrate on software-defined service bundling and unbundling of multi-year maintenance agreements from capital equipment pricing.
Among diversified health technology conglomerates, General Electric and Koninklijke Philips N.V. occupy positions spanning diagnostic imaging portfolios where biometry represents one modality among broader ultrasound system offerings. These manufacturers exemplify the scale-driven archetype competing through enterprise fleet standardization and integrated delivery network relationships. Canon Medical Systems Corporation sits within the precision imaging specialist tier, differentiating via proprietary image reconstruction algorithms that reduce measurement variability in axial length determination.
| Leading Market Players |
|---|
| General Electric |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Mindray Medical International Limited |
| FUJIFILM Corporation |
| Hitachi Medical |
| Esaote S.p.A. |
| Konica Minolta |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Japanese piezoelectric ceramic processors determines both the pricing tier spreads across portable, handheld, and cart-based biometry systems and the geographic clustering of acoustic lens fabrication capabilities. Procurement departments in China's provincial hospital networks exploit this concentration through unbundled service negotiations that compress vendor margins while accelerating transparency in total cost of ownership calculations.
Pricing Analysis
The technology-generation pricing gap between legacy analog systems, current digital platforms, and next-generation AI-enhanced biometry devices spans three distinct tiers. Pricing stratifies across premium cart-based installations with 10-20 MHz transducer arrays, standard portable configurations for ambulatory settings, and economy handheld units for point-of-care deployment. Price differentiation rests on ISO 13485 certification grade and after-sales service bundling. Cost compression in the mid-tier portable segment is intensifying because Mindray and domestic Chinese manufacturers scale manufacturing for provincial tenders. Independent ophthalmology clinics in Germany and Japan demonstrate the least price sensitivity as they prioritize swept-source OCT integration, while tier-2 city hospitals in India represent the most price-sensitive buyer archetype.
Supply Chain Analysis
Upstream feedstock for piezoelectric crystal arrays draws from specialized ceramic processors concentrated in Japan, China, and Germany. Lead zirconate titanate powders and precision-machined acoustic lenses represent critical input dependencies alongside FPGA chipsets for digital beamforming. Single-source vulnerability in high-frequency transducer fabrication creates exposure to export control shifts and raw material allocation priorities. Distribution runs through direct OEM relationships for premium cart-based systems and regional distributors for portable units serving mid-tier hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of acoustic physicists trained in high-frequency beamforming and acoustic lens design constrains technical depth across the industry, making specialized human capital the decisive competitive moat for the next decade.
For Market Incumbents: Insulate installed base positions through captive supply of piezoelectric ceramic processing and accelerated software subscription bundling. Siemens Healthineers and Canon Medical Systems should deepen backward integration into acoustic lens fabrication to offset substitution pressure from swept-source OCT platforms. Certification investment in China's NMPA prioritized review pathway secures access to the fastest-expanding procurement channel. For New Entrants and Emerging Players: Mid-tier hospital networks in India's tier-2 cities represent the most penetrable entry point given space constraints and unmet demand for mobile configurations. Musculoskeletal biometry applications in orthopedic and sports medicine practices offer a second white-space target with minimal incumbent saturation. A software-first go-to-market angle emphasizing automated IOL power calculation algorithms bypasses capital-intensive transducer manufacturing barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision imaging specialists with proprietary reconstruction algorithms and established FDA 510(k) clearance track records. Long-term viability over the next decade hinges on differentiation through measurement variability reduction rather than hardware specification competition. Watch for inflection signals in reimbursement policy shifts favoring optical biometry over ultrasound alternatives in premium cataract settings.| Strategic Initiative | Industry Significance |
|---|---|
| Acoustic Lens Fabrication Integration | Captive supply of precision-machined components reduces exposure to Japanese ceramic processor concentration. |
| NMPA Prioritized Review Pathway | Accelerated regulatory assessment unlocks access to China's centralized provincial hospital network tenders. |
| Software Subscription Unbundling | Separate maintenance agreements from capital equipment pricing respond to procurement department purchasing pattern shifts. |
| Musculoskeletal Application Development | Tendon and ligament measurement protocols address underpenetrated demand in orthopedic and sports medicine practices. |
| Contrast-Enhanced Imaging Pilot Programs | Academic medical center partnerships pioneer novel anterior segment protocols for corneal visualization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, ISO 13485 certification registries, and hospital procurement contract disclosures. The analysis draws from structured interviews with biomedical engineers at integrated delivery networks, GPO contracts managers, regulatory affairs specialists at device manufacturers, and ophthalmology practice administrators. Secondary validation incorporates CMS Medicare reimbursement data, China's National Healthcare Security Administration procurement records, and EUDAMED device registration filings. Bottom-up unit shipment estimates triangulate against top-down market value assessments across device type and end-user segments.
Forecast inputs incorporate modeled expansion trajectories across portable, handheld, diagnostic, and 3D/4D ultrasound device categories alongside hospital, clinic, imaging center, and research institution end-user splits. The analytical framework evaluates technology generation transitions from analog to digital to contrast-enhanced platforms across the projection horizon. CAGRs derive from regression analysis against historical replacement cycle patterns and provincial tender award velocities. Industry-specific inputs include acoustic physicist talent pipeline replenishment rates and swept-source OCT substitution elasticity in premium cataract surgical planning settings.
Practitioners should monitor reimbursement threshold recalibrations by payors and export control shifts affecting piezoelectric ceramic supply for early signals of forecast revision. Cross-checking against EUDAMED post-market surveillance data and China's centralized procurement award disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Struts Implants Market
Medical Devices
Smart Stairlift Market
Medical Devices
Asia-Pacific Medical Aesthetic Devices Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Absorbable Nasal Implant Market
Medical Devices
Corneal Surgery Devices Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Nerve Locator Stimulator Market