
 Pleural Cavity Drainage Market | 2026-2036
Pleural Cavity Drainage Market Size, Share, and Industry Trends Forecast 2026-2036
Pleural Cavity Drainage Market Analytics
Ambulatory surgical centers is repositioning pleural cavity drainage demand away from traditional inpatient settings. Merit Medical Systems sustains manufacturing scale across interventional product lines. Teleflex Incorporated dominates thoracic portfolio breadth through specialized catheter design. Cook Medical LLC navigates regulatory complexity with concentrated R&D investment in minimally invasive delivery systems.
Pleural cavity drainage encompasses closed-chest systems that evacuate air, blood, or fluid from the pleural space using tubes ranging from 6 Fr to 40 Fr with suction control between negative 10 and negative 40 cm H₂O. These systems prevent lung collapse, restore negative intrathoracic pressure, and enable postoperative recovery following thoracic surgery or trauma. Catheters lead product type revenue pools due to repeat procedural consumption, while video-assisted thoracoscopic surgery technology commands premium positioning through integration with operating room visualization platforms. Home care delivery mode represents the fastest-expanding channel as payors push cost reduction through early discharge protocols.
FDA 510(k) pathways govern device clearance timelines in the United States, while the EU MDR demands renewed clinical evidence for legacy thoracic drainage products seeking CE marking renewal. The EU F-Gas Regulation indirectly shapes suction pump replacement cycles in European hospitals. Stakeholders must monitor reimbursement coding shifts for outpatient thoracentesis procedures and align portfolio investments with the regulatory divergence between US and European conformity assessment requirements.
Market Dynamics
The EU MDR recertification deadline is compressing product development timelines for legacy thoracic drainage manufacturers while simultaneously accelerating consolidation among smaller device suppliers unable to absorb clinical evidence costs.
Growth Catalysts
- Aging Demographics in Developed Economies:Hospital admission rates for pleural effusion management are climbing in Japan, Germany, and the United States as population median age advances. Procedural volumes in acute care settings sustain catheter consumption.
- EU MDR Recertification Requirements:Renewed clinical evidence mandates for CE marking renewal are forcing portfolio rationalization among established manufacturers. This regulatory pressure is eliminating marginal competitors and concentrating market share among compliant suppliers.
- Video-Assisted Thoracoscopic Surgery Integration:Operating room visualization platforms are incorporating specialized drainage catheters into standardized surgical workflows. This technology convergence is expanding addressable procedure volumes beyond traditional thoracic surgery.
Market Restraints
- Silicone Polymer Price Volatility:Catheter raw material costs fluctuate with petrochemical feedstock markets. Manufacturers face margin compression when procurement contracts cannot pass through input cost swings.
- Supply Concentration in Southeast Asian Molding:Precision catheter manufacturing clusters in Thailand and Malaysia create geographic risk exposure. Single-source dependencies for high-tolerance extrusion limit supply chain resilience.
- Reimbursement Coding Rigidity:CMS procedural codes for outpatient thoracentesis create billing complexity that restricts ambulatory expansion. Payer classification delays compress provider margins on same-day procedures.
Strategic Opportunities
- Home Care Channel Development:Early discharge protocols are creating demand for portable suction systems outside hospital walls. Reimbursement frameworks in the United States are gradually adapting to cover home-based drainage management.
- Bioresorbable Material Convergence:Polymer science advances are enabling temporary pleural implants that eliminate secondary removal procedures. This technology intersection addresses infection risk and patient compliance simultaneously.
- Indian Market Underpenetration:Private hospital networks in Mumbai and Delhi are expanding thoracic surgery capacity faster than drainage device distribution can match. Local manufacturing partnerships could capture procedural volume growth.
Industry Challenges
- Specialized Thoracic Nursing Shortages:Proper chest tube management requires trained clinical staff that acute care facilities struggle to retain. Workforce gaps limit expansion of high-volume pleural effusion centers.
- Legacy Electronic Health Record Integration:New drainage monitoring devices face interoperability barriers with entrenched hospital IT systems. Connectivity standardization lags behind hardware innovation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pleural Cavity Drainage Market |
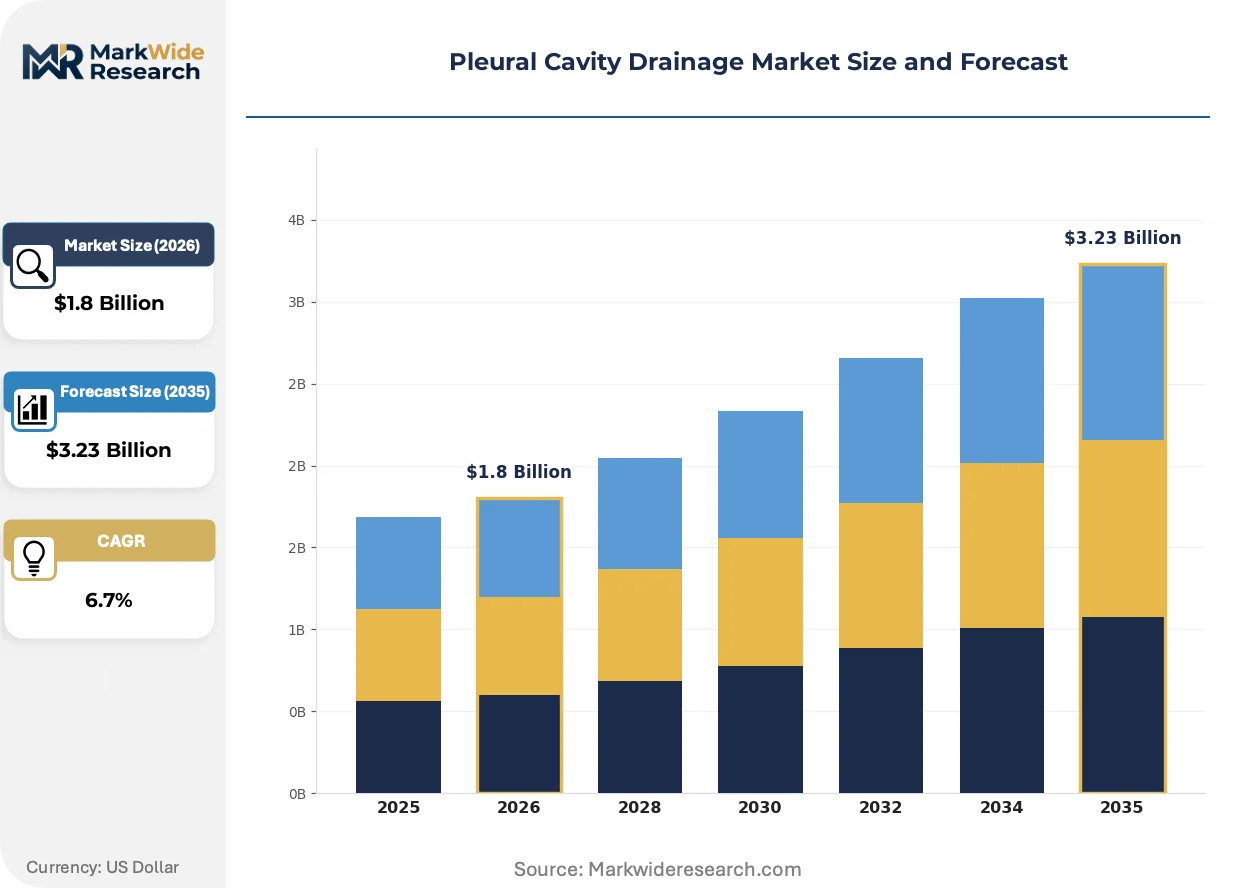
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chest Tubes, Catheters, Drainage Bags, Valves End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Technology: Open Surgery, Video-Assisted Thoracoscopic Surgery, Ultrasonography, Fluoroscopy Delivery Mode: Invasive, Non-Invasive, Continuous, Intermittent |
| Companies Covered | Smiths Medical, Inc., Merit Medical Systems, Inc., Medtronic plc, AngioDynamics, Inc., Cook Medical LLC, Teleflex Incorporated, Cardinal Health, Inc., B. Braun Melsungen AG, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pleural Cavity Drainage Market Evolving Landscape
Digital suction monitoring and disposable pump miniaturization are converging to enable pleural drainage outside traditional hospital infrastructure. These shifts are redrawing competitive boundaries between device categories.
Small-bore catheter systems (8-14 Fr) are overtaking traditional large-bore chest tubes for uncomplicated pneumothorax and malignant effusion management. Interventional pulmonologists in academic medical centers are adopting these devices for bedside insertion, reducing operative theater dependence. This technology transition is compressing average length of stay and enabling same-day discharge protocols that reshape revenue per procedure.
The EU F-Gas Regulation is accelerating replacement cycles for hospital suction pumps containing fluorinated greenhouse gases. European healthcare procurement departments must retire legacy vacuum systems ahead of mandated phase-out dates. This regulatory pressure is concentrating demand for compliant pump replacements in Germany, France, and the Netherlands during the 2024-2027 window.
Hospital purchasing departments are consolidating thoracic drainage procurement into broader interventional cardiology or surgical device contracts. Standalone catheter suppliers face margin pressure as bundled agreements favor full-portfolio vendors. This behavioral shift is most pronounced in United States integrated delivery networks where supply chain rationalization targets administrative cost reduction.
Pleural Cavity Drainage Market Segmentation
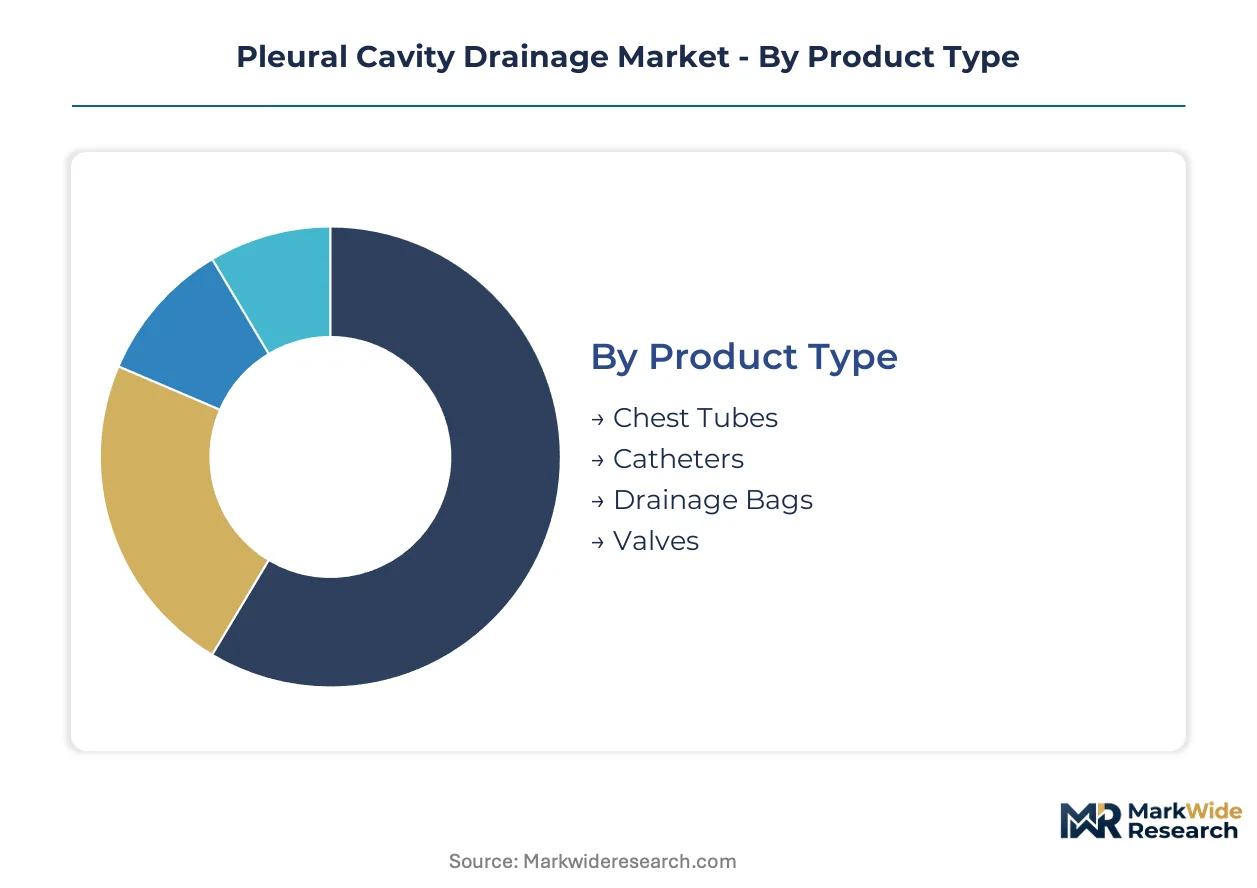
Pleural cavity drainage markets fragment across four critical axes: device specification, care setting, procedural technology, and therapeutic delivery approach. Each segmentation layer reveals distinct procurement patterns, reimbursement pathways, and competitive dynamics that shape manufacturer positioning.
Product Type:
Device specification determines material composition, French sizing range, and suction compatibility profiles that define clinical utility.
- Chest Tubes:Rigid polyvinyl chloride or silicone constructs spanning 20-40 Fr diameter with side-port configurations for high-volume air and fluid evacuation. Demand concentrates in United States trauma centers and German thoracic surgery departments where massive hemothorax protocols require large-bore evacuation capacity.
- Catheters:Flexible polyurethane or silicone systems ranging 6-14 Fr with integrated one-way valves or external suction ports. Smaller-bore designs are displacing traditional chest tubes in Japanese interventional pulmonology suites and United States oncology wards managing malignant effusions.
- Drainage Bags:Collapsible polymer reservoirs with graduated volume markings and anti-reflux mechanisms for closed-system collection.
- Valves:Mechanical one-way devices including Heimlich flutter valves and digital suction regulators that enable ambulatory management.
Mature deployment sits with chest tubes in acute surgical settings. Newer deployment is concentrated in catheters for minimally invasive and outpatient protocols.
End User:
Care setting economics and reimbursement frameworks create divergent procurement behaviors across the patient journey.
- Hospitals:Integrated delivery networks in the United States and university hospitals in Germany maintain centralized thoracic surgery units with standardized catheter inventories. These facilities drive volume through emergency department admissions and scheduled thoracotomy procedures.
- Ambulatory Surgical Centers:Same-day procedure facilities in Florida, Texas, and California are expanding thoracentesis capacity as CMS reimbursement shifts favor outpatient settings. Capital-light models prioritize disposable catheter systems over reusable suction infrastructure.
- Clinics:Pulmonology and interventional radiology practices performing image-guided drainage without overnight admission.
- Home Care:Post-acute settings where portable suction devices and patient-managed drainage systems enable early hospital discharge.
Procurement scale favors hospital systems with consolidated contracting. Margin expansion is climbing fastest in ambulatory surgical centers.
Technology:
Procedural approach dictates device integration requirements, visualization compatibility, and operator training thresholds.
- Video-Assisted Thoracoscopic Surgery:Minimally invasive thoracic procedures performed through small incisions with camera guidance requiring specialized trocar-compatible drainage catheters. Adoption is accelerating in United States academic medical centers and Japanese specialty hospitals where reduced length of stay justifies premium device costs.
- Open Surgery:Conventional thoracotomy with direct visualization and manual tube placement remains standard for complex trauma and lung resection.
- Ultrasonography:Bedside image guidance for percutaneous catheter insertion without fluoroscopy suite requirements.
- Fluoroscopy:Real-time X-ray guidance for challenging anatomical access or loculated effusion management.
Technology migration is pushing video-assisted methods into community hospital settings. Ultrasonography is gaining share fastest for bedside procedures.
Delivery Mode:
Therapeutic intensity and patient mobility requirements shape device configuration and monitoring infrastructure.
- Invasive:Percutaneous catheter or tube placement through chest wall penetration with sealed connection to closed drainage systems. United States emergency departments and German trauma networks rely on invasive delivery for acute pneumothorax and hemothorax.
- Non-Invasive:External suction application or needle aspiration without indwelling catheter placement for diagnostic or temporary relief.
- Continuous:Uninterrupted negative pressure application through wall suction or portable pumps for persistent air leaks.
- Intermittent:Scheduled drainage cycles or patient-activated suction for stable effusions with predictable accumulation rates.
Continuous invasive systems dominate postoperative thoracic surgery. Intermittent protocols are expanding most quickly in home care transition programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of pleural cavity drainage devices clusters in Germany, Japan, and the United States, while procedural consumption concentrates in aging populations across these same economies. Southeast Asian molding facilities supply precision catheter components to assembly plants in developed markets. Regulatory divergence between FDA clearance pathways and EU MDR recertification timelines is fragmenting product launch synchronization.
United States
Hospital admission rates for pleural effusion management climb as the population median age advances past 38 years. FDA 510(k) pathways govern thoracic drainage device clearances with average review timelines compressing for predicate-backed submissions. Integrated delivery networks in Texas and Florida consolidate procurement contracts across ambulatory surgical centers and acute care facilities.
Germany
University hospitals in Munich and Berlin maintain centralized thoracic surgery units with standardized catheter inventories driving procedural volume. EU MDR recertification demands renewed clinical evidence for legacy drainage products seeking CE marking renewal. The EU F-Gas Regulation accelerates hospital suction pump replacement cycles ahead of mandated phase-out dates.
Japan
Interventional pulmonology suites in Tokyo and Osaka adopt small-bore catheter systems for bedside insertion, reducing operative theater dependence. METI oversees medical device market access through PMDA consultation procedures that prioritize minimally invasive technologies. Specialty hospitals in the Kansai region pioneer video-assisted thoracoscopic surgery integration with operating room visualization platforms.
India
Private hospital networks in Mumbai and Delhi expand thoracic surgery capacity faster than drainage device distribution infrastructure can match. CDSCO regulates medical device imports and local manufacturing under strengthened quality control orders. Local manufacturing partnerships in Maharashtra and Gujarat could capture procedural volume growth as domestic production incentives expand.
United Kingdom
NHS procurement frameworks for interventional devices favor suppliers with comprehensive thoracic portfolios over standalone catheter vendors. The MHRA operates post-Brexit device registration requirements that diverge from EU MDR timelines. Academic medical centers in London and Manchester drive adoption of digital suction monitoring for postoperative recovery protocols.
Pleural Cavity Drainage Market Competitive Landscape
Top-tier vendors anchor comprehensive thoracic portfolios, while mid-scale specialists concentrate on catheter sub-categories or regional distribution networks. The vendor base stratifies across three tiers: full-portfolio multinationals with integrated suction and catheter offerings, focused interventional device manufacturers with concentrated R&D in minimally invasive delivery, and regional distributors with limited manufacturing assets. Strategic archetypes include scale-driven procurement consolidators, technology specialists in visualization-compatible drainage systems, and cost-optimized contract manufacturers. Dominant competitive moves involve portfolio diversification into adjacent interventional categories and geographic expansion through distributor acquisition in underpenetrated Asian markets.
Among full-portfolio multinationals, Teleflex Incorporated and Cook Medical LLC occupy positions representing integrated thoracic device suppliers with specialized catheter design capabilities. Merit Medical Systems exemplifies the interventional specialist archetype with manufacturing scale concentrated across minimally invasive product lines. These three entities anchor the competitive structure by representing distinct strategic postures: comprehensive portfolio breadth, concentrated R&D investment, and manufacturing scale specialization respectively.
| Leading Market Players |
|---|
| Smiths Medical, Inc. |
| Merit Medical Systems, Inc. |
| Medtronic plc |
| AngioDynamics, Inc. |
| Cook Medical LLC |
| Teleflex Incorporated |
| Cardinal Health, Inc. |
| B. Braun Melsungen AG |
| Becton, Dickinson and Company |
| Others |
Value Network & Pricing Analysis
Precision extrusion technicians in Thailand and Malaysia command wage premiums that widen pricing-tier spreads between economy-grade catheters and premium silicone systems. Labor-cost differentials across Southeast Asian molding clusters directly determine margin structures for manufacturers serving United States integrated delivery networks versus European university hospitals.
Pricing Analysis
Cost-down pressure on standard-grade catheters accelerates because hospital purchasing departments consolidate procurement into bundled interventional device contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared silicone systems from CE-marked polyurethane alternatives and non-certified economy imports. Price differentiation hinges on certification grade and volume scale, with ambulatory surgical centers exhibiting highest price sensitivity while German thoracic surgery departments absorb premium positioning for video-assisted thoracoscopic surgery-compatible designs.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume demand from United States integrated delivery networks, while distributor-mediated routes serve fragmented European clinics. Precision catheter manufacturing draws from Thailand, Malaysia, and China for high-tolerance extrusion, with silicone polymer feedstocks sourced from German and Japanese petrochemical suppliers. Single-source dependencies for 8-14 Fr small-bore systems create vulnerability to regional logistics disruptions. Distribution runs through specialized medical device distributors with cold-chain capabilities for sterile packaging integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pleural cavity drainage market functions as a cost-of-compliance story where EU MDR recertification requirements erect barrier-to-entry moats favoring established manufacturers with clinical evidence generation capabilities.
For Market Incumbents: Anticipate portfolio rationalization pressure as EU MDR deadlines eliminate marginal competitors unable to absorb renewed clinical evidence costs. Defensive positioning demands backward integration into silicone polymer sourcing to offset petrochemical feedstock volatility, alongside concentrated R&D investment in bioresorbable temporary implants that eliminate secondary removal procedures and address infection risk simultaneously. For New Entrants and Emerging Players: Begin with home care channel development where portable suction systems face less entrenched procurement relationships and reimbursement frameworks are gradually adapting to cover early discharge protocols. The most penetrable white-space sits with Indian private hospital networks in Mumbai and Delhi expanding thoracic surgery capacity faster than drainage device distribution infrastructure can match, approached through local manufacturing partnerships leveraging domestic production incentives. For Investors and Strategic Acquirers: The window for entry favors mid-scale interventional specialists with concentrated catheter R&D and established CE marking pathways. Long-term viability centers on acquisition targets possessing minimally invasive delivery system expertise and existing hospital system partnerships. Monitor EU MDR recertification completion rates among smaller device suppliers as early signals of consolidation acceleration and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | CE marking renewal with renewed clinical evidence secures market access across German and French hospital procurement frameworks. |
| Home Care Channel Partnership | Portable suction system distribution agreements with United States home health agencies capture early discharge protocol expansion. |
| Bioresorbable Material Development | Temporary pleural implant R&D addresses infection risk and patient compliance while eliminating secondary removal procedures. |
| Indian Local Manufacturing Joint Venture | Maharashtra and Gujarat production partnerships capture procedural volume growth in Mumbai and Delhi private hospital networks. |
| Digital Suction Monitoring Integration | Software companion development for drainage devices overcomes legacy electronic health record interoperability barriers in academic medical centers. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS reimbursement coding records, complemented by interviews with thoracic surgeons, interventional pulmonologists, biomedical engineers, and GPO contracts managers. Secondary validation drew from PMDA consultation procedures, CDSCO quality control orders, and METI medical device market access guidelines. Bottom-up catheter consumption modeling triangulated against top-down hospital admission projections for pleural effusion management.
Cross-referencing historical procedural volume trends against panel input from hospital purchasing committees enabled analytical framework construction across the projection horizon. Segmentation dimensions modeled include product specification, care setting, procedural technology, and therapeutic delivery approach alongside regional regulatory cluster differentiation. CAGRs were derived from installed base replacement cycles, ambulatory surgical center expansion trajectories, and aging demographic admission rate projections without year-specific anchoring.
Underlying measurement precision varies by segment; hospital and ambulatory surgical center demand carries tighter precision than emerging home care channel estimates. Forecasts reflect assumptions regarding EU MDR recertification timeline adherence, silicone polymer price stability, and reimbursement coding adaptation for outpatient thoracentesis. Practitioners should monitor FDA clearance pathway adjustments, EU F-Gas Regulation pump replacement cycle completion, and Indian domestic production incentive expansion for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
Catheter Systems Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
Subcutaneous Injection Ports Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Veterinary Arthroscopy Device Market
Medical Devices
Snare Devices Market
Medical Devices
Chile Artificial Organs and Bionic Implants Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Struts Implants Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
Ablation Devices Market