
 US Stethoscope Market | 2026-2036
US Stethoscope Market Size, Share, and Industry Trends Forecast 2026-2036
US Stethoscope Market Intelligence
Capital-intensity divergence between acoustic heritage manufacturers and digital sensor developers is rotating competitive priorities across the US stethoscope landscape. 3M leverages its Littmann brand equity and established hospital supply contracts to sustain dominant shelf presence in acute care settings. Eko Health differentiates through FDA-cleared AI algorithms and Bluetooth connectivity, positioning its devices at the intersection of traditional auscultation and remote patient monitoring workflows.
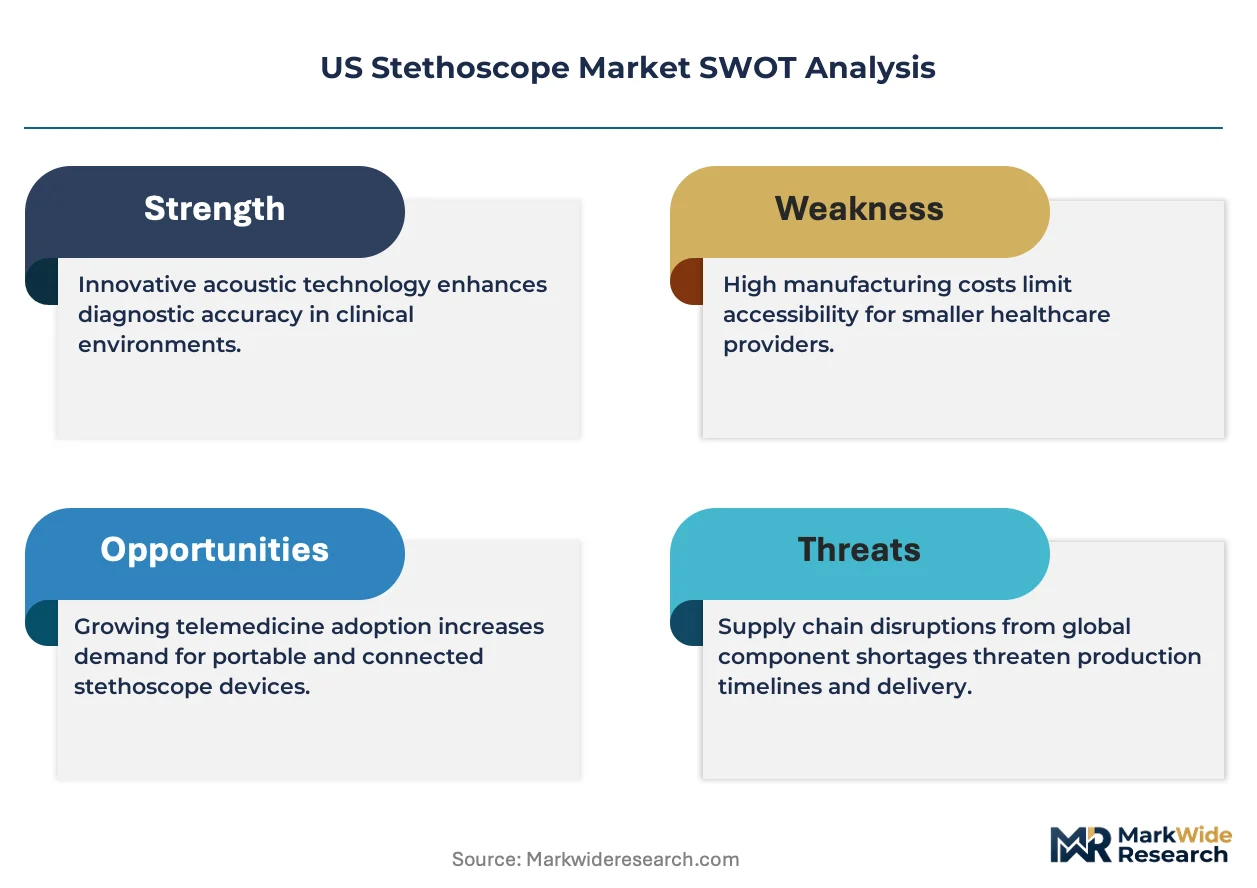
A stethoscope is an acoustic or electronic medical instrument designed to transmit internal body sounds—heart murmurs, lung crackles, vascular bruits—to a clinician's ear via a chest piece, tubing, and binaural headset, with digital variants incorporating piezoelectric sensors and signal amplification for frequency isolation. Electronic and Bluetooth product types are capturing expanding margin pools as health systems prioritize telemedicine compatibility and EHR-integrated sound capture, while acoustic models retain volume leadership in cost-sensitive clinic and home care channels. Cardiac monitoring applications command premium positioning due to subspecialist demand for murmur detection fidelity, whereas general examination segments face commoditization pressure from private-label distributors.
FDA device classification rules and HIPAA data security standards shape digital stethoscope software validation requirements and cloud transmission protocols, creating compliance thresholds that favor established players with regulatory affairs infrastructure. State-level Medicaid reimbursement policies in California and New York increasingly recognize remote auscultation as a billable telehealth service, expanding addressable demand for connected devices. Stakeholders must monitor whether FDA's evolving software-as-a-medical-device framework will accelerate clearance timelines for AI-augmented diagnostic features or extend validation burdens for emerging sensor platforms.
Market Dynamics
Health system consolidation across Texas, California, and New York is compressing purchasing timelines and forcing standardized fleet decisions that privilege connectivity over legacy acoustic performance.
Growth Catalysts
- Telehealth reimbursement expansion:State-level Medicaid policies in California and New York now classify remote auscultation as a billable service, expanding addressable demand for Bluetooth-enabled devices in outpatient networks.
- FDA software-as-a-medical-device pathways:Evolving clearance frameworks for AI-integrated diagnostic features are accelerating product development timelines for digital stethoscope platforms.
- Acute care sensor demand:Emergency departments in consolidated health systems are prioritizing piezoelectric amplification for murmur detection fidelity during high-throughput triage.
Market Restraints
- Piezoelectric component concentration:Specialized sensor supply chains concentrate in East Asian manufacturing clusters, exposing US assemblers to input volatility and logistics friction.
- HIPAA cloud transmission burdens:Data security standards impose validation requirements on digital stethoscope software that extend time-to-market for emerging sensor platforms.
- Acoustic commoditization pressure:Private-label distributors in cost-sensitive home care channels are compressing margins on non-amplified heritage designs.
Strategic Opportunities
- Rural health clinic penetration:Federally Qualified Health Centers in underserved Appalachian and Southwestern counties present untapped demand for EHR-integrated sound capture devices.
- AI-augmented cardiac screening:Machine learning algorithms for automated murmur classification are converging with Bluetooth telemetry to enable point-of-care diagnostics without specialist referral.
- Direct-to-clinician subscription models:Hardware-as-a-service pricing is bypassing traditional group purchasing organizations to capture individual practitioner segments.
Industry Challenges
- FDA validation timeline compression:Software iterations for diagnostic algorithms require repeated 510(k) submissions that strain regulatory affairs capacity at emerging sensor developers.
- Legacy EHR integration complexity:Health systems running decade-old record architectures face middleware costs and IT staffing gaps when connecting digital stethoscopes to existing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Stethoscope Market |
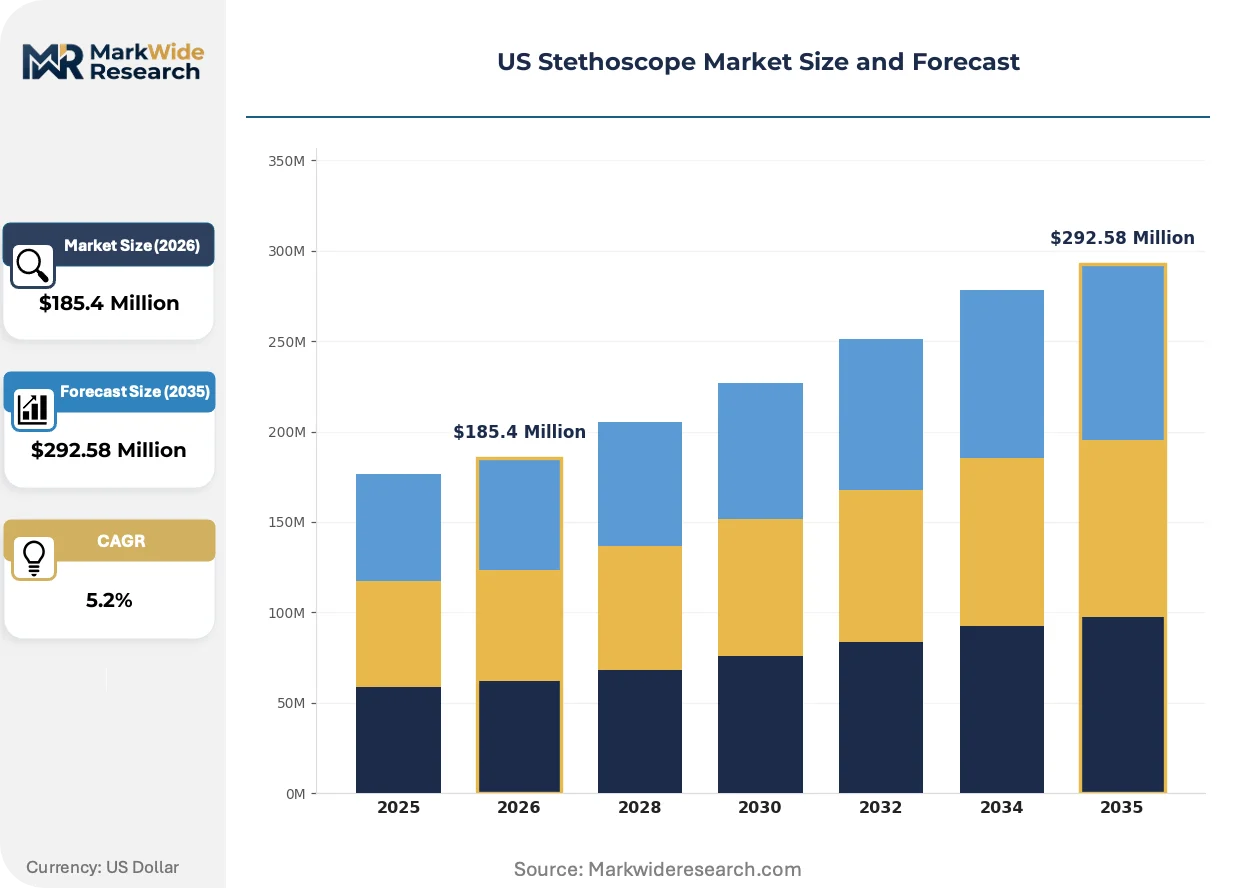
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $292.58 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic, Electronic, Digital, Bluetooth End User: Hospitals, Clinics, Private Practices, Home Care Delivery Mode: Online Retail, Supermarkets, Medical Supply Stores, Distributors Application: Cardiac Monitoring, Respiratory Assessment, General Examination, Pediatric Care |
| Companies Covered | 3M, Medline Industries, Welch Allyn, Eko Health, GF Health Products, American Diagnostic Corporation, Solventum, Thinklabs, HD Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Stethoscope Market Strategic Shifts & Innovations
Digital sensor architectures are fragmenting the stethoscope value chain, separating acoustic heritage manufacturing from software-defined diagnostic platforms and rewiring competitive advantage toward data interoperability.
Piezoelectric chest piece technology is bifurcating the product landscape into amplified frequency-isolation devices and legacy passive designs. Subspecialist cardiologists and academic medical centers are adopting sensor-based platforms at accelerated replacement cycles. This technological divide is compressing R&D investment into acoustic tubing and redirecting capital toward signal processing and cloud infrastructure.
FDA's evolving software-as-a-medical-device framework is reshaping validation requirements for AI-augmented diagnostic features. Manufacturers must now document algorithm performance across diverse patient populations before clearance. Digital stethoscope developers with established quality management systems are responding by front-loading clinical evidence generation, while newer entrants face extended timelines.
Health system procurement offices are consolidating vendor relationships around enterprise-wide connectivity standards. Independent physicians and small group practices are losing negotiating leverage as purchasing decisions migrate to supply chain executives. This concentration is most visible in Texas and California, where multi-hospital networks are mandating Bluetooth-enabled fleet uniformity across emergency and outpatient settings.
US Stethoscope Market Segmentation
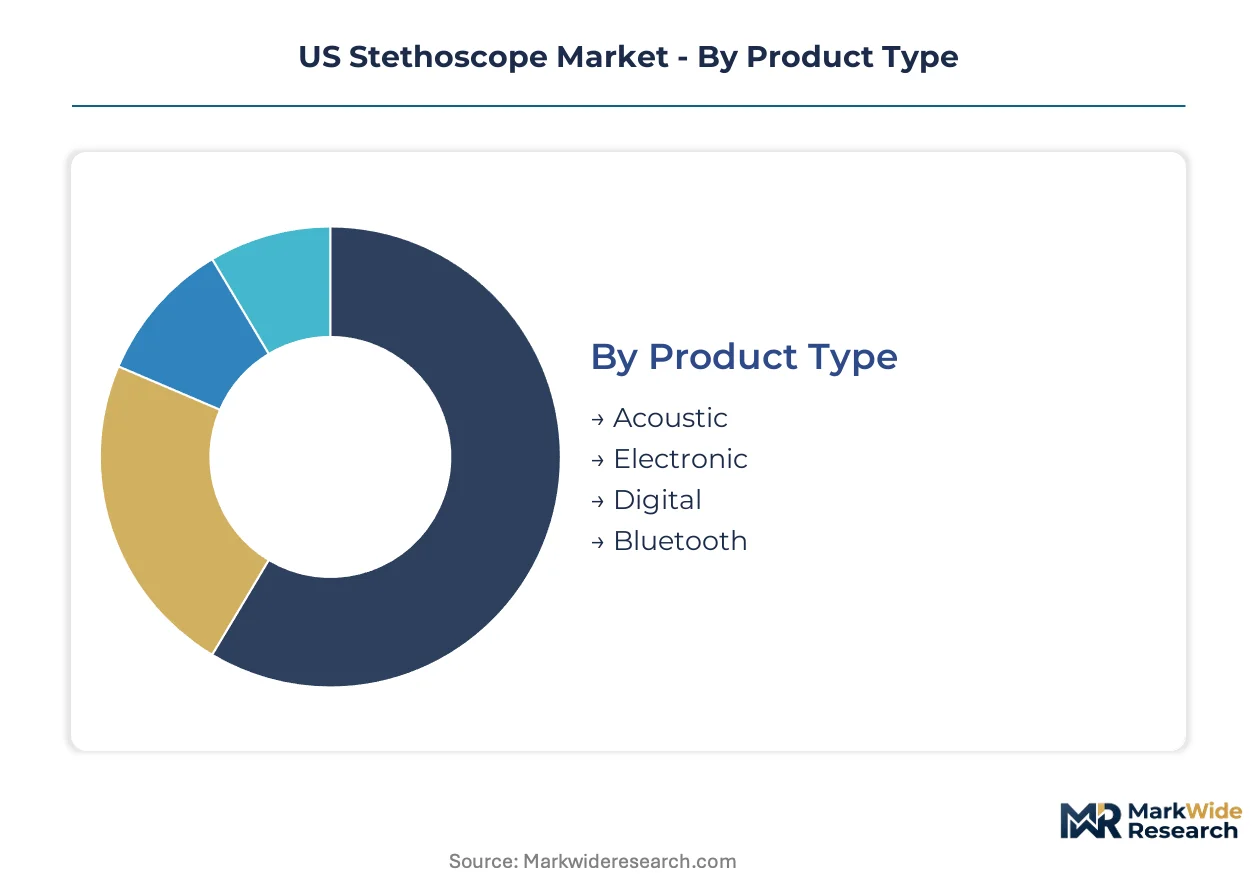
Segmentation in the US stethoscope market reveals how technology migration and purchasing authority concentration are reshaping channel economics. Understanding which configurations flow through health system procurement versus retail-direct channels illuminates margin capture and competitive positioning strategies.
Product Type:
Acoustic models dominate medical supply store and distributor channels, while electronic and Bluetooth variants concentrate through hospital group purchasing organizations seeking fleet standardization.
- Acoustic:Passive sound transmission through binaural tubing and dual-sided chest pieces remains the baseline specification for cost-sensitive clinic and educational settings. Demand concentrates in Texas community health centers and private practices where replacement cycles extend beyond seven years, constrained by Medicaid reimbursement compression on durable medical equipment.
- Electronic:Piezoelectric sensor arrays with frequency amplification and noise cancellation are capturing hospital emergency department procurement in California and New York consolidated systems. These devices command premium positioning through FDA-cleared amplification algorithms that isolate S3 gallops and mitral regurgitation murmurs during high-throughput triage.
- Digital:Waveform capture and onboard storage enable EHR-integrated documentation workflows for academic medical centers running Epic or Cerner architectures.
- Bluetooth:Wireless telemetry to tablets and smartphones supports telehealth reimbursement pathways in California and New York Medicaid networks, with software-as-a-medical-device validation requirements extending clearance timelines.
By volume, Acoustic leads. By growth pace, Bluetooth-enabled configurations are expanding most quickly.
End User:
Customer type determines pricing tolerance and connectivity requirements, with institutional buyers prioritizing interoperability and individual practitioners emphasizing acquisition cost.
- Hospitals:Multi-hospital networks in Texas and California mandate Bluetooth fleet uniformity across emergency and outpatient settings, compressing vendor selection to three approved suppliers with established HIPAA-compliant cloud infrastructure.
- Clinics:Federally Qualified Health Centers in Appalachian counties present untapped demand for EHR-integrated sound capture, though IT staffing gaps delay deployment timelines.
- Private Practices:Solo practitioners and small group practices in cost-sensitive markets retain acoustic heritage designs, losing negotiating leverage as purchasing decisions migrate to supply chain executives.
- Home Care:Post-acute and hospice settings drive private-label distributor volume for non-amplified examination-grade devices, with Medicare durable medical equipment fee schedules constraining price points.
By procurement value, Hospitals dominate. By volume expansion, Clinics serving underserved counties show the steepest demand trajectory.
Delivery Mode:
Channel structure reflects the bifurcation between institutional procurement complexity and consumer-direct simplicity, with regulatory validation requirements filtering product availability.
- Online Retail:Amazon and specialized medical equipment platforms serve individual practitioners and home care buyers with acoustic and entry-level electronic models, bypassing group purchasing organization markups.
- Supermarkets:Limited SKU availability concentrates on basic dual-head acoustic designs for consumer wellness and educational segments, with minimal professional clinical penetration.
- Medical Supply Stores:Regional distributors in Texas and California maintain acoustic inventory for same-day replacement needs, though digital and Bluetooth variants require manufacturer-direct fulfillment.
- Distributors:McKesson, Cardinal Health, and regional medical-surgical distributors handle hospital and health system contracts, with Bluetooth-enabled fleet orders requiring pre-negotiated connectivity standards and EHR compatibility verification.
By transaction frequency, Medical Supply Stores lead. By revenue concentration, Distributor channel contracts with consolidated health systems capture the largest share.
Application:
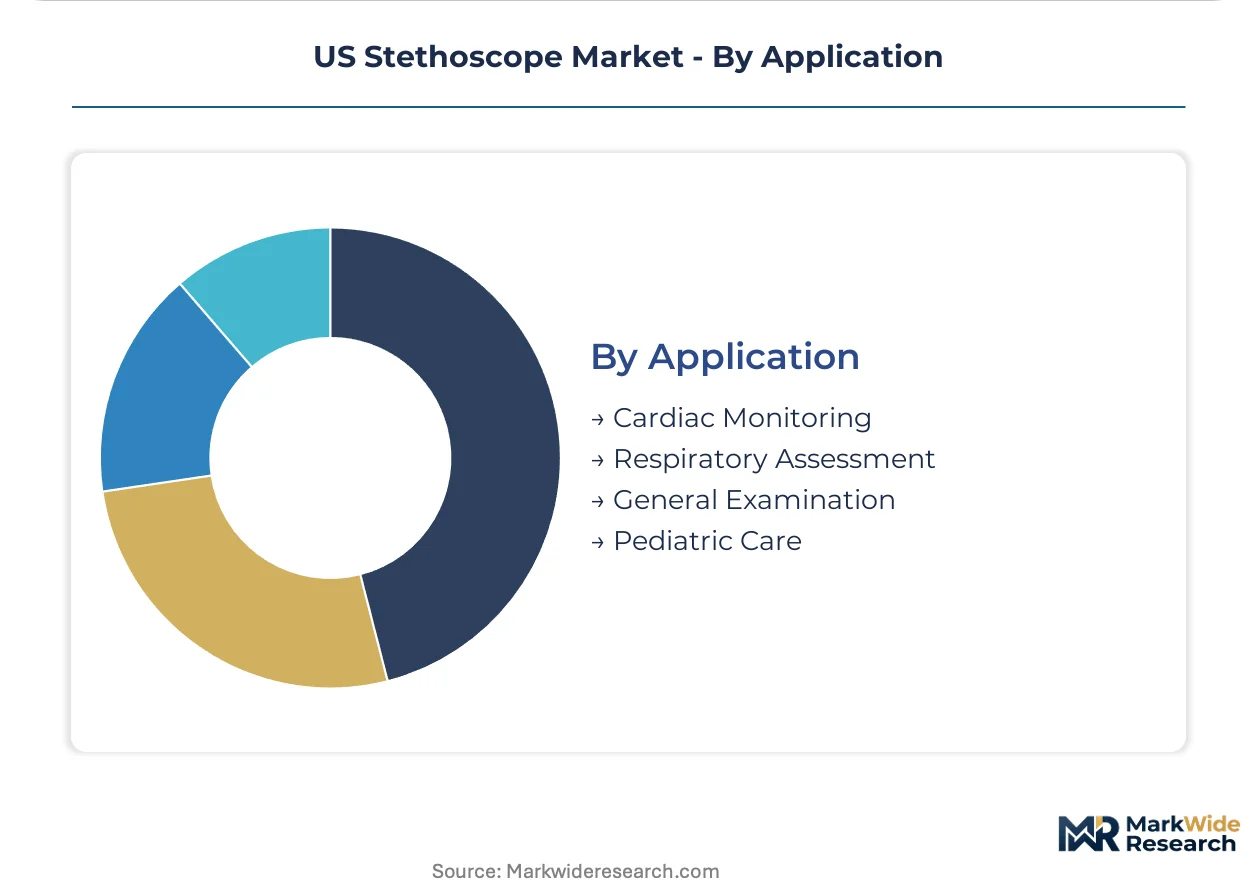
Clinical use case determines sensor specification and software feature requirements, with cardiac applications commanding development investment and general examination facing commoditization.
- Cardiac Monitoring:Subspecialist demand for murmur detection fidelity drives piezoelectric amplification adoption, with AI-augmented algorithms for automated classification converging with Bluetooth telemetry to enable point-of-care diagnostics without specialist referral.
- Respiratory Assessment:Crackle and wheeze isolation requires frequency filtering optimized for 100-2000 Hz ranges, with emergency departments in New York academic centers prioritizing rapid auscultation documentation for sepsis protocols.
- General Examination:Routine physical assessment applications face margin compression from private-label acoustic distributors, with minimal differentiation beyond chest piece material and tubing durability.
- Pediatric Care:Smaller diaphragm specifications and noise-reduction features address neonatal and infant auscultation, with specialized procurement through children's hospital networks in California and Texas.
By premium pricing power, Cardiac Monitoring leads. By volume accessibility, General Examination spans the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across US sub-regions, with consolidated health systems in coastal states absorbing premium pricing for connected devices while rural clinics in interior states extend replacement cycles on acoustic models.
Texas
Multi-hospital networks in the Dallas-Fort Worth and Houston medical corridors mandate Bluetooth fleet uniformity across emergency departments, compressing vendor selection to suppliers with established HIPAA-compliant cloud infrastructure. State Medicaid reimbursement policies for durable medical equipment constrain price points at Federally Qualified Health Centers in the Rio Grande Valley. San Antonio anchors pediatric stethoscope procurement through children's hospital specialty networks.
California
Academic medical centers in Los Angeles and the San Francisco Bay Area prioritize piezoelectric amplification for murmur detection fidelity during high-throughput triage. State-level Medicaid policies now classify remote auscultation as a billable telehealth service, expanding addressable demand for Bluetooth-enabled devices in outpatient networks. San Diego hosts concentrated procurement for EHR-integrated sound capture platforms running Epic architectures.
New York
Consolidated health systems in the New York City metro area are standardizing fleet replacements across emergency departments and outpatient networks, privileging connectivity over legacy acoustic performance. FDA software-as-a-medical-device validation requirements extend clearance timelines for emerging sensor developers seeking entry. Rochester anchors manufacturing supply relationships for piezoelectric component assembly.
Appalachian Region
Federally Qualified Health Centers in underserved Kentucky and West Virginia counties present untapped demand for EHR-integrated sound capture devices, though IT staffing gaps delay deployment timelines. Medicare durable medical equipment fee schedules constrain price points in post-acute and hospice settings. Pittsburgh anchors regional distribution networks for acoustic heritage replacement inventory.
Southwest
Arizona and New Mexico community health centers retain acoustic designs due to Medicaid reimbursement compression, extending replacement cycles beyond seven years. Telehealth reimbursement gaps limit Bluetooth device penetration compared to coastal states. Phoenix anchors medical supply distributor consolidation serving cost-sensitive clinic channels.
US Stethoscope Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with brand equity and regulatory infrastructure determining shelf presence in consolidated health systems. The upper tier commands hospital group purchasing organization contracts through established quality management systems and FDA clearance pathways. Three archetypes dominate: heritage acoustic manufacturers defending position through distributor relationships, digital sensor developers capturing telehealth reimbursement expansion, and private-label distributors compressing margins in cost-sensitive channels. Competitive moves concentrate on M&A for regulatory affairs capacity and strategic partnerships for EHR interoperability.
Within the heritage acoustic tier, 3M and Welch Allyn occupy positions anchored by decades of clinician brand recognition and established hospital supply contracts. Eko Health exemplifies the digital sensor developer archetype, representing the convergence of FDA-cleared AI algorithms with Bluetooth telemetry workflows. Among diversified medical device conglomerates, Medline Industries and Solventum sit within broader portfolios where stethoscope manufacturing represents one vertical among many clinical supply categories.
| Leading Market Players |
|---|
| 3M |
| Medline Industries |
| Welch Allyn |
| Eko Health |
| GF Health Products |
| American Diagnostic Corporation |
| Solventum |
| Thinklabs |
| HD Medical |
| Others |
Cost & Logistics Intelligence
Ninety-day sensor inventory cycles at East Asian component foundries concentrate pricing power among piezoelectric suppliers, forcing US assemblers to absorb input volatility or pass through cost escalations to hospital procurement offices already facing Medicaid reimbursement compression.
Pricing Analysis
Software subscription tiers for AI-augmented diagnostic algorithms now drive lifetime value capture beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance status and EHR integration depth. Cost compression in acoustic heritage tiers stems from private-label distributor consolidation in home care channels. Federally Qualified Health Centers exhibit acute price sensitivity, while academic medical centers prioritize connectivity premiums over unit economics.
Supply Chain Analysis
Inventory buffers at Malaysian and Taiwanese sensor foundries remain thin relative to demand spikes from California health system fleet rollouts. Piezoelectric crystals, Bluetooth modules, and medical-grade silicone tubing draw from East Asian manufacturing clusters. Single-source vulnerability concentrates in FDA-validated sensor suppliers with extended qualification timelines. Distribution runs through Cardinal Health and McKesson hospital contracts, with manufacturer-direct fulfillment for Bluetooth-enabled configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward consolidated health system procurement offices, with multi-hospital networks in Texas and California compressing vendor selection to three approved suppliers and stripping negotiating leverage from independent practitioners.
For Market Incumbents: Consolidate regulatory affairs capacity through acquisition of FDA-cleared AI algorithm developers to accelerate software-as-a-medical-device submission timelines. Deepen backward integration into piezoelectric sensor supply by qualifying secondary foundries in South Korea, reducing exposure to Taiwan Strait logistics friction. Defend hospital GPO shelf presence by embedding EHR interoperability teams within Epic and Cerner implementation workflows.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for AI-augmented cardiac screening algorithms open entry corridors without requiring de novo classification. Rural Federally Qualified Health Centers in Appalachian Kentucky and West Virginia present the most penetrable demand pocket, with IT staffing gaps creating appetite for turnkey EHR integration support. Pursue hardware-as-a-service subscription models bypassing traditional GPO markups to capture individual practitioner segments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Bluetooth-enabled digital platforms as software validation timelines extend and cloud infrastructure requirements deepen. Over a five-to-ten-year viability window, acquisition targets should emphasize regulatory affairs infrastructure over pure sensor technology. Watch for FDA software-as-a-medical-device framework revisions as the critical inflection signal for algorithm developer valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI Algorithms | Accelerates clearance timelines for murmur detection software in cardiac monitoring applications. |
| Hospital System Partnership | Locks in fleet uniformity mandates across Texas and California consolidated networks. |
| Software Companion Development | Enables EHR-integrated documentation workflows for Epic and Cerner architectures. |
| Reimbursement Strategy | Captures California and New York Medicaid telehealth billing codes for remote auscultation. |
| CE Marking Pathway | Opens European export channels for Bluetooth telemetry devices with MDR compliance. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and digital health product strategists. Secondary validation drew from FDA 510(k) filings, CMS Medicare durable medical equipment fee schedules, hospital procurement databases, and GPO contract disclosures. Bottom-up installed base estimates and top-down health system expenditure triangulation anchored volume and value assessments.
Across the analysis window, the forecasting framework modeled product type migrations, end-user procurement authority shifts, delivery mode channel economics, and application-specific sensor requirements. CAGRs were derived from replacement cycle compression analysis and telehealth reimbursement elasticity. Input assumptions incorporated piezoelectric sensor cost curves, FDA validation timeline distributions, and Medicaid policy adoption rates in coastal states.
Underlying assumptions cover health system consolidation trajectories, FDA software-as-a-medical-device framework stability, and East Asian supply chain continuity, with deviation risk concentrated in tariff exposure on sensor components and state-level telehealth reimbursement reversals. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
Airway Management Devices Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Global Cosmetic Implants Market
Medical Devices
Slip Disc Market
Medical Devices
Global Thrombectomy Devices Market
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Powered Mattress System Market
Medical Devices
Global Bone Screw System Market
Medical Devices
Osteotomy Plates Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Sensor Based Smart Catheters Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Autosamplers Market
Medical Devices
United States Contraceptive Devices Market