
 Airway Management Devices Market | 2026-2036
Airway Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Airway Management Devices Market Intelligence
ISO 13485 certification is rotating the competitive landscape, setting a high bar for quality management systems in manufacturing. Medtronic leverages its extensive distribution network to command a significant presence across multiple applications. Teleflex Incorporated competes on the strength of its specialized laryngeal mask and endotracheal tube portfolios. Meanwhile, Ambu A/S differentiates through its focus on single-use and video-enabled airway devices.
Airway management devices are medical instruments used to maintain or restore a patient's breathing pathway. These devices, often made from medical-grade PVC or silicone, ensure an open airway during anesthesia, resuscitation, or critical illness. Video laryngoscopes represent the fastest-growing product segment, driven by improved first-pass success rates. While hospitals remain the largest end-user, demand from ambulance services and trauma centers is accelerating due to the push for advanced prehospital care.
Regulatory frameworks, including the US FDA's 510(k) clearance process and Europe's Medical Device Regulation (MDR), govern market access. These regulations mandate stringent testing for biocompatibility and clinical efficacy, influencing design and material choices for manufacturers globally. The key decision point for providers now centers on balancing the upfront cost of reusable devices against the infection control benefits of disposable alternatives.
Market Dynamics
The integration of digital imaging into laryngoscopy is the central force altering clinical practice and device selection. This technological shift, combined with stringent new quality mandates from regulators, is reconfiguring the competitive and operational landscape for all manufacturers.
Growth Catalysts
- Video Laryngoscopy Adoption:The clinical push for higher first-pass intubation success rates, particularly in emergency medicine and intensive care units, is a primary catalyst for the adoption of video-enabled devices.
- Infrastructure Expansion:Sustained government and private investment in hospital construction and healthcare modernization programs in countries like India and Brazil creates baseline demand for fundamental medical equipment.
- Prehospital Care Standards:Evolving protocols for ambulance services and trauma centers increasingly mandate the inclusion of advanced airway tools, expanding the market beyond traditional hospital walls.
Market Restraints
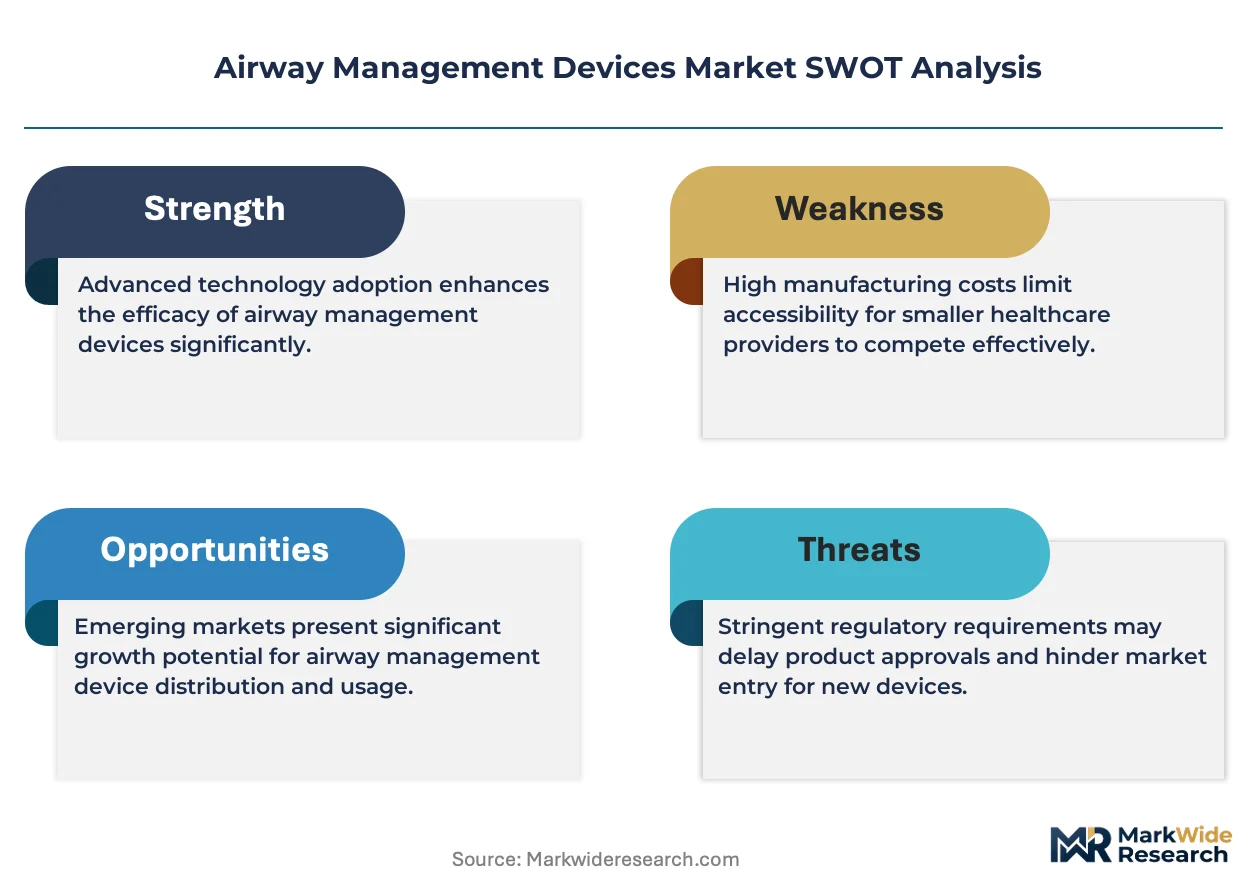
- Cost of Reusable Systems:The significant upfront capital investment required for reusable video laryngoscopes, coupled with ongoing sterilization and maintenance costs, can deter adoption in budget-constrained healthcare facilities.
- Regulatory Scrutiny:Europe's Medical Device Regulation (MDR) imposes extensive clinical data and traceability requirements, increasing compliance costs and extending time-to-market for new and existing devices.
- Material Price Volatility:Fluctuation in the global prices of medical-grade PVC and silicone, key raw materials for many disposable devices, directly impacts manufacturing costs and margin stability.
Strategic Opportunities
- Cost-Effective Single-Use Devices:Developing affordable, disposable video laryngoscopes and endoscopes addresses both infection control concerns and the capital expenditure limitations of reusable systems.
- Specialized Pediatric Devices:A clear opportunity exists for airway management tools specifically designed and validated for the unique anatomical challenges presented by pediatric and neonatal patients.
- Untapped Geographic Markets:Beyond the focus on India and Brazil, expanding healthcare access and infrastructure in many Southeast Asian and African nations presents significant long-term growth potential.
Industry Challenges
- Clinician Training and Skill Gaps:The effective transition to new technologies like video laryngoscopy requires comprehensive training programs to ensure proficient use and optimal patient outcomes across different clinical settings.
- Sterilization Process Management:For facilities using reusable devices, managing the complex logistics and validation of cleaning and sterilization processes to prevent cross-contamination is a major operational hurdle.
- ISO 13485 Compliance:Achieving and maintaining ISO 13485 certification for quality management systems demands significant and continuous investment in process control, documentation, and personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airway Management Devices Market |
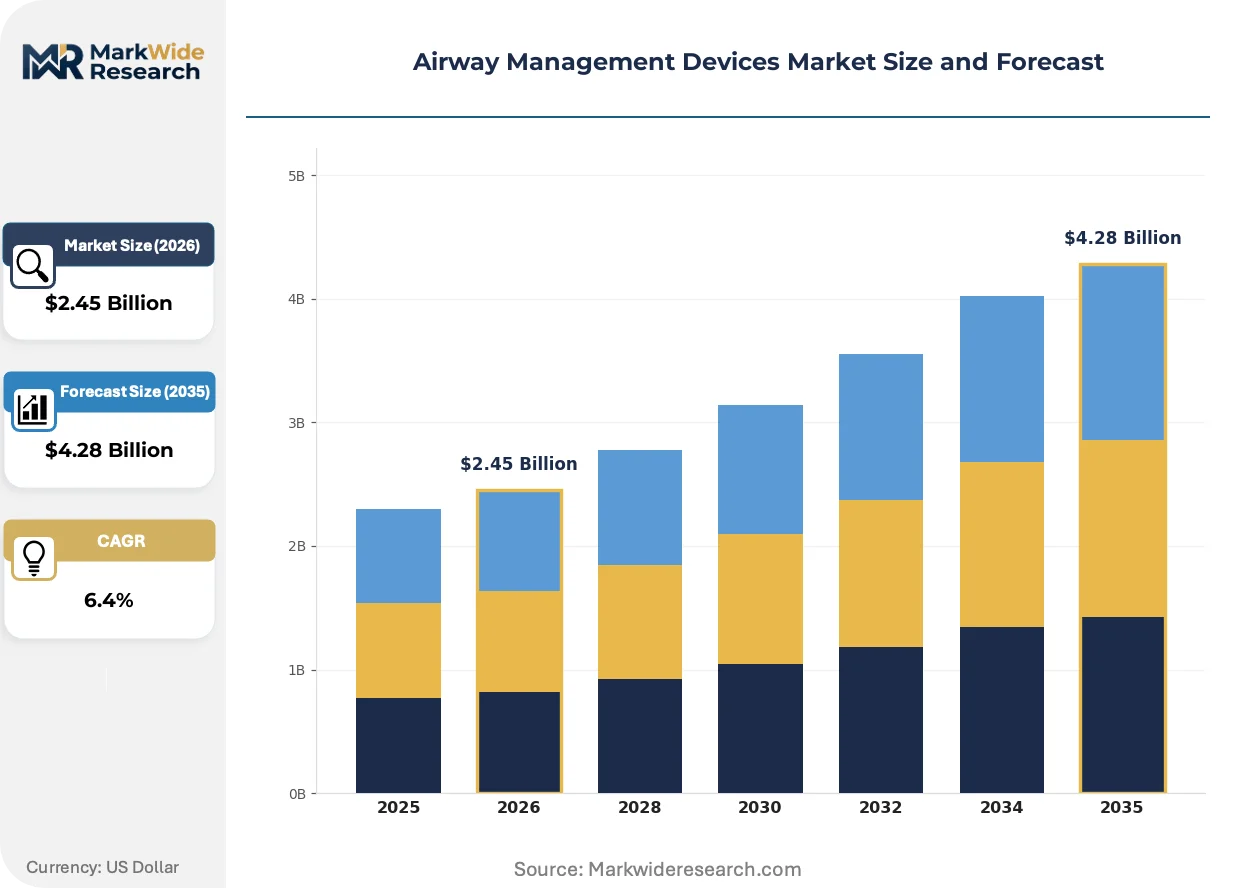
| Market Size in 2026 | $2.45 Billion |
| Market Size in 2035 | $4.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endotracheal Tubes, Laryngeal Masks, Oropharyngeal Airways, Nasopharyngeal Airways, Video Laryngoscopes Application: Emergency Medicine, Anesthesia, Critical Care, Neonatal Care, Prehospital Care End User: Hospitals, Ambulance Services, Surgical Centers, Specialty Clinics, Trauma Centers Deployment Type: Reusable, Disposable, Portable, Stationary |
| Companies Covered | ICU Medical, Intersurgical Ltd, Medtronic, Medline Industries, BD, Teleflex Incorporated, Convatec, KARL STORZ SE & Co. KG, Ambu A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airway Management Devices Market Strategic Shifts & Innovations
Technological advancements are intersecting with evolving clinical priorities, compelling a fundamental reassessment of device selection. This dynamic favors instruments that enhance procedural success and patient safety, particularly in high-stakes emergency and critical care environments.
Video laryngoscopy integrates a camera and a digital screen to provide a clear, real-time view of the airway. Emergency medical services and intensive care units are rapidly adopting this technology. This visual advantage is decomposing the traditional hierarchy of intubation skill, allowing a wider range of clinicians to achieve successful first-pass placement.
Europe's Medical Device Regulation (MDR) mandates more rigorous pre-market and post-market data collection for all devices. This directly increases the burden of proof for clinical efficacy and safety on manufacturers. The single-use device segment is most affected, as biocompatibility and sterility validation for products made of PVC or silicone must now meet a much higher standard.
A notable shift in buying criteria prioritizes infection control over initial unit price. Hospital procurement departments are moving from simple cost-per-device analysis toward a total cost of ownership model, which accounts for sterilization expenses and infection risks. This trend is most pronounced in surgical centers and hospitals across North America and Europe.
Airway Management Devices Market Segmentation
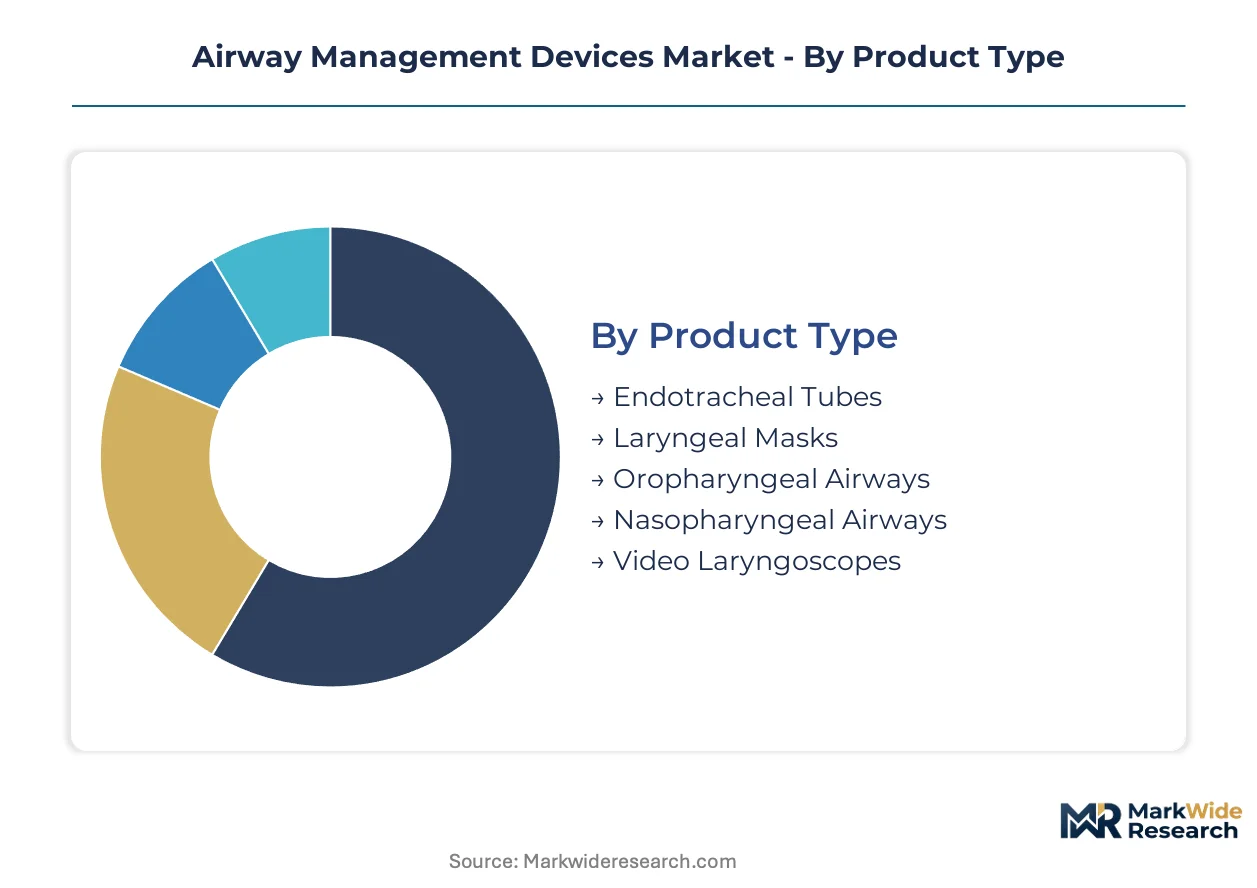
The Airway Management Devices Market segmentation provides a granular view of product innovation, end-user demand, and deployment strategies. Understanding these distinct segments helps manufacturers target specific clinical needs and regulatory compliance pathways across diverse healthcare settings.
Product Type:
Product type differentiation reflects clinical utility and manufacturing complexity, with some devices seeing widespread adoption globally while others are more concentrated in specific markets.
- Video Laryngoscopes:These devices integrate a camera and digital screen to visualize the airway, improving first-pass success rates. Demand is concentrating in emergency departments and intensive care units across North America and Europe due to clinical efficacy and safety protocols.
- Endotracheal Tubes:Flexible tubes inserted into the trachea to maintain an open airway, typically made from PVC or silicone. These are foundational devices with high volume demand in hospitals worldwide, driven by general anesthesia and critical care applications.
- Laryngeal Masks:Supraglottic airway devices designed for ventilation without tracheal intubation.
- Oropharyngeal Airways:Simple devices used to prevent the tongue from obstructing the airway in unconscious patients.
- Nasopharyngeal Airways:Flexible tubes inserted through the nostril into the pharynx to maintain airway patency.
Endotracheal Tubes hold the largest share; momentum sits with Video Laryngoscopes.
Application:
The application segment illustrates where airway management devices are most critically deployed, with usage patterns varying by clinical urgency and procedural requirements.
- Emergency Medicine:This application involves rapid airway securement in critical, time-sensitive situations such as trauma or cardiac arrest. Adoption of advanced tools like video laryngoscopes is accelerating in emergency departments and prehospital settings in countries like Brazil and India.
- Anesthesia:Airway devices are indispensable for maintaining ventilation during surgical procedures requiring general anesthesia. This segment represents a stable and high-volume demand driver in hospitals globally, particularly for elective surgeries.
- Critical Care:Sustained airway support for patients in intensive care units with respiratory failure or compromised airways.
- Neonatal Care:Specialized, smaller devices for managing airways in infants and newborns with delicate anatomies.
- Prehospital Care:Use of airway devices by paramedics and first responders at the scene of an emergency before hospital arrival.
The segment for Anesthesia dominates, while Emergency Medicine is experiencing the steepest expansion trajectory.
End User:
End-user categories highlight the primary purchasing entities for airway management devices, with procurement priorities shifting based on facility type and patient volume.
- Hospitals:These institutions represent the largest end-user segment, procuring a full spectrum of airway management devices for surgical, emergency, and critical care departments. Hospital networks in the US and Germany drive significant procurement volumes due to their comprehensive service offerings.
- Ambulance Services:These providers require rugged, portable, and easy-to-use devices for prehospital airway management. Demand from ambulance services is accelerating in regions with advanced emergency medical services, including the UK and Canada.
- Surgical Centers:Facilities primarily focused on outpatient surgical procedures, requiring devices for anesthesia administration.
- Specialty Clinics:Niche medical facilities that might require specific airway devices for procedures like endoscopy or pulmonology.
- Trauma Centers:Specialized hospitals equipped to handle severe injuries, requiring advanced airway management tools for rapid stabilization.
Procurement volumes are highest in Hospitals, with Ambulance Services showing significant acceleration.
Deployment Type:
Deployment type categorizes devices by their intended use model, influencing purchasing decisions based on infection control, cost, and mobility requirements for different clinical environments.
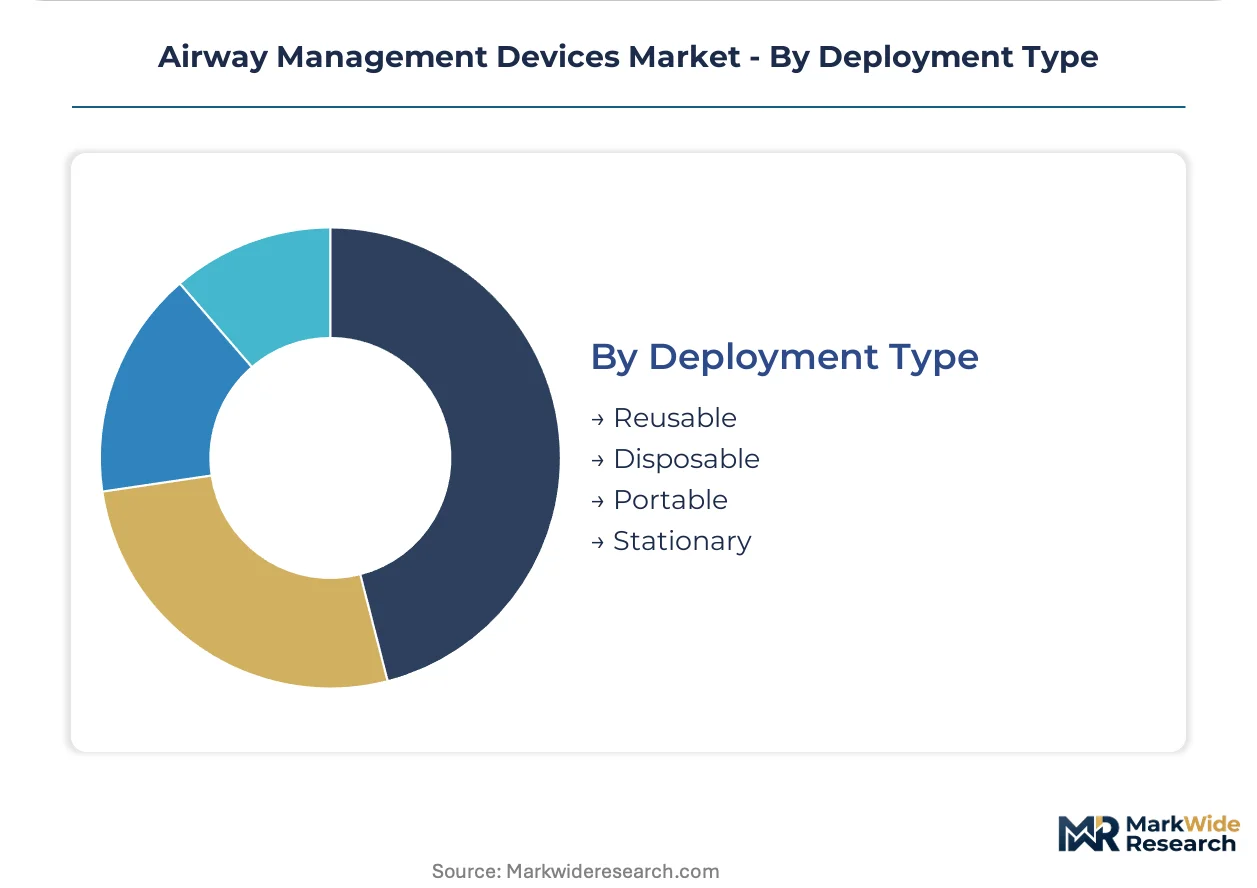
- Disposable:Single-use devices designed to mitigate infection risks and eliminate sterilization costs. Demand for disposable options is rapidly gaining traction in North America and Europe due to stringent infection control mandates.
- Reusable:Devices designed for multiple uses after proper cleaning and sterilization. Reusable systems offer a lower per-use cost but require significant capital investment and ongoing maintenance.
- Portable:Compact and lightweight devices suitable for transport and use outside traditional clinical settings, such as in ambulances.
- Stationary:Larger, fixed equipment typically found in operating rooms or intensive care units.
Most devices sold are Reusable, but demand for Disposable is rapidly gaining share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government and private investment in healthcare modernization programs significantly influence regional market dynamics. These initiatives stimulate demand for advanced airway management devices in developing and developed economies. Policy shifts towards advanced prehospital care also expand market reach beyond traditional hospital settings.
United States
Advanced prehospital care standards and emergency medicine applications drive significant demand for airway management devices. The US FDA's 510(k) clearance process mandates stringent testing for biocompatibility and clinical efficacy. Hospital networks in metropolitan areas such as Chicago and Houston drive substantial procurement volumes.
Germany
Stable demand for general anesthesia and critical care applications underpins the German market. Europe's Medical Device Regulation (MDR) mandates rigorous pre-market and post-market data collection for medical devices. Medical technology clusters around Stuttgart and Hamburg foster innovation and high-quality manufacturing standards.
India
Expanding hospital infrastructure and government investment in healthcare modernization programs create baseline demand in India. The Central Drugs Standard Control Organization (CDSCO) governs medical device approvals and quality standards. Major urban centers like Delhi and Chennai see rapid adoption of advanced airway management technologies.
Brazil
Accelerating adoption of advanced tools like video laryngoscopes in emergency departments drives market growth in Brazil. ANVISA, the national health surveillance agency, regulates medical devices, impacting market access and product specifications. Healthcare expansion in São Paulo and Rio de Janeiro drives procurement volumes for both public and private hospital sectors.
United Kingdom
Advanced emergency medical services and evolving protocols for ambulance services expand the market in the United Kingdom. The UK's Medicines and Healthcare products Regulatory Agency (MHRA) sets stringent device standards for safety and efficacy. NHS procurement in major cities like London and Birmingham significantly influences product specifications.
Airway Management Devices Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of airway management device categories. The market exhibits a tiered structure, with large, diversified medical device conglomerates alongside focused, innovative niche players. These archetypes include global generalists, specialized device manufacturers, and regional distributors. Strategic partnerships and technology licensing agreements represent common competitive moves to expand product reach and enhance innovation.
Specialized device manufacturers such as Teleflex Incorporated and Ambu A/S occupy distinct positions within the market. Teleflex Incorporated exemplifies strength in its specialized laryngeal mask and endotracheal tube portfolios. Ambu A/S represents a focus on single-use and video-enabled airway devices, differentiating its market approach. Furthermore, Medtronic, as a diversified medical technology conglomerate, leverages its extensive distribution network to command a significant presence across multiple applications.
| Leading Market Players |
|---|
| ICU Medical |
| Intersurgical Ltd |
| Medtronic |
| Medline Industries |
| BD |
| Teleflex Incorporated |
| Convatec |
| KARL STORZ SE & Co. KG |
| Ambu A/S |
| Others |
Cost & Logistics Intelligence
The shift towards disposable medical-grade PVC and silicone devices reshapes supply geography, concentrating manufacturing in cost-effective regions while influencing overall market pricing. This dynamic balances infection control benefits against material sourcing complexities.
Pricing Analysis
Certification level (ISO 13485, FDA 510(k), MDR compliance) creates the primary spread in airway management device pricing. The dominant model blends per-unit transactional pricing with a growing emphasis on total cost of ownership, particularly in North America and Europe. Price differentiation stems from clinical efficacy, brand reputation, and the balance between upfront cost for reusable systems versus infection control benefits of disposables. Cost compression in the disposable segment reflects increasing competition and demand for affordability. Budget-constrained facilities exhibit high price sensitivity, while larger hospital networks prioritize long-term value.
Supply Chain Analysis
Inbound logistics costs, particularly for medical-grade PVC and silicone, significantly influence the airway management device supply chain. Manufacturing concentrates across Germany, China, and Southeast Asia, drawing on global raw material sources. Key dependencies include medical-grade polymers and specialized digital imaging components for video laryngoscopes. Material price volatility presents a structural risk, impacting manufacturing costs and margin stability. Distribution runs through established medical device networks, with increasing direct sales to hospital procurement departments and specialized distributors for emergency services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The airway management devices market experiences a cyclical recovery, driven by sustained global healthcare infrastructure expansion and modernization programs. This rebound creates opportunities across product innovation and market penetration.
For Market Incumbents: Secure market share by investing in cost-effective single-use video laryngoscopes, addressing both infection control mandates and budget constraints. Incumbents like Medtronic must leverage their extensive distribution networks to counter the threat of specialized niche players. Strengthening R&D in biocompatible materials for advanced disposable devices will also reinforce their competitive positioning. Compliance with evolving regulations like Europe's MDR is a continuous lever for market access.
For New Entrants and Emerging Players: Certification fast-track pathways, like targeted 510(k) submissions for specific device types, offer new entrants a strategic entry point. A clear white-space target exists in specialized pediatric devices, addressing unique anatomical challenges. Focusing on affordable, disposable video laryngoscopes for budget-constrained facilities, particularly in expanding markets like Southeast Asia, provides a strong go-to-market angle. Differentiation through superior clinician training programs can also accelerate adoption.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized device manufacturers with strong R&D in video-enabled and single-use technologies. Long-term viability is strong, given the essential nature of airway management in critical care and surgery. Acquisition targets should prioritize innovative firms with robust intellectual property in next-generation video laryngoscopy or pediatric solutions. The signal to watch is the accelerating adoption rate of advanced airway tools in prehospital care settings across developing economies.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance | This streamlines market access for innovative video laryngoscopes in the United States. |
| Hospital Network Partnerships | Securing procurement contracts with major hospital networks ensures stable demand for essential devices. |
| Manufacturing Scale-Up for Disposables | Increasing production capacity for single-use devices addresses growing infection control priorities. |
| MDR Clinical Data Generation | Rigorous post-market data collection ensures compliance with Europe's Medical Device Regulation. |
| Targeted Geographic Expansion | Entering high-growth markets like India and Brazil capitalizes on expanding healthcare infrastructure. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry whitepapers, and medical association reports. Primary interviews engaged clinicians, hospital purchasing committees, and medical device engineers to gather granular insights. This approach triangulates bottom-up market intelligence with top-down industry trends.
Product type, application, end-user, and deployment type segmentation dimensions were modeled across the analysis window. Compound annual growth rates were derived from historical market performance, identified growth catalysts, and expert consensus. Industry-specific forecast inputs included video laryngoscopy adoption rates in emergency medicine and regional healthcare infrastructure investment trends.
Underlying assumptions cover regulatory stability and consistent raw material supply, with deviation risk concentrated in unforeseen material price volatility or major policy shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Annuloplasty System Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Asia-Pacific Viscosupplementation Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Plethysmograph Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Bariatric Beds Market
Medical Devices
Condylar Plate Fixation System Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
BFS Syringes Market