
 Global Angioplasty Balloons Market | 2026-2036
Global Angioplasty Balloons Market Size, Share, and Industry Trends Forecast 2026-2036
Global Angioplasty Balloons Market Foresight
Single-source procurement for balloon catheters is consolidating into multi-source contracts across integrated health networks. Medtronic leverages its vertically integrated balloon manufacturing to sustain supply security for hospital systems. Boston Scientific Corporation competes through specialized cutting balloon platforms that anchor its position in complex lesion intervention.
Angioplasty balloons are inflatable medical devices constructed from polyethylene terephthalate or nylon blends, designed to dilate stenotic vessels through controlled radial expansion at rated burst pressures typically spanning 12 to 20 atmospheres. Their primary purpose is restoring luminal patency in percutaneous coronary and peripheral interventions without requiring permanent implant placement. Drug-coated balloons command premium positioning within the product type dimension as antiproliferative coatings shift margin pools away from standard balloon commoditization. The therapy area dimension shows coronary artery disease maintaining volume leadership while peripheral artery disease segments attract faster procedural growth due to expanding endovascular alternatives to bypass surgery.
The FDA's premarket notification pathway and the European Medicines Agency's medical device regulation framework govern balloon safety validations, with both agencies tightening biocompatibility testing requirements that extend product development cycles. Japan's Ministry of Health, Labour and Welfare adds a third compliance layer through its pharmaceutical and medical device agency reviews that shape market entry sequencing across Asia-Pacific. Stakeholders must monitor how reimbursement shifts toward outpatient settings reshape procurement criteria for ambulatory surgical centers versus traditional hospital purchasing.
Market Dynamics
The shift toward drug-coated balloon platforms is compressing margins on standard balloon commoditization while forcing manufacturers to rebuild coating chemistry capabilities. FDA breakthrough device designations are accelerating clearance timelines for novel antiproliferative delivery systems, redistributing competitive advantage toward vertically integrated suppliers.
Growth Catalysts
- Breakthrough Device Pathway:The FDA's accelerated review mechanism shortens time-to-market for novel balloon technologies, concentrating investment in coating innovation pipelines.
- Peripheral Artery Disease Expansion:Endovascular alternatives to bypass surgery are capturing procedural volume in Germany's interventional cardiology centers, driving specialized balloon demand.
- Polyethylene Terephthalate Material Advances:Improved burst pressure tolerances in balloon construction materials enable safer dilation of calcified lesions.
Market Restraints
- Nylon Blend Input Volatility:Petroleum-derived polymer feedstock costs fluctuate with energy markets, compressing manufacturing margins unpredictably.
- Biocompatibility Testing Burden:The European Medicines Agency's MDR framework extends validation timelines for coating safety assessments.
- Coronary Stent Substitution:Drug-eluting stents retain preference in certain lesion types, limiting balloon-only procedure expansion.
Strategic Opportunities
- Japan's PMDA Review Alignment:Harmonized regulatory pathways with FDA breakthrough criteria enable faster Asia-Pacific market entry sequencing.
- Ambulatory Surgical Center Channel:Reimbursement migration toward outpatient settings creates procurement entry points outside traditional hospital purchasing.
- Cutting Balloon-Imaging Convergence:Integration with intravascular ultrasound guidance systems enables precise lesion modification in complex anatomies.
Industry Challenges
- Coating Chemistry Talent Scarcity:Antiproliferative formulation expertise concentrates in a limited pool of pharmaceutical-device hybrid specialists.
- ISO 10993 Certification Complexity:Biocompatibility testing standards require extensive cytotoxicity and sensitization studies that extend development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Angioplasty Balloons Market |
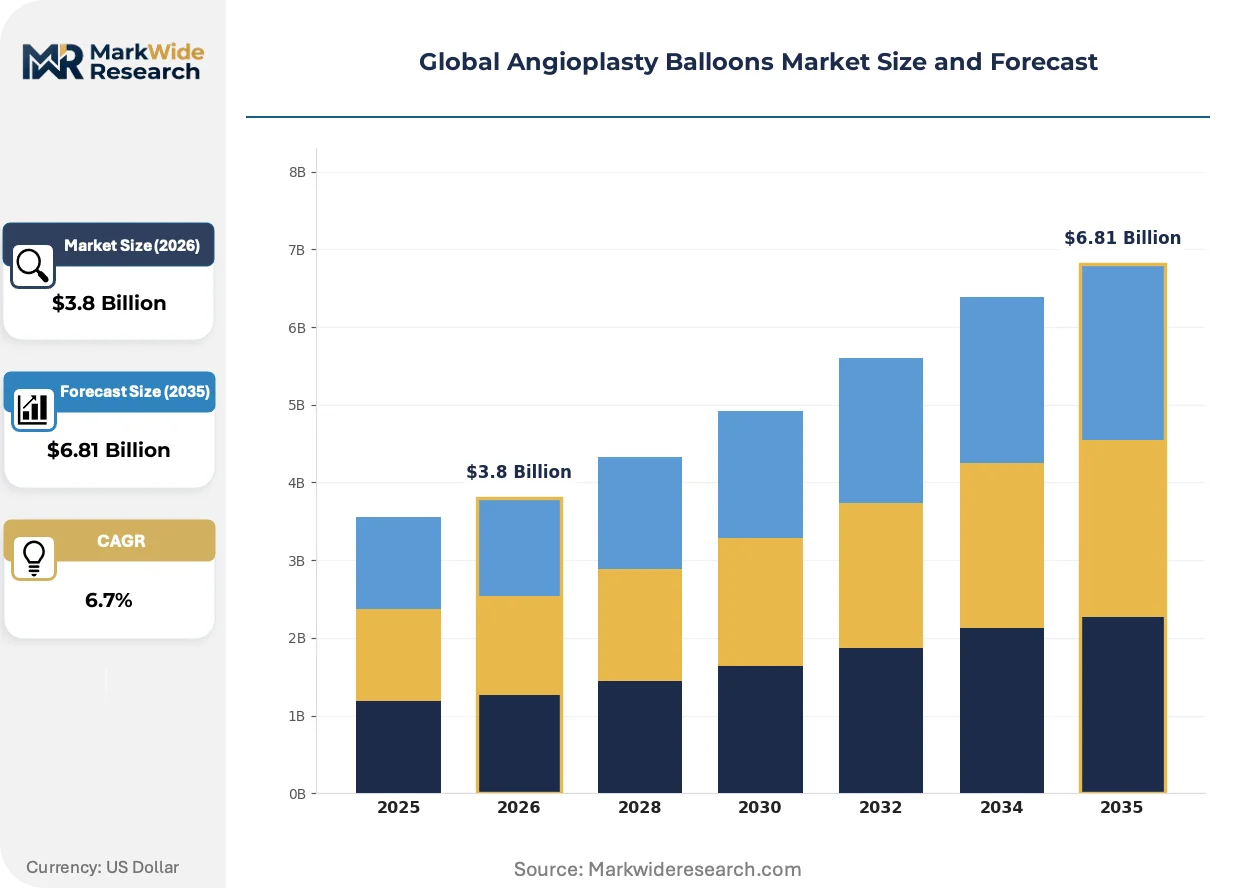
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Balloons, High-Pressure Balloons, Cutting Balloons, Drug-Coated Balloons, Scoring Balloons Therapy Area: Coronary Artery Disease, Peripheral Artery Disease, Renal Artery Stenosis, Carotid Artery Disease, Neurovascular Disease End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Research Institutions, Diagnostic Centers Delivery Mode: Over-the-Wire, Rapid Exchange, Semi-Compliant, Non-Compliant, Dual-Lumen |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, Terumo Corporation, BIOTRONIK, B. Braun Melsungen AG, Cook Medical, Teleflex Incorporated, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Angioplasty Balloons Market Shifts & Advancements
Balloon catheter design is converging with pharmaceutical delivery science, creating hybrid devices that challenge traditional stent economics. Manufacturers are rebuilding R&D organizations around coating chemistry rather than mechanical engineering alone.
Drug-coated balloon technology is unifying antiproliferative therapy with mechanical dilation in a single procedure. Cardiology clinics in Germany's interventional centers are adopting these platforms at accelerated rates. This convergence is compressing the addressable market for bare-metal and drug-eluting stents in focal lesion treatment.
REACH compliance requirements in Europe are tightening scrutiny of coating substance environmental fate and patient exposure pathways. Manufacturers must now document full chemical characterization of antiproliferative agents and excipients. The MDR framework most heavily impacts drug-coated balloon categories, forcing reformulation investments for market retention.
Hospital procurement committees are consolidating catheter purchasing into multi-year, multi-source agreements that span integrated health networks. Traditional distributor relationships face displacement by direct manufacturer contracting with procurement officers. This pattern is most visible in Germany's hospital federation purchasing structures and spreading to North American integrated delivery networks.
Global Angioplasty Balloons Market Segmentation
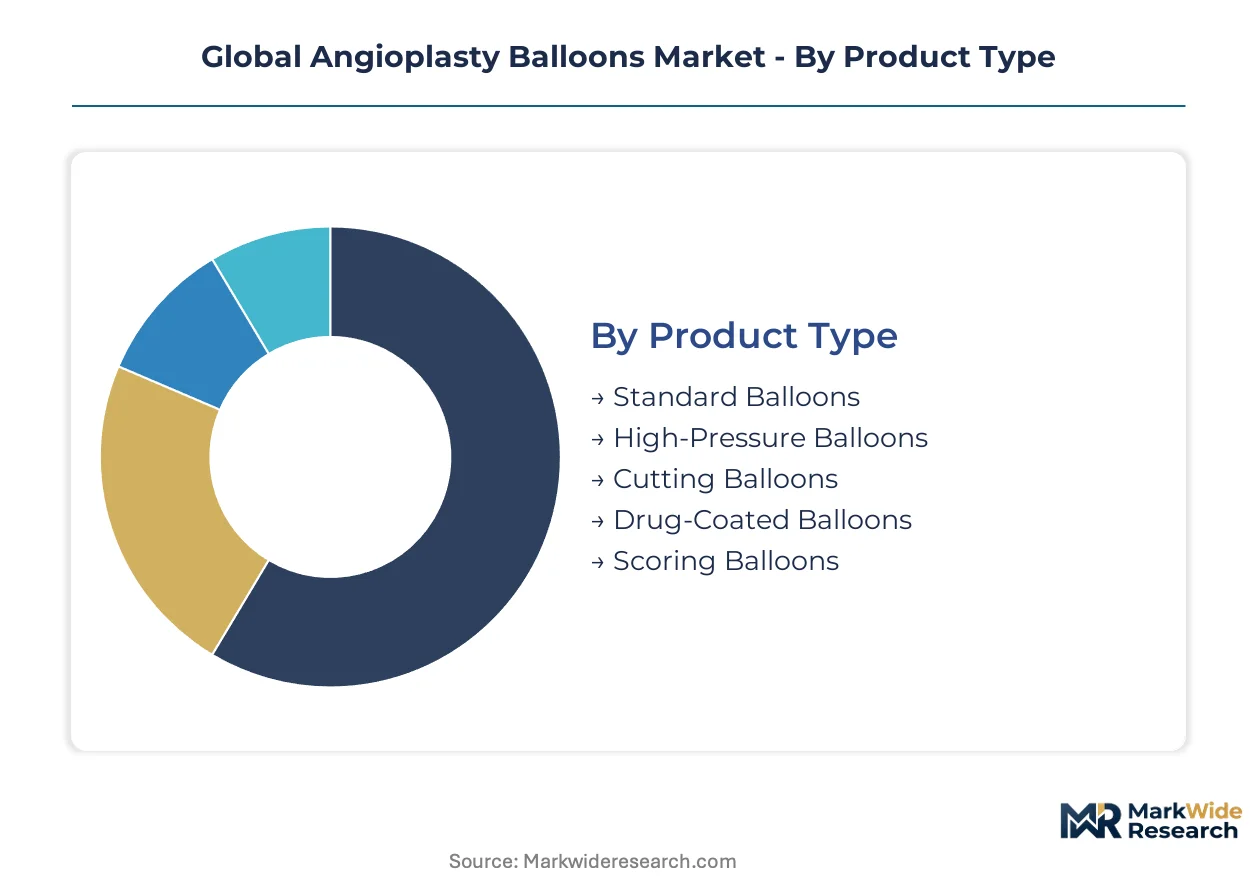
Angioplasty balloon segmentation reveals how manufacturers balance commoditized volume products against premium platforms commanding pricing power. The product type dimension captures this tension most directly, with coating chemistry investments separating margin leaders from price-takers.
Product Type:
Customization intensity spans from commodity polyethylene terephthalate constructions to pharmaceutical-device hybrids requiring antiproliferative formulation expertise.
- Drug-Coated Balloons:Polymer matrix or excipient-based coatings deliver paclitaxel or sirolimus analogs during vessel dilation. Germany's interventional cardiology centers are expanding adoption fastest as antiproliferative therapy shifts from permanent stent placement to transient drug delivery.
- Standard Balloons:Nylon blend or polyethylene terephthalate constructions without therapeutic coatings serve high-volume coronary and peripheral procedures. Procurement committees in integrated health networks are consolidating these into multi-source contracts that compress manufacturer margins.
- High-Pressure Balloons:Reinforced wall constructions withstand 20+ atmosphere rated burst pressures for calcified lesion modification.
- Cutting Balloons:Atherotome-equipped platforms combine mechanical scoring with radial expansion for fibrotic lesions.
- Scoring Balloons:Nitinol strut or wire-wrapped designs concentrate force distribution for controlled vessel preparation.
Leading the category by volume: Standard Balloons. Expanding most quickly: Drug-Coated Balloons.
Therapy Area:
Procedural volume concentrates in coronary interventions while peripheral segments attract endovascular alternatives to open surgery.
- Coronary Artery Disease:Percutaneous coronary intervention maintains procedural leadership across hospital systems and cardiology clinics. Japan's PMDA review pathways shape market entry sequencing for novel platforms targeting complex bifurcation lesions.
- Peripheral Artery Disease:Femoropopliteal and infrapopliteal endovascular procedures are capturing cases previously routed to bypass surgery. FDA breakthrough device designations are accelerating clearance timelines for drug-coated platforms in this segment.
- Renal Artery Stenosis:Resistant hypertension intervention represents a narrower addressable market with specialized sizing requirements.
- Carotid Artery Disease:Transfemoral and transcervical access routes demand specialized balloon profiles and embolic protection compatibility.
- Neurovascular Disease:Intracranial angioplasty requires ultra-low profile constructions and navigational flexibility for tortuous anatomy.
Coronary Artery Disease dominates procedural counts. Peripheral Artery Disease demonstrates the steepest expansion trajectory as endovascular technique diffusion continues.
End User:
Purchasing authority is migrating from hospital materials management toward integrated network procurement offices and ambulatory channel specialists.
- Hospitals:Interventional cardiology suites and hybrid operating rooms maintain the largest installed base of angiography systems. Germany's hospital federation purchasing structures exemplify multi-source contract consolidation across integrated networks.
- Cardiology Clinics:Specialized intervention centers in Germany are adopting drug-coated balloon platforms at accelerated rates. These facilities concentrate expertise in complex lesion subsets that justify premium platform selection.
- Ambulatory Surgical Centers:Outpatient reimbursement migration is creating procurement entry points outside traditional hospital purchasing.
- Research Institutions:Academic medical centers drive clinical trial enrollment for novel coating formulations.
- Diagnostic Centers:Peripheral vascular testing facilities occasionally perform low-complexity interventions.
Hospitals retain the largest procurement scale. Cardiology Clinics are gaining share fastest as procedure volume shifts toward specialized intervention centers.
Delivery Mode:
Trackability and pushability trade-offs define physician preference across lesion complexity and access site selection.
- Rapid Exchange:Short guidewire monorail segments enable single-operator technique with reduced radiation exposure. This design dominates coronary interventions where procedural efficiency drives throughput in busy catheterization laboratories.
- Over-the-Wire:Full-length guidewire lumen provides superior trackability for tortuous peripheral anatomy and subintimal reentry procedures.
- Semi-Compliant:Diameter expansion varies with inflation pressure for tapered vessel accommodation.
- Non-Compliant:Fixed diameter at rated pressure enables precise sizing for stent deployment or high-pressure dilation.
- Dual-Lumen:Separate inflation and guidewire channels facilitate simultaneous pressure monitoring or contrast injection.
Rapid Exchange leads by procedural volume. Over-the-Wire platforms are climbing fastest in peripheral artery disease applications requiring extended catheter support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene terephthalate and nylon polymer feedstocks concentrate manufacturing investment in Germany, the United States, and Japan. These material foundations shape regional competitive positioning across balloon catheter production.
United States
FDA breakthrough device designations accelerate clearance timelines for novel antiproliferative delivery systems. The agency's premarket notification pathway governs biocompatibility validations that extend development cycles. Minneapolis-St. Paul anchors vertically integrated balloon manufacturing operations serving hospital systems nationwide.
Germany
Interventional cardiology centers in Bavaria and Baden-Württemberg drive specialized drug-coated balloon adoption. The EU MDR framework tightens coating substance scrutiny through REACH compliance requirements. Berlin-Brandenburg hosts research institutions advancing pharmaceutical-device hybrid formulations.
Japan
PMDA review pathways shape Asia-Pacific market entry sequencing for complex bifurcation lesion platforms. METI standards guide polyethylene terephthalate material characterization for burst pressure tolerance. The Kanto region around Tokyo concentrates catheterization laboratory infrastructure and physician training networks.
China
NMPA medical device regulations govern balloon safety validations for domestic and export markets. The Yangtze River Delta clusters precision polymer processing capabilities for nylon blend constructions. Shanghai-based procurement offices consolidate multi-source contracts across integrated hospital networks.
India
CDSCO medical device rules align with international standards for coating chemistry assessments. The country's national pharmaceutical regulator emphasizes local clinical trial data for novel platform approvals. Maharashtra's Mumbai-Pune corridor attracts contract manufacturing for standard balloon commoditized segments.
Global Angioplasty Balloons Market Competitive Landscape
Backward integration into polymer feedstock supply dominates the current landscape among tier-one manufacturers. The vendor base organizes around three strategic archetypes: vertically integrated medical device conglomerates, specialized interventional cardiology platforms, and regional fabrication specialists serving price-sensitive procurement channels. Portfolio diversification and technology licensing represent the dominant competitive moves reshaping market structure.
Within the vertically integrated tier, Medtronic and Boston Scientific Corporation exemplify captive supply strategies that secure polyethylene terephthalate and nylon blend input security. Abbott Laboratories occupies a position bridging pharmaceutical coating science with mechanical device engineering. These three anchors represent how antiproliferative formulation expertise concentrates competitive advantage away from pure mechanical fabrication.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Terumo Corporation |
| BIOTRONIK |
| B. Braun Melsungen AG |
| Cook Medical |
| Teleflex Incorporated |
| MicroPort Scientific Corporation |
| Others |
Supply & Pricing Matrix
Polyethylene terephthalate resin price indices cascade through angioplasty balloon manufacturing into three-tier pricing stratification across premium, standard, and economy levels. Nylon blend feedstock volatility from petroleum derivatives compresses margins at the commodity tier while coating chemistry investments sustain premium positioning for drug-coated platforms.
Pricing Analysis
Service bundling separates warranty-backed coating performance guarantees from unbundled standard balloon transactions. Three-tier pricing stratification across premium, standard, and economy levels organizes around FDA breakthrough designation status and ISO 10993 certification tier. Price differentiation hinges on antiproliferative formulation complexity versus mechanical construction alone. Cost compression in standard balloon tiers is intensifying because integrated health networks consolidate multi-source procurement contracts. Ambulatory surgical centers exhibit highest price sensitivity; Germany's interventional cardiology centers demonstrate lowest sensitivity due to outcome-based reimbursement alignment.
Supply Chain Analysis
Single-source vulnerability sits with Germany's specialized polymer processing cluster for high-purity polyethylene terephthalate medical grades. Manufacturing draws from Germany, the United States, and Japan for polymer feedstock concentration. Raw material dependencies rest on petroleum-derived nylon blends, specialty polyethylene terephthalate resins, and antiproliferative active pharmaceutical ingredients. Supply chain risk centers on REACH compliance complexity forcing coating substance reformulation. Distribution runs through direct manufacturer contracting with hospital procurement committees and GPO aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Angioplasty balloon manufacturing is becoming a vertical-integration race as coating chemistry capabilities separate margin leaders from price-takers. Players are pursuing backward integration into polymer feedstock supply to secure input cost control and quality certification.
For Market Incumbents: Lock in captive supply of polyethylene terephthalate and nylon blend feedstocks through backward integration or long-term offtake agreements with German polymer specialists. Defend against drug-eluting stent substitution by accelerating FDA breakthrough pathway submissions for next-generation antiproliferative delivery systems. Expand coating chemistry R&D headcount in Berlin-Brandenburg research clusters to retain formulation expertise concentration.
For New Entrants and Emerging Players: Direct-to-ambulatory-surgical-center distribution routes bypass entrenched hospital GPO relationships and capture reimbursement migration toward outpatient settings. White-space opportunity concentrates in India's CDSCO-regulated market where local clinical trial requirements create barriers for established multinationals. Target peripheral artery disease drug-coated balloon segments where FDA breakthrough designations accelerate clearance timelines for novel entrants. Prioritize rapid exchange catheter designs for coronary efficiency demands.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier coating chemistry specialists in Germany facing REACH compliance investment burdens. Long-term viability across the projection horizon favors pharmaceutical-device hybrid capabilities over pure mechanical fabrication. Acquisition target archetype: vertically integrated European manufacturers with PMDA-aligned regulatory dossiers for Asia-Pacific expansion. Watch FDA breakthrough designation grant velocity as inflection indicator for competitive repositioning speed.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Acquisition | Captures antiproliferative formulation expertise concentrated in Berlin-Brandenburg research institutions. |
| Polymer Feedstock Integration | Secures polyethylene terephthalate supply security against petroleum price volatility in German manufacturing clusters. |
| PMDA Regulatory Alignment | Enables accelerated Japan market entry sequencing for complex bifurcation lesion platforms. |
| Ambulatory Surgical Center Partnership | Captures procurement entry points outside traditional hospital GPO contracting structures. |
| REACH Compliance Reformulation | Retains European market access as EMA MDR framework tightens coating substance scrutiny. |
Research Methodology
FDA 510(k) premarket notifications, EMA MDR technical documentation, and Japan PMDA review pathway records formed the secondary backbone for regulatory landscape mapping. Primary interviews with interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers validated procedural volume assumptions and procurement pattern shifts. Secondary sources included hospital procurement databases, CMS Medicare reimbursement filings, and German hospital federation purchasing structure disclosures. Bottom-up procedural volume estimates triangulated against top-down manufacturer capacity assessments.
Historical trendline analysis of polyethylene terephthalate material advances and coating chemistry diffusion patterns informed projection modeling across the analysis window. Segmentation dimensions modeled include product type differentiation, therapy area procedural volume, end-user purchasing authority migration, and delivery mode technical specifications. CAGRs derived from weighted average of procedure growth trajectories, pricing tier compression rates, and regulatory approval velocity assumptions. Forecast inputs incorporated FDA breakthrough designation pipeline tracking and REACH compliance investment cycles.
The model holds under stable regulatory harmonization between FDA, EMA, and PMDA frameworks; deviation in reimbursement migration speed or polymer feedstock cost volatility would shift volume and value trajectories. Forecasts reflect assumptions regarding coating chemistry talent availability and integrated health network consolidation pace. Risk factors include coronary stent technology substitution advances and biocompatibility testing standard revisions extending development cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cranial Orthoses Market
Medical Devices
Mucus Clearance Devices Market
Medical Devices
Steerable Needles Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
Interphalangeal Fusion Market
Medical Devices
Global Prosthetics Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Urometer Market
Medical Devices
Global Defibrillators Market
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Diabetic Eye Disease Devices Market
Medical Devices
Hybrid Microcirculation Detector Market