
 Slip Disc Market | 2026-2036
Slip Disc Market Size, Share, and Industry Trends Forecast 2026-2036
Slip Disc Market Outlook
Market Context
Project finance and leasing arrangements for surgical robotics suites is narrowing the competitive field to well-capitalized hospital systems and their vendor partners. Globus Medical leverages its integrated manufacturing footprint to control implant costs across multiple cervical and lumbar product lines. DePuy Synthes Companies sustains broad geographic coverage through established distributor relationships in tertiary care markets. Medtronic anchors its position via deep R&D commitments to navigated spinal technologies.
Technical Definition and Segments
Slip disc refers to the herniation or protrusion of the nucleus pulposus through a compromised annulus fibrosus, typically measuring 5–15 mm in extruded dimension and causing radicular compression requiring intervention from conservative management to discectomy. The condition serves commercial purpose across orthopedic, neurosurgical, and pain management practice settings where functional restoration drives reimbursement logic. Surgical Treatment commands the dominant value share given implant and instrumentation intensity, while Minimally Invasive Surgery generates the fastest expansion as hospital outpatient departments seek reduced length-of-stay metrics. Non-Surgical Management retains substantial volume in mild and moderate severity categories where physical therapy protocols and epidural steroid injections delay or preclude operative intervention.
Regulatory Environment
The FDA oversees spinal implant biocompatibility and 510(k) clearance pathways, while ISO 13485 quality management standards govern manufacturing consistency across international supply chains. Europe's MDR framework now demands enhanced clinical evidence for class III spinal devices, extending approval timelines and elevating documentation costs for market participants. Stakeholders must monitor how payor bundling experiments for spinal episodes reshape site-of-service economics between inpatient, ambulatory surgery center, and office-based settings.
Market Dynamics
Hospital outpatient departments are compressing length-of-stay metrics through same-day discharge protocols, forcing implant manufacturers to redesign instrumentation for faster operative times and earlier ambulation.
Growth Catalysts
- MDR Clinical Evidence Requirements:Europe's Medical Device Regulation demands enhanced documentation for Class III spinal implants, accelerating consolidation among manufacturers with robust clinical trial capabilities.
- Titanium Alloy Biocompatibility:The FDA's evolving guidance on implant materials is pushing R&D investment toward porous titanium structures that improve osseointegration and reduce revision rates.
- Munich-Berlin Orthopedic Clustering:Germany's concentration of specialized spine centers creates dense referral networks that concentrate surgical volume and justify capital investment in navigation systems.
Market Restraints
- Titanium Powder Supply Concentration:Additive manufacturing feedstock for patient-specific implants depends on a limited supplier base in Western Europe, exposing producers to input volatility.
- 510(k) Clearance Friction:The FDA's heightened scrutiny of predicate device comparisons extends regulatory timelines for iterative implant designs, delaying revenue recognition.
- Conservative Management Substitution:Epidural steroid injection protocols and structured physical therapy programs capture mild-to-moderate herniation cases before surgical candidacy.
Strategic Opportunities
- ASC Site-of-Service Migration:Ambulatory surgery centers in Texas and Florida are building dedicated spine suites that bypass hospital facility fees and capture bundled payment savings.
- AI-Assisted Surgical Planning:Machine learning algorithms trained on preoperative imaging are converging with robotic navigation to reduce fluoroscopy exposure and screw misplacement rates.
- IRA Hospital Capital Access:Inflation Reduction Act provisions for rural healthcare infrastructure expand leasing pathways for surgical robotics in underserved U.S. markets.
Industry Challenges
- Neuro-navigation Technician Scarcity:Operating room staff proficient in intraoperative imaging registration and robotic arm calibration command premium compensation in competitive labor markets.
- Legacy EMR Integration:New implant tracking systems must interface with hospital enterprise software architectures that lack standardized data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slip Disc Market |
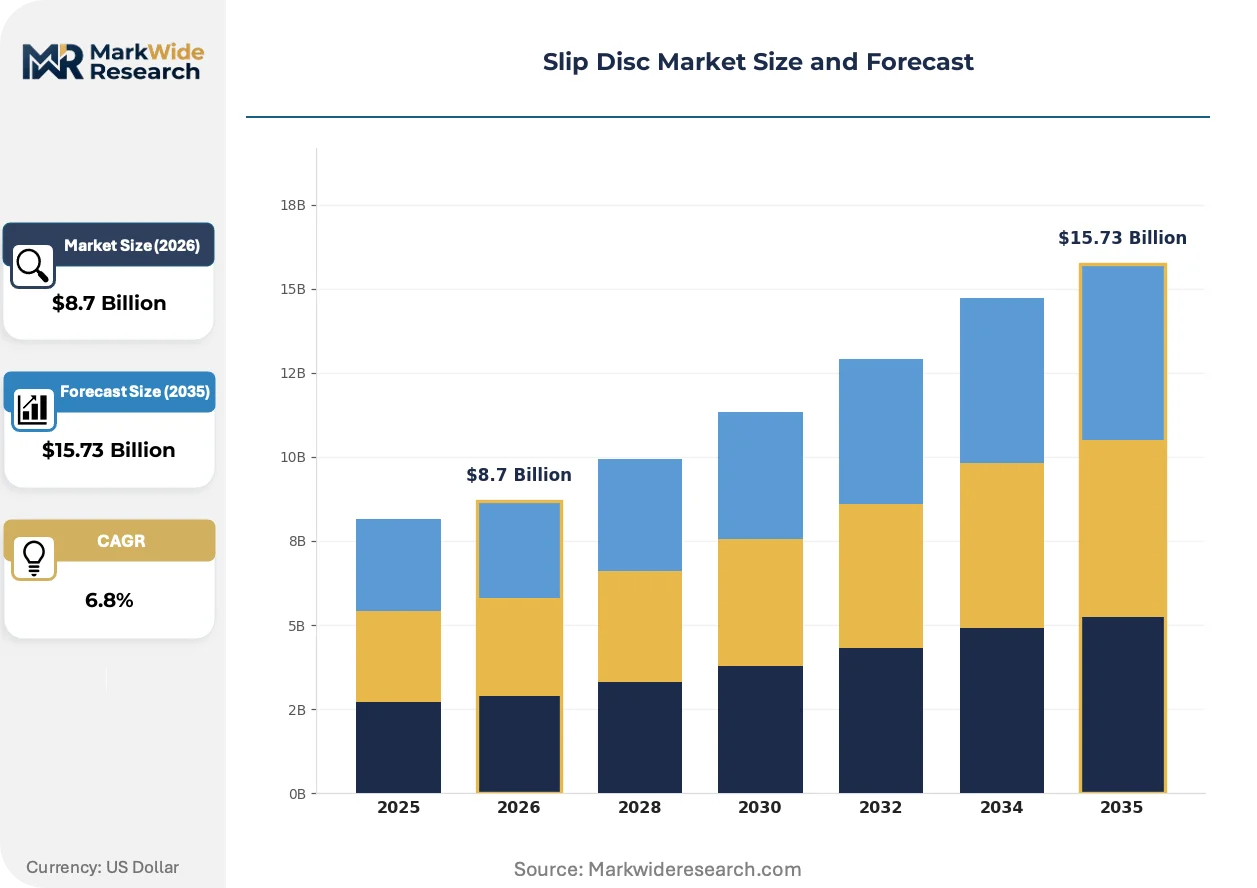
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Physical Therapy, Surgical Treatment, Injection Therapy End User: Hospitals, Rehabilitation Centers, Outpatient Clinics, Home Care Treatment Method: Minimally Invasive Surgery, Traditional Surgery, Chiropractic Care, Non-Surgical Management Severity Level: Mild, Moderate, Severe, Chronic |
| Companies Covered | Globus Medical, DePuy Synthes Companies, Medtronic, Captiva Spine, Orthofix Medical Inc., Stryker, Zimmer Biomet, B. Braun Melsungen AG, NuVasive, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slip Disc Market Strategic Shifts
Navigation-enabled surgical workflows are compressing the technical learning curve for complex deformity correction, redistributing procedural volume from academic medical centers to community hospital systems with capital access.
Patient-specific titanium interbody cages fabricated through selective laser melting are collapsing the distinction between off-the-shelf and custom implant portfolios. Community hospitals with robotic suites are adopting these devices to differentiate their spine programs without fellowship-trained surgeons. The technology is collapsing inventory carrying costs as hospitals shift from stocking multiple sizes to ordering single-use sterile implants post-preoperative planning.
The FDA's updated biocompatibility guidance for permanent implants is tightening cytotoxicity and sensitization testing requirements for polymer-based nucleus replacement devices. Manufacturers must now submit extended-duration animal studies that add 18-24 months to development cycles. Lumbar total disc replacement programs face the steepest compliance burden as predicate devices from the early 2000s lack contemporary toxicological profiles.
Hospital procurement committees are unbundling implant costs from instrumentation and biologics, creating discrete vendor relationships for each category rather than single-source bundled contracts. This fragmentation benefits specialized cage manufacturers while pressuring full-line suppliers to defend position through consignment inventory arrangements. The shift is most visible in California and New York health systems where centralized value analysis committees mandate multi-vendor sourcing for spinal fusion episodes.
Slip Disc Market Segmentation
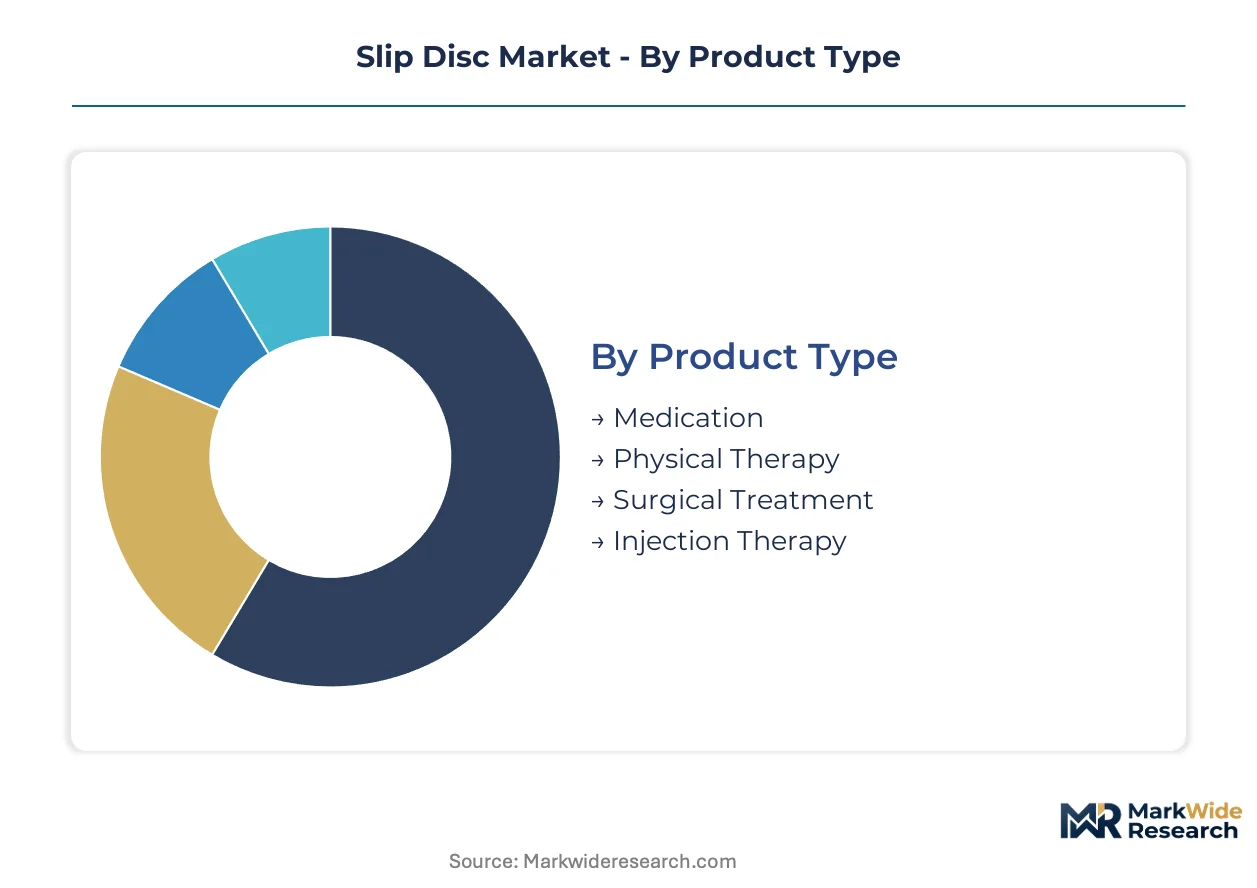
Slip disc treatment pathways diverge sharply across severity gradients, reimbursement models, and site-of-service economics. Manufacturers and service providers must align portfolio depth with where patient volumes actually concentrate rather than where clinical theory suggests they should flow.
Product Type:
Mature pharmaceutical and surgical implant portfolios coexist with emerging biologic and regenerative modalities, creating tiered investment horizons across the product spectrum.
- Surgical Treatment:Spinal fusion hardware and interbody cages dominate commercial value, with titanium alloy constructs commanding preference in German orthopedic centers and U.S. hospital systems pursuing navigated workflows. Implant intensity per procedure sustains manufacturer margins even as outpatient migration pressures facility fees.
- Medication:NSAID protocols and neuropathic pain agents capture chronic management volumes, though opioid prescribing restrictions in multiple jurisdictions have shifted prescribing patterns toward gabapentinoids and muscle relaxants with lower reimbursement ceilings.
- Physical Therapy:Structured exercise protocols and manual therapy represent the conservative management backbone, with demand clustering in rehabilitation centers seeking bundled payment inclusion.
- Injection Therapy:Epidural steroid and facet joint interventions serve as surgical gatekeepers, with ASC site-of-service expansion driving volume toward freestanding facilities in Texas and Florida.
Surgical Treatment retains volume leadership; Minimally Invasive Surgery within that category holds the steepest expansion curve.
End User:
Capital intensity and regulatory licensing requirements create distinct competitive moats across institutional settings, with reimbursement differentials determining where procedural volume migrates.
- Hospitals:Tertiary centers anchor complex deformity and revision caseloads, with academic medical centers in Munich and Berlin concentrating navigation-enabled surgical volume that justifies robotics capital expenditure.
- Outpatient Clinics:Injection therapy and conservative management protocols dominate, with independent practices in U.S. metropolitan markets capturing episodic bundling experiments.
- Rehabilitation Centers:Post-operative recovery and non-surgical functional restoration programs align with European MDR documentation requirements for Class III device follow-up.
- Home Care:Remote monitoring and patient-administered physical therapy protocols emerge as cost containment tools, though reimbursement frameworks lag technology deployment.
Hospitals retain volume leadership; Outpatient Clinics gain share fastest as site-of-service economics shift.
Treatment Method:
Technical capability requirements and training pathways segment the provider base, with capital access determining which modalities institutions can offer.
- Minimally Invasive Surgery:Tubular retractor systems and endoscopic discectomy techniques compress length-of-stay metrics, with hospital outpatient departments in North American markets adopting same-day discharge protocols that demand redesigned instrumentation.
- Traditional Surgery:Open laminectomy and fusion procedures retain indication for severe stenosis and instability cases, with academic centers maintaining volume for training purposes despite outpatient migration.
- Chiropractic Care:Manual adjustment protocols serve mild herniation presentations, with practice concentration in U.S. states permitting direct access without physician referral.
- Non-Surgical Management:Structured conservative protocols capture moderate severity cases before surgical candidacy, with physical therapy and injection sequencing governed by payor prior authorization requirements.
Traditional Surgery retains volume leadership; Minimally Invasive Surgery climbs the fastest as capital equipment penetrates community hospitals.
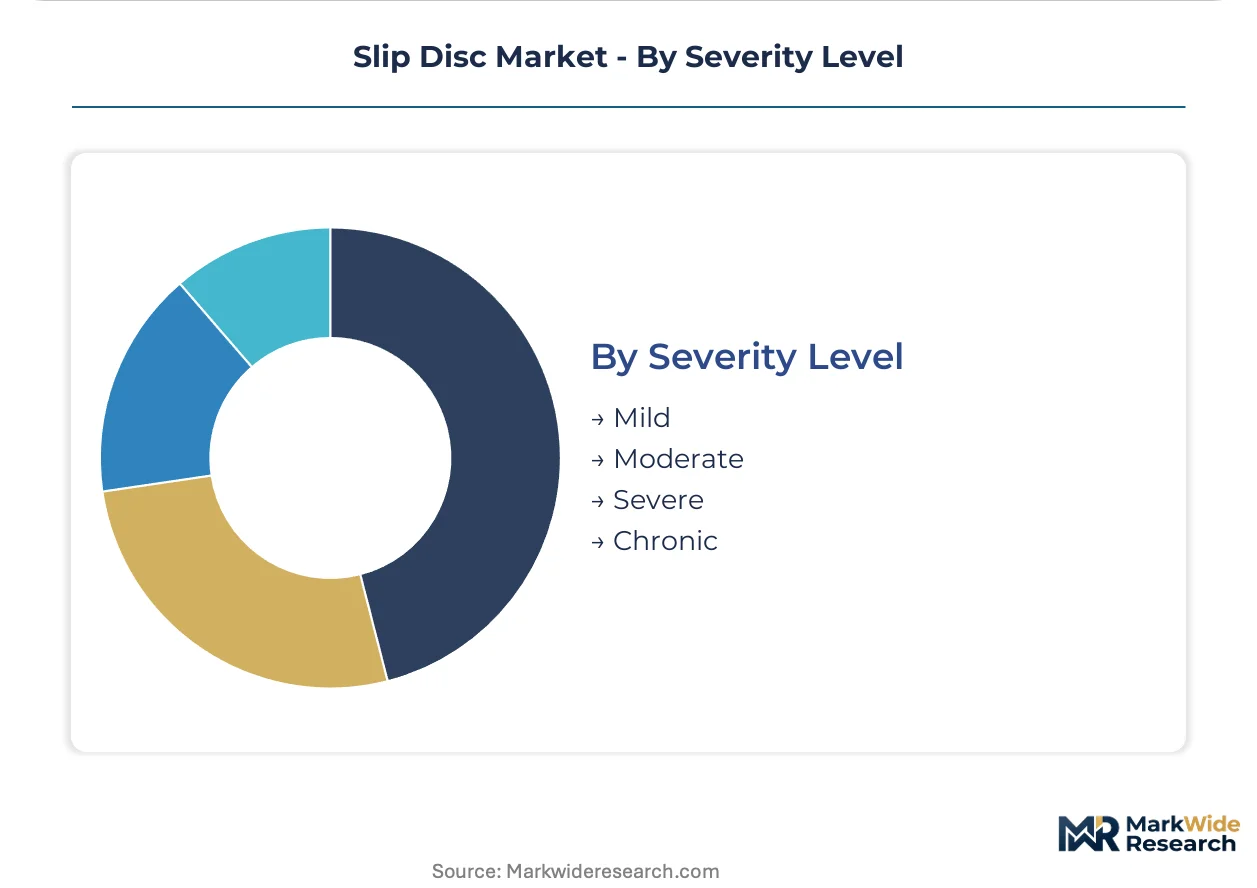
Severity Level:
Clinical presentation intensity determines reimbursement tier and site-of-service eligibility, with diagnostic imaging thresholds governing progression through treatment pathways.
- Severe:Cauda equina compression and progressive motor deficit mandate urgent surgical intervention, with emergency department presentation driving inpatient admission regardless of subsequent procedural setting.
- Chronic:Persistent radiculopathy beyond twelve weeks triggers surgical evaluation, though patient selection for operative versus continued conservative management varies by payor preauthorization stringency.
- Moderate:Intermittent radicular symptoms with preserved function capture injection therapy and targeted physical therapy volumes, representing the largest addressable population for non-surgical service providers.
- Mild:Localized back pain without radiculopathy self-selects into activity modification and over-the-counter analgesic use, with limited commercial relevance outside consumer health products.
Moderate severity retains volume leadership; Severe presentations concentrate value per episode despite lower case counts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net import dependence for titanium alloy feedstock shapes regional production economics, with European additive manufacturing clusters absorbing premium-priced powder while Asian fabricators source lower-grade sponge. Trade flows concentrate surgical instrumentation exports from Germany and Switzerland toward Middle Eastern hospital construction projects.
United States
Hospital outpatient departments in Texas and Florida are building dedicated spine suites to capture bundled payment savings from commercial payors. The FDA's evolving 510(k) clearance pathways extend timelines for predicate device comparisons, favoring manufacturers with established clinical trial infrastructure. Academic medical centers in Boston and the Pacific Northwest concentrate navigation-enabled surgical volume that justifies robotics capital expenditure.
Germany
Specialized orthopedic centers cluster around Munich and Berlin, creating dense referral networks that concentrate surgical volume and drive demand for patient-specific titanium interbody cages. The MDR framework demands enhanced clinical evidence for Class III spinal devices, extending approval timelines and elevating documentation costs. Bavarian manufacturing hubs supply precision-machined instrumentation to hospital systems across Western Europe.
Japan
PMDA oversight of permanent implant biocompatibility tightens cytotoxicity testing requirements for polymer-based nucleus replacement devices. Kanto region hospitals adopt AI-assisted surgical planning systems to reduce fluoroscopy exposure in aging patient populations. Osaka-based fabricators export minimally invasive retractor systems to Southeast Asian markets with expanding private hospital capacity.
India
CDSCO regulatory harmonization with ISO 13485 standards accelerates domestic manufacturing of spinal fusion hardware for price-sensitive hospital procurement. Maharashtra and Karnataka host contract manufacturing operations serving European OEMs seeking cost arbitrage on titanium alloy machining. Delhi-NCR rehabilitation centers expand post-operative physical therapy capacity to capture conservative management volumes.
Switzerland
Swissmedic oversight of Class III device quality management sustains premium positioning for precision-machined spinal instrumentation. Zurich and Basel clusters concentrate R&D investment in porous titanium structures that improve osseointegration outcomes. Watchmaking-derived micro-machining expertise transfers to patient-specific implant fabrication for export to German and French orthopedic centers.
Slip Disc Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in instrumentation and biologics. The vendor base stratifies across three tiers: full-line suppliers with navigation system portfolios, focused cage manufacturers with additive manufacturing capabilities, and regional distributors with consignment inventory arrangements. Consolidation pressures concentrate among mid-scale players lacking clinical trial infrastructure for MDR compliance. Dominant competitive moves include backward integration into titanium powder supply and strategic partnerships with ambulatory surgery center chains.
Within the full-line supplier tier, Medtronic and Stryker occupy positions anchored by navigated spinal technology commitments. Among European precision manufacturers, B. Braun Melsungen AG exemplifies the vertically integrated archetype controlling implant costs across multiple cervical and lumbar product lines. Zimmer Biomet sits within the reconstructive-focused group leveraging established distributor relationships in tertiary care markets.
| Leading Market Players |
|---|
| Globus Medical |
| DePuy Synthes Companies |
| Medtronic |
| Captiva Spine |
| Orthofix Medical Inc. |
| Stryker |
| Zimmer Biomet |
| B. Braun Melsungen AG |
| NuVasive, Inc. |
| Others |
Value Chain & Pricing Dynamics
Titanium powder suppliers in Germany and Switzerland capture disproportionate margin pools downstream, as additive manufacturing feedstock for patient-specific interbody cages commands premium pricing that implant manufacturers struggle to pass through to hospital procurement committees.
Pricing Analysis
Hospital procurement committees anchor a fragmented pricing structure where implant costs unbundle from instrumentation and biologics. Pricing stratifies across premium navigated titanium constructs, standard machined cages, and economy-grade legacy systems, with differentiation driven by FDA 510(k) clearance tier and osseointegration performance data. Cost compression in the standard tier intensifies as ASC site-of-service migration pressures facility fees. Ambulatory surgery centers exhibit the highest price sensitivity; academic medical centers with robotics capital commitments show the least.
Supply Chain Analysis
Titanium sponge feedstock draws from concentrated mining operations in Australia, South Africa, and Ukraine, with premium alloy powder production clustering in Western European additive manufacturing hubs. Raw material dependencies span aerospace-grade titanium sponge, argon gas for selective laser melting, and precision-machined instrumentation blanks. Single-source vulnerability in German powder metallurgy suppliers exposes producers to input volatility. Distribution runs through consignment inventory arrangements at hospital systems and specialized orthopedic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The slip disc market operates as a regulatory-entrenchment story, where MDR clinical evidence requirements and FDA 510(k) predicate scrutiny create switching costs that cement incumbent positions.
For Market Incumbents: Build regulatory data moats through extended-duration biocompatibility studies that emerging competitors cannot replicate within viable investment horizons. Deepen backward integration into titanium powder supply to neutralize feedstock volatility from Western European suppliers. The MDR documentation burden threatens mid-scale players lacking clinical trial infrastructure; capture their distressed assets. Prioritize R&D investment in porous titanium structures to defend margin position against polymer-based nucleus replacement substitutes. For New Entrants and Emerging Players: Pursue white-space opportunities in AI-assisted surgical planning software that complements rather than displaces established implant portfolios. Target ambulatory surgery center chains in Texas and Florida seeking bundled payment navigation without full-line vendor dependency. The most penetrable segment sits in patient-specific cage fabrication for community hospitals lacking fellowship-trained surgeons. A software-hardware bundling go-to-market angle bypasses direct implant competition with entrenched full-line suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision manufacturers in Bavaria and Baden-Württemberg facing MDR compliance cost escalation. The five-to-ten year viability window favors platforms with navigated technology portfolios and established hospital GPO contracts. Acquisition target archetypes include additive manufacturing specialists with ISO 13485 certification and captive titanium powder arrangements. Watch FDA guidance evolution on permanent implant cytotoxicity testing as the inflection signal for polymer-based device viability.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Clinical Evidence Buildout | Extended documentation timelines favor manufacturers with captive trial infrastructure in Germany. |
| Titanium Powder Backward Integration | Captive feedstock supply insulates margins from Western European supplier concentration. |
| ASC Site-of-Service Partnership | Dedicated spine suites in Texas and Florida bypass hospital facility fees for bundled savings. |
| AI-Assisted Surgical Planning | Machine learning convergence with robotic navigation reduces fluoroscopy exposure at Kanto region hospitals. |
| Patient-Specific Cage Fabrication | Selective laser melting collapses inventory carrying costs for community hospital systems. |
Study Parameters
Cross-validation between surgeon interviews and hospital procurement database analysis anchors the qualitative findings. Primary fieldwork engaged spinal surgeons, biomedical engineers, GPO contracts managers, and ASC operations directors across tertiary centers and freestanding surgical facilities. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, hospital capital expenditure disclosures, and CMS Medicare claims patterns. Bottom-up procedure volume modeling and top-down implant revenue triangulation converged on segment-level estimates.
Calibration against historical reimbursement shifts and robotics adoption curves informed the projection framework across the analysis window. Segmentation dimensions modeled include treatment severity tier, surgical modality, site-of-service setting, implant material class, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to demographic aging and payor bundling penetration. Forecast inputs incorporated PMDA biocompatibility guidance evolution and IRA rural hospital capital access provisions.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories for hospital leasing arrangements or titanium commodity pricing would shift the trajectory. Forecasts embed assumptions regarding MDR enforcement consistency and FDA predicate device scrutiny levels. Cross-checking against external benchmarks from spinal implant trade associations and hospital supply chain consortiums is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Carotid Artery Stents Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Aerosol Drug Delivery Devices Market
Medical Devices
Sensor Based Smart Catheters Market
Medical Devices
Japan Hemostats Market
Medical Devices
Vaginal Pessary Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Arthroscopy Procedures and Products Market
Medical Devices
France Anesthesia Devices Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Medical Device Connectivity Market
Medical Devices
Total Artificial Heart Market
Medical Devices
Global Chemotherapy Devices Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
North America Neurostimulation Devices Market