
 Japan Neonatal and Prenatal Devices Market | 2026-2036
Japan Neonatal and Prenatal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Neonatal and Prenatal Devices Market Foresight
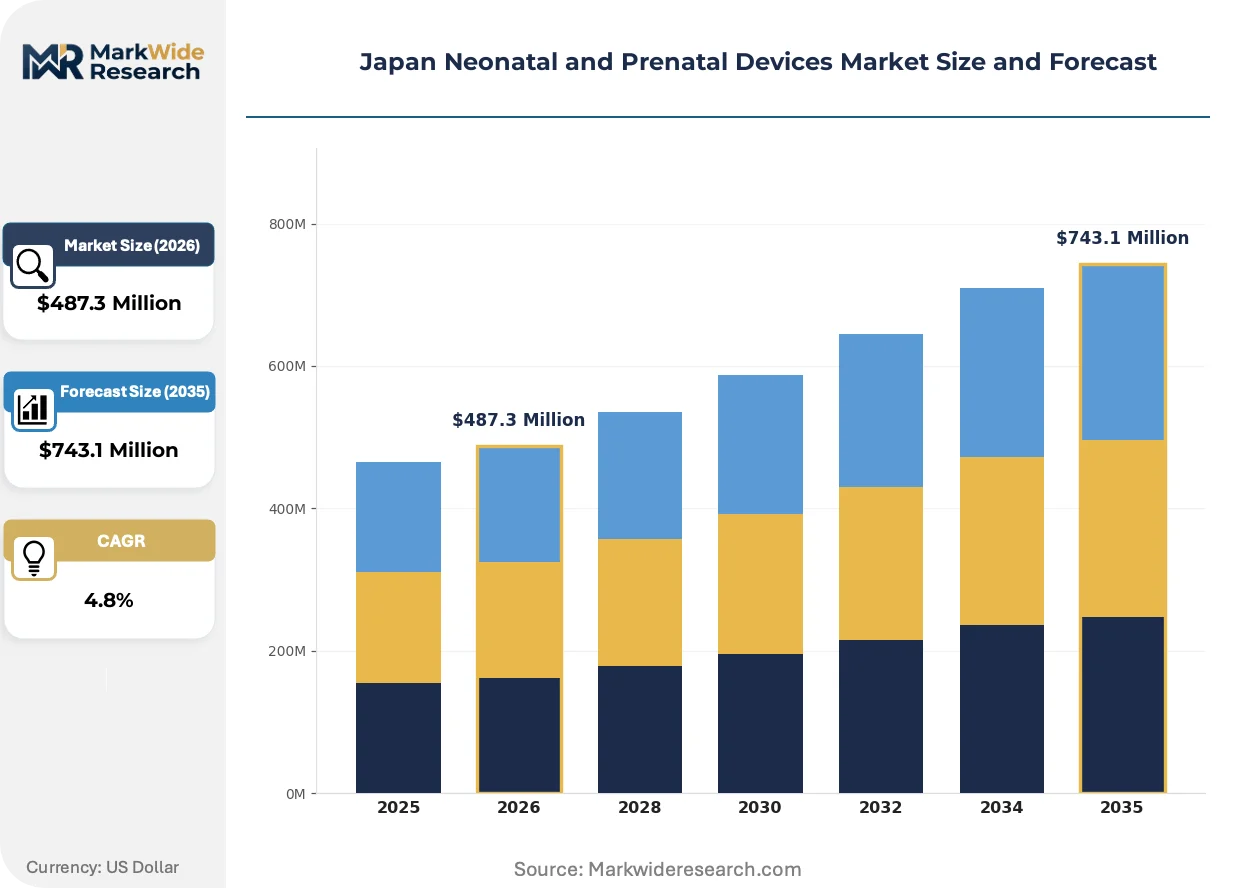
Equipment leasing and pay-per-use service models is reconfiguring capital deployment across Japan's maternity care infrastructure, lowering barriers for mid-sized clinics. Nihon Kohden Corporation leverages its domestic manufacturing footprint to sustain cost competitiveness against multinational suppliers. Koninklijke Philips N.V. anchors its position through intensive R&D collaboration with Japanese university hospitals. Atom Medical specializes in incubator systems designed for Japan's low-birth-weight infant protocols.
Neonatal and prenatal devices comprise diagnostic, monitoring, and therapeutic equipment engineered for fetal assessment and newborn critical care, typically operating within precision ranges of 0.1°C thermal stability and sub-millimeter ultrasound resolution. These systems serve to reduce perinatal mortality, manage preterm complications, and enable early congenital anomaly detection in clinical settings. Fetal monitors and incubators command the largest installed base across Japanese perinatal centers, while wireless monitoring and IoT integration segments attract disproportionate capital allocation as hospitals pursue remote telemetry and centralized nursery oversight. Digital imaging maintains stable replacement demand tied to PMDA-mandated safety inspection cycles.
PMDA enforces stringent quality management system requirements under the Pharmaceutical and Medical Device Act, compelling manufacturers to maintain Japan-specific technical documentation and post-market surveillance protocols. METI promotes domestic production of advanced medical devices through targeted industrial policy, indirectly shaping supplier location decisions and local content thresholds. Stakeholders must weigh regulatory compliance costs against the strategic imperative to capture volume in Japan's consolidating prefectural hospital networks.
Market Dynamics
Equipment leasing and pay-per-use service models is reconfiguring capital deployment across Japan's maternity care infrastructure, lowering barriers for mid-sized clinics while reshaping vendor-customer relationships.
Growth Catalysts
- Revised Pharmaceutical and Medical Device Act:PMDA streamlined approval pathways for Class II prenatal devices, compressing time-to-market for domestic and foreign manufacturers targeting Japanese perinatal centers.
- Wireless fetal monitoring systems:Metropolitan Tokyo hospitals are expanding adoption of remote telemetry platforms, driving replacement cycles in tertiary maternity centers.
- Kanto prefecture concentration:Tertiary maternity centers in this region generate disproportionate demand for high-acuity neonatal equipment, creating anchor demand for precision thermal stability systems.
Market Restraints
- PMDA quality management system requirements:Manufacturers must maintain Japan-specific technical documentation and post-market surveillance protocols, elevating fixed compliance costs for smaller suppliers.
- Domestic production concentration:METI's industrial policy promotes local manufacturing, indirectly raising local content thresholds that disadvantage pure importers.
- Precision engineering limitations:Sub-millimeter ultrasound resolution standards demand specialized component sourcing, constraining rapid scaling for non-specialized device makers.
Strategic Opportunities
- IoT integration segments:Wireless monitoring and centralized nursery oversight capabilities attract disproportionate capital allocation from prefectural hospital networks consolidating operations.
- Digital imaging replacement cycles:PMDA-mandated safety inspection cycles create predictable demand windows for ultrasound and imaging system vendors.
- Mid-sized clinic access:Pay-per-use service models unlock underpenetrated tier-two municipalities outside metropolitan Tokyo, extending equipment access without full capital commitment.
Industry Challenges
- Prefectural hospital network integration:Consolidating healthcare systems demand seamless interoperability with legacy monitoring infrastructure, complicating deployment timelines.
- Specialized technical talent scarcity:Precision thermal stability engineering and fetal signal processing expertise concentrates in established domestic manufacturers, constraining new entrant hiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Neonatal and Prenatal Devices Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, Fetal Monitors, Incubators, Resuscitation Devices Application: Prenatal Monitoring, Neonatal Care, Emergency Services, Diagnosis Technology: Digital Imaging, Wireless Monitoring, IoT Integration, Telemedicine End User: Hospitals, Clinics, Home Care, Research Institutes |
| Companies Covered | Atom Medical, Apel Co. Ltd., GE Healthcare, Masimo, Natus Medical, Koninklijke Philips N.V., Nihon Kohden Corporation, Canon Medical Systems Corporation, Terumo Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Neonatal and Prenatal Devices Market Shifts & Advancements
Wireless connectivity and cloud-based telemetry architectures are actively displacing wired bedside configurations across Japanese perinatal wards, with tertiary centers piloting centralized monitoring stations.
Artificial intelligence-enhanced fetal heart rate pattern recognition is digitizing diagnostic workflows in university-affiliated maternity hospitals. Clinicians at Keio University Hospital and similar institutions are integrating machine learning algorithms into existing monitoring platforms. This convergence is digitizing clinical decision support, reducing false-positive alert rates while compressing specialist review time.
PMDA's revised Pharmaceutical and Medical Device Act frameworks are accelerating Class II device registration timelines for wireless monitoring equipment. Domestic manufacturers leveraging existing quality management certifications gain first-mover advantage in prenatal telemetry. Foreign suppliers are responding by establishing Japan-specific technical documentation teams to capture volume in consolidating prefectural networks.
Leasing arrangements and managed service contracts are displacing outright equipment purchases among mid-sized maternity clinics. Device vendors are unbundling hardware from maintenance and software upgrade commitments. This shift is most visible in Osaka and Nagoya metropolitan clusters, where independent clinics face capital constraints amid regional hospital consolidation.
Japan Neonatal and Prenatal Devices Market Segmentation
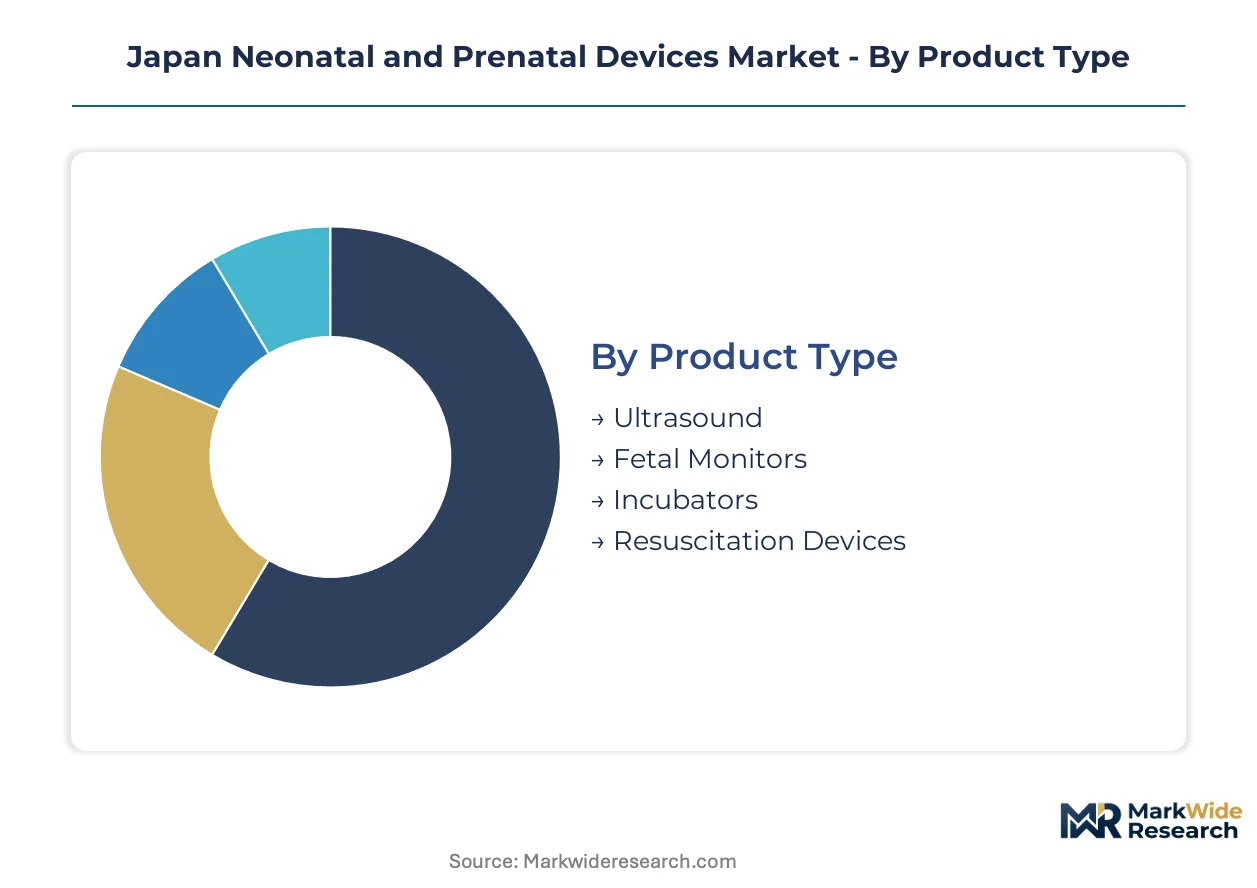
Segmentation in Japan's neonatal and prenatal devices market reveals distinct procurement rhythms across product categories, with replacement cycles varying from annual software upgrades to decade-long infrastructure investments. Understanding these temporal patterns enables suppliers to align inventory and service contracts with hospital capital planning cycles.
Product Type:
Fetal monitors and incubators turn over on 7-10 year cycles tied to PMDA safety inspection mandates, while ultrasound systems face more compressed 4-6 year refresh windows as imaging resolution standards advance.
- Fetal Monitors:Cardiotocography systems measuring fetal heart rate and uterine contractions with sub-beat precision. Demand concentrates in Tokyo Metropolitan tertiary centers where wireless telemetry upgrades are displacing wired bedside units under revised Pharmaceutical and Medical Device Act pathways.
- Incubators:Precision thermal regulation systems maintaining 0.1°C stability for low-birth-weight protocols. Kanto prefecture maternity centers anchor installed base expansion as regional networks consolidate neonatal intensive care capacity.
- Ultrasound:High-frequency transducer arrays enabling sub-millimeter resolution for congenital anomaly detection. Replacement demand tracks PMDA-mandated inspection cycles.
- Resuscitation Devices:Positive pressure ventilation and suction systems for delivery room emergency protocols. Mid-sized clinics in Osaka and Nagoya clusters access through pay-per-use leasing models.
Incubators anchor the volume base while wireless-enabled fetal monitors gain share at the steepest rate.
Application:
Cost tier differentiation separates high-acuity neonatal intensive care from routine prenatal screening, with emergency services commanding premium pricing for rapid-deployment configurations.
- Neonatal Care:Critical thermoregulation and respiratory support for preterm infants. Tertiary centers in Kanto prefecture drive specification requirements for precision thermal stability systems.
- Prenatal Monitoring:Continuous fetal assessment during gestation and labor. Wireless telemetry adoption is accelerating replacement cycles in university-affiliated hospitals.
- Emergency Services:Portable resuscitation and stabilization equipment for delivery room complications. Demand clusters in metropolitan Tokyo's consolidated perinatal networks.
- Diagnosis:Imaging and laboratory-based congenital anomaly detection. PMDA inspection mandates create predictable procurement windows.
Neonatal care absorbs the largest capital allocation while prenatal monitoring demonstrates the most rapid technology refresh trajectory.
Technology:
Application maturity separates established digital imaging from emerging IoT architectures, with integration complexity determining deployment timelines across prefectural hospital networks.
- Wireless Monitoring:Remote telemetry platforms enabling centralized nursery oversight. Tokyo Metropolitan hospitals are piloting cloud-based architectures that displace wired configurations.
- IoT Integration:Sensor networks connecting incubators, monitors, and clinical information systems. Prefectural network consolidation is driving interoperability investments.
- Digital Imaging:Ultrasound and MRI-based fetal assessment with machine learning-enhanced pattern recognition. Keio University Hospital and peer institutions anchor AI diagnostic workflow adoption.
- Telemedicine:Remote consultation platforms connecting regional clinics to tertiary specialists. METI industrial policy indirectly shapes local content requirements for system components.
Digital imaging maintains stable replacement demand while IoT integration climbs the fastest as networks consolidate operations.
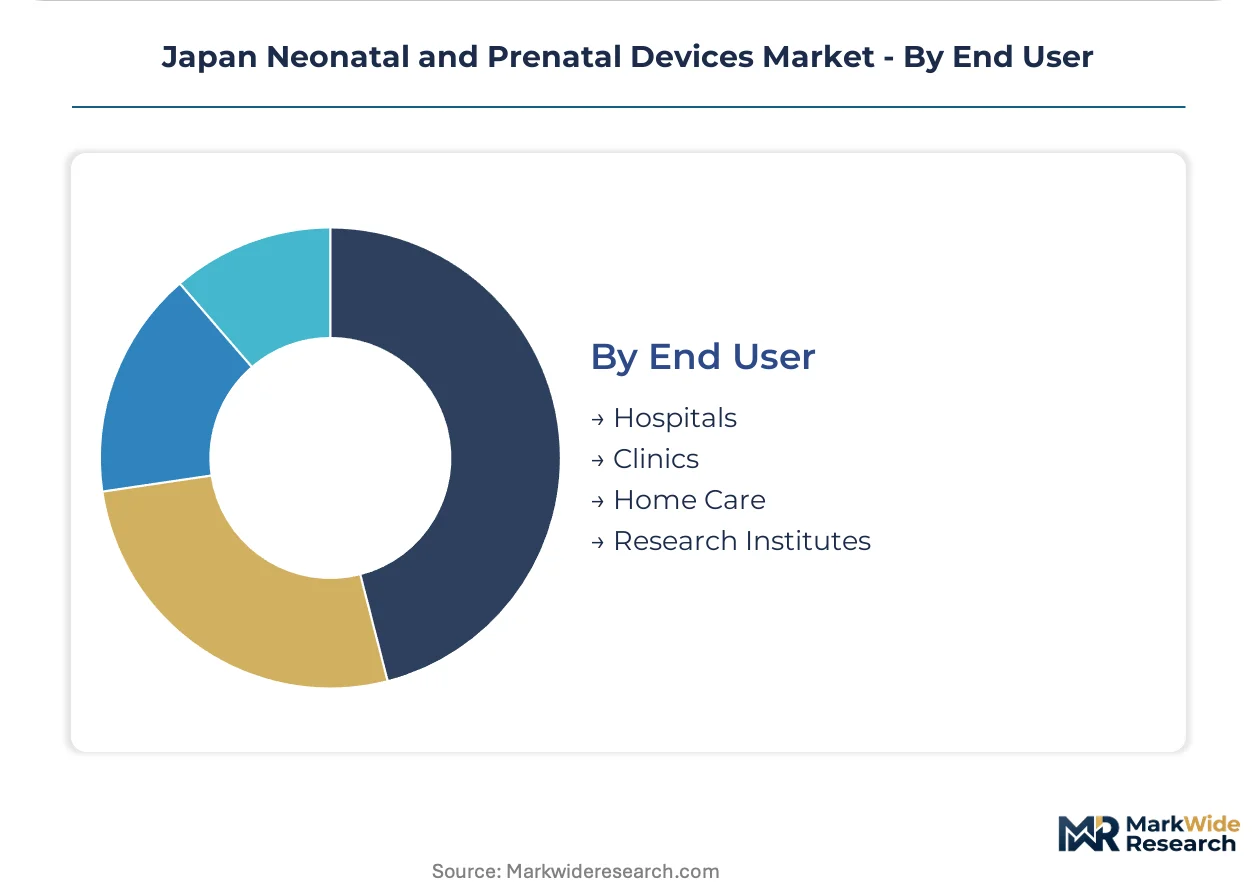
End User:
Customer type determines procurement modality, with capital-constrained clinics favoring service contracts over outright purchase.
- Hospitals:Tertiary perinatal centers with integrated neonatal intensive care units. Kanto prefecture networks generate anchor demand for high-acuity equipment configurations.
- Clinics:Independent maternity facilities in Osaka and Nagoya metropolitan clusters. Leasing arrangements are unlocking access to wireless monitoring without full capital commitment.
- Home Care:Limited direct equipment procurement; primarily consumables and remote consultation services. Penetration remains constrained by PMDA quality management documentation requirements.
- Research Institutes:University hospitals conducting fetal signal processing and thermal stability engineering studies. Collaboration agreements with domestic manufacturers concentrate technical talent.
Hospitals dominate absolute equipment volume while clinics are expanding most quickly through alternative financing structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto prefecture commands premium pricing power over Chubu and Kyushu regions, reflecting Tokyo Metropolitan tertiary centers' concentration of high-acuity neonatal intensive care capacity and their procurement leverage in wireless fetal monitoring systems.
Kanto/Tokyo
Metropolitan Tokyo hospitals anchor national demand for wireless fetal monitoring and precision thermal stability incubators, with Keio University Hospital piloting AI-enhanced diagnostic workflows. PMDA's streamlined Class II approval pathways under revised Pharmaceutical and Medical Device Act frameworks accelerate technology refresh cycles. Tertiary maternity centers in this cluster generate disproportionate capital allocation for IoT-integrated nursery oversight systems.
Kansai/Osaka
Independent maternity clinics in Osaka metropolitan clusters access neonatal equipment through pay-per-use leasing models rather than outright purchase. METI industrial policy promotes domestic manufacturing content thresholds that shape supplier location decisions. Regional hospital consolidation is driving interoperability demands for legacy monitoring infrastructure integration.
Chubu/Nagoya
Mid-sized clinics in Nagoya face capital constraints amid prefectural network consolidation, favoring managed service contracts over equipment ownership. PMDA quality management system requirements elevate compliance documentation burdens for non-specialized device vendors. The region's perinatal centers concentrate replacement demand around PMDA-mandated safety inspection cycles.
Kyushu
Regional clinics outside metropolitan cores exhibit underpenetrated demand for wireless telemetry platforms. METI's targeted industrial policy indirectly raises local content thresholds for system components. Fukuoka and surrounding prefectures represent expansion targets for pay-per-use service models lowering capital barriers.
Hokkaido
Remote perinatal facilities in northern prefectures drive telemedicine consultation platform adoption connecting regional clinics to Tokyo specialists. PMDA post-market surveillance protocols constrain rapid deployment of unproven monitoring architectures. Sapporo medical centers anchor demand for portable resuscitation equipment serving dispersed populations.
Japan Neonatal and Prenatal Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision thermal regulation modules and high-frequency transducer arrays. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with domestic manufacturing footprints, specialized neonatal equipment fabricators focused on low-birth-weight protocols, and imaging system providers leveraging university hospital R&D collaborations. Competitive maneuvering concentrates on M&A activity targeting wireless telemetry capabilities and strategic partnerships with prefectural hospital networks consolidating procurement authority.
Among Japan-based fabricators, Nihon Kohden Corporation and Atom Medical occupy positions reflecting distinct specialization vectors, while Koninklijke Philips N.V. represents the multinational platform integrator archetype competing through intensive R&D collaboration with Japanese university hospitals. These three entities exemplify how geographic origin and organizational structure map onto divergent competitive strategies in a market where METI industrial policy and PMDA regulatory frameworks shape supplier positioning.
| Leading Market Players |
|---|
| Atom Medical |
| Apel Co. Ltd. |
| GE Healthcare |
| Masimo |
| Natus Medical |
| Koninklijke Philips N.V. |
| Nihon Kohden Corporation |
| Canon Medical Systems Corporation |
| Terumo Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in precision thermal regulation component fabrication is compressing lead times for domestic incubator manufacturers while elevating pricing power among certified suppliers serving Kanto prefecture's tertiary maternity centers. PMDA-mandated quality management documentation requirements create natural supply segmentation that reinforces premium positioning for established fabricators against price-competitive importers.
Pricing Analysis
Customization-premium spreads separate configured-to-order wireless fetal monitoring systems from standard cardiotocography units by substantial margins. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling, with university-affiliated hospitals absorbing premium configurations while mid-sized clinics in Osaka and Nagoya clusters gravitate toward economy tiers under leasing arrangements. Price differentiation stems from METI-promoted local content thresholds and PMDA post-market surveillance protocol compliance costs. Pricing pressure runs through standard-tier incubators as domestic manufacturers expand capacity. Mid-sized clinics exhibit highest price sensitivity; Tokyo Metropolitan tertiary centers demonstrate lowest.
Supply Chain Analysis
Contract-manufacturing concentration for high-frequency ultrasound transducers rests with specialized Japanese electronics fabricators and select South Korean component specialists. Geographic supply concentration centers on Japan, South Korea, and Germany for precision thermal regulation modules, signal processing chipsets, and medical-grade sensor arrays. Raw material dependencies include rare-earth elements for transducer ceramics, medical-grade polymers for incubator housings, and specialized alloys for thermal regulation components. Single-source vulnerability constrains rapid scaling for wireless telemetry platforms. Distribution runs through authorized medical device distributors with PMDA-licensed quality management certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's neonatal and prenatal devices market presents a defensive-moat structure anchored in PMDA regulatory entrenchment, where quality management certification requirements create switching costs that protect incumbent positions against foreign challengers.
For Market Incumbents: Harden defensive positioning by deepening backward integration into precision thermal regulation module production and securing exclusive service contracts with consolidating prefectural hospital networks. Threat from AI-enhanced diagnostic workflow providers necessitates accelerated R&D collaboration with Keio University Hospital and peer institutions. Certification investment in revised Pharmaceutical and Medical Device Act pathways represents the critical lever for maintaining share against multinational platform integrators. For New Entrants and Emerging Players: Build out white-space presence in Kyushu and Hokkaido regional clinics where wireless telemetry penetration remains underdeveloped and pay-per-use service models unlock capital-constrained demand. Mid-sized municipalities outside metropolitan cores offer the most penetrable geography. Go-to-market execution should anchor on managed service contracts displacing outright equipment purchases. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among domestic manufacturers with established PMDA quality management certifications and long-term service agreements with prefectural networks. Long-term viability over the projection horizon favors platform integrators with wireless telemetry capabilities and university hospital R&D pipelines. Acquisition target archetype: specialized neonatal equipment fabricators with low-birth-weight protocol expertise. Signal to watch: consolidation velocity among prefectural hospital networks and associated procurement authority centralization.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Class II Streamlined Approval | Accelerates time-to-market for wireless fetal monitoring systems under revised Pharmaceutical and Medical Device Act frameworks. |
| University Hospital R&D Partnership | Secures access to AI-enhanced diagnostic workflow validation at Keio University Hospital and peer institutions. |
| Prefectural Network Consolidation Alliance | Captures anchor demand from Kanto prefecture tertiary maternity centers integrating IoT nursery oversight systems. |
| Pay-per-Use Service Model Expansion | Unlocks mid-sized clinic access in Osaka and Nagoya clusters without full capital commitment barriers. |
| Precision Component Backward Integration | Reduces dependency on single-source thermal regulation module suppliers and compresses cost structures. |
Research Methodology
The analysis maps fetal monitors, incubators, ultrasound systems, and resuscitation devices, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and PMDA regulatory affairs specialists. Primary interviews with device manufacturers and tertiary center clinicians combined with secondary validation from PMDA submission databases, hospital procurement records, METI industrial policy filings, and pharmaceutical and medical device trade association reports. Bottom-up installed base estimates and top-down market sizing triangulate volume and value outputs.
Assumptions held fixed include PMDA regulatory framework continuity, METI industrial policy trajectory, and prefectural hospital network consolidation velocity; variables included wireless telemetry adoption curves and AI diagnostic workflow penetration rates. Segmentation dimensions modeled encompass product type, application acuity tier, technology maturity, and end-user procurement modality across the projection horizon. CAGRs derive from replacement cycle analysis tied to PMDA-mandated safety inspection schedules and technology refresh patterns in university-affiliated hospitals.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by multinational platform integrators or accelerated AI diagnostic workflow deployment by emerging entrants would shift outcomes. Quarterly review of PMDA Class II approval timelines, prefectural network consolidation announcements, and wireless telemetry pilot program expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Preterm Birth Prevention and Management Market
Neonatal Care
United States Neonatal and Prenatal Devices Market
Neonatal Care
Infant Resuscitators Market
Neonatal Care
Neonatal Phototherapy Devices Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Infant Care Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Treatment Market