
 Sensor Based Smart Catheters Market | 2026-2036
Sensor Based Smart Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Sensor Based Smart Catheters Market Analytics
CE-marked and FDA-cleared performance tiers is collapsing into a single baseline as health systems demand simultaneous regulatory compliance across multiple jurisdictions. Abbott Laboratories leverages its vertically integrated sensor manufacturing to sustain price competitiveness in pressure monitoring platforms. Medtronic plc anchors its portfolio through geographic dominance in North American electrophysiology labs. Johnson & Johnson Services, Inc. differentiates via specialized catheter designs for complex cardiac ablation procedures.
Sensor based smart catheters integrate microelectromechanical systems, fiber-optic transducers, or conductive polymer elements into flexible polymer shafts to enable real-time physiological monitoring during minimally invasive procedures. These devices typically incorporate 2-12 French diameter profiles with sensor response times under 50 milliseconds, serving primarily to reduce procedural radiation exposure and enable closed-loop therapeutic adjustment. Optical sensor technology leads current revenue generation due to established fiber-optic manufacturing infrastructure and superior signal fidelity in blood-contact environments. Capacitive sensor platforms represent the fastest-expanding category as manufacturers achieve biocompatible dielectric coatings that withstand repeated sterilization cycles. Pressure monitoring catheters command concentrated margin pools because their disposable sensor tips create recurring revenue streams within integrated hospital supply chains.
FDA Class II device controls, EU MDR technical documentation requirements, and ISO 13485 quality management standards collectively elevate barriers for sensor-integrated catheter entrants by mandating biocompatibility validation and electromagnetic compatibility testing across full product families. Japan's PMDA and South Korea's MFDS impose additional clinical data requirements that fragment approval pathways and extend commercialization timelines for multinational manufacturers. Stakeholders must monitor evolving cybersecurity labeling requirements from FDA and analogous bodies, as connected sensor platforms attract heightened scrutiny over data integrity and patient safety interdependencies.
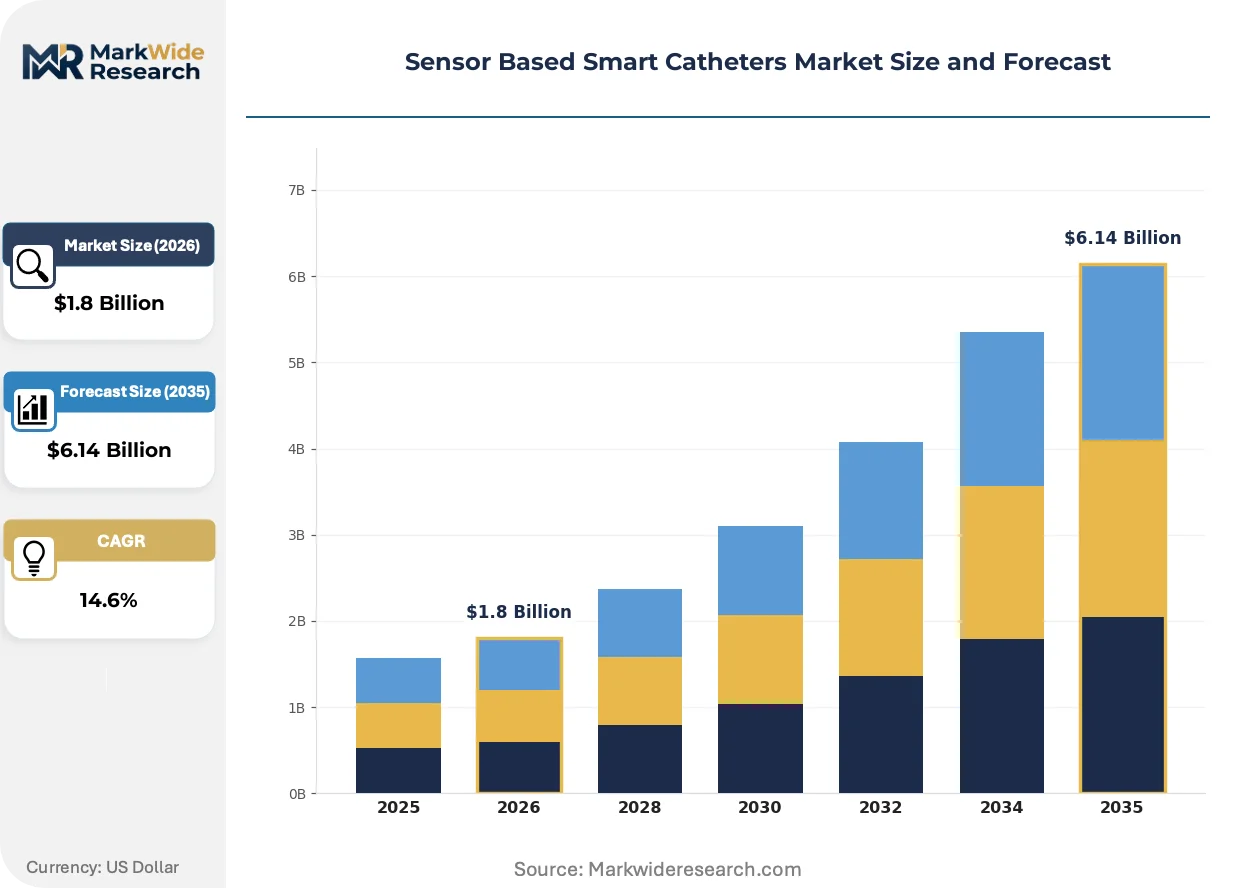
Market Dynamics
Integrated delivery networks in the United States are consolidating procurement around sensor-enabled interventional platforms, compressing vendor diversity and forcing catheter manufacturers to bundle hardware with data analytics services to retain hospital system contracts.
Growth Catalysts
- FDA Class II cybersecurity guidance refinement:Embedded sensor authentication protocols are becoming mandatory design requirements, accelerating replacement cycles for legacy catheter inventories across American electrophysiology labs.
- Capacitive sensor biocompatibility breakthroughs:Dielectric coatings that withstand repeated sterilization cycles are enabling closed-loop therapeutic adjustment in cardiac ablation procedures previously limited to optical platforms.
- Flow measurement catheter demand:Cardiology departments are expanding real-time hemodynamic assessment capabilities, creating pull-through revenue for pressure monitoring disposable tips within hospital supply chains.
Market Restraints
- EU MDR technical documentation burdens:Biocompatibility validation and electromagnetic compatibility testing requirements extend commercialization timelines and elevate fixed costs for sensor-integrated catheter families seeking CE marking.
- Optical fiber supply concentration:Superior signal fidelity in blood-contact environments depends on specialized fiber-optic manufacturing infrastructure concentrated among limited component suppliers.
- PMDA and MFDS clinical data fragmentation:Japan and South Korea impose non-harmonized approval pathways that duplicate testing expenditures and delay market entry for multinational manufacturers.
Strategic Opportunities
- Sensor-response time compression:Sub-50 millisecond physiological monitoring is decomposing the boundary between diagnostic and therapeutic catheter functions, enabling single-device procedure consolidation.
- Conductive polymer shaft integration:Flexible polymer substrates with embedded microelectromechanical systems are opening catheter diameter reduction pathways below 2 French for neurovascular access.
- ISO 13485 quality management certification:Quality system standardization creates arbitrage opportunities for contract manufacturers serving mid-tier device companies lacking in-house regulatory infrastructure.
Industry Challenges
- Cross-functional talent scarcity:Electrophysiologists with catheter engineering literacy and regulatory affairs specialists with ISO 13485 audit experience command premium compensation and extended recruitment cycles.
- Legacy sterilization validation:Gamma and ethylene oxide cycle confirmation for sensor-embedded polymers requires capital-intensive bioburden testing facilities with extended validation timelines.
- Data integrity architecture:Connected sensor platforms face heightened FDA scrutiny over patient safety interdependencies, forcing firmware security investments without immediate reimbursement capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensor Based Smart Catheters Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Catheters, Pressure Monitoring Catheters, Temperature Sensing Catheters, Flow Measurement Catheters Application: Cardiology, Urology, Neurology, Gastroenterology Technology: Optical Sensors, Ultrasonic Sensors, Electromagnetic Sensors, Capacitive Sensors End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Home Healthcare |
| Companies Covered | Abbott Laboratories, Johnson & Johnson Services, Inc., Medtronic plc, Becton, Dickinson and Company, Teleflex Incorporated, B. Braun Melsungen AG, ICU Medical, Inc., Biometrix, COOK Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensor Based Smart Catheters Market Evolving Landscape
Catheter sensor architectures are fragmenting across optical, capacitive, and conductive polymer pathways, with each technology stack attracting distinct end-use specializations and regulatory approval strategies.
Optical sensor technology is decomposing the traditional separation between imaging and therapeutic catheters by embedding fiber-optic transducers directly into ablation device tips. Electrophysiology labs in the United States are adopting these platforms at accelerated replacement cycles. The structural consequence is compression of standalone diagnostic catheter categories into multifunction therapeutic systems.
EU MDR requirements for electromagnetic compatibility testing are forcing sensor-integrated catheter manufacturers to redesign shielding architectures before CE marking renewal. Industrial consequence includes extended technical documentation timelines and elevated third-party notified body costs. Cardiology device portfolios with legacy sensor designs face the most acute compliance pressure and are responding with accelerated product family refreshes.
Hospital procurement committees are unbundling after-sales service contracts from hardware acquisition, compressing traditional vendor lock-in structures. Integrated delivery networks negotiate sensor calibration and data analytics separately from disposable catheter supply agreements. This behavioral shift is most visible in United States health systems with centralized supply chain governance and multi-hospital catheter standardization mandates.
Sensor Based Smart Catheters Market Segmentation
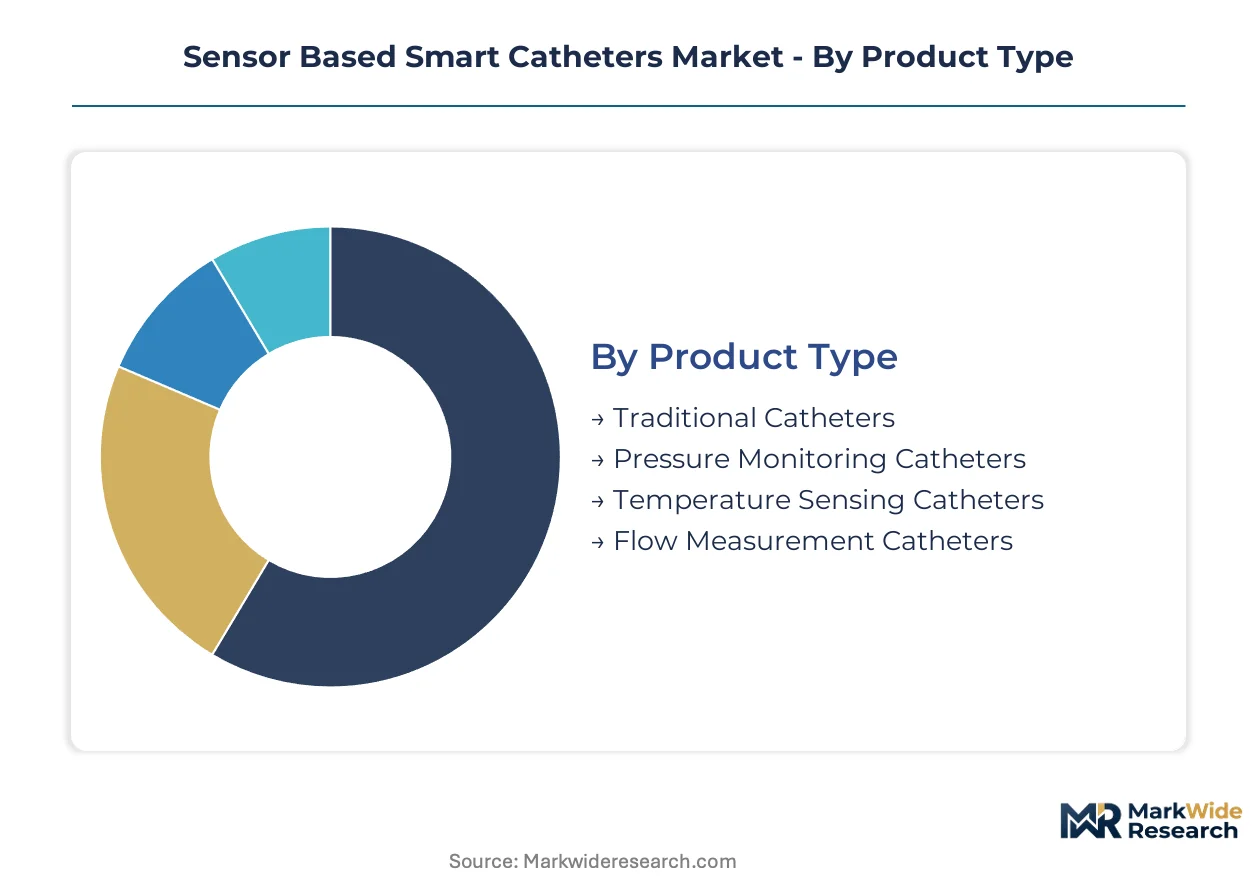
Sensor based smart catheters fragment across four distinct dimensions that shape procurement channels and reimbursement pathways. Product type determines disposable versus capital equipment purchasing models. Technology selection drives regulatory classification and sterilization validation requirements.
Product Type:
Channel mix splits between disposable single-use catheters flowing through hospital supply chains and capital-connected systems requiring direct manufacturer service contracts.
- Pressure Monitoring Catheters:Disposable sensor tips integrate fiber-optic or capacitive transducers into 2-12 French profiles for real-time hemodynamic assessment. Demand concentrates in United States integrated delivery networks consolidating procurement around sensor-enabled interventional platforms, driven by recurring revenue streams within hospital supply chains and FDA Class II cybersecurity guidance accelerating replacement cycles.
- Flow Measurement Catheters:These devices incorporate microelectromechanical systems or conductive polymer elements to enable closed-loop therapeutic adjustment during cardiac procedures. Cardiology departments in American hospital systems are expanding real-time hemodynamic capabilities, creating pull-through revenue for disposable tips and compressing vendor diversity through bundled data analytics contracts.
- Traditional Catheters:Standard polymer shafts without embedded sensor architectures serve baseline diagnostic functions across electrophysiology labs.
- Temperature Sensing Catheters:Thermocouple or thermistor-integrated designs monitor tissue temperature during ablation procedures.
By volume, Pressure Monitoring Catheters leads. By growth pace, Flow Measurement Catheters is ahead.
Application:
End-use concentration varies sharply by procedure reimbursement rates and catheter sophistication requirements, with cardiac applications commanding premium pricing tiers.
- Cardiology:Electrophysiology labs and interventional cardiology suites deploy pressure monitoring and flow measurement catheters for real-time hemodynamic assessment during ablation and structural heart procedures. United States health systems with centralized supply chain governance are standardizing sensor-enabled platforms across multi-hospital networks.
- Neurology:Neurovascular access demands sub-2 French diameter profiles with embedded microelectromechanical systems for minimally invasive intracranial navigation.
- Urology:Pressure and temperature sensing catheters serve diagnostic and therapeutic functions in endourological procedures.
- Gastroenterology:Sensor-integrated designs enable real-time physiological monitoring during endoscopic interventions.
Cardiology captures the dominant revenue share. Neurology shows the steepest expansion trajectory as catheter miniaturization enables previously inaccessible anatomical targets.
Technology:
Manufacturing infrastructure concentration and signal fidelity requirements create divergent margin structures across sensor architectures.
- Optical Sensors:Fiber-optic transducers embedded in catheter tips deliver superior signal fidelity in blood-contact environments through established manufacturing infrastructure. Revenue generation concentrates here due to proven biocompatibility and electromagnetic immunity, though supply concentration among limited component suppliers creates vulnerability.
- Capacitive Sensors:Biocompatible dielectric coatings now withstand repeated sterilization cycles, enabling closed-loop therapeutic adjustment in cardiac ablation previously limited to optical platforms. This category is expanding most quickly as manufacturers achieve ISO 13485-compliant quality systems for sensor-integrated catheter families.
- Ultrasonic Sensors:Piezoelectric elements enable flow measurement and tissue characterization through acoustic signal processing.
- Electromagnetic Sensors:Coil-based designs face heightened EU MDR electromagnetic compatibility testing requirements that extend technical documentation timelines.
Optical Sensors maintains installed base dominance. Capacitive Sensors is gaining share fastest through sterilization durability breakthroughs.
End User:
Procurement authority and reimbursement capture determine channel strategy, with consolidated health systems extracting maximum pricing leverage.
- Hospitals:Integrated delivery networks in the United States unbundle after-sales service contracts from hardware acquisition, negotiating sensor calibration and data analytics separately from disposable catheter supply agreements. Multi-hospital standardization mandates compress traditional vendor lock-in structures.
- Ambulatory Surgical Centers:These facilities prioritize cost-efficient sensor platforms with simplified calibration protocols for high-volume outpatient procedures.
- Diagnostic Laboratories:Specialized hemodynamic assessment centers require precision-calibrated pressure monitoring systems with documented traceability.
- Home Healthcare:Emerging remote monitoring applications face unresolved FDA cybersecurity labeling requirements for connected sensor platforms.
Hospitals dominate absolute volume. Home Healthcare presents the most uncertain regulatory pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in sensor-integrated catheters favor established manufacturing hubs with vertical component supply, while emerging markets absorb technology through licensing partnerships and localized assembly operations rather than indigenous production.
United States
Integrated delivery networks in Texas and the Northeast Corridor consolidate procurement around sensor-enabled interventional platforms, compressing vendor diversity through bundled data analytics contracts. FDA Class II cybersecurity guidance refinement accelerates replacement cycles for legacy catheter inventories across American electrophysiology labs. The Minneapolis-St. Paul medical device cluster anchors domestic manufacturing of pressure monitoring platforms with captive sensor fabrication.
Germany
Baden-Württemberg's precision engineering base supplies fiber-optic transducer components to catheter manufacturers serving European cardiology departments. EU MDR technical documentation requirements for electromagnetic compatibility testing extend commercialization timelines for sensor-integrated families seeking CE marking renewal. The Munich medical technology corridor concentrates sterilization validation facilities for gamma and ethylene oxide cycle confirmation.
Japan
PMDA clinical data requirements fragment approval pathways for multinational manufacturers, extending commercialization timelines beyond European and American benchmarks. METI funding programs support domestic development of sub-2 French neurovascular catheter miniaturization. The Kansai region's Osaka-Kobe medical device cluster specializes in biocompatible dielectric coating processes for capacitive sensor platforms.
China
NMPA regulatory pathways for Class II medical devices impose biocompatibility validation requirements that parallel FDA controls but with extended technical review periods. MIIT industrial policy directs domestic manufacturers toward optical sensor technology substitution for imported fiber-optic components. The Suzhou industrial park hosts contract manufacturers serving mid-tier device companies lacking in-house ISO 13485 quality management infrastructure.
South Korea
MFDS imposes non-harmonized clinical data requirements that duplicate testing expenditures for sensor-integrated catheter families. The national pharmaceutical regulator's cybersecurity labeling standards for connected platforms attract heightened scrutiny over data integrity. Seoul Capital Area medical device foundries concentrate on conductive polymer shaft integration for neurovascular access applications.
Sensor Based Smart Catheters Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates that leverage vertically integrated sensor manufacturing and established electrophysiology lab relationships. The vendor base organizes around three strategic archetypes: full-line manufacturers with captive component supply, specialized catheter engineering firms with regulatory affairs depth, and contract manufacturers with ISO 13485 certification arbitrage. Competitive moves center on portfolio diversification into data analytics services and geographic expansion through distributor acquisition rather than greenfield manufacturing.
Among diversified health technology conglomerates, Abbott Laboratories and Medtronic plc exemplify the integrated-manufacturing archetype, while Johnson & Johnson Services, Inc. occupies a position emphasizing specialized therapeutic applications. These three anchors represent distinct competitive vectors: sensor fabrication control, electrophysiology lab channel dominance, and complex procedure design differentiation.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Johnson & Johnson Services, Inc. |
| Medtronic plc |
| Becton, Dickinson and Company |
| Teleflex Incorporated |
| B. Braun Melsungen AG |
| ICU Medical, Inc. |
| Biometrix |
| COOK Medical |
| Others |
Value Network & Pricing Analysis
Scale economies in fiber-optic transducer fabrication concentrate manufacturing among German and Japanese precision engineering clusters, compressing price floors for optical sensor catheters while capacitive alternatives exploit dielectric coating breakthroughs to undercut established tiers. United States integrated delivery networks exploit this supplier concentration through consolidated procurement mandates that unbundle hardware from service contracts.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across sensor-integrated catheter families. Pricing stratifies across premium optical platforms with FDA Class II cybersecurity certification, standard capacitive systems with ISO 13485 validation, and economy conductive polymer shafts for high-volume ambulatory procedures. Cost compression in the standard tier is intensifying because dielectric coating sterilization durability is displacing optical signal fidelity as the dominant performance metric. Ambulatory surgical centers exhibit highest price sensitivity; electrophysiology labs with bundled data analytics contracts show lowest.
Supply Chain Analysis
Specialized fiber-optic preform manufacturing in Germany, Japan, and the United States creates single-source vulnerability for optical sensor catheter tip assemblies. Raw material dependencies center on high-purity silica fiber, biocompatible polyimide coatings, and platinum-iridium electrode alloys. Tariff exposure on Chinese-sourced conductive polymers is forcing catheter shaft manufacturers toward South Korean and domestic polymer compounders. Distribution runs through hospital supply chain consignment models with direct manufacturer service overlays for capital-connected pressure monitoring systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
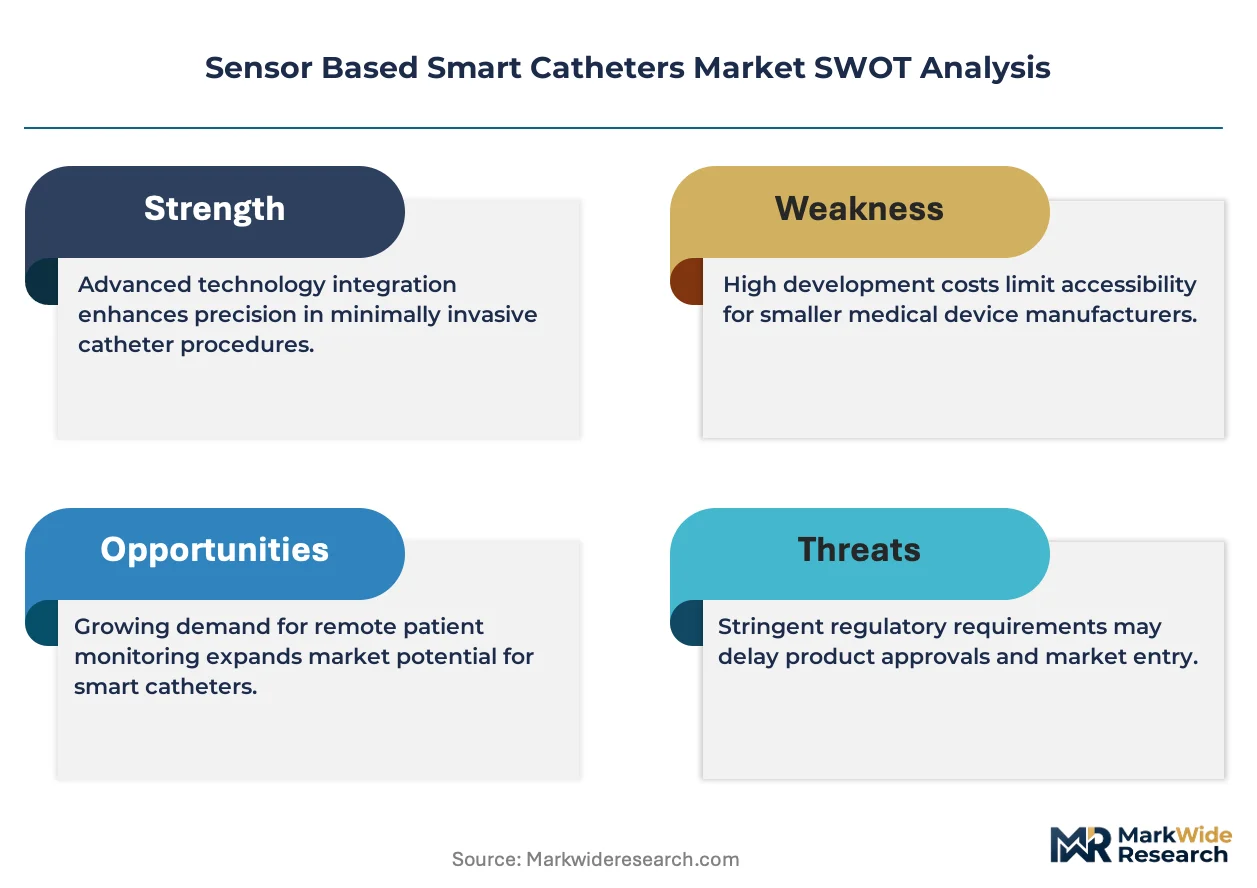
Fragmentation opportunity concentrates in mid-tier capacitive sensor platforms where ISO 13485 certification arbitrage attracts contract manufacturers lacking in-house regulatory infrastructure. Hospital procurement unbundling creates niche entry points for specialized data analytics providers.
For Market Incumbents: Compound channel control through captive sensor fabrication and exclusive electrophysiology lab service contracts. Acquire ISO 13485-certified contract manufacturers in the Minneapolis-St. Paul cluster to defend against capacitive sensor price erosion. Prioritize FDA cybersecurity guidance compliance as a renewal trigger for legacy optical platform replacement cycles. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany accelerates European market entry before PMDA clinical data requirements stall Japanese commercialization. Target neurovascular access applications with sub-2 French conductive polymer shafts where Abbott and Medtronic optical platforms retain premium positioning. Lead with simplified calibration protocols for ambulatory surgical center procurement committees. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized catheter engineering firms with regulatory affairs depth over diversified conglomerates facing portfolio refresh burdens. Five-to-ten year viability hinges on conductive polymer sterilization durability convergence with optical signal fidelity. Watch for FDA cybersecurity labeling finalization as inflection indicator for connected platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Quality System Certification | Contract manufacturers leverage certification arbitrage to serve mid-tier device companies lacking in-house regulatory infrastructure. |
| FDA Cybersecurity Submission Pathway | Embedded sensor authentication protocols accelerate replacement cycles for legacy catheter inventories across American electrophysiology labs. |
| Hospital System Partnership | Integrated delivery networks consolidate procurement around bundled data analytics contracts that compress traditional vendor lock-in structures. |
| CE Marking Renewal Redesign | EU MDR electromagnetic compatibility testing requirements force shielding architecture investments before technical documentation deadlines. |
| Software Companion Development | Real-time hemodynamic data platforms attract unbundled procurement negotiations separate from disposable catheter supply agreements. |
Research Methodology
Operator-level perspectives from electrophysiology lab directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract repositories, and ISO 13485 certification registries. Bottom-up catheter shipment estimates triangulated against top-down health system capital expenditure tracking.
Sensitivity analysis tested forecast outputs across sterilization cycle durability assumptions, cybersecurity compliance timeline scenarios, and integrated delivery network consolidation trajectories. Segmentation modeling spanned product type, sensor technology, application specialty, and end-user procurement authority across the projection horizon. CAGRs derived from procedure volume elasticity to catheter replacement rates and pricing tier migration patterns. Forecast inputs incorporated PMDA clinical data requirement timelines and NMPA technical review period benchmarks.
Underlying assumptions cover dielectric coating biocompatibility validation, electromagnetic compatibility test standardization, and cybersecurity protocol adoption curves, with deviation risk concentrated in FDA guidance finalization timing and EU notified body capacity constraints. Practitioners should keep alternative scenarios live as hospital procurement unbundling and capacitive sensor performance convergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
Global Capillary Blood Collection Devices Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Suction Catheters Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Global Scleral Lens Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Tracheobronchial Stent Grafts Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Global Implantable Drug Delivery Market