
 Global Bone Screw System Market | 2026-2036
Global Bone Screw System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bone Screw System Market Foresight
Market Context
Titanium alloys is rebalancing cost-performance tradeoffs as stainless steel retreats from premium fixation applications. Stryker Corporation leverages captive forging capacity to control alloy sourcing across its trauma portfolio. Zimmer Biomet Holdings, Inc. anchors North American distribution through direct hospital contracts and specialized sales forces. DePuy Synthes competes on instrumentation breadth, bundling screw systems with plating platforms.
Technical Definition and Segment Structure
A bone screw system comprises threaded metallic or polymeric implants paired with dedicated insertion instruments, designed to achieve compression or fixation in cortical or cancellous bone with torque tolerances typically exceeding 1.5 Nm. These systems serve orthopedic and trauma surgeons by stabilizing fractures, fusing joints, or anchoring spinal constructs until biological union occurs. Locking screws and cannulated screws command margin concentration due to their mechanical complexity and dependence on precision manufacturing, while bioabsorbable polymers in screw materials represent the fastest-expanding segment as surgeons seek to eliminate secondary removal procedures. Spinal fixation applications sustain premium pricing through regulatory burden and specialized training requirements, whereas trauma surgery volumes in ambulatory surgical centers are expanding access points for standardized screw configurations.
Regulatory Frame and Outlook
The FDA enforces 510(k) clearance pathways with escalating biocompatibility documentation under ISO 10993, while the EU Medical Device Regulation mandates notified body oversight and post-market surveillance for all implantable screw systems. Japan's PMDA imposes additional clinical data requirements that filter market entrants and sustain incumbent advantages. Stakeholders must monitor evolving sterilization validation standards and alloy traceability mandates as regulators tighten supply chain accountability for permanent implants.
Market Dynamics
EU MDR biocompatibility mandates are compressing supplier timelines and forcing alloy traceability investments across the orthopedic implant supply base.
Growth Catalysts
- Trauma Volume Expansion:Orthopedic clinics in the United States are scaling screw system inventories as emergency department fracture presentations rise and ambulatory surgical centers expand trauma capabilities.
- ISO 10993 Escalation:FDA clearance pathways now demand expanded biocompatibility documentation, filtering out undercapitalized entrants and concentrating procurement among validated manufacturers.
- Bioabsorbable Polymer Maturation:Polylactic acid and polyglycolic acid formulations are eliminating secondary removal surgeries, creating pull from pediatric and sports medicine specialties.
Market Restraints
- Titanium Alloy Cost Volatility:Sponge and mill product pricing fluctuations compress margin predictability for trauma screw producers dependent on Ti-6Al-4V ELI feedstock.
- PMDA Clinical Data Barriers:Japan's pharmaceutical and medical device agency imposes extended local trial requirements that extend market entry timelines beyond eighteen months.
- Stainless Steel Retreat:Nickel sensitivity concerns and inferior fatigue performance are displacing 316LVM from premium applications, stranding legacy tooling investments.
Strategic Opportunities
- Indian Orthopedic Expansion:CDSCO streamlined pathways for Class C implants and government hospital procurement reforms are opening access to a billion-patient fracture care market.
- Spinal Navigation Convergence:Robotic guidance systems and patient-specific screw trajectories are creating premium positioning for cannulated and fenestrated configurations.
- Bundled Instrumentation Contracts:Direct hospital partnerships covering screw systems, plating platforms, and single-use tool kits are displacing distributor intermediaries in North American health systems.
Industry Challenges
- Notified Body Bottlenecks:EU MDR designation shortages are extending certification timelines for implantable screw systems, freezing product launches and freezing revenue recognition.
- Precision Manufacturing Talent Scarcity:Swiss-type lathe programming and micro-thread grinding expertise are concentrating in aging workforces across Midwestern US medical device clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bone Screw System Market |
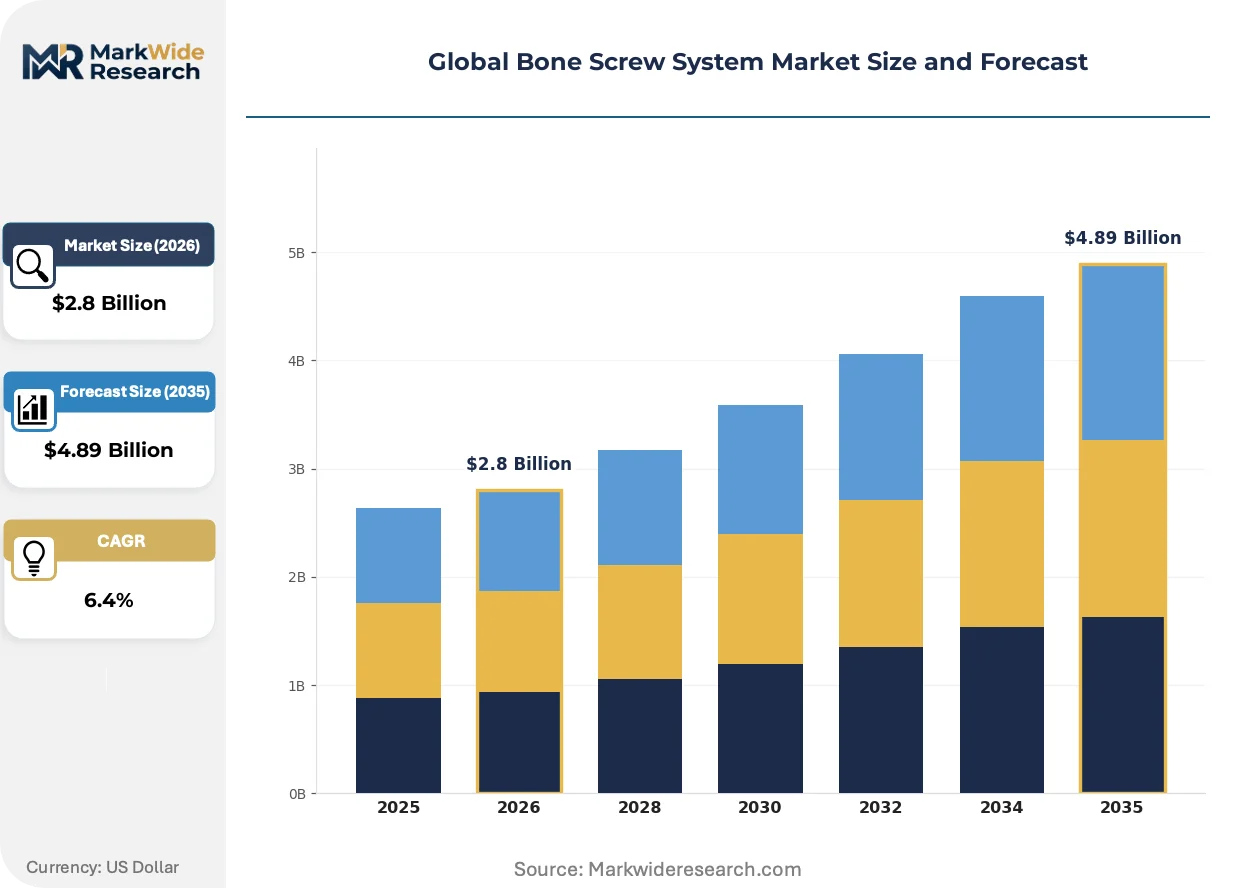
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cortical Screws, Cancellous Screws, Locking Screws, Cannulated Screws, Herbert Screws Application: Spinal Fixation, Fracture Fixation, Osteotomy, Arthrodesis, Trauma Surgery End User: Orthopedic Clinics, Trauma Centers, Rehabilitation Facilities, Ambulatory Surgical Centers Material: Titanium Alloys, Stainless Steel, Bioabsorbable Polymers, Cobalt-Chromium Alloys |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Inc., DePuy Synthes, Medtronic plc, Arthrex, Inc., Integra LifeSciences, Smith+Nephew, Acumed LLC, Orthofix US LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bone Screw System Market Shifts & Advancements
Additive manufacturing is disrupting traditional forging and machining workflows, enabling patient-specific geometries and lattice structures that were previously uneconomical at production scale.
Patient-matched screw trajectories derived from preoperative CT segmentation are overtaking standard anatomical plates in complex pelvic and acetabular fracture repair. Academic trauma centers in Germany and the Netherlands are adopting these workflows fastest, compressing operative time and reducing fluoroscopy exposure. The shift is forcing instrument manufacturers to integrate surgical planning software with mechanical insertion guides.
EU MDR post-market surveillance requirements now mandate systematic implant tracking and adverse event reporting across all member states. Manufacturers must maintain unique device identification registries and submit periodic safety update reports to notified bodies. Spinal fixation systems face the heaviest documentation burden, driving consolidation among mid-tier suppliers unable to sustain regulatory affairs headcount.
Hospital procurement committees are consolidating vendor relationships and demanding total cost-of-ownership guarantees spanning instrumentation, sterilization, and revision liability. United States health systems in Texas and Florida are piloting multi-year fixation contracts that bundle screw systems with plating platforms and dedicated case coverage. The model transfers inventory risk to manufacturers while locking in volume commitments.
Global Bone Screw System Market Segmentation
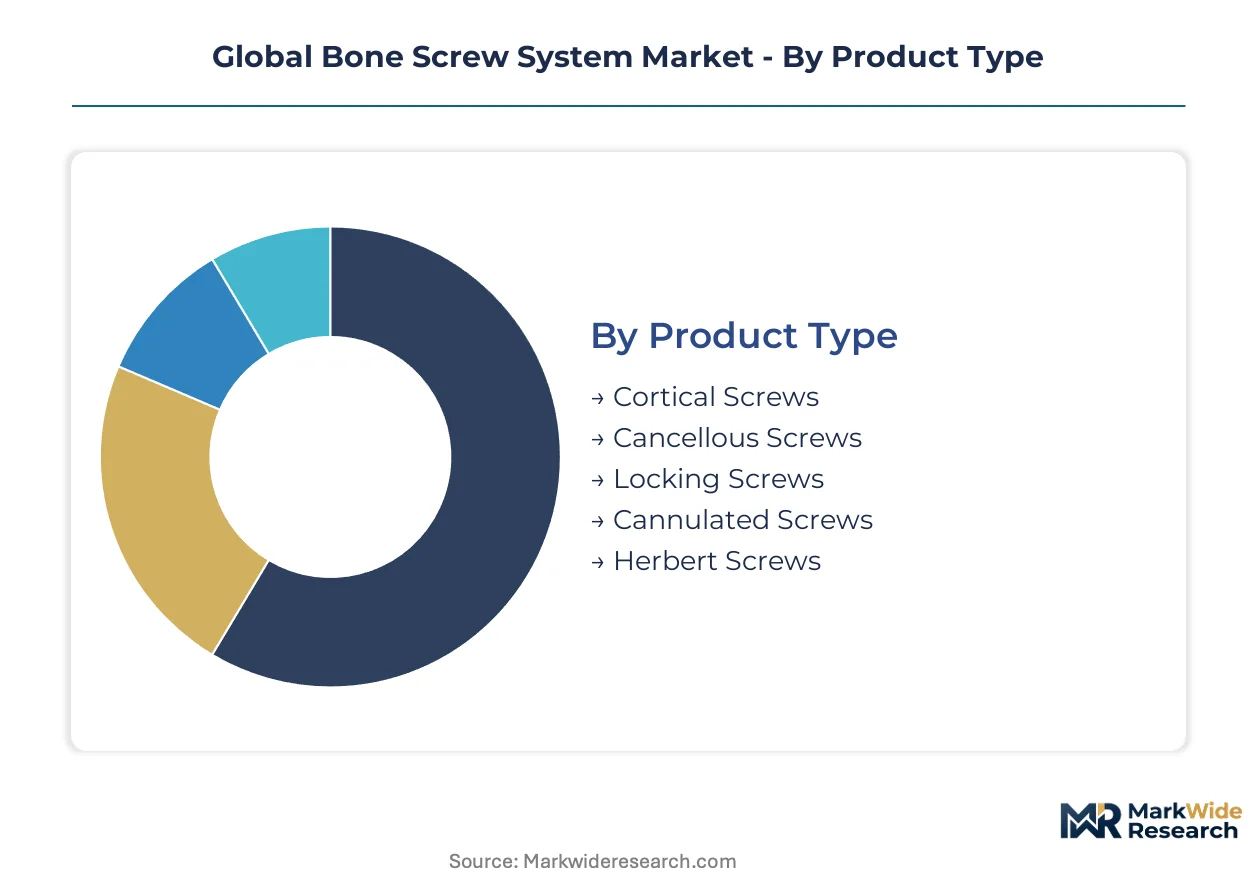
Bone screw system procurement diverges sharply by surgical setting and material specification, with reimbursement pathways and sterilization protocols driving distinct purchasing behaviors across patient populations. Manufacturers must align torque tolerances, alloy traceability, and instrumentation bundles to each segment's regulatory burden and case volume profile.
Product Type:
Surgeons select thread geometry and head design based on bone density, load-bearing requirements, and whether secondary removal is anticipated.
- Locking Screws:These implants combine threaded shafts with spherical heads that engage locking plates at fixed angles, eliminating micromotion in osteoporotic bone. Demand concentrates in German trauma centers where angular stability protocols dominate geriatric fracture care, constrained by the EU MDR's expanded biocompatibility documentation for permanent implants.
- Cannulated Screws:Hollow-core designs accommodate guidewires for percutaneous insertion, enabling minimally invasive trauma repair. Adoption is accelerating in United States ambulatory surgical centers where fluoroscopy-guided fixation reduces operative time and supports same-day discharge metrics.
- Cortical Screws:Fine-pitch threads maximize purchase in dense diaphyseal bone for fracture compression plating.
- Cancellous Screws:Aggressive thread profiles achieve fixation in porous metaphyseal bone common in periarticular injuries.
- Herbert Screws:Headless, differential-pitch designs permit compression across scaphoid and small bone fractures without prominent hardware.
Volume sits with cortical and cancellous configurations in high-throughput trauma; growth tilts toward locking and cannulated systems as minimally invasive techniques expand.
Application:
Reimbursement intensity and regulatory scrutiny separate high-complexity spinal constructs from standardized trauma fixation.
- Spinal Fixation:Pedicle screw systems anchor rods across multiple vertebral levels for deformity correction and fusion. Premium pricing persists in Japan where PMDA clinical data requirements filter market entrants and sustain incumbent advantages through extended surveillance obligations.
- Trauma Surgery:Emergency fracture stabilization drives highest absolute screw consumption across cortical, cancellous, and locking configurations. United States orthopedic clinics are scaling inventories as emergency department presentations rise and ambulatory centers expand after-hours trauma capabilities.
- Fracture Fixation:General orthopedic applications span plating and intramedullary nail adjuncts in long bone repair.
- Osteotomy:Corrective bone cuts in deformity reconstruction require precise screw trajectory planning and patient-specific guides.
- Arthrodesis:Joint fusion procedures in foot, ankle, and wrist applications demand low-profile screw designs.
Revenue concentrates in spinal fixation; trauma surgery delivers steepest expansion trajectory as point-of-care settings proliferate.
End User:
Capital equipment access and sterilization infrastructure determine whether facilities purchase comprehensive systems or single-use alternatives.
- Ambulatory Surgical Centers:These settings prioritize streamlined instrument sets and disposable tool kits to minimize reprocessing overhead. Texas and Florida health systems are piloting bundled contracts covering screw systems, plating platforms, and dedicated case coverage that transfer inventory risk to manufacturers.
- Orthopedic Clinics:Office-based surgical suites concentrate sports medicine and minor trauma volumes where local anesthesia and limited fluoroscopy suffice. Indian government hospital procurement reforms under CDSCO streamlined pathways are expanding access to standardized configurations.
- Trauma Centers:Level I facilities maintain comprehensive screw inventories for polytrauma and complex pelvic reconstruction.
- Rehabilitation Facilities:Post-acute settings deploy screws primarily for hardware removal and secondary procedures.
Procurement authority sits with hospital systems; volume expansion tilts toward ambulatory surgical centers as site-of-service migration accelerates.
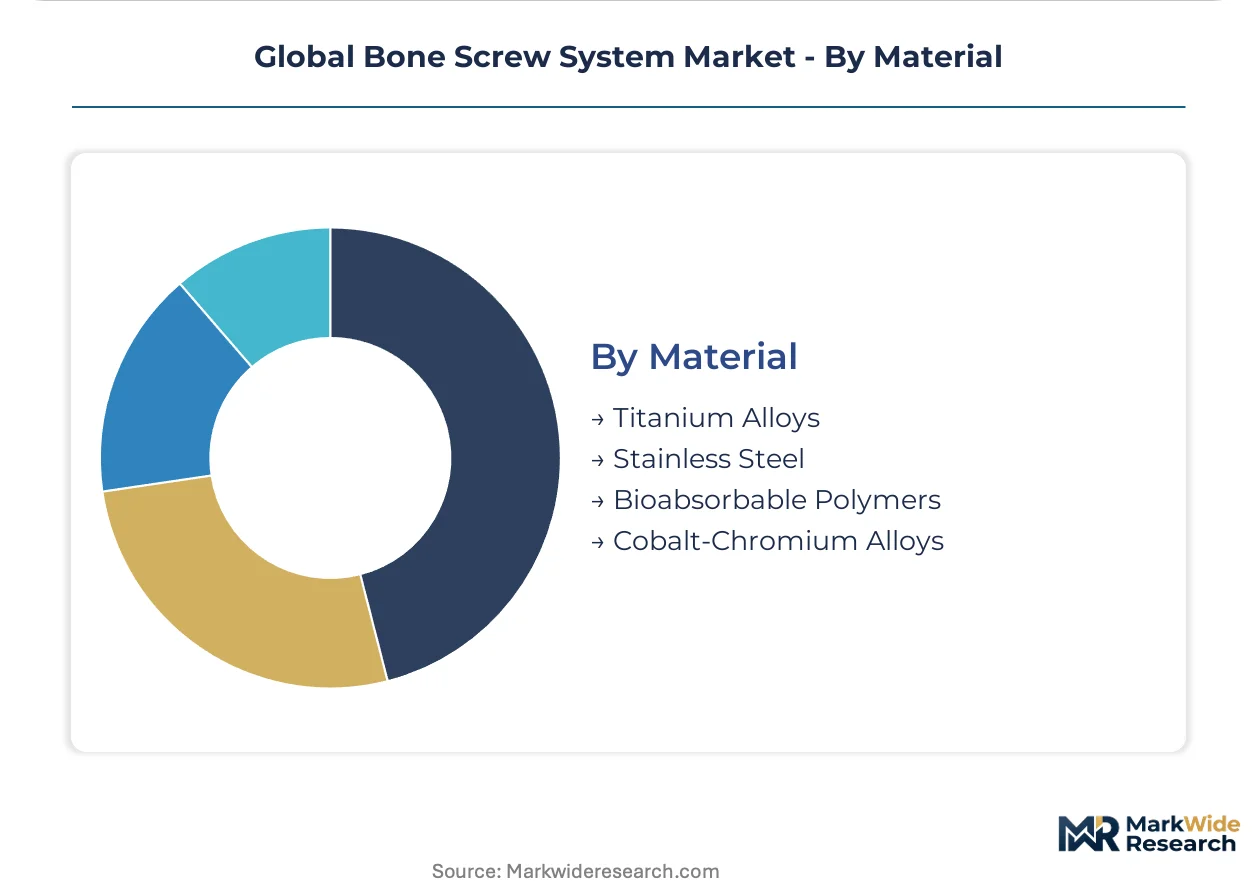
Material:
Biocompatibility certification grade and alloy sourcing traceability separate premium implant tiers from commodity alternatives.
- Titanium Alloys:Ti-6Al-4V ELI dominates permanent fixation due to favorable strength-to-weight ratio and osseointegration properties. Stryker Corporation leverages captive forging capacity to control alloy sourcing across trauma portfolios, insulating against sponge and mill product pricing fluctuations.
- Bioabsorbable Polymers:Polylactic acid and polyglycolic acid formulations eliminate secondary removal surgeries in pediatric and sports medicine applications. Academic centers in the Netherlands are adopting these fastest as polymer degradation profiles mature and mechanical strength approaches metallic equivalents.
- Stainless Steel:316LVM persists in temporary fixation and cost-sensitive markets despite nickel sensitivity concerns and inferior fatigue performance.
- Cobalt-Chromium Alloys:High modulus alternatives serve specialized applications requiring exceptional wear resistance.
Revenue share sits with titanium alloys; bioabsorbable polymers are gaining share fastest as elimination of revision procedures aligns with value-based care incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems concentrate the highest absolute demand for bone screw systems, with ambulatory surgical centers driving fastest volume expansion as site-of-service migration accelerates fracture care decentralization.
United States
Emergency department fracture presentations and ASC trauma capability upgrades are scaling screw system inventories across Texas and Florida health systems. FDA 510(k) clearance pathways with escalating ISO 10993 biocompatibility documentation are filtering undercapitalized entrants from premium fixation segments. The Midwestern medical device cluster spanning Ohio and Indiana maintains precision manufacturing expertise for Swiss-type lathe programming and micro-thread grinding.
Germany
Geriatric fracture care protocols emphasizing angular stability are concentrating demand for locking screw configurations in trauma centers across Bavaria and North Rhine-Westphalia. EU MDR notified body oversight and expanded post-market surveillance obligations are extending certification timelines for implantable systems. Academic trauma centers in Berlin and Hamburg are fastest to adopt patient-matched screw trajectories derived from preoperative CT segmentation.
Japan
PMDA clinical data requirements and extended local trial obligations are sustaining incumbent advantages through eighteen-month market entry barriers. Spinal fixation applications command premium pricing as deformity correction volumes rise in Kanto region metropolitan hospitals. The Nagoya medical device corridor concentrates precision forging capacity for Ti-6Al-4V ELI alloy sourcing.
India
CDSCO streamlined pathways for Class C implants and government hospital procurement reforms are opening access to standardized trauma configurations across Maharashtra and Gujarat. Nickel sensitivity concerns in pediatric populations are accelerating bioabsorbable polymer evaluation in Delhi-NCR academic centers. The Karnataka medical technology corridor near Bangalore is attracting contract manufacturing investments for cost-sensitive stainless steel alternatives.
Netherlands
Academic centers in Rotterdam and Utrecht are fastest to mature polylactic acid and polyglycolic acid degradation profiles for pediatric and sports medicine applications. EU MDR unique device identification registries and periodic safety update reporting are consolidating procurement among validated manufacturers. The Eindhoven medical technology cluster integrates surgical planning software with mechanical insertion guides for complex pelvic reconstruction.
Global Bone Screw System Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers invest in captive forging and precision machining to secure alloy traceability and insulate against titanium sponge pricing volatility. The vendor base concentrates around three strategic archetypes: diversified orthopedic conglomerates with direct hospital contracting capabilities, mid-tier trauma specialists competing on instrumentation breadth, and emerging polymer-focused innovators pursuing bioabsorbable elimination of secondary procedures. M&A activity and bundled instrumentation contracts represent the dominant competitive moves, with manufacturers acquiring precision machining assets and negotiating multi-year fixation agreements that transfer inventory risk while locking volume commitments.
Among diversified orthopedic conglomerates, Stryker Corporation, Zimmer Biomet Holdings, Inc., and DePuy Synthes exemplify distinct positioning archetypes. Stryker leverages its captive forging capacity to control Ti-6Al-4V ELI sourcing across trauma portfolios. Zimmer Biomet anchors North American distribution through direct hospital contracts and specialized sales force deployment. DePuy Synthes competes on instrumentation ecosystem breadth, representing the bundling strategy that pairs screw systems with plating platforms to displace distributor intermediaries in United States health systems.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| DePuy Synthes |
| Medtronic plc |
| Arthrex, Inc. |
| Integra LifeSciences |
| Smith+Nephew |
| Acumed LLC |
| Orthofix US LLC |
| Others |
Supply & Pricing Matrix
EU MDR post-market surveillance mandates and unique device identification registries gate qualified supply access and premium-tier pricing power, concentrating procurement among manufacturers sustaining regulatory affairs headcount while filtering mid-tier competitors from high-margin spinal fixation segments.
Pricing Analysis
Volume concentrates in standardized cortical and cancellous configurations for trauma surgery, while margins accrue to locking and cannulated systems serving minimally invasive techniques. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared titanium alloy systems from CE-marked alternatives and cost-sensitive stainless steel configurations. Cost compression in economy tiers intensifies as Indian contract manufacturers scale stainless steel production for government hospital procurement. Ambulatory surgical centers exhibit highest price sensitivity due to bundled contract pressures, whereas academic trauma centers prioritize mechanical performance over unit cost.
Supply Chain Analysis
Reverse logistics flows for explanted hardware and instrument refurbishment programs are emerging as supply chain differentiators as EU MDR mandates systematic implant tracking and adverse event reporting. Feedstock concentration rests in the United States for Ti-6Al-4V ELI sponge, Germany for precision forging capacity, and Japan for high-purity mill products. Raw material dependencies center on titanium sponge, surgical-grade stainless steel, and polylactic acid polymer feedstocks. Single-source vulnerability in Swiss-type lathe programming expertise across Midwestern medical device clusters threatens production continuity. Distribution runs through direct hospital contracts displacing distributor intermediaries in North American health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR notified body oversight and ISO 10993 biocompatibility escalation create barrier-to-entry moats favoring validated incumbents with sustained regulatory investment capacity.
For Market Incumbents: Extend captive forging capacity into titanium alloy sourcing to insulate against sponge pricing volatility and secure traceability documentation for EU MDR compliance. Fortify direct hospital contracting positions in Texas and Florida health systems before bundled instrumentation agreements lock in competitor volume commitments. Prioritize precision manufacturing talent acquisition in Ohio and Indiana clusters to offset aging workforce concentration in Swiss-type lathe programming. For New Entrants and Emerging Players: Ambulatory surgical centers seeking streamlined instrument sets represent the most penetrable buyer archetype for bioabsorbable polymer configurations eliminating secondary removal procedures. CDSCO streamlined pathways for Class C implants open access to Indian government hospital procurement reforms across Maharashtra and Gujarat. Lead with disposable tool kit offerings minimizing reprocessing overhead rather than competing on comprehensive system breadth. For Investors and Strategic Acquirers: Consolidation among mid-tier suppliers unable to sustain EU MDR regulatory affairs headcount is the leading indicator that acquisition opportunities are materializing in the spinal fixation segment. Five-to-ten year viability favors precision machining assets with established notified body relationships and captive alloy sourcing. Monitor notified body designation shortages as the signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Investment | EU MDR certification timelines determine market access velocity for implantable systems. |
| Captive Titanium Alloy Forging | Stryker's upstream control insulates trauma portfolios from sponge pricing fluctuations. |
| Bioabsorbable Polymer R&D Partnership | Academic centers in Rotterdam and Utrecht validate degradation profiles for pediatric applications. |
| Direct Hospital System Contracting | Texas and Florida health systems pilot multi-year bundled fixation agreements. |
| Surgical Planning Software Integration | Berlin and Hamburg trauma centers adopt patient-matched screw trajectories fastest. |
Research Methodology
FDA 510(k) clearance databases, EU MDR notified body submission records, and hospital procurement contract registries formed the secondary backbone, cross-referenced against primary interviews with orthopedic trauma surgeons, biomedical engineers, GPO contracts managers, and precision manufacturing plant managers. Bottom-up triangulation across screw system shipment data and top-down validation against health system capital expenditure disclosures anchored volume estimates.
Historical trendline analysis of trauma surgery volumes, spinal fusion procedure rates, and ambulatory surgical center expansion patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end-user setting, material specification, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted procedure growth projections and reimbursement pathway evolution, incorporating titanium alloy cost volatility and bioabsorbable polymer adoption curves as industry-specific forecast inputs.
Revisions become necessary when notified body designation shortages intensify, titanium sponge pricing experiences sustained volatility, or bioabsorbable polymer mechanical performance achieves parity with metallic equivalents. Practitioners should monitor EU MDR periodic safety update report submission rates and CDSCO Class C implant approval velocities for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Global Positive Airway Pressure Devices Market
Medical Devices
Retinal Surgery Devices Market
Medical Devices
Digital Medical Thermometers Market
Medical Devices
Global IVF Devices Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
Global Medical Implants Market
Medical Devices
Global Chemotherapy Devices Market
Medical Devices
Medical Device Films Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
Coronary Guidewires Market