
 United States Contraceptive Devices Market | 2026-2036
United States Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Contraceptive Devices Market Analytics
Long-acting reversible contraceptive placement services is reshaping margin distribution across the United States contraceptive devices landscape, pulling value from commodity condom sales toward clinical administration and device insertion protocols. Bayer AG leverages its vertical integration across hormone synthesis and polymer engineering to sustain manufacturing scale for intrauterine systems. CooperSurgical, Inc. anchors its position through specialized channel control over OB-GYN office and ambulatory surgery center networks. Church & Dwight Co., Inc. competes in retail pharmacy and e-commerce channels with differentiated brand strength in over-the-counter barrier methods.
Contraceptive devices encompass engineered products designed to prevent pregnancy through mechanical barrier, hormonal modulation, or copper-ion interference with sperm function, typically incorporating medical-grade silicone, polyethylene, or elastomer substrates manufactured under ISO 13485 quality systems for implantation or insertion into human tissue. Their primary commercial purpose centers on providing reversible fertility management through clinician-administered or patient-directed application. Hormonal intrauterine devices occupy the deepest margin pools due to multi-year efficacy windows and recurring replacement cycles, while non-hormonal copper IUDs attract price-sensitive segments through extended duration without hormone-related side effects. Condoms remain the most mature category with volume concentration in retail and direct-to-consumer channels, though diaphragm demand has contracted with shifting patient preference toward lower-maintenance alternatives.
FDA 510(k) clearance requirements and EPA environmental compliance standards for copper extraction govern device safety, efficacy claims, and material sourcing across the United States market, with state-level Medicaid formulary decisions further conditioning reimbursement access and provider prescribing behavior. The Department of Health and Human Services contraceptive coverage mandates under the Affordable Care Act shape commercial insurance payment flows and patient out-of-pocket exposure. Stakeholders must monitor evolving judicial interpretations of federal funding restrictions on specific device categories and their cascading effects on state procurement budgets and clinic inventory planning.
Market Dynamics
Medicaid expansion dynamics across Texas, California, and Florida are concentrating procurement volumes for long-acting reversible contraceptives, pulling patient flow toward clinic-based insertion services and away from retail pharmacy channels.
Growth Catalysts
- FDA 510(k) Acceleration:The FDA premarket notification pathway for novel hormone-eluting intrauterine systems compresses clearance timelines from 18 months to under 12 months. Device manufacturers file abbreviated submissions leveraging predicate device equivalence.
- Clinic Network Expansion:Hospital systems in Texas and Florida are adding dedicated LARC placement suites to capture Medicaid reimbursement. Ambulatory surgery centers deploy same-day insertion protocols.
- Copper Extraction Standards:EPA environmental compliance mandates for copper sourcing in non-hormonal IUDs favor domestic smelters with ISO 13485-certified supply chains. Texas-based polymer engineering firms secure long-term material contracts.
Market Restraints
- Medicaid Formulary Fragmentation:State-level reimbursement decisions in non-expansion states create prescribing uncertainty. Clinics in Georgia and Alabama face 90-day prior authorization delays for hormonal IUDs.
- Silicone Supply Concentration:Medical-grade silicone precursor production clusters in Louisiana and Ohio chemical corridors. Hurricane disruptions to Gulf Coast refineries spike elastomer input costs by double-digit percentages.
- Copper Price Volatility:Chilean concentrate supply interruptions transmit directly to copper IUD manufacturing costs. Domestic wire drawing capacity cannot absorb raw material spikes without margin compression.
Strategic Opportunities
- Telehealth-Enabled Counseling:Virtual pre-insertion consultations expand access in rural Texas counties lacking OB-GYN density. Remote patient monitoring platforms reduce no-show rates for scheduled placement appointments.
- Biodegradable Polymer R&D:Polylactic acid frame materials eliminate extraction procedures for hormone-free devices. Michigan polymer research institutes partner with Minnesota medical device incubators on prototype validation.
- Affordable Care Act Coverage Mandates:Department of Health and Human Services contraceptive coverage requirements eliminate patient cost-sharing for FDA-approved methods. Commercial insurers in California must reimburse clinic administration fees without copay.
Industry Challenges
- Specialized Insertion Training:Clinician certification for difficult-placement protocols requires 40-hour continuing medical education modules. Rural health centers in Florida struggle to retain staff through recertification cycles.
- Legacy EHR Integration:Clinic inventory management systems lack real-time connectivity to state Medicaid eligibility databases. Front-desk staff manually verify coverage before device dispensing.
- Device Retrieval Complexity:Embedded IUD extraction demands hysteroscopic equipment unavailable in 30% of community health centers. Referral networks to tertiary facilities extend resolution timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Contraceptive Devices Market |
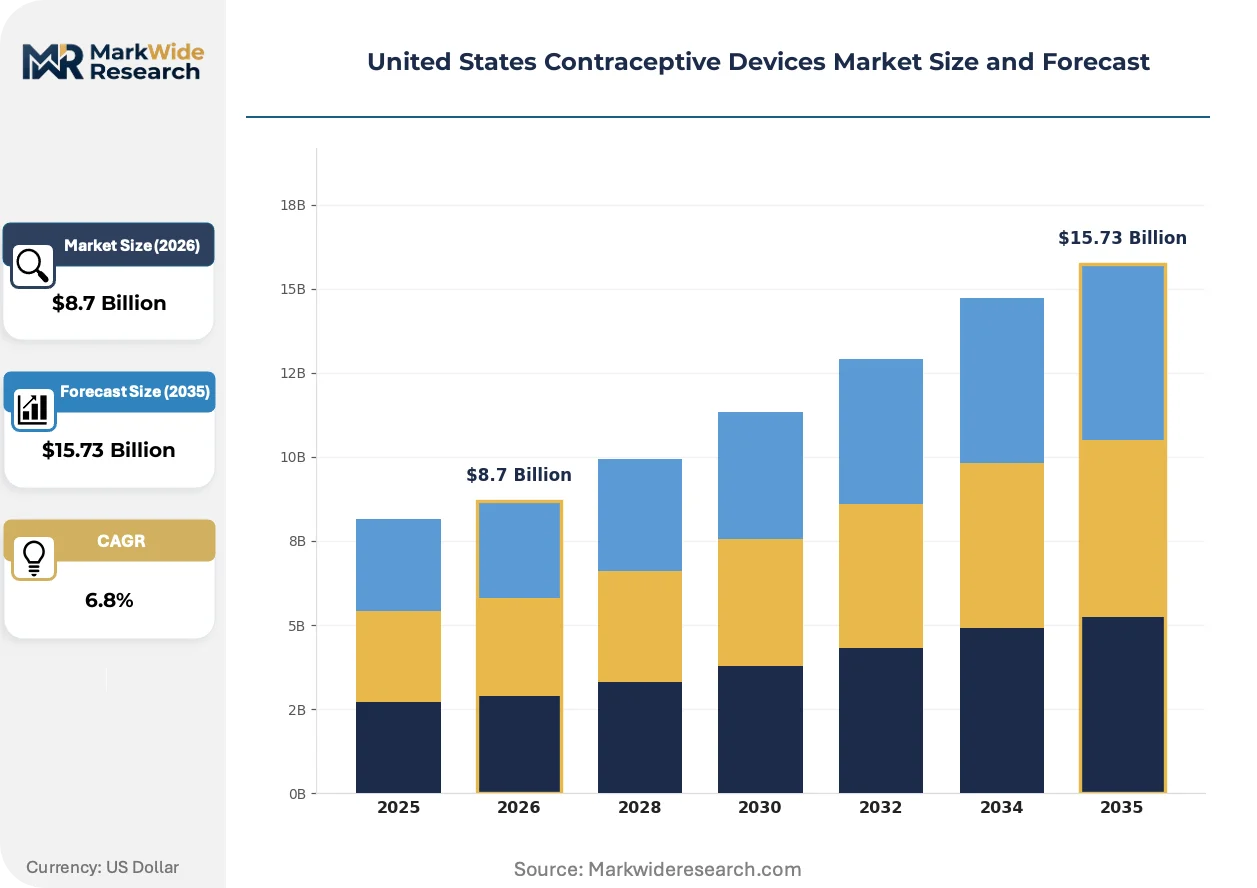
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IUD, Implant, Condom, Diaphragm End User: Women, Clinics, Hospitals, Pharmacies Delivery Mode: Intravaginal, Transdermal, Oral, Injection Content Type: Hormonal, Non-Hormonal, Natural, Others |
| Companies Covered | Bayer AG, CooperSurgical, Inc., Merck & Co., Inc., Church & Dwight Co., Inc., Reckitt Benckiser Group plc, Teva Pharmaceutical Industries Ltd, Pfizer Inc., The Cooper Companies, AbbVie, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Contraceptive Devices Market Evolving Landscape
Biodegradable frame materials and telehealth-integrated care pathways are restructuring how contraceptive devices reach patients, collapsing traditional distinctions between clinical and consumer channels.
Frameless intrauterine systems utilizing nitinol shape-memory alloy are collapsing the distinction between hormonal and non-hormonal device categories. OB-GYN practices in metropolitan California adopt these platforms for patients with silicone hypersensitivity. The technology compresses manufacturing complexity by eliminating polymer T-frame molding requirements.
EPA copper extraction standards under the Toxic Substances Control Act now mandate closed-loop wastewater recovery for IUD manufacturing facilities. Domestic smelters in Arizona and Utah invest in zero-discharge electrolytic refining to maintain medical-grade certification. Copper IUD producers source exclusively from EPA-compliant suppliers to avoid batch rejection.
Patients in Texas Medicaid expansion counties now initiate device selection through state health department portals before clinic contact. This digital triage displaces traditional physician-directed counseling models. Urban hospital networks capture these pre-qualified patients through centralized scheduling platforms.
United States Contraceptive Devices Market Segmentation
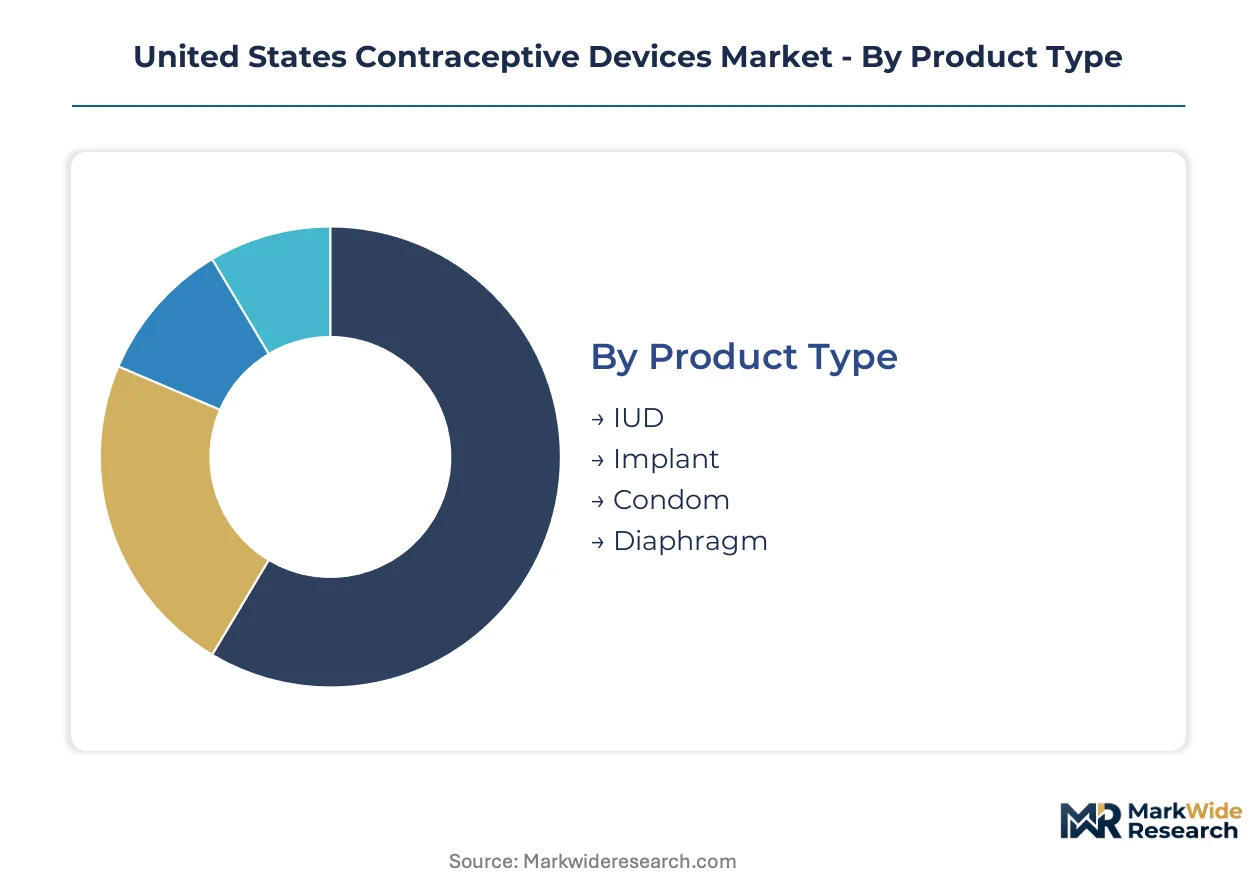
Contraceptive device segmentation in the United States reveals how clinical administration requirements, reimbursement pathways, and patient self-direction split procurement across institutional and retail channels. Understanding these divisions exposes where margin pools concentrate and which access barriers persist.
Product Type:
Product categories span clinician-administered long-acting methods through patient-directed barrier approaches, each carrying distinct placement protocols and replacement economics.
- IUD:Intrauterine devices deploy hormone-eluting or copper-ion mechanisms within the uterine cavity, requiring speculum-based insertion by certified providers. Demand concentrates in Texas and California Medicaid expansion counties where clinic networks capture reimbursement for placement and follow-up services. FDA 510(k) pathways for novel frame designs are compressing clearance timelines below twelve months.
- Implant:Subdermal rods release progestin through polymer matrices inserted beneath the upper arm skin, delivering multi-year efficacy with single-point administration. Hospital systems in Florida are adding dedicated implant suites to capture same-day procedure volumes from patients pre-qualified through state health department portals.
- Condom:Barrier sheaths manufactured from medical-grade latex or synthetic elastomers prevent sperm transmission through physical occlusion. Retail pharmacy and direct-to-consumer channels dominate procurement.
- Diaphragm:Dome-shaped silicone barriers require spermicide co-application and patient-fitting protocols, with demand contracting as lower-maintenance alternatives expand availability.
The dominant share belongs to IUD, while Implant is closing the gap fastest.
End User:
Procurement authority splits between patient-directed purchasing and institutional acquisition governed by formulary committees and reimbursement contracts.
- Women:Individual patients exercising direct purchasing power through retail pharmacy counters, e-commerce platforms, and over-the-counter channels for non-prescription methods. Out-of-pocket exposure varies by insurance coverage status under Affordable Care Act mandates.
- Clinics:Community health centers and reproductive health clinics in Texas, California, and Florida anchor long-acting reversible contraceptive placement volumes. Medicaid reimbursement rates condition device selection and inventory depth.
- Hospitals:Acute care systems and ambulatory surgery centers deploy operating-room and procedure-suite infrastructure for complex insertions and embedded device extractions. OB-GYN department purchasing committees negotiate manufacturer contracts.
- Pharmacies:Retail chains and independent dispensaries manage condom and emergency contraceptive stock-to-shelf ratios, with CVS and Walgreens capturing volume through private-label and national brand placement.
Clinics command the largest procurement volume, though Hospital purchasing is expanding most quickly through integrated delivery network consolidation.
Delivery Mode:
Physical administration pathways determine whether device utilization requires clinical infrastructure or permits patient self-management.
- Intravaginal:Devices inserted through the vaginal canal include diaphragms, cervical caps, and female condoms, with some hormone-releasing rings permitting patient self-placement after initial fitting. This mode spans clinical and retail channels depending on prescription status.
- Transdermal:Hormone delivery through adhesive patches applied to skin surfaces bypasses gastrointestinal metabolism, though patches themselves fall outside mechanical contraceptive classification and compete for patient mindshare.
- Oral:Daily hormone tablets represent pharmaceutical rather than device categories, yet patient overlap and switching behavior create competitive reference points for long-acting method counseling.
- Injection:Depot medroxyprogesterone acetate administered intramuscularly every three months requires clinical contact, bridging gap between daily compliance burden and multi-year implant or IUD commitment.
Intravaginal methods retain the widest patient access, while Injection delivery is gaining share fastest among patients transitioning from oral compliance routines.
Content Type:
Active ingredient classification separates hormone-modulating approaches from physical and behavioral alternatives, driving side-effect trade-offs and contraindication profiles.
- Hormonal:Progestin or estrogen-progestin combinations suppress ovulation and thicken cervical mucus, delivered through IUD, implant, patch, or ring mechanisms. Texas and California Medicaid formularies favor these methods for their superior efficacy metrics in quality reporting programs.
- Non-Hormonal:Copper IUDs leverage ionic sperm immobilization without endocrine disruption, attracting patients with hormone sensitivity or contraindications. EPA copper extraction standards now mandate closed-loop wastewater recovery for domestic manufacturing.
- Natural:Fertility awareness and behavioral methods rely on cycle tracking and abstinence timing, carrying no device cost but demanding sustained patient engagement and education support.
- Others:Emerging categories including pH-modulating gels and novel barrier chemistries occupy pre-commercial or limited-distribution status.
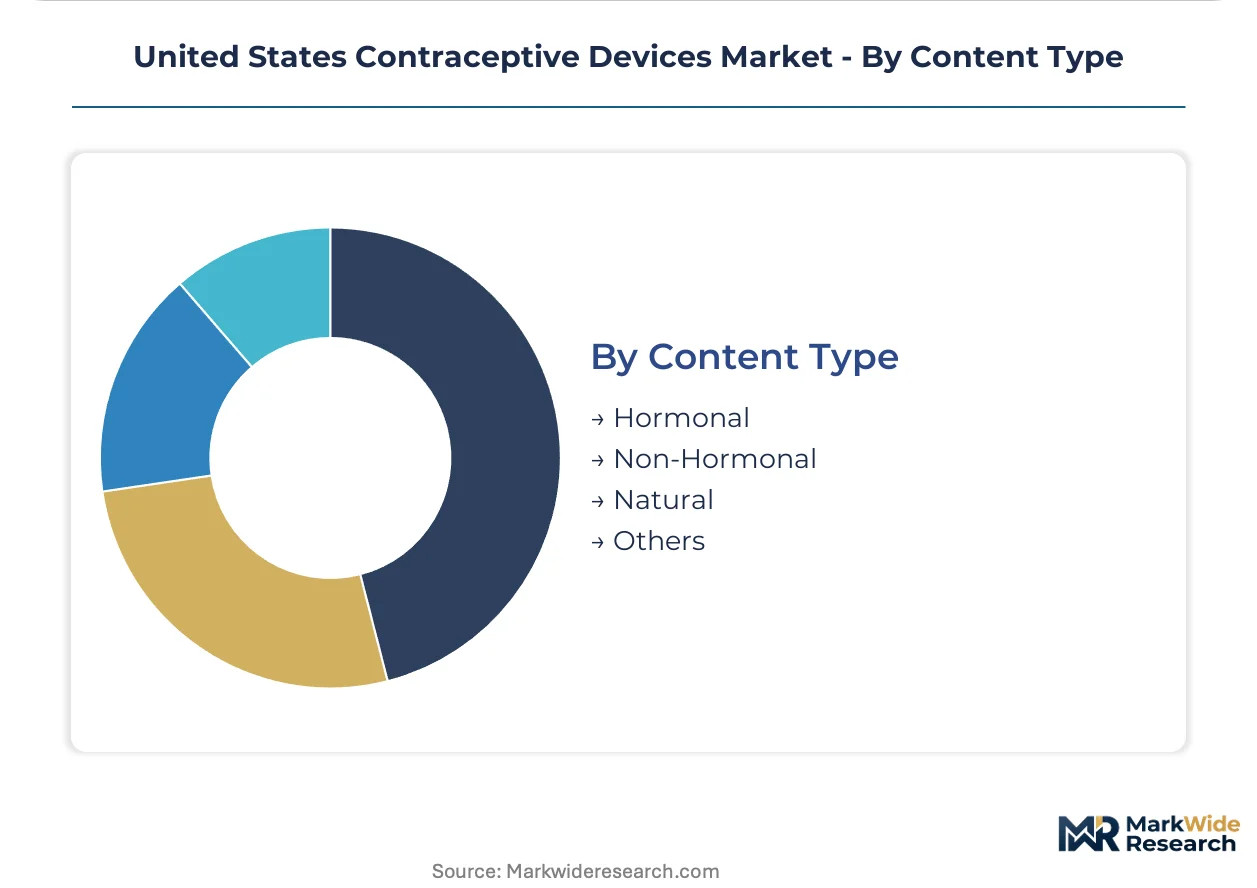
Hormonal systems generate the deepest revenue pools, while Non-Hormonal alternatives are climbing fastest as patient preference shifts toward side-effect avoidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic polymer engineering and copper refining capacity clusters along the Gulf Coast and Southwest, anchoring IUD manufacturing supply chains. Texas, California, and Florida concentrate Medicaid-funded placement volumes through expanded clinic networks. State-level formulary decisions and EPA environmental compliance standards shape procurement patterns across sub-regional markets.
Texas
Medicaid expansion counties drive LARC placement demand through hospital system expansion of dedicated insertion suites. FDA 510(k) clearance timelines for novel hormone-eluting devices compress below twelve months for Texas-registered manufacturers. Houston-based polymer engineering firms secure long-term medical-grade silicone contracts with domestic chemical corridors.
California
Affordable Care Act contraceptive coverage mandates eliminate patient cost-sharing for FDA-approved methods in commercial insurance markets. State health department portals enable digital triage for device selection before clinic contact. Metropolitan OB-GYN practices in Los Angeles and San Francisco adopt frameless nitinol intrauterine systems for silicone-hypersensitive patients.
Florida
Hospital networks add same-day implant procedure capacity to capture Medicaid reimbursement flows. Ambulatory surgery centers deploy centralized scheduling platforms for pre-qualified patients from state health portals. Rural health centers struggle with clinician recertification cycles for difficult-placement protocols.
Southeast
Georgia and Alabama clinics face ninety-day prior authorization delays for hormonal IUDs in non-expansion Medicaid environments. Silicone precursor production concentration in Louisiana chemical corridors exposes manufacturers to hurricane disruption risks. Regional tertiary facilities absorb embedded device extraction referrals from community health centers lacking hysteroscopic equipment.
Midwest
Michigan polymer research institutes partner with Minnesota medical device incubators on biodegradable polylactic acid frame prototypes. Ohio medical-grade silicone production anchors elastomer supply for domestic IUD manufacturers. Chicago-based integrated delivery networks consolidate hospital purchasing committee authority over manufacturer contract negotiations.
United States Contraceptive Devices Market Competitive Landscape
Vertically integrated pharmaceutical conglomerates and specialized reproductive health device manufacturers split the market along channel control lines. The competitive structure concentrates around three strategic archetypes: hormone-synthesis integrators with captive polymer engineering capabilities, OB-GYN channel specialists controlling ambulatory access points, and retail pharmacy incumbents with over-the-counter brand equity. Dominant competitive moves include backward integration into medical-grade material supply chains and strategic partnerships with state Medicaid procurement networks.
Within the hormone-synthesis integrator tier, Bayer AG exemplifies vertical control across active pharmaceutical ingredient production and device manufacturing. CooperSurgical, Inc. occupies a channel-specialist position through concentrated access to OB-GYN office and ambulatory surgery center networks. Church & Dwight Co., Inc. anchors the retail-facing archetype with established pharmacy and e-commerce distribution for patient-directed barrier methods.
| Leading Market Players |
|---|
| Bayer AG |
| CooperSurgical, Inc. |
| Merck & Co., Inc. |
| Church & Dwight Co., Inc. |
| Reckitt Benckiser Group plc |
| Teva Pharmaceutical Industries Ltd |
| Pfizer Inc. |
| The Cooper Companies |
| AbbVie |
| Others |
Value Network & Pricing Analysis
Undercapacity in domestic medical-grade silicone refining is compressing supplier margins and amplifying pricing power for hormone-eluting IUD manufacturers with captive polymer engineering capabilities. Texas and Louisiana chemical corridor disruptions transmit directly to device input costs, forcing procurement committees to absorb volatility or reformulate material specifications.
Pricing Analysis
Affordable Care Act contraceptive coverage mandates dictate the pricing tier structure across institutional procurement channels, eliminating patient cost-sharing for FDA-approved methods while preserving clinic administration fee differentials. Premium-mid-economy pricing differentiation separates hormone-eluting intrauterine systems with extended efficacy windows from copper alternatives and barrier methods. Pricing pressure stems from Medicaid formulary rate compression in non-expansion states, with Georgia and Alabama clinics facing reimbursement delays that squeeze device margins. Hospital purchasing committees exhibit lowest price sensitivity due to bundled procedure economics, while retail pharmacy channels for condoms face highest consumer elasticity.
Supply Chain Analysis
Tariff exposure between Chile and domestic copper wire drawing facilities dominates supply chain risk assessment for non-hormonal IUD manufacturers. Medical-grade silicone production concentrates in Louisiana and Ohio chemical corridors, copper concentrate refining anchors in Arizona and Utah EPA-compliant smelters, and polymer engineering clusters in Texas and Michigan. Raw material dependencies encompass elastomer precursors, electrolytic copper cathodes, and nitinol shape-memory alloy feedstock. Single-source vulnerability in Gulf Coast silicone precursor production exposes manufacturers to hurricane disruption cascades. Distribution runs through hospital system GPO contracts, clinic network procurement consortia, and retail pharmacy direct-to-shelf logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified clinician scarcity for complex LARC placement protocols constrains market expansion more than manufacturing capacity or regulatory clearance timelines. This bottleneck rewards stakeholders who solve training throughput or bypass insertion complexity through device design innovation.
For Market Incumbents: Entrench channel control through exclusive supply agreements with Texas and Florida Medicaid expansion hospital networks, locking in placement volume commitments before competitor suite expansion. Acquire or partner with telehealth platforms offering virtual pre-insertion counseling to capture rural patient flow and reduce no-show attrition. Defend against biodegradable polymer substitutes by accelerating frameless nitinol platform iteration and securing patent thickets around extraction-simplification mechanisms. For New Entrants and Emerging Players: Rural Southeast counties lacking OB-GYN density present the most penetrable white-space for telehealth-integrated device counseling and mobile placement unit deployment. Target community health centers in Georgia and Alabama facing ninety-day prior authorization delays with streamlined prior authorization support services bundled to device supply. Pursue FDA 510(k) abbreviated submissions leveraging predicate equivalence to compress clearance timelines below incumbent benchmarks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hormone-eluting IUD manufacturers with multi-year replacement cycles and established clinic network contracts. Long-term viability over the projection horizon favors acquisition targets combining vertical polymer engineering control with state Medicaid procurement relationships. Monitor FDA premarket notification backlog clearance velocities as the critical inflection signal for novel device category entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer R&D Partnership | Michigan polymer institutes collaborating with Minnesota incubators on polylactic acid frame validation eliminate extraction procedure requirements. |
| Telehealth Platform Integration | Virtual pre-insertion counseling expands Texas rural county access and reduces scheduled placement appointment no-show rates. |
| Medicaid GPO Contract Consolidation | Hospital system purchasing committee authority over manufacturer negotiations concentrates procurement volume in expansion states. |
| EPA-Compliant Copper Smelter Certification | Arizona and Utah zero-discharge electrolytic refining investments secure medical-grade supply chain continuity under Toxic Substances Control Act mandates. |
| Clinician Certification Program Expansion | Florida rural health center recertification support addresses forty-hour continuing medical education module completion barriers for difficult-placement protocols. |
Research Methodology
The analysis maps hormone-eluting IUD, copper IUD, implant, condom, and diaphragm sub-sectors, each validated through clinician interviews, hospital purchasing committee discussions, Medicaid formulary directors, and reproductive health clinic administrators. Primary fieldwork combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, state health department procurement records, and EPA environmental compliance disclosures. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation anchored volume and value estimates.
Assumptions held fixed include Affordable Care Act contraceptive coverage mandate continuity, current FDA premarket notification pathway timelines, and existing state Medicaid expansion geographies. Variable assumptions encompass copper price volatility trajectories, hurricane disruption frequencies to Gulf Coast chemical infrastructure, and biodegradable polymer prototype validation progress. Segmentation dimensions modeled span product type, end user procurement authority, delivery mode, and content classification. CAGRs derived from regression analysis against historical placement volume trends and reimbursement rate evolution. Industry-specific inputs incorporated clinic network expansion announcements and EPA smelter certification status changes.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration into silicone precursor production or sudden biodegradable platform commercialization by established manufacturers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Middle East and Africa Surgical Equipment Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Biliary Catheters Market
Medical Devices
Medical Face Shield Market
Medical Devices
Non- Resorbable Cranial Fixation System Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Phoropters Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
Alpha Emitter Market
Medical Devices
Dual Chamber Prefilled Syringes Market