
 Saudi Arabia Respiratory Devices Market | 2026-2036
Saudi Arabia Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Respiratory Devices Market Analytics
Connected inhaler platforms with embedded dose counters and Bluetooth telemetry are reshaping how Saudi patients manage asthma and COPD therapy adherence. Koninklijke Philips N.V. leverages its sleep apnea portfolio to anchor the CPAP segment across the Kingdom's private hospital networks. ResMed Inc. competes through cloud-connected ventilation systems that sustain remote patient monitoring contracts with Ministry of Health facilities. Medtronic PLC differentiates via miniaturized nebulizer platforms designed for pediatric and geriatric homecare use.
Respiratory devices encompass mechanical ventilators, positive airway pressure systems, aerosol delivery apparatus, and humidification equipment engineered to maintain or restore pulmonary gas exchange. These systems incorporate flow sensors, pressure transducers, and filtration media rated to HEPA standards, serving acute critical care, chronic disease management, and sleep-disordered breathing intervention. CPAP devices and smart inhalers command the strongest margin pools as technology-intensive categories where proprietary algorithms and patient data platforms create switching costs. Homecare settings represent the fastest-growing end-user channel as Saudi Arabia's healthcare privatization agenda shifts reimbursement toward outpatient and domiciliary models. Jet nebulizers retain volume dominance in clinic and rehabilitation center procurement due to lower capital outlay and simpler maintenance protocols.
SFDA medical device regulations govern product registration, clinical evidence requirements, and post-market surveillance for all respiratory equipment distributed in the Kingdom. The Saudi Food and Drug Authority aligns its classification system with international standards while requiring local authorized representatives for foreign manufacturers, which shapes market access timelines and partnership structures. MOHAP facility licensing standards for homecare providers are expanding the addressable base of certified oxygen therapy and ventilation service operators. Stakeholders must monitor how Saudi Vision 2030 healthcare localization targets will reshape procurement preferences toward domestic assembly and regional supply chain partnerships.
Market Dynamics
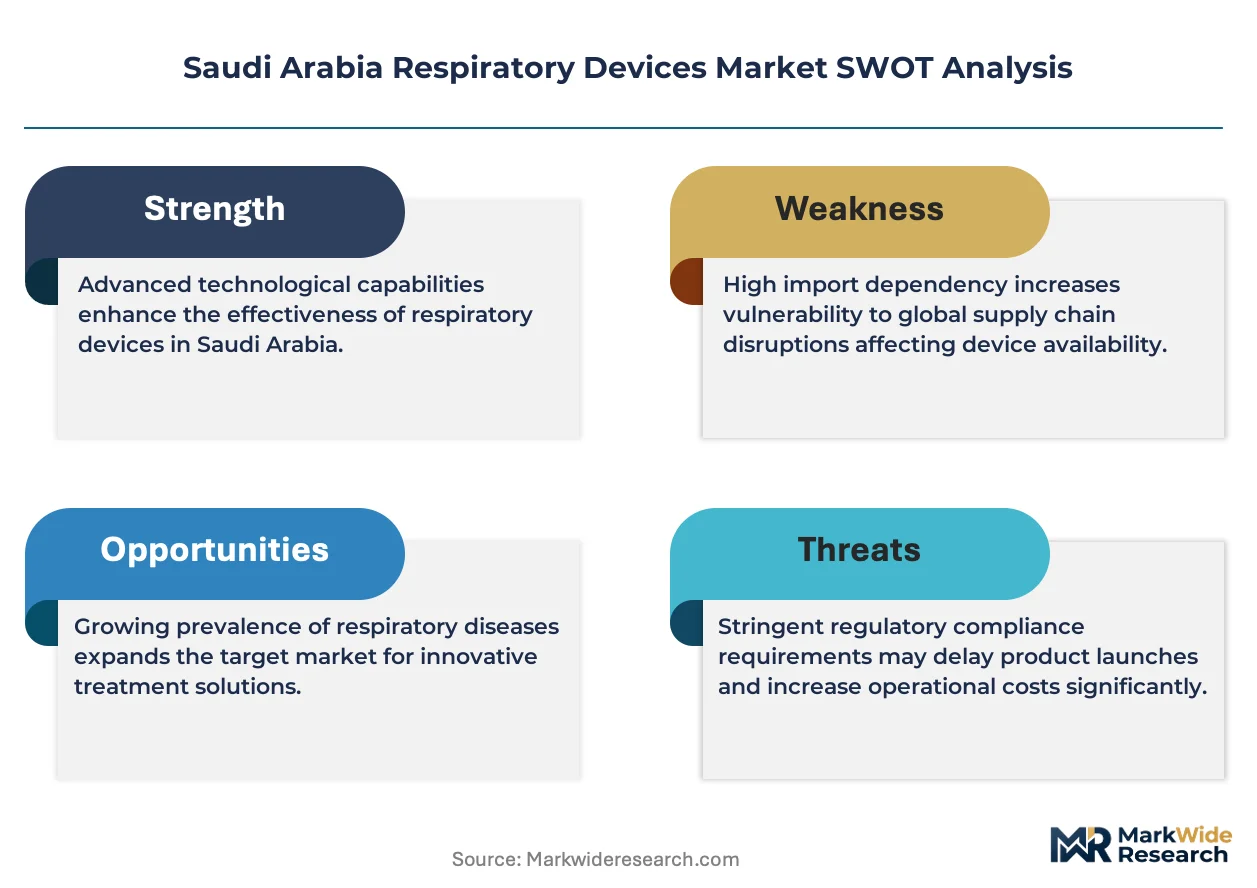
Saudi Vision 2030 healthcare privatization is redirecting respiratory device procurement from Ministry of Health bulk tenders toward fragmented private hospital networks and homecare service operators requiring localized distribution partnerships.
Growth Catalysts
- SFDA Registration Harmonization:The Saudi Food and Drug Authority's alignment with international medical device standards is compressing approval timelines for European and American manufacturers, accelerating market entry for advanced ventilation platforms.
- Homecare Reimbursement Expansion:MOHAP facility licensing for certified oxygen therapy providers is creating a reimbursable channel for CPAP and home ventilation units previously confined to out-of-pocket purchases.
- Remote Monitoring Infrastructure:Cloud-connected respiratory platforms are digitizing patient adherence data, enabling Ministry of Health contracts that prioritize telemetry-enabled devices over conventional equipment.
Market Restraints
- Import Dependency Concentration:Over 90 percent of mechanical ventilators and CPAP systems originate from US and European manufacturing bases, exposing Saudi distributors to trans-Atlantic shipping volatility and currency fluctuation risk.
- SFDA Clinical Evidence Burden:The requirement for local authorized representatives and Kingdom-specific clinical validation studies extends product registration cycles, freezing smaller manufacturers out of the market.
- Jet Nebulizer Commoditization:Lower-margin aerosol delivery devices face price compression from Asian contract manufacturers, eroding distributor margins on clinic-procured equipment.
Strategic Opportunities
- Jeddah Private Healthcare Corridor:The concentration of premium private hospitals in Jeddah's medical district creates demand for high-acuity ventilator configurations and anesthesia workstations absent from public procurement lists.
- Pediatric Homecare Gap:Miniaturized nebulizer and ventilation platforms designed for pediatric domiciliary use remain underpenetrated relative to adult sleep apnea segments, offering first-mover positioning.
- Localization Incentives:Saudi Vision 2030 domestic assembly targets and regional supply chain partnership requirements favor manufacturers establishing in-Kingdom technical service centers and final assembly operations.
Industry Challenges
- Biomedical Engineering Talent Scarcity:The shortage of technicians trained on cloud-connected ventilation telemetry and pressure transducer calibration is constraining homecare service expansion.
- Legacy System Integration Friction:New Bluetooth-enabled inhaler platforms face interoperability barriers with Ministry of Health electronic health record architectures, delaying institutional adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Respiratory Devices Market |
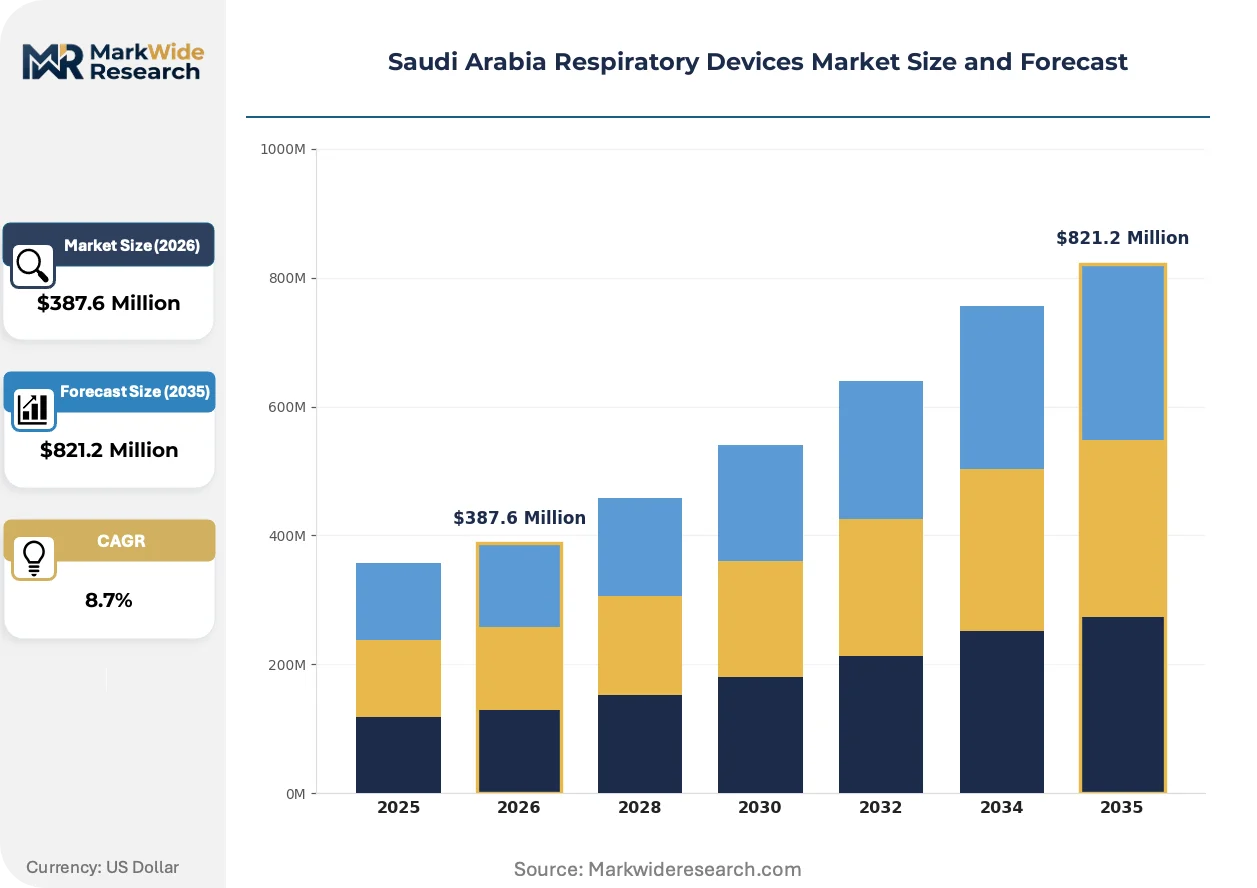
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, CPAP Devices, Humidifiers End User: Hospitals, Homecare Settings, Clinics, Rehabilitation Centers Technology: Jet Nebulizers, Ultrasonic Nebulizers, Pill Container Nebulizers, Smart Inhalers Application: Chronic Obstructive Pulmonary Disease, Asthma, Sleep Apnea, Bronchitis |
| Companies Covered | Dragerwerk AG, Fisher & Paykel Healthcare Limited, Koninklijke Philips N.V, GE Healthcare, GSK plc, Medtronic PLC, ResMed Inc., Invacare Corporation, Smiths Group PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Respiratory Devices Market Evolving Landscape
Connected respiratory platforms and algorithm-driven therapy personalization are compressing the gap between acute hospital ventilation and domiciliary care, blurring traditional procurement boundaries.
Smart inhaler ecosystems incorporating embedded dose counters and Bluetooth telemetry are digitizing asthma and COPD management workflows. Saudi private hospital networks are piloting these platforms for remote adherence monitoring. The technology is digitizing how pharmaceutical manufacturers contract with payers, shifting from device sales toward therapy-outcome subscription models.
SFDA post-market surveillance requirements now mandate adverse event reporting through centralized digital portals, tightening accountability for ventilator and CPAP manufacturers. The regulation is forcing distributors to maintain localized technical service capabilities rather than relying on remote overseas support. High-acuity ICU ventilator segments face the steepest compliance cost increases as real-time performance data submission becomes mandatory.
Ministry of Health procurement officers are unbundling device purchases from maintenance contracts, creating separate bidding lanes for equipment supply and multi-year service agreements. Private hospital groups in Riyadh and Jeddah are consolidating vendor panels, awarding sole-source contracts to respiratory device suppliers offering integrated training and remote monitoring. This concentration is most visible in tertiary hospital clusters where standardization reduces biomedical engineering training burden.
Saudi Arabia Respiratory Devices Market Segmentation
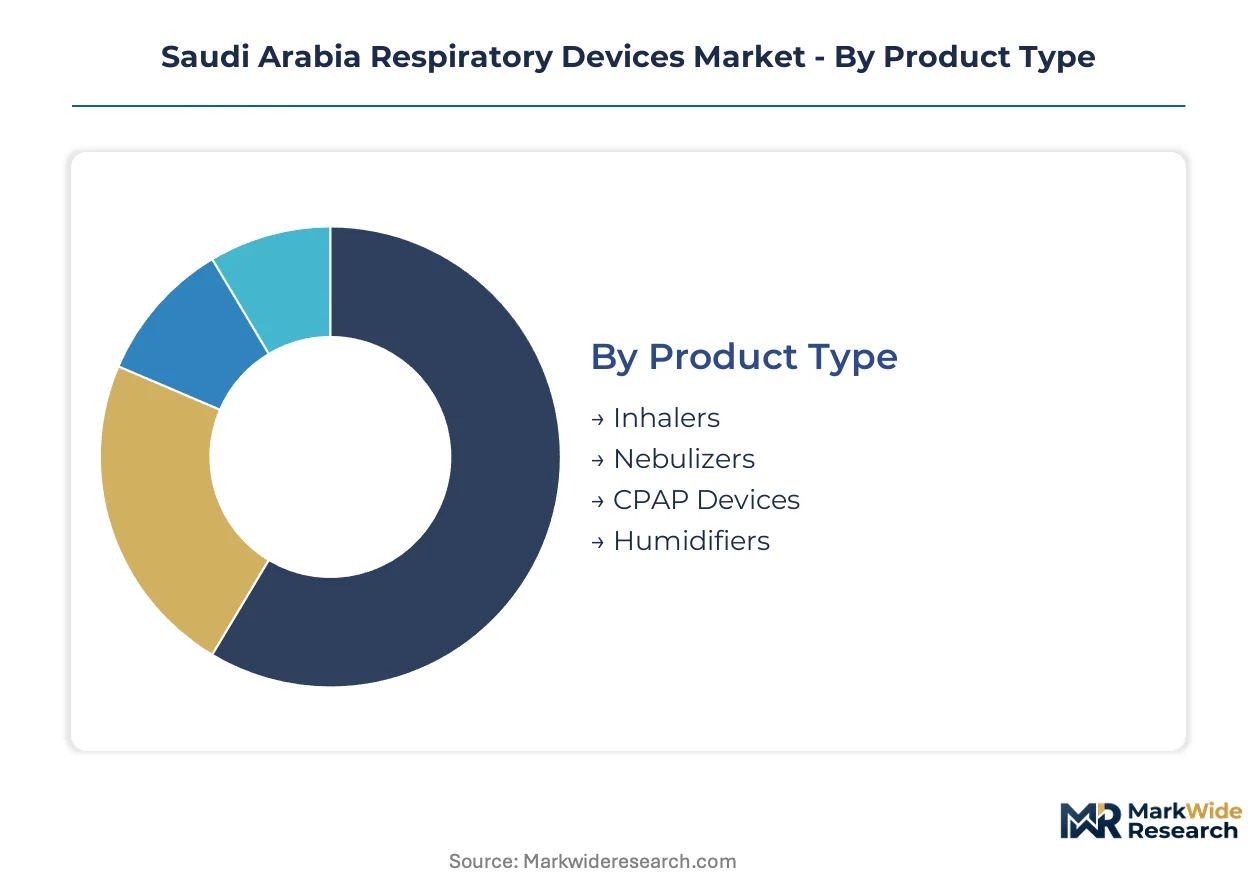
Respiratory device procurement in Saudi Arabia fragments across therapeutic purpose, care setting, and technology intensity. Each segmentation axis reveals distinct margin structures and regulatory exposure that shape vendor strategy.
Product Type:
Mature mechanical platforms dominate hospital procurement volumes while connected therapeutic systems capture expanding homecare reimbursement.
- CPAP Devices:Positive airway pressure systems with algorithm-driven pressure titration and heated humidification modules anchor sleep apnea therapy. Riyadh's tertiary hospital cluster and Jeddah's private healthcare corridor concentrate demand as MOHAP expands homecare reimbursement for obstructive sleep apnea diagnosis.
- Inhalers:Metered-dose and dry-powder platforms with embedded Bluetooth dose counters are digitizing asthma management. SFDA registration requirements for connected inhaler platforms are tightening clinical evidence standards, compressing approval timelines for European and American manufacturers.
- Nebulizers:Aerosol delivery apparatus serving acute bronchospasm management in pediatric and geriatric populations.
- Humidifiers:Active and passive humidification systems integrated with mechanical ventilation circuits.
CPAP devices handle the majority of throughput; smart inhaler platforms are expanding most quickly into remote monitoring contracts.
End User:
Institutional procurement channels favor capital-intensive platforms while domiciliary care is absorbing portable, reimbursable equipment.
- Homecare Settings:Certified oxygen therapy and ventilation service operators are proliferating under MOHAP facility licensing standards. Riyadh's suburban corridors and Jeddah's residential zones concentrate demand as Saudi Vision 2030 privatization redirects reimbursement toward outpatient models.
- Hospitals:Tertiary critical care units and emergency departments deploy high-acuity ventilator configurations with real-time performance telemetry. SFDA post-market surveillance mandates now require adverse event reporting through centralized digital portals, elevating compliance costs for ICU equipment suppliers.
- Clinics:Primary care and pulmonary specialty practices utilizing jet nebulizers for acute exacerbation management.
- Rehabilitation Centers:Long-term care facilities integrating respiratory therapy with physical rehabilitation protocols.
Hospitals absorb the bulk of capital expenditure; homecare settings are climbing the fastest on patient volume.
Technology:
Cost-tier stratification separates commodity aerosol delivery from premium connected platforms with proprietary data ecosystems.
- Smart Inhalers:Bluetooth-enabled devices with embedded sensors and companion mobile applications are reshaping pharmaceutical contracting models. The technology is digitizing adherence data for Ministry of Health remote monitoring pilots, though interoperability friction with legacy electronic health record architectures delays institutional scale.
- Jet Nebulizers:Compressed-air aerosol generators with lower capital outlay and simplified maintenance protocols retain volume dominance in clinic procurement. Asian contract manufacturers are compressing distributor margins through price competition.
- Ultrasonic Nebulizers:Piezoelectric crystal-driven platforms offering quieter operation for pediatric and nocturnal use.
- Pill Container Nebulizers:Portable, battery-operated units designed for patient mobility and travel scenarios.
Jet nebulizers command the volume base; smart inhalers are gaining share fastest on connected health infrastructure investment.
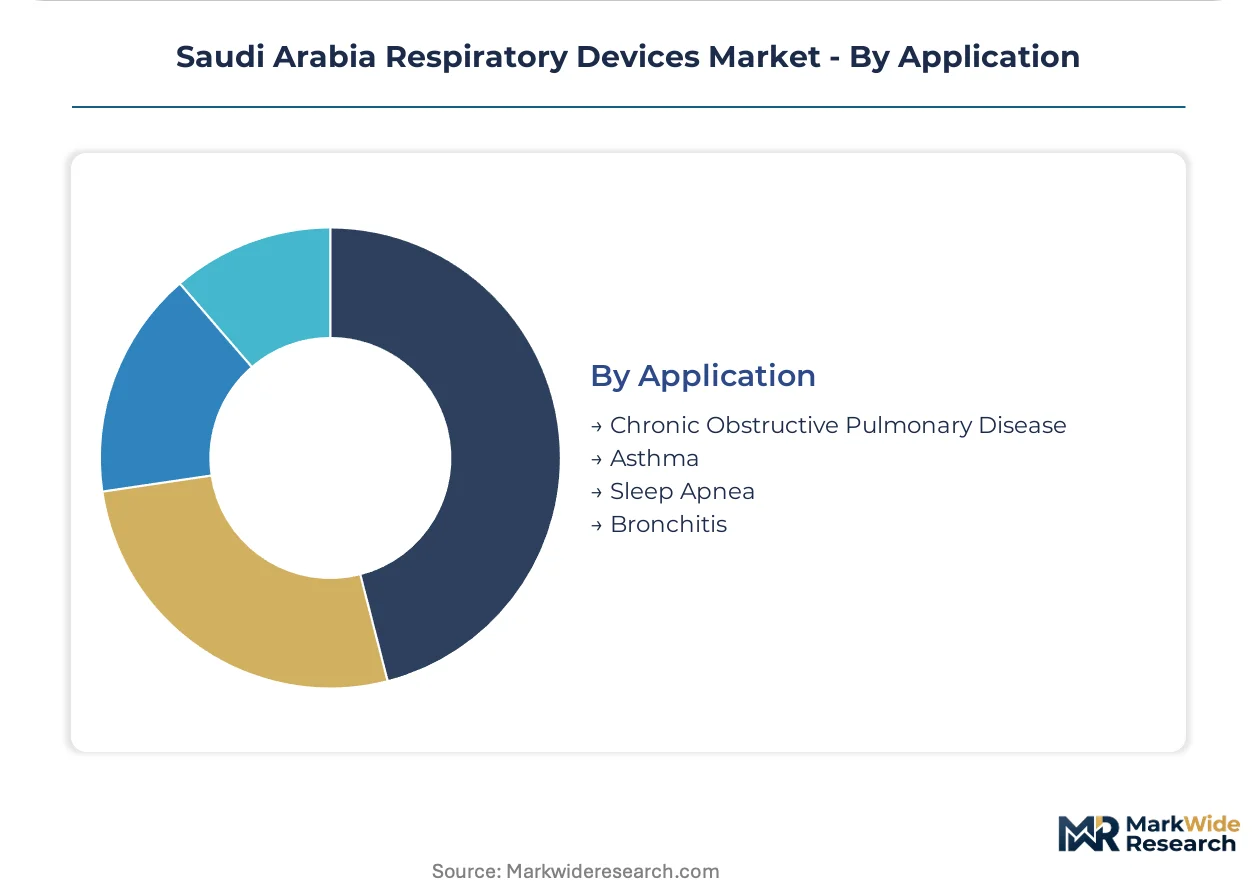
Application:
Disease prevalence and reimbursement eligibility determine addressable market depth across therapeutic indications.
- Sleep Apnea:Obstructive sleep apnea diagnosis and therapy represent the most reimbursable application channel under expanding MOHAP homecare licensing. CPAP and BiPAP platforms with cloud-connected adherence monitoring are securing sole-source contracts from consolidated private hospital vendor panels.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation requiring long-term oxygen therapy and intermittent ventilation support. Saudi Arabia's aging demographic and smoking prevalence sustain demand for portable oxygen concentrators and home ventilator platforms.
- Asthma:Reversible airway obstruction managed through inhaled corticosteroid and bronchodilator therapy.
- Bronchitis:Acute and chronic inflammatory conditions treated with nebulized bronchodilators and corticosteroids.
Sleep Apnea captures the steepest reimbursement expansion; COPD is deepening fastest on demographic tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Dutch manufacturers ship high-acuity ventilators through Rotterdam and Hamburg to Saudi distributors serving Riyadh's tertiary hospital cluster.
Riyadh
The capital's tertiary hospital cluster concentrates demand for ICU ventilator configurations with real-time telemetry. SFDA post-market surveillance mandates require adverse event reporting through centralized digital portals, elevating compliance costs for equipment suppliers. King Faisal Specialist Hospital and Research Centre anchors procurement volumes for high-acuity respiratory platforms.
Eastern Province
Aramco-affiliated healthcare facilities and industrial medical centers drive demand for emergency ventilation and respiratory protection systems. MOHAP facility licensing standards are expanding certified oxygen therapy provider networks across Dammam and Al Khobar. The Dammam medical corridor is absorbing portable ventilator units for offshore and remote industrial site deployment.
Jeddah
The private healthcare corridor concentrates demand for premium CPAP configurations and sleep apnea diagnostic platforms. Expanding homecare reimbursement under MOHAP licensing is redirecting procurement toward domiciliary ventilation service operators. King Fahd General Hospital and private hospital groups in the Al Rawdah district are consolidating vendor panels for integrated respiratory therapy contracts.
Western Region
Pilgrimage-season medical infrastructure and seasonal population surges create episodic demand spikes for emergency respiratory equipment. The Holy Cities of Makkah and Madinah require surge-capable ventilator inventories managed through Ministry of Health regional warehouses. Taif's altitude medical facilities specialize in respiratory adaptation therapy for visitors transitioning from sea level.
Saudi Arabia Respiratory Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the Saudi respiratory devices market. The vendor base stratifies between diversified medical technology conglomerates with established SFDA registration pathways and focused respiratory specialists leveraging cloud-connected platform differentiation. Three archetypes dominate: sleep therapy platform providers, critical care ventilation manufacturers, and homecare service-integrated distributors. Consolidation pressures are intensifying as private hospital networks consolidate vendor panels and Ministry of Health procurement unbundles equipment from service contracts.
Within the diversified medical technology tier, Koninklijke Philips N.V. and GE Healthcare exemplify channel-controlling players with broad SFDA-registered portfolios spanning diagnostic imaging and respiratory therapy. ResMed Inc. occupies a specialist position focused on cloud-connected sleep apnea and ventilation platforms. These three companies represent contrasting strategic postures: full-stack hospital system integration versus focused respiratory platform dominance versus sleep-disordered breathing specialization.
| Leading Market Players |
|---|
| Dragerwerk AG |
| Fisher & Paykel Healthcare Limited |
| Koninklijke Philips N.V |
| GE Healthcare |
| GSK plc |
| Medtronic PLC |
| ResMed Inc. |
| Invacare Corporation |
| Smiths Group PLC |
| Others |
Value Network & Pricing Analysis
Rotterdam-Hamburg trans-Atlantic freight corridors impose cost volatility on Saudi distributors serving Riyadh's tertiary hospital cluster, compressing margins on high-acuity ventilators while amplifying price differentiation between telemetry-enabled platforms and conventional equipment. This logistics chokepoint concentrates procurement power among channel-controlling players with bonded warehousing capacity in Jeddah's free trade zone.
Pricing Analysis
Next-generation cloud-connected CPAP units command 40-60% premiums over prior-generation fixed-pressure devices, while current-gen algorithm-driven platforms occupy the volume middle. Three-tier pricing structure across premium telemetry-integrated, standard humidification-equipped, and economy fixed-pressure levels reflects certification grade differentiation under SFDA quality benchmarks. Pricing pressure stems from Asian contract manufacturers flooding jet nebulizer segments with undifferentiated alternatives. Government hospital procurement committees exhibit highest price sensitivity, while Jeddah's private healthcare corridor absorbs premium configurations with bundled service contracts.
Supply Chain Analysis
US Commerce Department export controls on advanced pressure transducer and flow sensor technologies constrain supply flows to Saudi assembly operations, forcing distributors toward European alternative sourcing. Manufacturing concentration rests on Germany, Netherlands, and United States for high-acuity ventilation platforms, with China and South Korea supplying commodity nebulizer components. Critical dependencies include piezoelectric crystals for ultrasonic platforms, medical-grade silicones for mask interfaces, and HEPA filtration media. Single-source vulnerability concentrates in cloud-connected telemetry chipsets from US-based semiconductor fabricators. Distribution runs through Jeddah-based authorized representatives holding SFDA import licenses, with final-mile delivery to MOHAP-certified homecare operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins in Saudi respiratory devices are flattening as Ministry of Health procurement unbundles equipment from service contracts, yet recurring-revenue layers from remote monitoring subscriptions and multi-year technical service agreements are expanding faster than device sales alone.
For Market Incumbents: Insulate market position by deepening backward integration into cloud-connected telemetry platform development, capturing patient adherence data that creates switching costs for hospital procurement committees. Acquire or partner with MOHAP-licensed homecare service operators to control the downstream channel as reimbursement shifts toward domiciliary models. Prioritize SFDA regulatory affairs investment to compress registration timelines for next-generation devices before emerging Asian manufacturers establish local authorized representative networks. For New Entrants and Emerging Players: Pediatric miniaturized nebulizer and ventilation platforms for domiciliary use represent the most penetrable white-space entry point, with reimbursement eligibility expanding under MOHAP facility licensing standards. Eastern Province industrial medical centers and Aramco-affiliated facilities offer second-tier access with less consolidated vendor panels than Riyadh's tertiary cluster. Establish go-to-market positioning through telemedicine platform partnerships that bundle respiratory devices with remote physician monitoring services. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core respiratory portfolios amid healthcare privatization uncertainty. Long-term viability over the coming decade hinges on regulatory data platform ownership rather than device manufacturing scale alone. Monitor SFDA post-market surveillance compliance cost escalation as the inflection signal for distressed acquisition opportunities among smaller manufacturers frozen out by clinical evidence burdens.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Acceleration | Compresses market entry timelines for European and American manufacturers against Asian competitors. |
| Homecare Service Integration | Captures recurring revenue from MOHAP-licensed oxygen therapy providers as reimbursement shifts. |
| Cloud Telemetry Platform Development | Creates proprietary patient adherence data ecosystems that lock in Ministry of Health contracts. |
| Pediatric Miniaturization R&D | Addresses underpenetrated domiciliary segment with first-mover positioning in reimbursement expansion. |
| Regional Assembly Localization | Aligns with Saudi Vision 2030 domestic manufacturing targets and procurement preference policies. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineering directors, hospital procurement committee members, SFDA regulatory consultants, and homecare service operators, then refined through secondary validation across SFDA medical device registration databases, Ministry of Health procurement tender records, GPO contract filings, and customs import manifests. Bottom-up demand modeling from end-user facility counts and equipment replacement cycles was triangulated against top-down market sizing from distributor revenue proxies and manufacturer shipment data.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across product type, end-user channel, technology tier, and therapeutic application, with CAGRs derived from installed base growth, replacement cycle compression, and reimbursement eligibility expansion. Forecast inputs incorporated SFDA regulatory timeline assumptions, MOHAP facility licensing trajectory, and Saudi Vision 2030 healthcare privatization milestones.
Stress conditions across trans-Atlantic shipping cost volatility, currency fluctuation bands, and SFDA registration timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement policy continuity and regulatory harmonization pace. Material shifts in Saudi Vision 2030 localization enforcement or MOHAP procurement unbundling intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Patient Lift Slings Market
Medical Devices
Breast Lesion Localization Device Market
Medical Devices
Functional Electrical Stimulation Market
Medical Devices
Portable Medical Electronic Products Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Europe Invisible Orthodontics Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Transcranial Doppler Devices Market