
 Global Cosmetic Implants Market | 2026-2036
Global Cosmetic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetic Implants Market Foresight
Modular implant systems that separate shell construction from filler customization are rebalancing how plastic surgery clinics configure inventory. AbbVie Inc. leverages its Allergan Aesthetics portfolio to sustain dominance in silicone gel breast implants across North American and European channels. Johnson & Johnson anchors reconstructive applications through its Mentor subsidiary's extensive surgeon training networks. Sientra Inc. differentiates via proprietary High-Strength Cohesive silicone and direct-to-physician distribution control in the United States.
Cosmetic implants comprise biocompatible prosthetic devices surgically inserted to alter body contour, restore volume, or reconstruct tissue defects, typically manufactured from medical-grade silicone elastomers, saline solutions, or porous polymers with specified durometer hardness and shell thickness parameters. Breast implants command the largest revenue pool due to established reimbursement pathways for post-mastectomy reconstruction and sustained out-of-pocket demand for aesthetic augmentation. Facial implants represent the fastest-expanding category as porous polyethylene and custom CAD-CAM designs displace traditional bone grafting in maxillofacial procedures. Silicone materials retain margin concentration owing to superior tactile properties and decades of clinical safety documentation that streamline regulatory submissions.
The FDA's premarket approval requirements for silicone breast implants and the EU MDR's heightened clinical surveillance obligations for Class III implantable devices collectively elevate barriers for new entrants while mandating post-market safety registries. Health Canada and Brazil's ANVISA enforce parallel vigilance systems that shape multinational manufacturers' quality management investments. Stakeholders must monitor evolving biocompatibility testing standards and surgeon certification requirements as gatekeepers for market access.
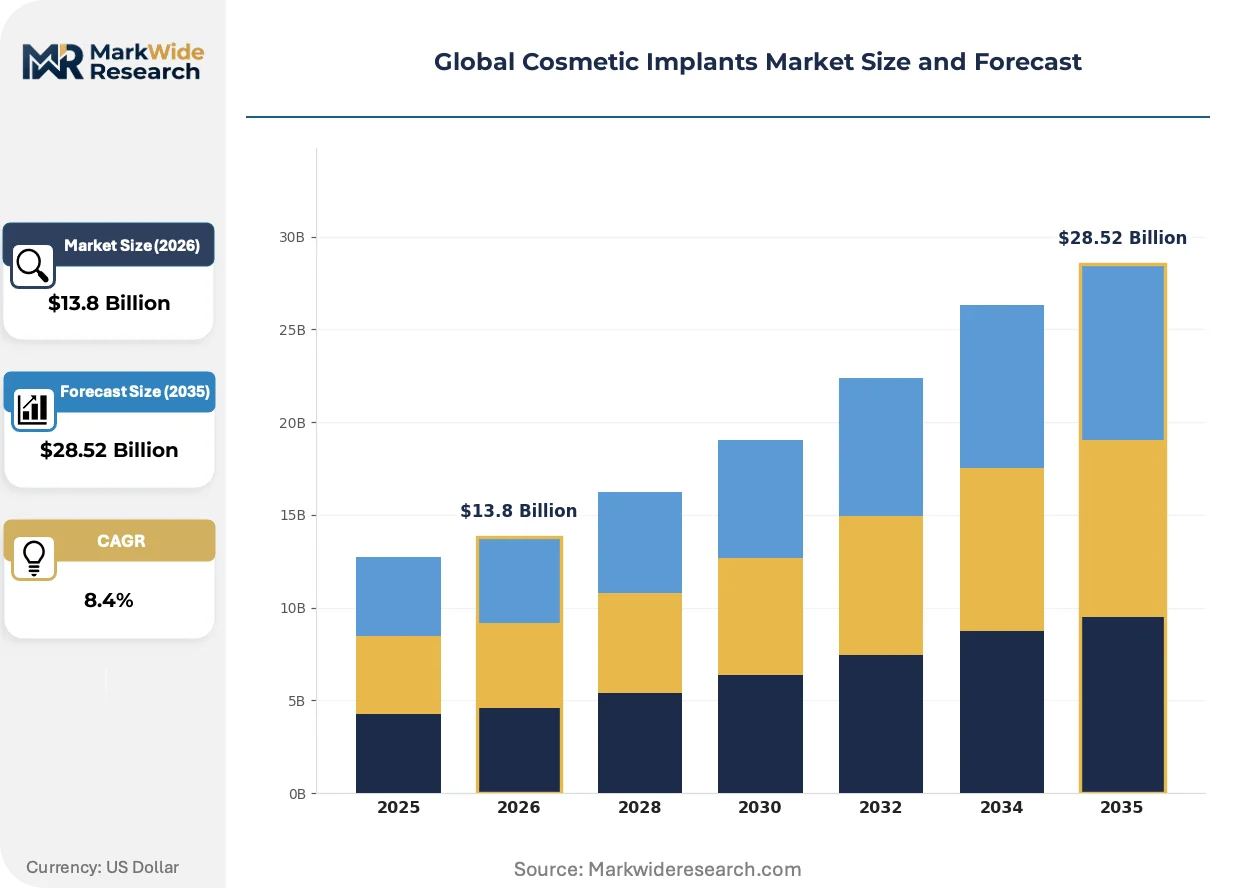
Market Dynamics
Silicone breast implant manufacturers face intensifying clinical evidence demands as the EU MDR and FDA impose parallel post-market surveillance registries, forcing portfolio reallocation toward reconstructive reimbursement pathways and direct-to-physician service models.
Growth Catalysts
- EU MDR Clinical Evidence Mandates:Post-mastectomy reconstruction pathways in France and Germany now require structured long-term safety data, accelerating hospital procurement of established silicone gel portfolios with documented biocompatibility profiles.
- Porous Polyethylene Facial Implants:Maxillofacial surgery departments in South Korea and Brazil are replacing autologous bone grafting with patient-specific CAD-CAM facial implants, compressing operative time and donor site morbidity.
- Modular Inventory Systems:Plastic surgery clinics in the United States are adopting shell-and-filler separation architectures that reduce SKU proliferation and enable same-day customization for revision procedures.
Market Restraints
- Medical-Grade Silicone Elastomer Concentration:Three specialty chemical suppliers control high-purity silicone precursor supply to implant manufacturers, exposing margin volatility to semiconductor industry demand cycles.
- FDA Premarket Approval Timelines:New silicone breast implant submissions face 18-36 month review windows with mandatory adjunct study commitments, freezing pipeline investments for mid-cap entrants.
- Saline Implant Substitution Pressure:Cost-conscious ambulatory surgery centers in select Latin American markets continue specifying saline-filled devices despite inferior tactile outcomes, capping silicone premium capture.
Strategic Opportunities
- Underpenetrated Indian Aesthetic Market:Metro hospital chains in Mumbai and Delhi are establishing dedicated cosmetic surgery units with imported silicone portfolios, ahead of domestic manufacturing scale-up under PLI scheme incentives.
- 3D Bioprinting Convergence:Research consortia in Japan and Switzerland are integrating adipose-derived stem cell matrices with resorbable polymer scaffolds, positioning for next-generation autologous-adjacent implants.
- Direct-to-Physician Digital Platforms:Specialized distributors are bypassing traditional hospital procurement committees through surgeon-facing inventory management applications with embedded training modules.
Industry Challenges
- Microsurgical Reconstruction Skill Scarcity:Fellowship-trained plastic surgeons capable of complex implant-based breast reconstruction remain concentrated in tertiary academic centers, limiting procedure volume expansion.
- Biocompatibility Testing Capex Burden:ISO 10993 cytotoxicity and sensitization studies for novel surface coatings require dedicated in-vivo facilities with multi-year amortization horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetic Implants Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breast Implants, Facial Implants, Body Implants, Buttock Implants, Calf Implants Material: Silicone, Saline, Hydrogel, Polyurethane, Polytetrafluoroethylene Application: Reconstructive Surgery, Aesthetic Enhancement, Gender Affirmation, Scar Correction, Tissue Augmentation End User: Plastic Surgery Clinics, Dermatology Centers, Ambulatory Surgical Centers, Cosmetic Hospitals |
| Companies Covered | AbbVie Inc., Johnson & Johnson, Sientra Inc., GC Aesthetics, POLYTECH Health & Aesthetics, Establishment Labs Holdings Inc., 3M Company, Dentsply Sirona Inc., Zimmer Biomet Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetic Implants Market Shifts & Advancements
Digital manufacturing workflows and surface engineering advances are compressing the gap between diagnostic imaging and implant delivery, while regulatory convergence across North America and Europe is standardizing safety documentation requirements.
CAD-CAM patient-specific implant design is automating the transition from CT segmentation to surgical guide production. Academic medical centers in Germany and South Korea are deploying in-house milling centers for porous polyethylene facial implants, reducing turnaround from weeks to 48 hours. This distributed manufacturing model is automating supply chain disintermediation for complex craniofacial reconstructions.
REACH Annex XVII restrictions on certain silicone oligomers are compelling reformulation of implant shell elastomers toward reduced cyclic siloxane migration profiles. German and French notified bodies are enforcing enhanced chemical characterization protocols that extend technical file preparation timelines. Breast implant manufacturers with legacy European market presence are absorbing compliance costs through selective portfolio pruning rather than price pass-through.
After-sales surveillance unbundling is separating device warranty from long-term safety monitoring services. Private plastic surgery groups in Brazil and the United States are contracting independent registries for patient-reported outcome collection, displacing manufacturer-managed follow-up programs. This accountability shift is most visible in high-volume aesthetic markets where malpractice exposure drives documentation rigor.
Global Cosmetic Implants Market Segmentation
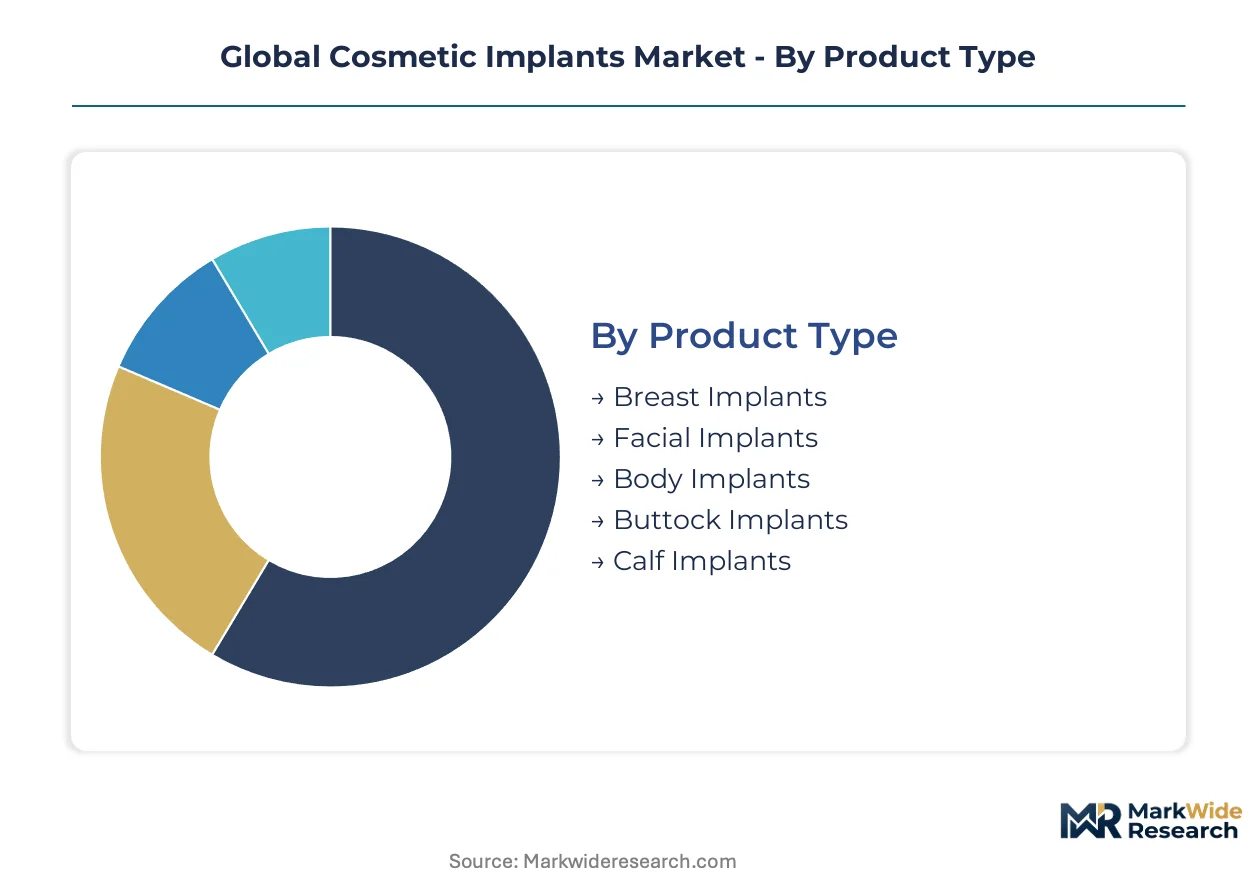
Product-material combinations determine reimbursement pathways and regulatory submission complexity across implant categories. Surgeons weigh tactile outcomes against biocompatibility documentation when selecting configurations for specific anatomical sites.
Product Type:
Procedure volume and average selling price diverge sharply across anatomical applications, with reconstructive pathways commanding premium reimbursement and aesthetic segments driving unit expansion.
- Breast Implants:Silicone gel-filled devices with specified shell thickness and surface texture parameters dominate post-mastectomy reconstruction and elective augmentation. Demand concentrates in plastic surgery clinics across the United States, Brazil, and South Korea, where silicone portfolios with established FDA premarket approval histories secure hospital procurement preference.
- Facial Implants:Porous polyethylene and patient-specific CAD-CAM designs displace autologous bone grafting in maxillofacial reconstruction. Maxillofacial surgery departments in South Korea and Germany are adopting in-house milling workflows that compress turnaround from weeks to 48 hours.
- Body Implants:Pectoral and abdominal contouring devices address congenital asymmetry and post-traumatic defects. Brazil's aesthetic surgery networks specify textured silicone surfaces for reduced capsular contracture incidence.
- Buttock Implants:Intramuscular placement configurations with cohesive silicone gel reduce migration risk versus subcutaneous alternatives. Colombian and Brazilian surgeons favor round-base designs for gluteal augmentation volume.
- Calf Implants:Anatomically contoured silicone shells address lower leg hypoplasia and body dysmorphia presentations. European reconstructive centers specify softer durometer grades for natural gait mechanics.
Breast implants lead on scale; facial implants lead on momentum.
Material:
Shell-filler pairings determine tactile properties, rupture profiles, and regulatory evidence requirements for premarket submissions.
- Silicone:Medical-grade elastomer shells with cohesive gel fillers deliver superior aesthetic outcomes and decades of safety documentation. REACH Annex XVII restrictions on cyclic siloxane migration are compelling reformulation investments among German and French manufacturers.
- Saline:Sterile saltwater fillers enable smaller incision placement and immediate volume adjustability. Cost-conscious ambulatory surgery centers in select Latin American markets continue specifying saline despite inferior tactile properties.
- Hydrogel:Cross-linked polymer fillers offer intermediate consistency between saline and silicone with reduced capsular contracture rates. Japanese regulatory pathways for novel hydrogel compositions remain underdeveloped relative to silicone benchmarks.
- Polyurethane:Foam-coated silicone shells reduce capsular contracture through tissue integration mechanisms. Health Canada maintains specific vigilance requirements for polyurethane-textured devices.
- Polytetrafluoroethylene:Expanded PTFE facial implants provide permanent soft tissue augmentation with minimal inflammatory response. Swiss maxillofacial centers specify ePTFE for nasal dorsum reconstruction.
Silicone leads on scale; hydrogel leads on momentum.
Application:
Reimbursement status and out-of-pocket elasticity create divergent margin structures across clinical indications.
- Reconstructive Surgery:Post-mastectomy breast reconstruction and craniofacial trauma repair command established insurance pathways. France and Germany now require structured long-term safety data under EU MDR post-market surveillance mandates.
- Aesthetic Enhancement:Elective augmentation procedures generate pure out-of-pocket revenue with premium pricing tolerance. Direct-to-physician distribution models in the United States bypass traditional hospital procurement committees.
- Gender Affirmation:Chest and facial feminization procedures are expanding through specialized surgical centers. Thailand's medical tourism infrastructure anchors Asia-Pacific demand for comprehensive affirmation surgery packages.
- Scar Correction:Subcuticular implants address keloid and contracture deformities following burn or traumatic injury. Israeli dermatology centers integrate laser-assisted implant placement for hypertrophic scar revision.
- Tissue Augmentation:Volume restoration for lipoatrophy and age-related facial hollowing leverages smaller-diameter delivery systems. South Korean dermatology clinics specify micro-implant cannulas for periorbital applications.
Reconstructive surgery leads on scale; gender affirmation leads on momentum.
End User:
Procurement authority and patient volume concentration determine channel-specific service and pricing strategies.
- Plastic Surgery Clinics:High-volume aesthetic practices with dedicated implant inventory management drive silicone gel breast implant demand. Modular shell-and-filler separation architectures are reducing SKU proliferation for revision procedures.
- Dermatology Centers:Facial implant and soft tissue filler integration expands through minimally invasive delivery protocols. South Korean dermatology networks are deploying thread-lift and micro-implant combination therapies.
- Ambulatory Surgical Centers:Cost-optimized settings in Brazil and Mexico specify saline-filled devices for price-sensitive patient segments. Same-day discharge protocols favor smaller incision techniques.
- Cosmetic Hospitals:Integrated inpatient and surgical facilities in India and the UAE are establishing dedicated aesthetic surgery units ahead of domestic manufacturing scale-up.
Plastic surgery clinics lead on scale; cosmetic hospitals lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cosmetic implants industry traces its commercial origins to the United States and Brazil, where aesthetic surgery cultures first institutionalized silicone breast augmentation procedures during the 1960s and 1970s. These founding markets established the regulatory templates and surgeon training infrastructures that subsequent geographies adapted.
United States
FDA premarket approval requirements for silicone breast implants and sustained out-of-pocket demand from aesthetic patients drive procedure concentration. The agency mandates post-market surveillance registries that elevate compliance costs for new entrants. Plastic surgery clinics in California, Florida, and Texas anchor national volume through direct-to-physician distribution models.
Brazil
ANVISA vigilance systems for implantable devices run parallel to FDA frameworks, shaping multinational manufacturers' quality investments. The country's aesthetic surgery networks specify textured silicone surfaces for reduced capsular contracture rates. São Paulo and Rio de Janeiro surgical clusters generate among the highest per-capita implant procedure volumes globally.
Germany
EU MDR post-market surveillance mandates for Class III devices accelerate hospital procurement of silicone gel portfolios with documented biocompatibility profiles. Notified bodies enforce enhanced chemical characterization protocols under REACH Annex XVII restrictions. Maxillofacial centers in Bavaria and North Rhine-Westphalia deploy in-house CAD-CAM milling for porous polyethylene facial implants.
South Korea
MFDS regulatory pathways for facial implants support rapid adoption of patient-specific CAD-CAM designs in maxillofacial departments. Seoul Capital Area dermatology networks integrate thread-lift and micro-implant combination therapies. Busan-Ulsan surgical clusters compress operative turnaround through distributed manufacturing workflows.
India
PLI scheme incentives for domestic medical device manufacturing precede scale-up of imported silicone portfolios in metro hospital chains. CDSCO regulatory harmonization with global standards shapes multinational market entry strategies. Mumbai and Delhi cosmetic surgery units establish dedicated aesthetic infrastructure ahead of local production expansion.
Global Cosmetic Implants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across reimbursement pathway access and surgeon training network depth. The vendor base stratifies between diversified healthcare conglomerates with aesthetic divisions and specialized implant manufacturers with focused silicone portfolios. Three strategic archetypes dominate: integrated healthcare multinationals leveraging reconstructive reimbursement channels, pure-play aesthetic device specialists controlling direct distribution, and diversified materials science companies extending polymer expertise into implantable applications. Competitive moves concentrate on selective portfolio pruning to absorb EU MDR compliance costs and backward integration into high-purity silicone precursor supply.
Within the integrated healthcare multinational tier, AbbVie Inc. and Johnson & Johnson occupy positions anchored by established FDA approval histories and extensive surgeon training infrastructures. Sientra Inc. exemplifies the pure-play aesthetic specialist archetype through proprietary silicone formulations and controlled direct-to-physician distribution. These three entities collectively represent the competitive structure spanning diversified conglomerate, specialized device, and materials science positioning vectors.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Johnson & Johnson |
| Sientra Inc. |
| GC Aesthetics |
| POLYTECH Health & Aesthetics |
| Establishment Labs Holdings Inc. |
| 3M Company |
| Dentsply Sirona Inc. |
| Zimmer Biomet Holdings Inc. |
| Others |
Supply & Pricing Matrix
Plastic surgery clinic procurement committees concentrate purchasing authority for silicone breast implants, anchoring a three-tier pricing structure across premium, standard, and economy levels that stratifies by FDA premarket approval tier and surgeon training network depth.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates established silicone gel portfolios with documented biocompatibility from mid-tier saline alternatives and entry-level hydrogel configurations. Price differentiation hinges on FDA PMA certification tier and volume procurement scale, with premium capture strongest in reconstructive reimbursement pathways. Pricing pressure stems from EU MDR compliance cost absorption among European manufacturers. Ambulatory surgery centers in Latin America exhibit highest price sensitivity, while United States academic medical centers tolerate premium positioning for established safety registries.
Supply Chain Analysis
Explant retrieval and post-market surveillance sample flows reverse through manufacturer-managed logistics networks to centralized biocompatibility testing facilities in Germany and the United States. Raw material supply concentrates among three specialty chemical suppliers in Germany, Japan, and the United States controlling medical-grade silicone precursor production. Shell fabrication draws from elastomer compounding expertise in Bavaria and Osaka, while final assembly clusters in Costa Rica and Ireland for FDA and EU market access. Single-source vulnerability in high-purity silicone monomer supply exposes margin volatility to semiconductor industry demand cycles. Distribution runs through direct-to-physician platforms and hospital procurement committees in parallel channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cosmetic implants market compounds steadily as aging demographics and reconstructive oncology pathways sustain procedure volume expansion across mature and emerging economies.
For Market Incumbents: Extend surgeon training network coverage into tier-two metropolitan markets ahead of mid-cap entrant certification investments. Deepen backward integration into medical-grade silicone precursor supply to defend margin position against specialty chemical supplier concentration. Absorb EU MDR compliance costs through selective portfolio pruning rather than price pass-through to maintain hospital procurement preference.
For New Entrants and Emerging Players: Begin with gender affirmation surgery centers in Thailand and Spain as the most penetrable white-space channel, where specialized surgical infrastructure outpaces established implant manufacturer coverage. Target direct-to-physician digital platform partnerships to bypass entrenched hospital procurement committee relationships. Prioritize porous polyethylene facial implant portfolios where CAD-CAM distributed manufacturing lowers capital barriers versus silicone breast implant PMA pathways.
For Investors and Strategic Acquirers: Diversified healthcare conglomerates with aesthetic divisions represent the most active acquirer category in this space, seeking reconstructive reimbursement channel access. Acquisition target archetypes include pure-play facial implant specialists with in-house milling capabilities and established MFDS or ANVISA regulatory footholds. Monitor EU MDR notified body capacity constraints as inflection signal for compliance cost absorption timelines and portfolio rationalization waves.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Silicone gel breast implant submissions require 18-36 month review windows with mandatory adjunct study commitments. |
| EU MDR CE Marking Transition | Class III implantable devices face heightened clinical surveillance obligations and enhanced chemical characterization protocols. |
| Hospital System Partnership | France and Germany now require structured long-term safety data for post-mastectomy reconstruction procurement. |
| Backward Integration | Captive supply of medical-grade silicone precursors reduces exposure to semiconductor industry demand cycle volatility. |
| Software Companion Development | Surgeon-facing inventory management applications with embedded training modules displace traditional distributor relationships. |
Research Methodology
Bottom-up plastic surgery clinic demand modeling reconciled against top-down silicone precursor supply tracking forms the analytical core. Primary interviews with plastic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers triangulate against secondary validation from FDA PMA filings, EU MDR notified body technical file databases, ANVISA vigilance registries, and hospital procurement contract disclosures.
Historical procedure volume trendlines across breast, facial, and body implant categories inform projection frameworks segmented by material composition, application pathway, and end-user channel throughout the forecast period. CAGRs derive from elasticity-adjusted demand curves incorporating reimbursement pathway expansion, regulatory approval timeline compression, and surgeon workforce growth assumptions.
Several conditions sit outside the modeled scope, including 3D bioprinting technology commercialization timelines and stem cell-matrix implant regulatory pathway development. Forecasts reflect documented assumptions regarding EU MDR implementation consistency and notified body capacity expansion. Practitioners should monitor REACH Annex XVII silicone oligomer restriction enforcement and MFDS facial implant approval velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Injection Practice Pad Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Global Intragastric Balloon Market
Medical Devices
Global Nebuliser Market
Medical Devices
Snoring Control Devices Market
Medical Devices
Ventilation Devices Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Gastric Electrical Stimulators Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
Pharmacy Automation Devices Market