
 Mexico Ultrasound Devices Market | 2026-2036
Mexico Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Ultrasound Devices Market Foresight
Trained sonographer availability is collapsing across northern Mexico, forcing equipment vendors to bundle AI-assisted image acquisition with hardware sales. GE Healthcare leverages automated measurement protocols to reduce operator dependency in understaffed facilities. Mindray Medical International Limited anchors its position through cost-engineered portable systems that compete on total cost of ownership in state hospital tenders. Samsung Electronics differentiates via semiconductor integration, controlling chip supply for its digital beamforming architectures.
Ultrasound devices generate acoustic images through piezoelectric transducer arrays operating at frequencies from two to fifteen megahertz, converting reflected sound waves into real-time anatomical visualizations for non-invasive diagnostic and interventional guidance. Diagnostic ultrasound systems dominate installed base value across Mexican facilities, while portable ultrasound captures the fastest expansion trajectory as point-of-care protocols spread to rural clinics and emergency departments. Doppler ultrasound technology leads cardiac and vascular applications, with 4D ultrasound commanding premium placement in obstetrics suites of Mexico City metropolitan hospitals.
COFEPRIS, the national health regulator, enforces medical device registration and post-market surveillance that shapes product entry timelines and clinical evidence requirements for ultrasound manufacturers. NOM-087-ECOL-SSA1 standards govern electromagnetic emissions and electrical safety, filtering non-compliant equipment from institutional procurement channels. Stakeholders must monitor whether Mexico's pending alignment with FDA recognition agreements accelerates parallel approval pathways for advanced imaging platforms.
Market Dynamics
COFEPRIS registration timelines and COBEFES accreditation mandates are compressing procurement cycles across Mexican states, forcing vendors to pre-certify hardware platforms before tender participation.
Growth Catalysts
- COBEFES Equipment Accreditation:Tighter imaging standards across public hospital networks are mandating digital Doppler upgrades in tertiary care facilities.
- Point-of-Care Protocol Expansion:Emergency departments in Monterrey and Guadalajara are deploying portable systems for trauma triage and bedside cardiac assessment.
- AI-Assisted Image Acquisition:Automated measurement protocols are reducing operator dependency as sonographer availability contracts in northern border states.
Market Restraints
- Piezoelectric Crystal Supply Concentration:Transducer manufacturing depends on specialized ceramic suppliers concentrated in East Asian production clusters.
- COFEPRIS Evidence Requirements:Post-market surveillance mandates extend product entry timelines by requiring clinical validation datasets for novel beamforming architectures.
- Radiology Resident Pipeline Collapse:Training program capacity constraints in Mexican medical schools limit deployment of advanced 4D obstetric systems.
Strategic Opportunities
- Rural Clinic Connectivity:Tele-ultrasound platforms enable remote specialist interpretation for isolated facilities in Chiapas and Oaxaca.
- State Hospital Leasing Models:Equipment-as-a-service structures reduce capital barriers for IMSS-affiliated facilities in secondary cities.
- NOM-087-ECOL-SSA1 Compliance Arbitrage:Vendors with pre-certified electromagnetic safety profiles capture accelerated procurement pathways.
Industry Challenges
- Legacy Analog System Integration:Digital platform deployment requires parallel maintenance of obsolete hardware in underfunded regional hospitals.
- Interventional Ultrasound Training Gaps:Biopsy and vascular access guidance protocols demand specialized physician certification unavailable outside Mexico City metropolitan training centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Ultrasound Devices Market |
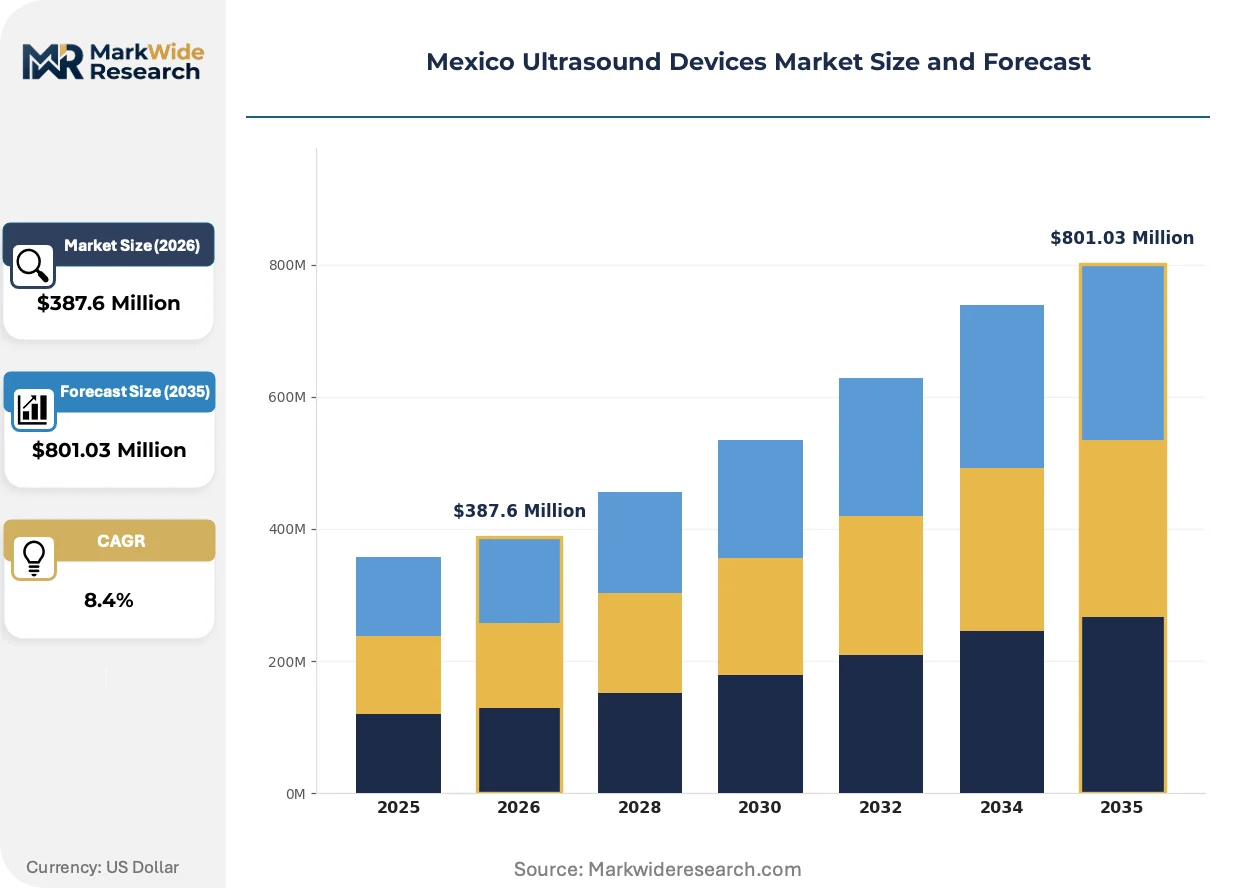
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound, Therapeutic Ultrasound, 3D Ultrasound, Portable Ultrasound End User: Hospitals, Clinics, Research Institutes, Home Care Technology: Analog Ultrasound, Digital Ultrasound, Doppler Ultrasound, 4D Ultrasound Application: Obstetrics, Cardiology, Musculoskeletal, Urology |
| Companies Covered | Canon Medical Systems Corporation, Samsung Electronics, GE Healthcare, Esaote, Mindray Medical International Limited, Siemens Healthineers, Fujifilm Holdings Corporation, Hologic, Koninklijke Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Ultrasound Devices Market Shifts & Advancements
Semiconductor integration and automated image processing are compressing the performance gap between premium cart-based systems and portable units across Mexican healthcare networks.
Digital beamforming architectures with in-house chip fabrication are supplanting analog delay-line systems in mid-tier hospital procurements. State health secretariats in Nuevo León and Jalisco are specifying semiconductor-integrated platforms for tender eligibility. This transition is compressing price premiums for advanced imaging capabilities previously restricted to academic medical centers.
COFEPRIS alignment discussions with FDA recognition agreements are accelerating parallel approval pathways for advanced imaging platforms. Manufacturers with existing 510(k) clearances are pre-positioning technical files for streamlined Mexican registration. Diagnostic ultrasound vendors with dual-jurisdiction portfolios are capturing first-mover advantage in digital Doppler segments.
Hospital purchasing cooperatives are consolidating procurement authority for imaging equipment across state health systems. Traditional distributor networks face margin compression as IMSS and ISSSTE centralize tender administration. This concentration is most visible in Mexico City where metropolitan hospital networks negotiate enterprise-scale maintenance contracts independent of equipment vendors.
Mexico Ultrasound Devices Market Segmentation
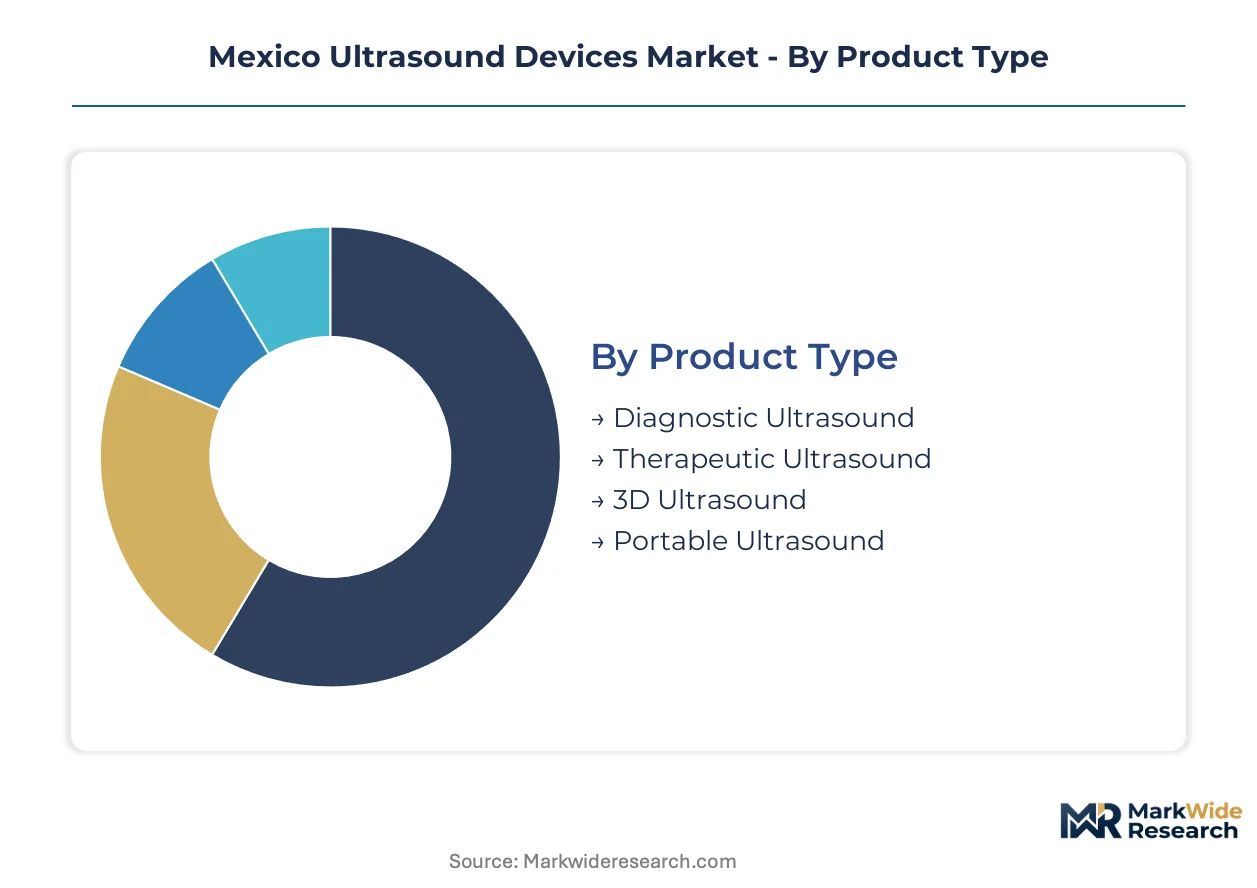
Ultrasound device segmentation in Mexico reflects divergent procurement priorities across public hospital networks, private clinic chains, and emerging point-of-care settings. Equipment specifications, connectivity requirements, and operator skill levels create distinct margin pools that vendors must target through differentiated platform architectures.
Product Type:
Margin concentration sits in systems that balance advanced imaging capability with total cost of ownership compliance for state tender processes.
- Diagnostic Ultrasound:Cart-based systems with transducer arrays operating across two to fifteen megahertz frequencies constitute the revenue foundation. IMSS tertiary facilities in Mexico City and Monterrey prioritize these platforms for comprehensive radiology departments, though procurement cycles stretch twelve to eighteen months under COFEPRIS registration requirements.
- Portable Ultrasound:Battery-powered units with semiconductor-integrated beamforming are displacing analog alternatives in emergency departments and rural clinics. Jalisco state health secretariat tenders now specify portable systems for secondary city hospitals, with Nuevo León following suit for trauma triage protocols.
- 3D Ultrasound:Volumetric imaging systems command placement in academic medical center obstetrics suites.
- Therapeutic Ultrasound:Phonophoresis and tissue heating applications concentrate in physical therapy departments of private hospital chains.
The dominant share belongs to Diagnostic Ultrasound, while Portable Ultrasound is gaining share fastest through point-of-care protocol expansion.
End User:
Customer type determines purchasing authority structure, with consolidated procurement cooperatives reshaping vendor access patterns.
- Hospitals:Tertiary care networks in Mexico City, Monterrey, and Guadalajara deploy enterprise-scale imaging fleets with centralized maintenance contracts. COBEFES accreditation mandates are forcing digital Doppler upgrades across these facilities, compressing replacement cycles for legacy analog installations.
- Clinics:Outpatient imaging centers in Guanajuato and Querétaro specialize in obstetric and vascular screening services. These operators prioritize semiconductor-integrated platforms that reduce per-scan labor costs amid sonographer shortages in central Mexican states.
- Research Institutes:Academic medical centers in Mexico City metropolitan area maintain experimental imaging protocols for clinical trial endpoints.
- Home Care:Post-acute monitoring applications remain nascent, limited by reimbursement frameworks and operator certification requirements.
Hospitals capture the dominant procurement volume, while Clinics are climbing the fastest as decentralized imaging networks proliferate.
Technology:
Architecture transitions create replacement demand windows, with analog-to-digital migration concentrated in mid-tier facility budgets.
- Digital Ultrasound:Beamforming architectures with in-house chip fabrication are supplanting analog delay-line systems across state hospital procurements. Jalisco and Nuevo León health secretariats now specify semiconductor-integrated platforms for tender eligibility, compressing price premiums previously restricted to academic centers.
- Doppler Ultrasound:Color flow mapping and spectral analysis capabilities dominate cardiac and vascular applications. Monterrey metropolitan hospitals deploy these systems for coronary assessment protocols, with demand reinforced by interventional cardiology expansion in Nuevo León.
- 4D Ultrasound:Real-time volumetric rendering commands premium placement in Mexico City obstetrics suites.
- Analog Ultrasound:Legacy delay-line systems persist in underfunded regional hospitals requiring parallel maintenance support.
Digital Ultrasound holds the dominant installed base position, while Doppler Ultrasound is expanding most quickly through cardiac application growth.
Application:
Clinical use case specialization drives transducer configuration requirements and software module pricing differentiation.
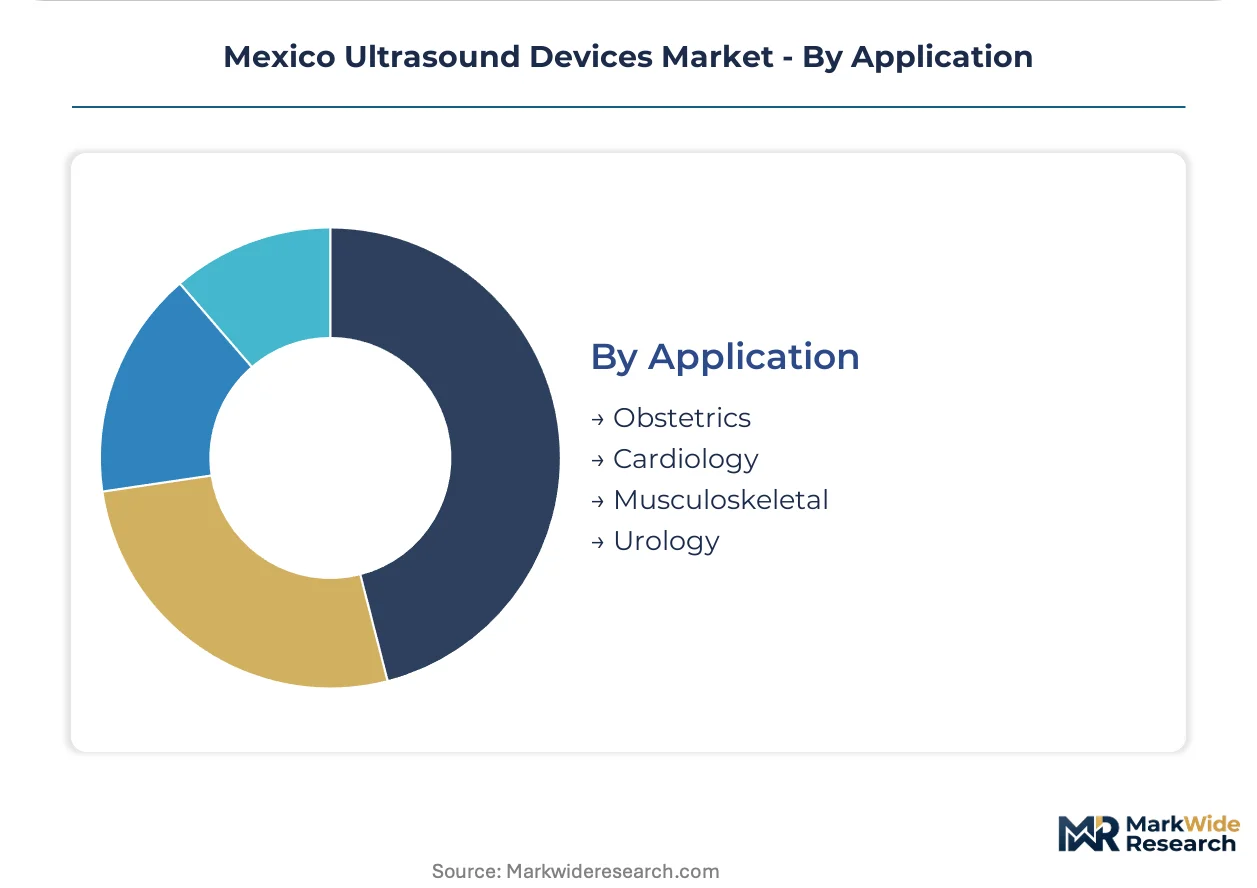
- Obstetrics:Fetal anatomical assessment and biometry protocols require curved array transducers with harmonic imaging optimization. 4D capabilities command premium placement in Mexico City metropolitan hospitals where maternal-fetal medicine subspecialization concentrates.
- Cardiology:Echocardiography and vascular access guidance demand phased array and linear transducers with Doppler functionality. Monterrey cardiac centers are expanding interventional ultrasound protocols, though physician certification gaps outside Mexico City constrain deployment velocity.
- Musculoskeletal:High-frequency linear arrays for tendon and joint assessment serve sports medicine and rheumatology practices.
- Urology:Transrectal and transabdominal prostate imaging applications concentrate in urology-focused hospital departments.
Obstetrics maintains the dominant application share, while Cardiology is closing the gap fastest through interventional protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico City commands pricing premiums for 4D obstetric systems while northern border states absorb cost-engineered portable units, creating a two-tier procurement geography that vendors must navigate through differentiated platform strategies.
Mexico City Metropolitan Area
Academic medical centers in Tlalpan and Coyoacán deploy enterprise-scale imaging fleets with centralized maintenance contracts. COFEPRIS registration requirements stretch procurement cycles to eighteen months for novel beamforming architectures. Maternal-fetal medicine subspecialization concentrates in Hospital General de México and Instituto Nacional de Perinatología, driving premium placement of real-time volumetric rendering systems.
Nuevo León
Monterrey metropolitan hospitals expand interventional cardiology protocols that demand Doppler functionality for coronary assessment. The state health secretariat now specifies semiconductor-integrated platforms for tender eligibility, compressing price premiums previously restricted to academic centers. Trauma triage protocols at Hospital Universitario drive emergency department deployment of battery-powered portable units.
Jalisco
Guadalajara's tertiary care networks upgrade digital Doppler capabilities under tightening COBEFES accreditation mandates. The state health secretariat tenders specify portable systems for secondary city hospitals, displacing analog alternatives. Outpatient imaging centers in Zapopan specialize in vascular screening services that prioritize semiconductor-integrated platforms.
Northern Border States
Sonora, Chihuahua, and Tamaulipas face collapsing sonographer availability that forces vendors to bundle AI-assisted image acquisition with hardware sales. IMSS-affiliated facilities in Ciudad Juárez and Tijuana rely on equipment-as-a-service structures to reduce capital barriers. Automated measurement protocols reduce operator dependency in understaffed regional hospitals.
Chiapas and Oaxaca
Isolated rural clinics in these southern states deploy tele-ultrasound platforms for remote specialist interpretation. Connectivity infrastructure gaps limit real-time transmission bandwidth for 4D volumetric datasets. State hospital leasing models from IMSS regional directorates reduce upfront capital requirements for secondary facilities in Tuxtla Gutiérrez and Oaxaca City.
Mexico Ultrasound Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Mexican procurement channels. The vendor base clusters around three strategic positions: semiconductor-integrated premium platforms, AI-assisted portable systems, and cost-engineered state-tender offerings. Consolidation pressure intensifies as hospital purchasing cooperatives centralize procurement authority across IMSS and ISSSTE networks. Dominant competitive moves include pre-certification of hardware platforms for COFEPRIS registration and enterprise-scale maintenance contract bundling.
Among diversified healthcare conglomerates, GE Healthcare and Siemens Healthineers occupy positions emphasizing automated measurement protocols and digital beamforming architectures. Samsung Electronics anchors the semiconductor-integrated tier through in-house chip fabrication for digital beamforming. Mindray Medical International Limited exemplifies cost-engineered portable systems that compete on total cost of ownership in state hospital tenders. Canon Medical Systems Corporation and Fujifilm Holdings Corporation represent imaging-focused specialists navigating procurement concentration in metropolitan hospital networks.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Samsung Electronics |
| GE Healthcare |
| Esaote |
| Mindray Medical International Limited |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Hologic |
| Koninklijke Philips |
| Others |
Supply & Pricing Matrix
Semiconductor-integrated beamforming architectures replacing analog delay-line systems are redrawing procurement economics across Mexican state hospital networks while simultaneously shifting vendor sourcing patterns toward East Asian chip fabrication clusters. This substitution dynamic compresses price premiums for digital Doppler capabilities previously restricted to academic medical centers, forcing legacy equipment vendors to absorb margin erosion or cede tender participation.
Pricing Analysis
Metropolitan hospital networks in Mexico City command 15-25% price premiums for 4D obstetric systems versus equivalent configurations procured by IMSS-affiliated facilities in northern border states. Pricing stratifies across three tiers: premium semiconductor-integrated platforms with AI-assisted acquisition, standard digital beamforming systems for secondary hospitals, and cost-engineered portable units for rural deployment. Cost compression in the standard tier is intensifying because Jalisco and Nuevo León health secretariats now specify chip-integrated architectures as baseline tender requirements. State hospital purchasing cooperatives exhibit highest price sensitivity, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Port congestion at Manzanillo and Lázaro Cárdenas elevates inbound logistics costs for transducer arrays and semiconductor components arriving from South Korea, Taiwan, and Japan. Piezoelectric crystal fabrication draws from specialized ceramic suppliers concentrated in Chinese and Japanese production clusters, while digital signal processors source from Taiwanese foundries. Single-source vulnerability concentrates in advanced beamforming chipsets where Samsung Electronics maintains captive supply advantages. Distribution runs through authorized medical device distributors with COFEPRIS import permits, though hospital purchasing cooperatives increasingly negotiate direct vendor relationships for enterprise-scale maintenance bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across Mexico's ultrasound market as point-of-care protocol expansion creates distinct procurement channels underserved by unified platform strategies. IMSS decentralization and state health secretariat autonomy generate niche positions for specialized vendors.
For Market Incumbents: Compound installed base advantages by embedding AI-assisted measurement protocols that reduce operator dependency in understaffed northern facilities. Defend against cost-engineered portable competitors through enterprise-scale maintenance contract bundling with Mexico City metropolitan hospital networks. Pre-certify hardware platforms for COFEPRIS registration to compress tender participation timelines.
For New Entrants and Emerging Players: After-sales service gaps in legacy analog system maintenance present white-space entry points for regional service specialists targeting underfunded hospitals in Chiapas and Oaxaca. Tele-ultrasound connectivity platforms for isolated rural clinics offer the most penetrable application layer. Pursue equipment-as-a-service leasing structures to bypass capital barriers at IMSS-affiliated secondary facilities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed medical device distributors holding COFEPRIS import permits and established relationships with state purchasing cooperatives. Long-term viability hinges on regulatory navigation capabilities rather than manufacturing scale. Monitor COFEPRIS-FDA recognition agreement progress as inflection signal for parallel approval pathway acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Pre-Certification Investment | Accelerates tender eligibility timelines for digital Doppler platforms across state hospital networks. |
| AI-Assisted Image Acquisition Development | Reduces operator dependency in northern Mexico facilities facing sonographer availability collapse. |
| Tele-Ultrasound Platform Deployment | Enables remote specialist interpretation for isolated rural clinics in Chiapas and Oaxaca. |
| Equipment-as-a-Service Leasing Models | Lowers capital barriers for IMSS-affiliated facilities in secondary cities and border states. |
| Semiconductor Integration Partnership | Secures chip supply for digital beamforming architectures specified in Jalisco and Nuevo León tenders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineers at IMSS tertiary facilities, GPO contracts managers, and ultrasound equipment distribution executives. Secondary validation drew from COFEPRIS medical device registration databases, state health secretariat tender documentation, hospital procurement records, and SEC filings of listed equipment manufacturers. Bottom-up installed base estimates triangulated against top-down healthcare expenditure projections.
Across the analysis window, forecasts incorporate product type segmentation by imaging capability tier, technology architecture by beamforming implementation, end-user channel by purchasing authority structure, and application specialization by clinical use case. CAGRs derive from replacement cycle analysis of legacy analog systems, point-of-care protocol diffusion rates, and state hospital budget allocation trends. Modeled inputs include sonographer training pipeline capacity, COBEFES accreditation mandate rollout schedules, and semiconductor supply availability for digital platform manufacturing.
Underlying assumptions cover stable COFEPRIS registration timelines, continued IMSS decentralization, and intact East Asian chip supply chains, with deviation risk concentrated in regulatory recognition agreement delays and piezoelectric crystal supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Middle East and Africa Biomedical Sensors Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Global Electronic Stethoscope Market
Medical Devices
India Diabetes Devices Market
Medical Devices
Global Wheelchair Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Slip Disc Market
Medical Devices
Middle East and Africa Orthotic Devices Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Surgical Robot Accessories Market
Medical Devices
Ambulatory Aids Market
Medical Devices
Global Medical Tricorder Device Market