
 Global Thrombectomy Devices Market | 2026-2036
Global Thrombectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thrombectomy Devices Market Foresight
Hospital procurement is narrowing around bundled stroke-care contracts that tie device supply to outcome metrics. Medtronic leverages its neurovascular portfolio to anchor integrated clot-retrieval workflows across major stroke networks. Stryker competes through its Trevo franchise and sustained investment in physician training infrastructure. Penumbra, Inc. differentiates via aspiration-first platforms that occupy the fastest-growing technical segment in peripheral thrombectomy.
Thrombectomy devices are catheter-based or endovascular instruments engineered to extract or dissolve intravascular clots, typically incorporating nitinol retrieval stents, aspiration lumens ranging from 0.060 to 0.088 inches, or ultrasonic energy delivery systems to restore perfusion in acute ischemic events. Mechanical systems dominate procedural volume in cerebrovascular applications where stent-retriever technology commands premium positioning, while aspiration platforms are accelerating fastest in peripheral artery and pulmonary embolism settings where large-bore catheter designs reduce blood loss and procedure time. Deployment through interventional labs and hospital-based settings captures the majority of value, though mobile stroke units and point-of-care configurations are emerging as structural growth pockets in rural and prehospital access models.
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards shape product development timelines and market access costs for manufacturers seeking multi-territory distribution. Japan's PMDA and South Korea's MFDS impose additional clinical evidence requirements that filter entrants and sustain incumbent advantage in East Asian markets. Stakeholders must monitor evolving reimbursement thresholds for mechanical thrombectomy in emerging stroke systems and anticipate how real-world evidence mandates will reshape competitive positioning across regulatory jurisdictions.
Market Dynamics
Hospital procurement teams are consolidating mechanical thrombectomy purchasing into bundled stroke-care contracts that tie device supply to clinical outcome metrics, compressing vendor margins while rewarding integrated workflow providers.
Growth Catalysts
- EU MDR conformity pathways:Accelerated CE marking timelines for stent-retriever systems are streamlining market entry across Western European stroke networks.
- Aspiration-first platforms:Large-bore catheter designs are displacing traditional retrieval methods in peripheral artery procedures due to reduced blood loss profiles.
- Japan's aging demographics:PMDA reimbursement expansions for endovascular stroke interventions are driving procedural volume in tertiary care centers.
Market Restraints
- Nitinol supply concentration:Shape-memory alloy sourcing clusters in specific Asian manufacturing zones create raw material vulnerability for retrieval stent production.
- 510(k) evidentiary burdens:FDA requirements for predicate device comparisons extend development timelines and inflate regulatory submission costs for novel catheter designs.
- Pharmacological substitution:Intravenous thrombolytics retain first-line protocol status in prehospital settings, limiting mechanical intervention to comprehensive stroke centers.
Strategic Opportunities
- Rural access models:Mobile stroke units equipped with portable imaging and telemedicine links are opening point-of-care thrombectomy in underserved US territories.
- Pulmonary embolism expansion:Aspiration catheter adaptations for venous clot extraction are penetrating interventional radiology suites previously dependent on surgical embolectomy.
- Real-world evidence mandates:Post-market surveillance requirements under Japan's PMDA are creating data partnerships between device manufacturers and academic medical centers.
Industry Challenges
- Interventionalist training pipelines:The specialized skill set for endovascular navigation and clot retrieval faces supply constraints relative to procedural demand growth.
- EU MDR technical documentation:Clinical evaluation report requirements for legacy stent-retriever systems are forcing retrospective data collection and notified body re-certification.
- Catheter-EMR integration:Procedural data capture from thrombectomy devices into hospital information systems requires custom interface development across heterogeneous platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thrombectomy Devices Market |
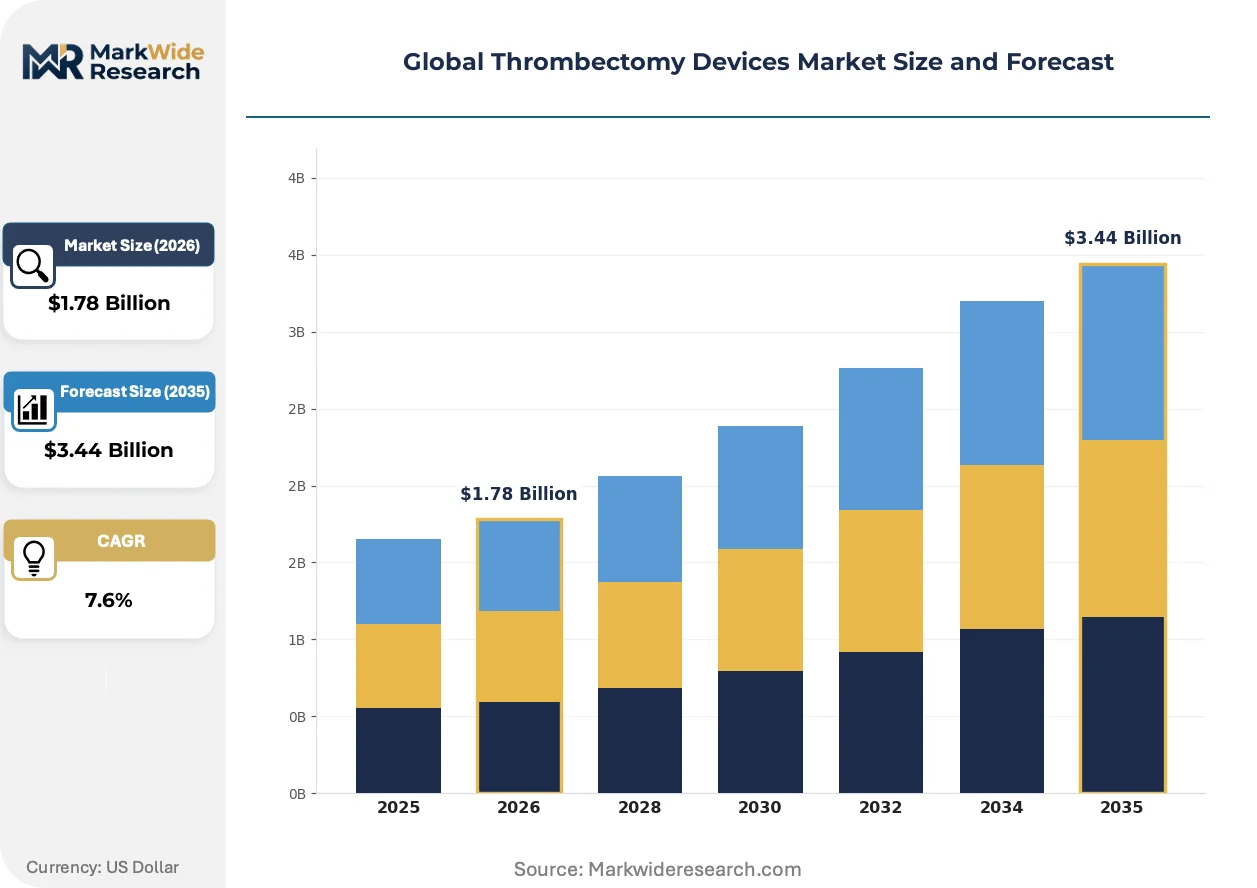
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.44 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Mechanical, Aspiration, Pharmacomechanical, Laser, Ultrasound Application Area: Cerebrovascular, Peripheral Artery, Deep Vein, Pulmonary Embolism, Portal Vein End User: Specialized Clinics, Ambulatory Surgical Centers, Cardiac Care Units, Interventional Labs, Diagnostic Centers Deployment Mode: Hospital-based, Mobile Units, Teleoperated Systems, Point-of-Care, Outpatient Facilities |
| Companies Covered | Medtronic, Stryker, Penumbra, Inc., Boston Scientific Corporation, Johnson & Johnson, Terumo Corporation, Teleflex Incorporated, Inari Medical, Inc., Edwards Lifesciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thrombectomy Devices Market Shifts & Advancements
Workflow digitization and outcome measurement integration are restructuring how thrombectomy systems are designed, procured, and deployed across acute care networks.
Artificial intelligence-enabled imaging analysis is digitizing clot characterization and treatment decision support. Stroke networks in Germany and the United States are piloting automated large-vessel occlusion detection algorithms that compress door-to-puncture intervals. This capability is digitizing triage protocols and redistributing procedural volume toward highest-volume centers.
EU MDR post-market clinical follow-up requirements are tightening surveillance obligations for mechanical thrombectomy devices. Manufacturers must now submit periodic safety update reports and proactive risk-benefit reassessments to notified bodies. Aspiration catheter portfolios face particular scrutiny given their rapid technical iteration cycles and limited long-term implant data.
Integrated service contracts are replacing transactional device purchasing in US academic medical centers. Procurement teams now bundle catheter supply with physician training, outcome reporting, and inventory management. This restructuring is most advanced in comprehensive stroke centers where bundled payments for acute ischemic stroke care create alignment incentives between suppliers and hospital systems.
Global Thrombectomy Devices Market Segmentation
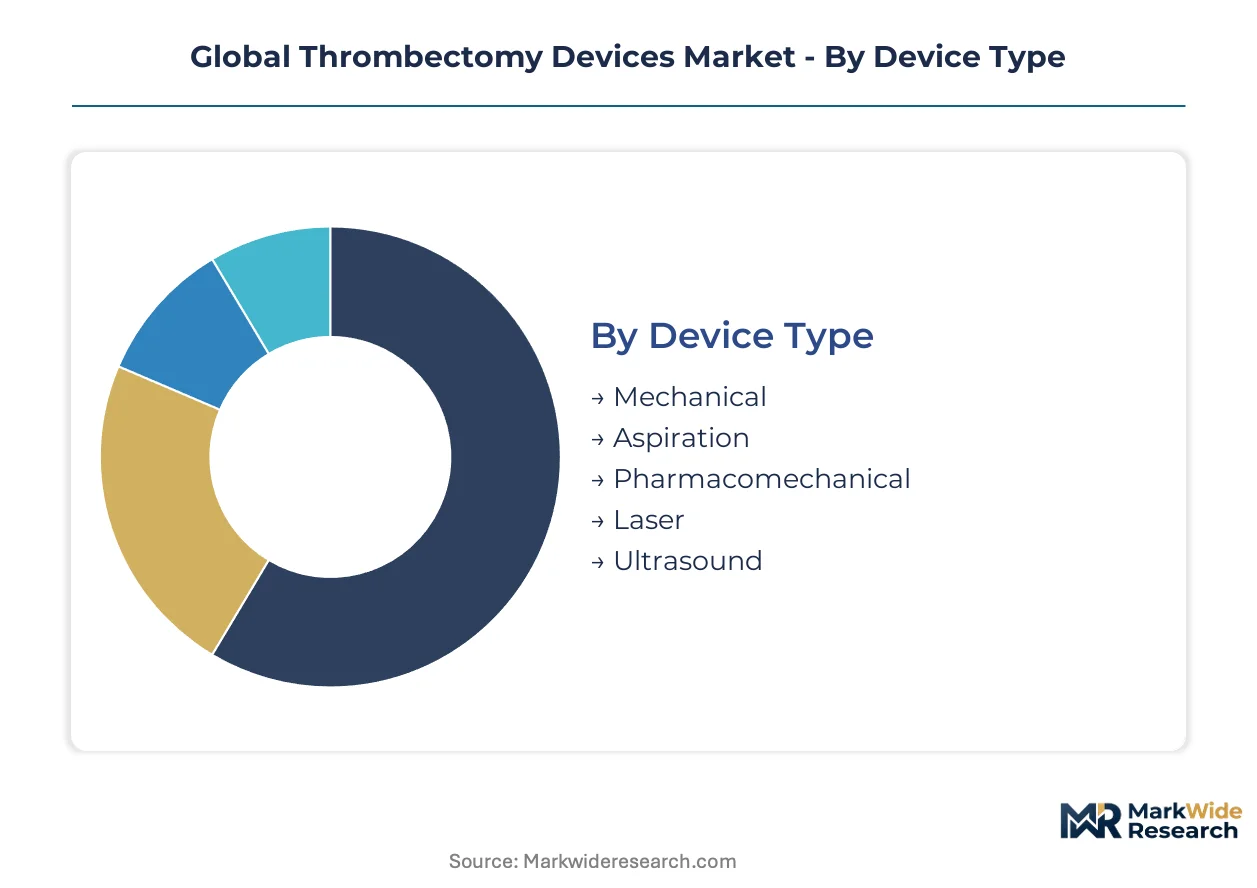
Thrombectomy device segmentation reveals how technical specifications, clinical settings, and care delivery models create distinct commercial battlegrounds. Manufacturers must align R&D investment and distribution strategy to the specific performance requirements and procurement patterns of each segment cluster.
Device Type:
Cost tier stratification separates premium retrieval technologies from commoditizing aspiration platforms, with reimbursement rates and material costs driving portfolio prioritization decisions.
- Mechanical:Stent-retriever systems utilizing nitinol cages and integrated delivery sheaths dominate cerebrovascular procedures. Demand concentrates in comprehensive stroke centers across the United States and Germany where favorable DRG reimbursement sustains premium pricing.
- Aspiration:Large-bore catheter designs with 0.060 to 0.088 inch lumens extract clots through negative pressure without permanent implant. Peripheral artery applications in interventional radiology suites are climbing the fastest as procedural volume shifts toward lower-acuity settings.
- Pharmacomechanical:Hybrid systems combine catheter-directed thrombolysis with mechanical disruption for complex occlusions.
- Laser:Photothermal ablation platforms target calcified thrombus in peripheral vessels.
- Ultrasound:High-frequency acoustic energy enhances clot dissolution without mechanical retrieval.
Mechanical systems hold installed capacity. Aspiration is rotating up the share rankings.
Application Area:
Clinical indication maturity determines competitive intensity, with established stroke pathways contrasting against emerging venous and pulmonary segments.
- Cerebrovascular:Large-vessel occlusion treatment commands the deepest clinical evidence base and strongest guideline support. Academic medical centers in Japan and the United States anchor procedural volume through tiered stroke center certification programs.
- Peripheral Artery:Limb salvage indications in diabetic and atherosclerotic populations drive chronic total occlusion interventions. German and US interventional cardiology practices are expanding fastest as outpatient lab capabilities mature.
- Deep Vein:Iliofemoral thrombus extraction prevents post-thrombotic syndrome in younger patient cohorts.
- Pulmonary Embolism:Intermediate-risk patient stratification is opening interventional alternatives to systemic thrombolysis.
- Portal Vein:Hepatocellular carcinoma and cirrhosis complications create niche procedural demand.
Cerebrovascular maintains procedural dominance. Pulmonary embolism is climbing fastest in share rankings.
End User:
Customer type concentration shapes sales force deployment and service contract structures across the care continuum.
- Specialized Clinics:Dedicated neurovascular and vascular centers concentrate high-complexity cases and physician expertise.
- Ambulatory Surgical Centers:Lower-acuity peripheral procedures are migrating to outpatient settings with streamlined reimbursement.
- Cardiac Care Units:Integrated cardiovascular service lines capture stroke and peripheral interventions through shared cath lab infrastructure.
- Interventional Labs:Hybrid operating rooms and dedicated endovascular suites represent the highest equipment utilization rates and steepest expansion trajectory among all end user categories.
- Diagnostic Centers:Pre-procedural imaging and triage functions create upstream influence over device selection.
Interventional labs hold installed capacity. Ambulatory surgical centers are rotating up the share rankings.
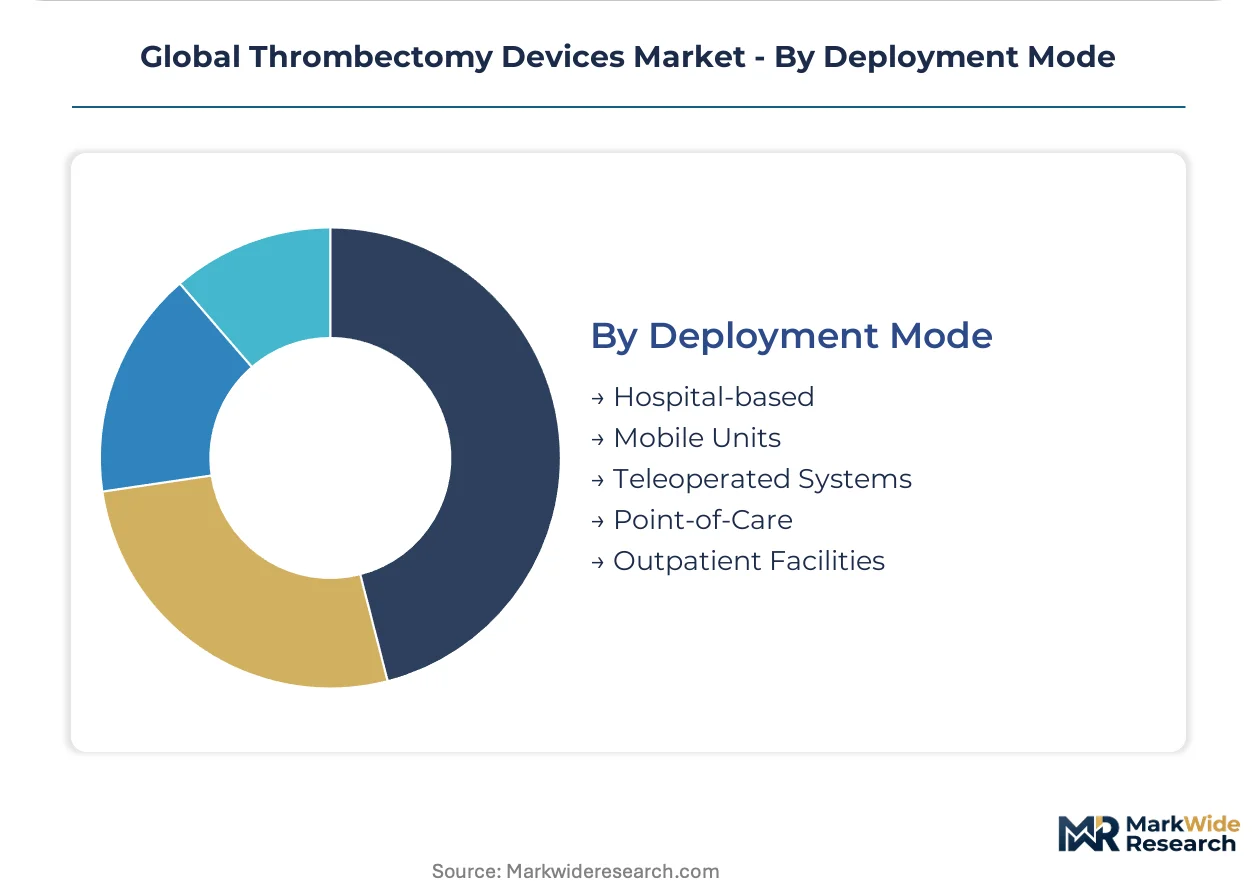
Deployment Mode:
Care delivery geography determines equipment portability requirements and regulatory pathways for prehospital intervention.
- Hospital-based:Fixed interventional suites in tertiary centers capture complex cases with full surgical backup.
- Mobile Units:CT-equipped ambulances with telemedicine links enable field triage and direct transport to thrombectomy-capable centers.
- Teleoperated Systems:Remote catheter manipulation platforms extend specialist reach into underserved territories.
- Point-of-Care:Portable aspiration systems for rural emergency departments are gaining share fastest as network hub-and-spoke models mature.
- Outpatient Facilities:Standalone vascular centers perform elective peripheral thrombectomy with same-day discharge protocols.
Hospital-based deployment holds installed capacity. Point-of-care configurations are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing in the United States sustains device margins that German and Japanese markets compress through reference pricing and DRG bundling. This asymmetry shapes manufacturer prioritization across regulatory jurisdictions.
United States
Comprehensive stroke center certification programs concentrate procedural volume in academic medical centers across Texas, Florida, and California. FDA 510(k) pathways accelerate stent-retriever introductions while bundled payment models tie device supply to outcome metrics. The Cleveland Clinic and Mayo Clinic networks anchor clinical trial infrastructure for next-generation aspiration platforms.
Germany
EU MDR conformity assessments streamline CE marking for mechanical thrombectomy systems entering Western European stroke networks. DRG reimbursement for endovascular procedures sustains hospital investment in interventional lab capacity. The Rhine-Ruhr and Bavarian medical technology clusters host notified body expertise and manufacturing partnerships for nitinol retrieval stents.
Japan
PMDA reimbursement expansions for acute ischemic stroke interventions drive procedural growth in tertiary care centers serving aging metropolitan populations. Post-market clinical follow-up requirements mandate periodic safety updates that filter market entrants. Tokyo and Osaka academic hospitals anchor real-world evidence partnerships between device manufacturers and stroke researchers.
United Kingdom
NHS England stroke service reconfigurations consolidate thrombectomy capability into hyper-acute stroke units across London, Manchester, and Birmingham. MHRA post-Brexit regulatory pathways maintain alignment with EU MDR technical standards while streamlining UK-specific market access. The Oxford-Cambridge life sciences corridor hosts clinical evaluation infrastructure for emerging aspiration catheter designs.
South Korea
MFDS clinical evidence requirements for novel catheter designs sustain incumbent advantage in East Asian markets while filtering smaller entrants. National health insurance reimbursement for mechanical thrombectomy expands procedural access beyond Seoul metropolitan stroke centers. The Songdo and Pangyo biotech clusters incubate domestic device development partnerships with global manufacturers.
Global Thrombectomy Devices Market Competitive Landscape
Integrated portfolio providers and aspiration-first specialists split the market between bundled stroke-care contracts and technical differentiation strategies. Tiered concentration prevails, with three to five manufacturers capturing majority procedural volume in cerebrovascular applications while peripheral segments fragment across catheter-focused entrants. Strategic archetypes include workflow integrators anchoring hospital system partnerships, technology specialists monetizing rapid product iteration, and regional champions leveraging domestic regulatory relationships. Competitive moves center on physician training infrastructure expansion and real-world evidence generation for reimbursement defense.
Among integrated neurovascular providers, Medtronic, Stryker, and Penumbra occupy positions spanning mechanical retrieval and aspiration platform portfolios. Medtronic exemplifies the workflow-integrator archetype through stroke network anchoring. Stryker represents sustained investment in physician training ecosystems. Penumbra sits within the aspiration-first technology specialist tier. These three manufacturers collectively illustrate how portfolio breadth and technical focus define competitive positioning across bundled procurement environments.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Penumbra, Inc. |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Terumo Corporation |
| Teleflex Incorporated |
| Inari Medical, Inc. |
| Edwards Lifesciences Corporation |
| Others |
Supply & Pricing Matrix
The Shanghai-Frankfurt air freight corridor transmits cost volatility from nitinol alloy sourcing clusters directly into configured-to-order stent-retriever premiums, while standard aspiration catheter pricing absorbs logistics compression through volume scale. This dynamic separates premium mechanical retrieval systems from commoditizing peripheral platforms.
Pricing Analysis
The customization-premium spread between configured-to-order stent-retriever systems and standard aspiration catheters spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FDA 510(k) clearance tier and bundled training service inclusion. Cost compression in economy aspiration segments is intensifying because hospital procurement teams consolidate stroke-care contracts. Academic medical centers exhibit lowest price sensitivity due to outcome-metric reimbursement, while ambulatory surgical centers face acute margin pressure.
Supply Chain Analysis
Export-control regimes on shape-memory alloy processing technology limit nitinol flow from specialized Taiwanese and Chinese manufacturing zones into European stent production. Supply concentration rests on Germany, Japan, and United States for precision catheter fabrication, with raw material dependencies spanning nickel-titanium alloys, laser-cut hypotubes, and hydrophilic polymer coatings. Single-source vulnerability concentrates in nitinol wire drawing capacity. Distribution runs through GPO-anchored hospital procurement networks with inventory managed by manufacturer field specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thrombectomy device market sits in procedural volume recovery following pandemic-era stroke center investment pauses, with aging demographics across OECD markets providing cyclical tailwinds.
For Market Incumbents: Pre-empt aspiration-first specialists by anchoring integrated workflow contracts across comprehensive stroke networks before bundled reimbursement matures. Threat from Penumbra's technical differentiation in peripheral segments demands counterinvestment in physician training infrastructure. Priority lever: backward integration into nitinol alloy processing to defend margin position against raw material volatility.
For New Entrants and Emerging Players: Pursue pulmonary embolism aspiration platforms where interventional radiology adoption curves remain underpenetrated relative to cerebrovascular saturation. White-space concentrates in intermediate-risk PE stratification protocols and rural point-of-care configurations. Go-to-market angle: telemedicine-linked mobile stroke unit partnerships bypassing incumbent hospital system lock-in.
For Investors and Strategic Acquirers: Aspiration-first technology specialists with CE marking momentum but limited US commercial infrastructure represent priority acquisition targets. Long-term viability frames around real-world evidence generation capabilities for PMDA and FDA post-market surveillance defense. Signal to watch: Japan's reimbursement expansion velocity for peripheral thrombectomy indications.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Locks procedural volume through bundled stroke-care contracts with outcome-metric alignment. |
| FDA 510(k) Submission | Accelerates market entry for next-generation aspiration catheter designs in cerebrovascular segments. |
| Physician Training Infrastructure | Builds switching costs through certified interventionalist pipelines tied to device platforms. |
| Reimbursement Strategy | Secures DRG category 1 status for mechanical thrombectomy in emerging stroke systems. |
| Software Companion Development | Integrates AI-enabled clot characterization into workflow digitization for comprehensive stroke centers. |
Research Methodology
A standing panel of interventional neuroradiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR technical documentation, CMS Medicare claims data, and hospital procurement databases. Bottom-up installation base modeling triangulated with top-down reimbursement flow analysis.
Scenario-bracketing anchored projections across the analysis window around high-case stroke center certification expansion and low-case pharmacological substitution protocols. Segmentation dimensions spanned device type, application area, end user category, and deployment mode. CAGRs derived from procedural volume elasticity to reimbursement threshold shifts and interventionalist training pipeline constraints.
Sensitivities concentrate around EU MDR notified body capacity constraints and PMDA real-world evidence mandate evolution. Forecasts reflect assumptions on bundled payment adoption velocity and nitinol supply concentration stability. Material shifts in FDA predicate device evidentiary requirements or Japan's reimbursement expansion trajectory would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
North America 3D Printing in Healthcare Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Soft Tissue Market
Medical Devices
Global Artificial Skin Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Veterinary Ventilators Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Global Hernia Mesh Devices Market
Medical Devices
Global Insufflation Devices Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
Global Joint Replacement Device Market