
 US Hospice Market | 2026-2036
US Hospice Market Size, Share, and Industry Trends Forecast 2026-2036
US Hospice Market Intelligence
Home-based referral networks is reshaping how hospice providers secure patient volume in the US. Amedisys leverages its home health infrastructure to create seamless care transitions. VITAS Healthcare anchors its position through hospital partnerships and physician outreach programs. Compassus differentiates via community-based palliative care integration that upstreams hospice-eligible patients.
Hospice care constitutes interdisciplinary end-of-life services encompassing pain management, symptom control, psychosocial support, and spiritual care delivered by teams of physicians, nurses, social workers, and chaplains. The primary purpose centers on quality-of-life optimization for terminally ill patients with prognoses of six months or less. Home Care commands the largest service type share as patients and families prioritize dying in residential settings over institutional environments. Inpatient Care generates concentrated margin pools through crisis symptom management and GIP-level reimbursement rates. Telehealth delivery mode exhibits the fastest expansion trajectory as CMS waivers permanently embed virtual visit allowances into hospice benefit structures.
CMS, the OIG, and state Medicaid agencies collectively govern hospice eligibility certification, capitation compliance, and fraud prevention through targeted medical review protocols. The Medicare Hospice Benefit payment structure directly shapes provider profitability through per-diem rates that incentivize length-of-stay optimization and routine home care utilization. Stakeholders must monitor proposed hospice payment reform rulemaking and site-neutral policy debates that threaten to compress reimbursement differentials between home and facility-based settings.
Market Dynamics
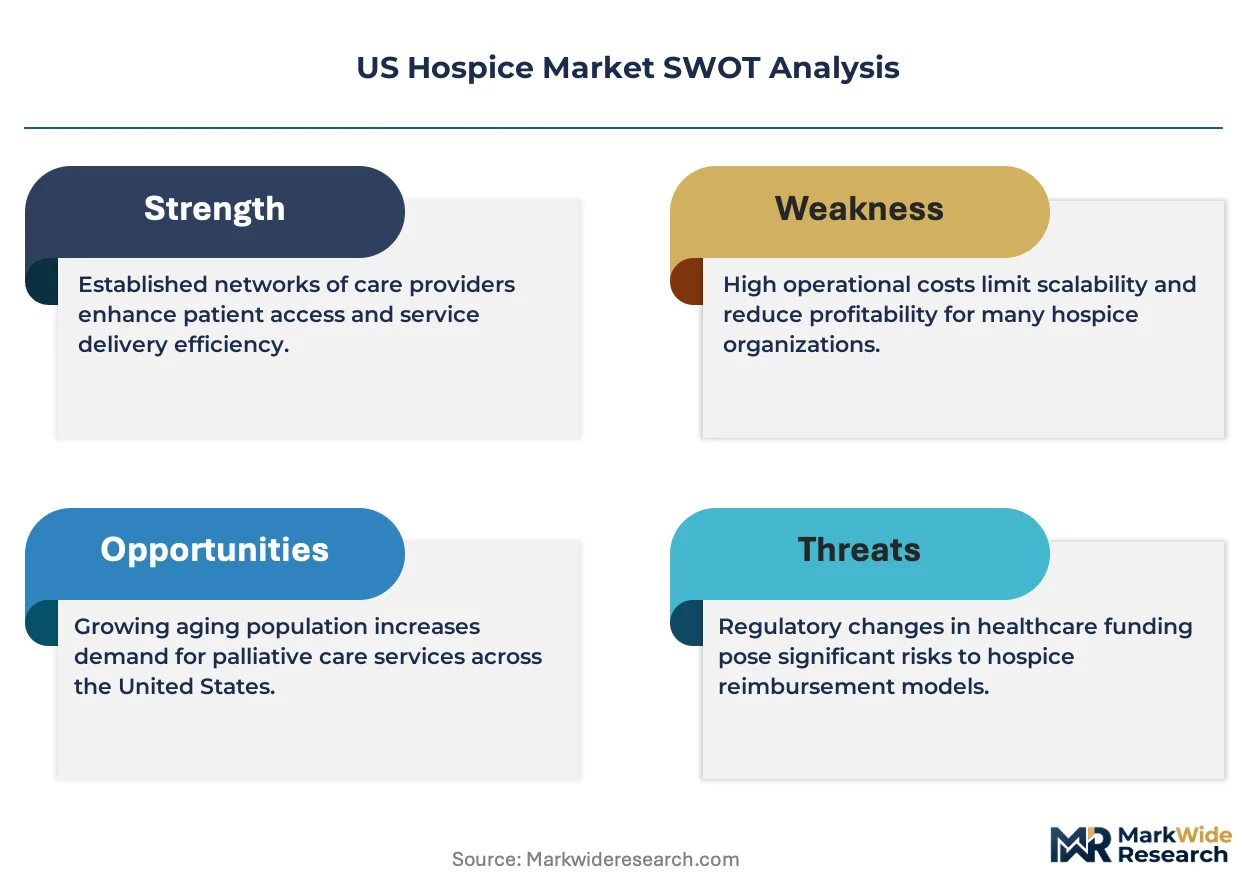
CMS site-neutral payment proposals are compressing reimbursement differentials between home-based and facility-based hospice delivery, forcing providers to recalibrate cost structures around routine home care intensity.
Growth Catalysts
- Medicare Hospice Benefit refinements:Per-diem rate adjustments for routine home care incentivize length-of-stay optimization and care continuity investments.
- Florida retirement migration:Dense aging-in-place populations in the Sun Belt generate concentrated patient volume and referral network density.
- Telehealth permanence:CMS waivers embedding virtual visit allowances enable remote symptom monitoring and family consultation expansion.
Market Restraints
- Capitation compliance burden:OIG medical review protocols and hospice eligibility certification requirements create administrative friction and audit exposure.
- Interdisciplinary staffing scarcity:Licensed clinical social workers and board-certified hospice physicians concentrate in metropolitan markets, leaving rural gaps.
- Institutional substitution risk:Palliative care program expansion within hospital systems upstreams patients before hospice election.
Strategic Opportunities
- Arizona and Texas geographic white space:Underserved rural counties in these states present first-mover advantages for community-based palliative care integration.
- Hospital-at-home convergence:Partnerships with acute care systems enable bundled payment participation and downstream hospice capture.
- IRA care coordination incentives:Medicare Advantage supplemental benefits for in-home supportive services create alignment opportunities with hospice providers.
Industry Challenges
- Electronic health record fragmentation:Disparate systems between home health, primary care, and acute settings impede seamless care transitions and referral tracking.
- Bereavement service scaling:Regulatory mandates for thirteen months of family follow-up strain social work capacity without direct reimbursement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hospice Market |
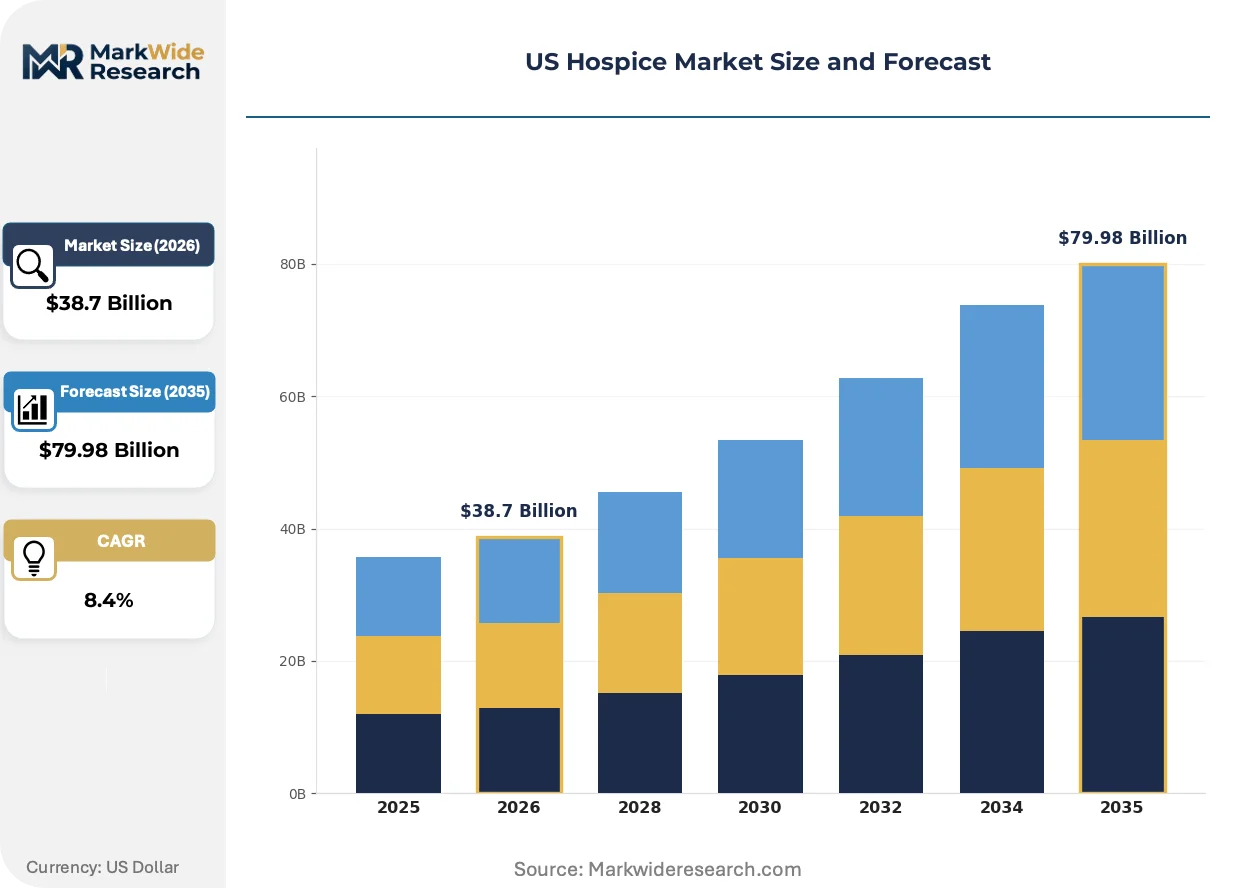
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inpatient Care, Home Care, Respite Care, Hospice Care Centers End User: Patients, Family Caregivers, Healthcare Professionals, Palliative Care Teams Delivery Mode: Telehealth, In-Person Visits, Consultations, Community-based Services Funding Source: Medicare, Medicaid, Private Insurance, Out-of-Pocket |
| Companies Covered | Amedisys, CURO Health Services, VITAS Healthcare, Empath Health, Compassus, Kindred Healthcare, Seasons Hospice & Palliative Care, LHC Group, HCR ManorCare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hospice Market Strategic Shifts & Innovations
Digital health infrastructure and payment model experimentation are restructuring how hospice services are delivered, measured, and reimbursed across the care continuum.
Remote patient monitoring platforms are collapsing the distinction between scheduled nursing visits and continuous oversight. Medicare-certified providers deploy biometric sensors and mobile symptom reporting tools to detect crisis escalations before emergency department utilization. This capability compression enables higher-acuity patients to remain in residential settings while reducing per-diem cost exposure.
CMS hospice payment reform rulemaking is recalibrating reimbursement weights toward care intensity metrics. The proposed structural shift from service volume to patient condition complexity threatens margin structures optimized for routine home care length-of-stay. Providers with advanced data infrastructure and predictive analytics capabilities are positioning to capture value-based payment pilots.
Family caregiver burden is driving demand for respite service innovation and volunteer program expansion. Adult children in multigenerational households seek temporary relief solutions that prevent nursing home placement and preserve hospice election eligibility. Texas and Florida markets exhibit the strongest program development activity, with faith-based organizations and community health workers filling formal service gaps.
US Hospice Market Segmentation
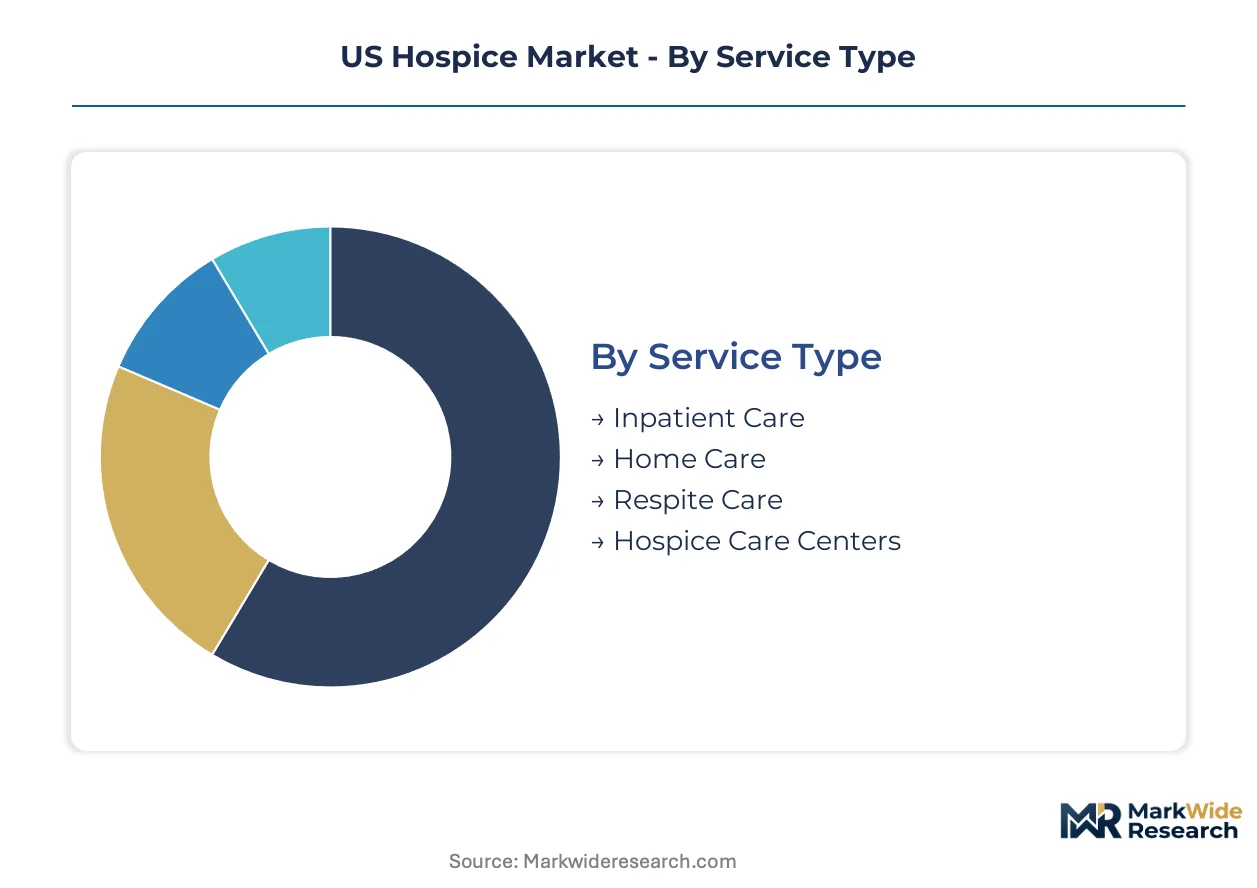
Hospice market segmentation reveals distinct operational models and reimbursement pathways that determine provider profitability. Each dimension captures different patient needs, regulatory requirements, and care intensity levels across the Medicare benefit structure.
Service Type:
Mature institutional formats coexist with emerging home-based modalities as CMS payment reforms reshape site-of-care economics.
- Home Care:Interdisciplinary teams deliver pain management, symptom control, and psychosocial support in residential settings. Florida, Texas, and Arizona concentrate demand where aging-in-place preferences intersect with Medicare-certified provider density and routine home care per-diem optimization.
- Inpatient Care:Crisis symptom management and General Inpatient (GIP) level services address uncontrolled pain or acute respiratory distress requiring 24-hour nursing supervision. Hospital-based units and freestanding facilities generate concentrated margin pools through higher reimbursement rates tied to intensity thresholds.
- Respite Care:Temporary institutional placement relieves family caregiver burden while preserving hospice election eligibility.
- Hospice Care Centers:Freestanding facilities bridge home and hospital environments for patients needing structured support without acute medical necessity.
Home Care retains volume leadership; Inpatient Care holds the steepest expansion curve as crisis intervention capabilities extend residential eligibility.
End User:
Customer archetypes span the clinical-to-familial spectrum with divergent decision authority and information needs.
- Patients:Terminally ill individuals with six-month or less prognoses who elect the Medicare Hospice Benefit and direct care preferences.
- Family Caregivers:Adult children and spouses managing medication schedules, symptom reporting, and advance care planning conversations.
- Healthcare Professionals:Primary care physicians and hospitalists certifying terminal prognosis and coordinating referral handoffs to hospice agencies.
- Palliative Care Teams:Hospital-based specialists upstreaming appropriate candidates before hospice election through concurrent care models.
Family Caregivers drive utilization decisions; Palliative Care Teams represent the fastest-growing referral channel as health system integration deepens.
Delivery Mode:
Technology infrastructure investments separate scalable virtual capabilities from labor-intensive in-person requirements.
- Telehealth:CMS waivers permanently embed virtual visit allowances enabling remote symptom monitoring, family consultation, and interdisciplinary team conferences across state lines.
- In-Person Visits:Scheduled nursing assessments, aide services, and chaplaincy contacts constitute the core benefit structure with defined frequency minimums.
- Consultations:Specialist physician availability for complex symptom management and medication regimen adjustments.
- Community-based Services:Volunteer programs, bereavement groups, and faith-based support networks extending formal care boundaries.
In-Person Visits anchor operational capacity; Telehealth climbs the fastest as remote patient monitoring platforms compress crisis detection timelines.
Funding Source:
Payer mix concentration determines revenue stability and administrative complexity exposure for certified providers.
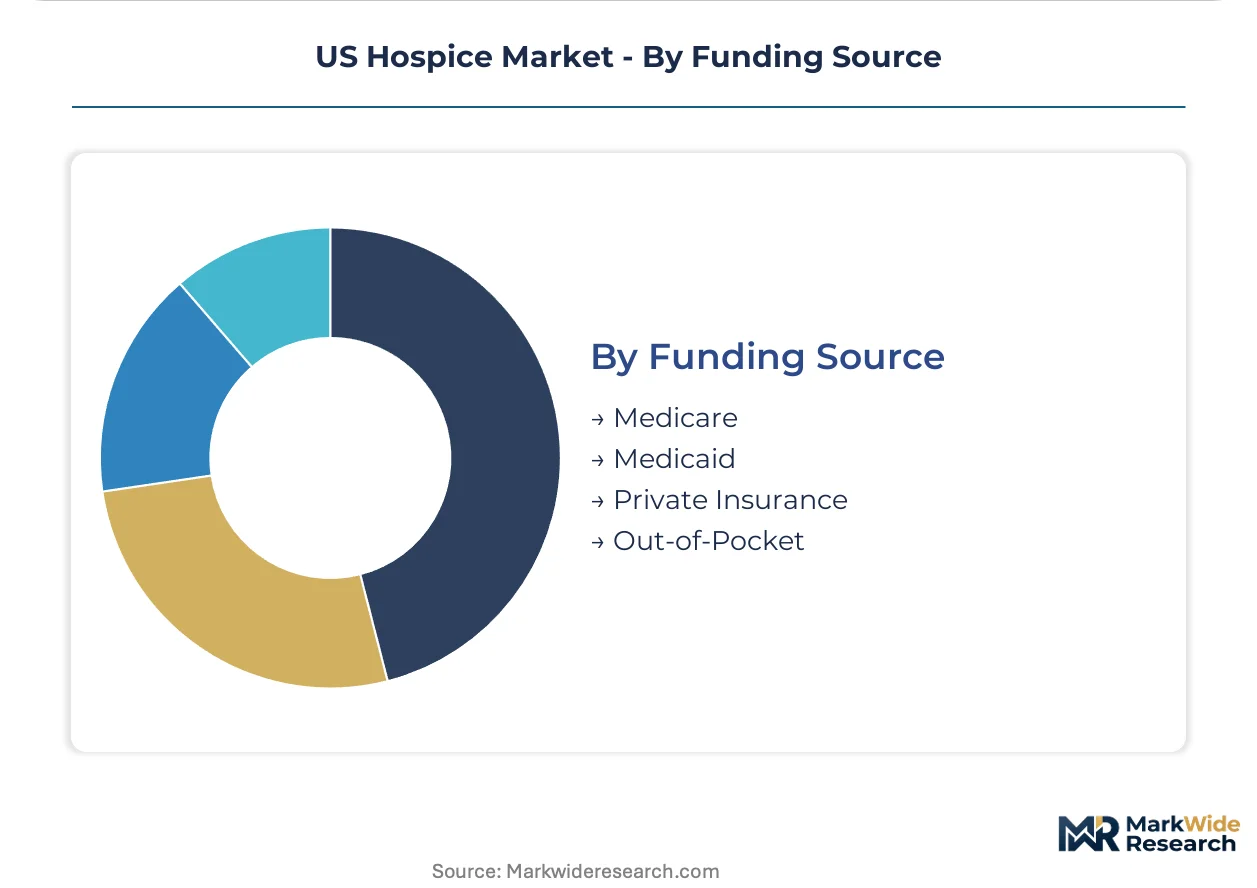
- Medicare:The Medicare Hospice Benefit dominates reimbursement through per-diem rates for routine home care, continuous home care, inpatient respite, and general inpatient levels.
- Medicaid:State plan coverage mirrors Medicare benefit structure with variable rate-setting methodologies and eligibility certification requirements.
- Private Insurance:Employer-sponsored and individual market policies supplement government programs with prior authorization protocols.
- Out-of-Pocket:Direct payment for non-covered services including private room differentials and alternative therapy modalities.
Medicare retains volume leadership; Private Insurance gains share fastest as Medicare Advantage supplemental benefit expansion creates alignment opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate highway network and Medicare administrative infrastructure underwrite geographic concentration patterns across the US hospice market, with patient volume clustering along retirement migration corridors and certified provider density zones.
Florida
Snowbird migration patterns and aging-in-place preferences concentrate Medicare-eligible populations across the Gulf and Atlantic coasts. State Medicaid agencies coordinate with CMS on hospice eligibility certification and capitation compliance protocols. The Tampa Bay and Orlando metropolitan areas anchor referral network density, with hospital-at-home partnerships expanding service footprints into surrounding rural counties.
Texas
Multigenerational household structures and Hispanic family caregiving traditions sustain home-based hospice demand across the Rio Grande Valley and Central Texas. The state's Health and Human Services Commission administers Medicaid hospice benefits with variable rate-setting methodologies. Dallas-Fort Worth and Houston medical centers drive hospital partnership activity, while Austin and San Antonio markets exhibit palliative care program expansion.
Arizona
Retirement community development and dry climate preferences attract terminal prognosis patients seeking residential end-of-life settings. Arizona Health Care Cost Containment System (AHCCCS) manages Medicaid hospice coverage with distinct eligibility pathways. The Phoenix-Tucson corridor concentrates provider competition, with rural counties in Northern Arizona presenting geographic white space for community-based palliative care integration.
California
Population aging and Medicare Advantage penetration create complex payer mix environments across coastal and inland markets. Department of Health Care Services (DHCS) oversees Medicaid hospice benefits with stringent medical review protocols. Los Angeles and San Francisco Bay Area markets face interdisciplinary staffing scarcity, while Central Valley counties exhibit underserved hospice access gaps.
Pennsylvania
Legacy hospital systems and long-term care facility density generate institutional referral channels in the Northeast and Midwest corridor. Pennsylvania Department of Human Services coordinates Medicaid hospice coverage with Medicare benefit alignment requirements. Pittsburgh and Philadelphia anchor academic medical center partnerships, with rural Appalachian counties experiencing workforce recruitment challenges.
US Hospice Market Key Industry Players
On the supply side, the industry is consolidating around integrated home health and hospice platforms with established Medicare certification infrastructure. National multi-site operators compete with regional specialists across routine home care, inpatient crisis management, and palliative care upstreaming. Two strategic archetypes dominate: vertically integrated home health-hospice hybrids leveraging care transition pathways, and hospital-anchored hospice divisions capturing downstream referrals. M&A activity concentrates on Medicare-certified agency acquisitions in Sun Belt markets, while strategic partnerships with acute care systems enable bundled payment participation.
Within the integrated home health-hospice tier, Amedisys and LHC Group exemplify platform consolidation strategies that collapse service boundaries between episodic skilled nursing and end-of-life care. VITAS Healthcare anchors the hospital-partnership archetype, representing referral capture models that embed hospice teams within acute care discharge planning. These three operators occupy positions across the competitive spectrum, with Amedisys and LHC Group emphasizing geographic density in Medicare Advantage markets while VITAS Healthcare concentrates on physician outreach and crisis intervention capabilities.
| Leading Market Players |
|---|
| Amedisys |
| CURO Health Services |
| VITAS Healthcare |
| Empath Health |
| Compassus |
| Kindred Healthcare |
| Seasons Hospice & Palliative Care |
| LHC Group |
| HCR ManorCare |
| Others |
Cost & Logistics Intelligence
Interstate freight corridors connecting the Sun Belt distribution hubs concentrate cost dynamics for hospice supply chains, compressing margins on rural deliveries while enabling tiered service pricing that differentiates routine home care from crisis intervention levels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs hospice reimbursement, with Medicare per-diem rates for routine home care anchoring the standard tier, General Inpatient intensity thresholds commanding premium rates, and volunteer-supported community services filling economy gaps. Price differentiation hinges on care intensity certification and geographic accessibility, with rural delivery surcharges widening spreads. Pricing pressure stems from CMS site-neutral proposals compressing facility-home differentials. Family caregivers in multigenerational households exhibit highest price sensitivity, while hospital systems negotiating bundled payments show lowest.
Supply Chain Analysis
Upstream feedstock for hospice services draws from licensed clinical social worker pipelines concentrated in Florida, Texas, and California metropolitan markets, with board-certified hospice physician training programs clustered in academic medical centers across Pennsylvania and New York. Medical equipment dependencies span biometric monitoring devices, durable medical equipment, and pharmaceutical formularies for symptom management. Supply chain risk centers on interdisciplinary staffing scarcity creating single-source vulnerability for rural service expansion. Distribution runs through Medicare-certified agency networks with hospital partnership anchoring referral density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospice operators should treat community-based palliative care integration as a service-attach opportunity, given upstream care coordination revenues expanding faster than core per-diem reimbursement through Medicare Advantage supplemental benefit structures.
For Market Incumbents: Entrench position through backward integration into home health infrastructure that collapses care transition friction, while investing in predictive analytics capabilities to capture value-based payment pilots. Defend against hospital-at-home convergence threats by deepening acute care system partnerships that secure downstream hospice capture.
For New Entrants and Emerging Players: Rural counties in Northern Arizona and the Texas Rio Grande Valley present first-mover advantages where aging-in-place demand outpaces certified provider density. Target community-based palliative care integration as the most penetrable entry vector, leveraging faith-based volunteer networks as a low-capital go-to-market angle.
For Investors and Strategic Acquirers: Medicare-certified agencies with established CMS capitation compliance infrastructure and routine home care length-of-stay optimization capabilities represent the priority acquisition archetype. Monitor OIG medical review protocol intensity as the signal for regulatory risk inflection that reshapes valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Community-Based Palliative Care Integration | Upstream patient capture before hospice election strengthens referral pipeline density. |
| Remote Patient Monitoring Platform Deployment | Biometric sensors extend residential eligibility while reducing emergency department utilization. |
| Hospital-at-Home Partnership Development | Acute care system alignment enables bundled payment participation and downstream hospice capture. |
| Medicare Advantage Supplemental Benefit Alignment | IRA care coordination incentives create revenue diversification beyond traditional per-diem structures. |
| Interdisciplinary Staffing Pipeline Investment | Licensed clinical social worker recruitment addresses rural service gaps and audit compliance requirements. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospice agency executives, Medicare reimbursement specialists, hospital discharge planners, and family caregiver advocacy organizations. Secondary validation drew from CMS Medicare cost reports, state Medicaid hospice rate filings, OIG medical review protocol documentation, and Medicare Advantage plan benefit design disclosures. Bottom-up patient volume modeling and top-down reimbursement trend analysis were triangulated against certified provider density maps.
Calibration across the analysis window applied service type segmentation by care intensity level, delivery mode by technology infrastructure requirement, and geographic cluster by retirement migration corridor concentration. CAGRs were derived from length-of-stay optimization trends and per-diem rate adjustment trajectories. Forecast inputs incorporated telehealth permanence policy embedding and site-neutral payment reform probability weighting.
Practitioners should monitor CMS hospice payment reform rulemaking and OIG audit intensity escalation for early signals of margin compression. Cross-checking against state Medicaid hospice rate-setting methodologies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
North America Healthcare Cold Chain Logistics Market
Healthcare Services
Regulatory Affairs Outsourcing Market
Healthcare Services
Assisted Living Market
Healthcare Services
Global Healthcare Contract Development and Manufacturing Organization Market
Healthcare Services
Healthcare Staffing Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Hospital Outsourcing Market
Healthcare Services
US Sterilization Services Market
Healthcare Services
Aged Care Market
Healthcare Services
Packaging and Labeling (Healthcare) Services Market
Healthcare Services
Canada Corporate Wellness Market
Healthcare Services
Hospice Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market