
 Autosamplers Market | 2026-2036
Autosamplers Market Size, Share, and Industry Trends Forecast 2026-2036
Autosamplers Market Intelligence
Subscription-based service contracts and remote diagnostic software is pivoting vendor-customer relationships from hardware transactions to recurring revenue models. Agilent Technologies leverages its global service infrastructure to lock in multi-year maintenance agreements across pharmaceutical accounts. Thermo Fisher Scientific anchors its position through integrated chromatography-autosampler platforms that reduce customer switching costs. Waters Corporation differentiates via specialized mass-spectrometry-compatible autosamplers that command premium positioning in biopharma quality control labs.
An autosampler is a precision electromechanical device that automatically introduces discrete sample volumes into analytical instruments such as gas or liquid chromatographs, typically achieving injection reproducibility within ±0.5% relative standard deviation through motorized syringe drives and inert fluidic pathways. Its primary purpose is to eliminate human variability, enable unattended overnight sequencing of hundreds of samples, and satisfy regulatory documentation requirements in pharmaceutical batch release and environmental compliance monitoring. Liquid chromatography autosamplers dominate installed base and aftermarket revenue given their ubiquity in drug purity analysis, while automated technology segments capture disproportionate growth as environmental labs replace manual protocols with robotic sample prep to meet tightening EPA detection limits. Quality control applications anchor near-term demand from generics manufacturers facing intensifying pharmacopeial scrutiny, whereas research and development segments in clinical research organizations show faster trajectory as biomarker quantification studies scale.
FDA 21 CFR Part 11 and EPA Good Automated Laboratory Practice standards shape software architecture and validation documentation requirements, compelling vendors to embed electronic signature workflows and tamper-evident data logging. ISO/IEC 17025 accreditation pressures in contract testing labs drive demand for autosamplers with certified calibration traceability and automated qualification protocols. EMA's Annex 11 guidance on computerized systems in GMP environments adds parallel compliance obligations for vendors serving European pharmaceutical manufacturers. Stakeholders must monitor evolving data-integrity enforcement patterns across FDA and EMA jurisdictions to anticipate retrofit cycles and qualification service opportunities.
Market Dynamics
Pharmaceutical batch release protocols are hardening around electronic data integrity requirements, forcing instrument vendors to embed audit-trail architectures directly into autosampler firmware rather than treating compliance as a software overlay.
Growth Catalysts
- EPA Method 8270 revisions:Environmental testing laboratories in the United States must achieve lower detection limits for semivolatile organic compounds, compelling replacement of manual injection systems with automated liquid handlers that eliminate operator-to-operator variability.
- Biopharma quality control expansion:Monoclonal antibody manufacturers are scaling batch release testing, driving demand for high-precision autosamplers capable of sub-microliter injection reproducibility in chromatography workflows.
- ISO/IEC 17025 accreditation pressure:Contract testing organizations require automated qualification protocols and certified calibration traceability to maintain laboratory accreditation status, prioritizing autosamplers with built-in diagnostic routines.
Market Restraints
- Precious metal fluidic pathway costs:Inert sample pathways requiring hastelloy or titanium construction face raw material price volatility from concentrated mining operations in South Africa and Russia.
- Single-source syringe drive motors:Precision stepper motors for sub-microliter dispensing originate from a narrow supplier base concentrated in Japan and Germany, creating procurement vulnerability.
- Legacy HPLC system incompatibility:Installed chromatography platforms from the 2010-2015 vintage lack the digital communication protocols required for modern autosampler integration, extending replacement cycles.
Strategic Opportunities
- Cell and gene therapy manufacturing:Emerging viral vector quantification workflows require novel autosampler configurations capable of handling high-viscosity biological matrices without sample degradation.
- India's pharmaceutical export growth:Active pharmaceutical ingredient manufacturers in Gujarat and Hyderabad are building analytical capacity to meet US FDA and EMA inspection standards.
- AI-driven predictive maintenance:Machine learning algorithms analyzing injection pressure traces and motor current signatures enable shift from scheduled to condition-based service interventions.
Industry Challenges
- Mechatronics engineering scarcity:The specialized intersection of precision fluid handling, embedded software, and regulatory documentation requires talent pools concentrated in Switzerland and Massachusetts.
- 21 CFR Part 11 validation timelines:Pharmaceutical customers demand documented IQ/OQ/PQ protocols that extend sales-to-revenue recognition cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autosamplers Market |
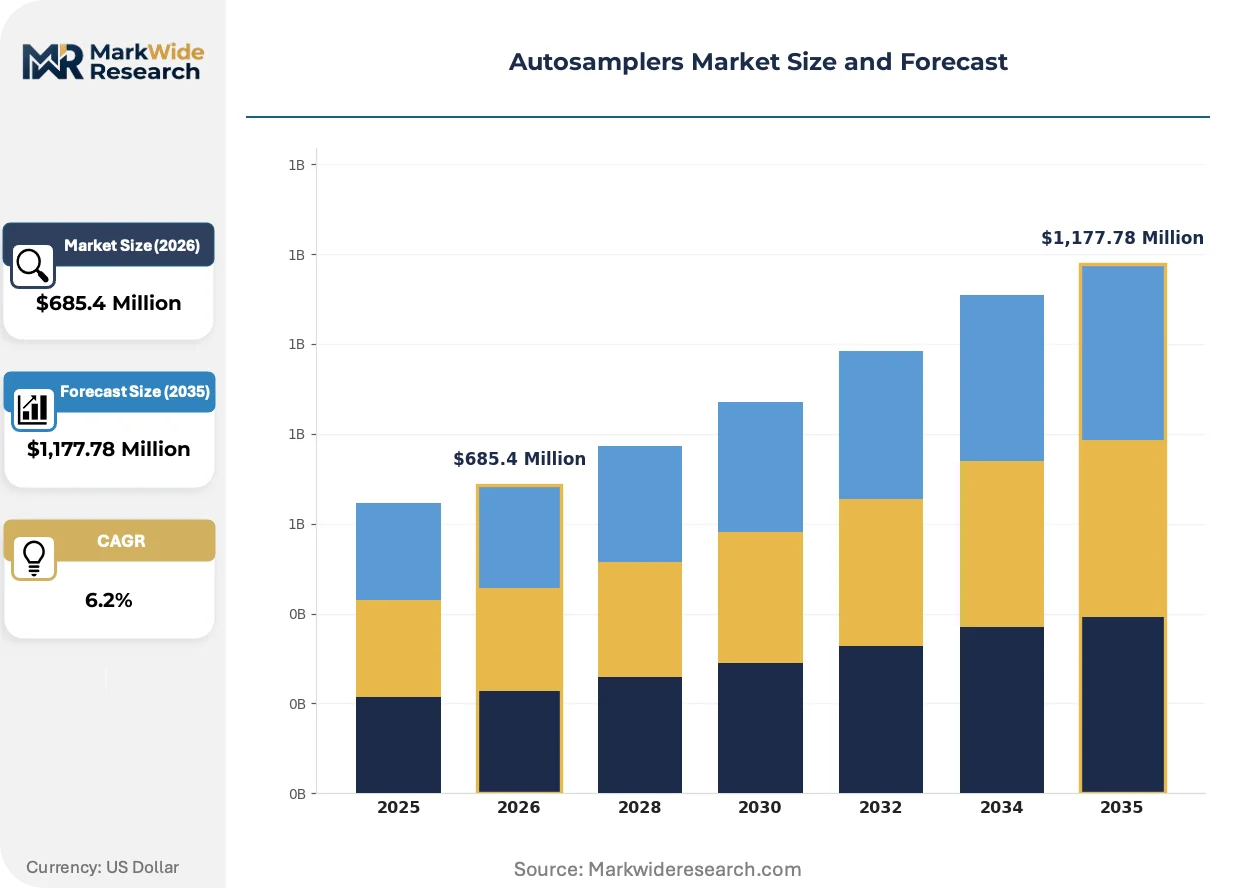
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Gas Chromatography, Liquid Chromatography, Solid Phase, Others End User: Pharmaceuticals, Environmental Labs, Food & Beverage, Clinical Research Technology: Manual, Automated, Semi-Automated, Portable Application: Quality Control, Research & Development, Compliance Testing, Process Monitoring |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, Waters Corporation, Shimadzu Corporation, PerkinElmer, Gilson, Restek Corporation, Bio-Rad Laboratories, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autosamplers Market Strategic Shifts & Innovations
Autosampler architectures are fragmenting into application-specific configurations as end-users reject universal platforms in favor of instruments optimized for particular sample matrices and throughput requirements.
Microfluidic sample preparation modules are modularizing liquid chromatography autosampler design, enabling pharmaceutical quality control labs to swap solvent exchange, derivatization, or solid-phase extraction cartridges without reconfiguring the core injection mechanism. Generic drug manufacturers in Eastern Europe are adopting these configurable systems to accommodate diverse pharmacopeial methods on single instrument footprints. This modularity is compressing capital equipment procurement cycles by allowing incremental capability expansion rather than full-system replacement.
FDA's evolving enforcement of 21 CFR Part 11 data integrity requirements is mandating tamper-evident audit trails with cryptographic hashing in autosampler software architectures. Instrument vendors must now embed electronic signature workflows and immutable timestamp logging at the firmware level rather than relying on external laboratory information management systems. Biopharma quality control laboratories in the United States are prioritizing autosamplers with native compliance architectures over lower-cost alternatives requiring extensive validation documentation.
Service contract unbundling is fragmenting traditional vendor-customer relationships as pharmaceutical procurement teams separate hardware acquisition from maintenance and qualification services. Large contract research organizations are negotiating direct relationships with third-party metrology providers for calibration and preventive maintenance, bypassing original equipment manufacturer service networks. This disintermediation is most pronounced in the United States, where centralized procurement functions at multinational pharmaceutical headquarters exert leverage over distributed laboratory operations.
Autosamplers Market Segmentation
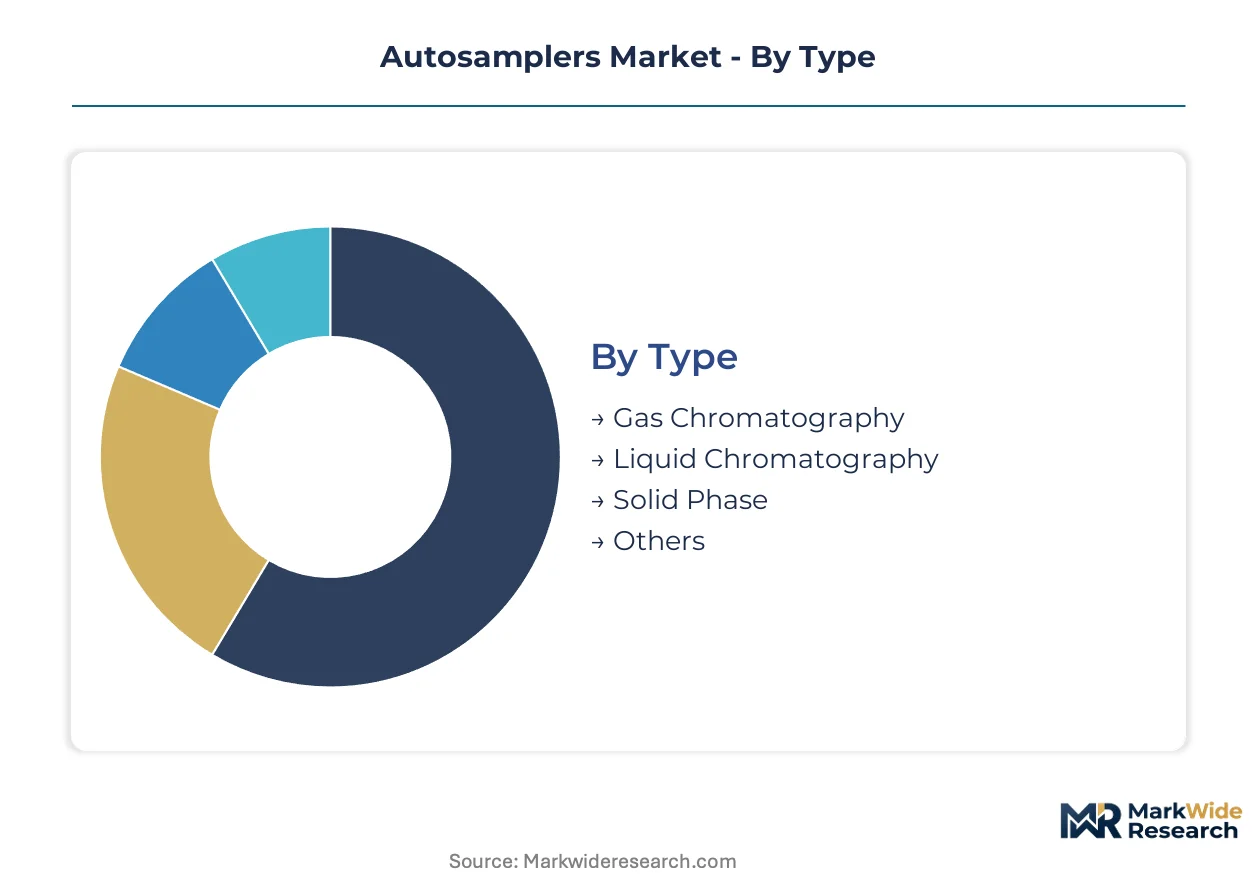
Autosampler purchasing decisions split sharply between high-volume routine screening and precision-critical biopharma workflows. Each segmentation axis reveals distinct procurement patterns: chromatography type determines capital intensity, end-use dictates compliance architecture, technology tier shapes staffing models, and application focus calibrates throughput versus sensitivity trade-offs.
Type:
Liquid chromatography autosamplers command the largest installed base while gas chromatography variants capture premium pricing through specialized detector integration.
- Liquid Chromatography:These systems handle aqueous and organic solvent matrices through motorized syringe drives achieving sub-microliter precision. Pharmaceutical quality control labs in the United States deploy these for drug purity batch release under FDA 21 CFR Part 11 protocols. Demand concentrates where high-throughput screening meets pharmacopeial documentation requirements.
- Gas Chromatography:Heated injection ports and inert sample pathways characterize these units for volatile and semivolatile compound analysis. Environmental testing laboratories facing EPA Method 8270 detection limit revisions are replacing manual injection with automated headspace and purge-and-trap configurations. Procurement accelerates where operator variability directly compromises compliance data.
- Solid Phase:Automated SPE cartridges integrate extraction and injection for complex biological matrices.
- Others:Specialized configurations include ion chromatography and supercritical fluid chromatography autosamplers for niche analytical methods.
Mature deployment sits with liquid chromatography systems in established pharmaceutical manufacturing. Newer deployment is concentrated in gas chromatography autosamplers as environmental labs modernize for tightened regulatory detection thresholds.
End User:
Pharmaceutical procurement drives qualification-intensive sales cycles while environmental and food testing segments prioritize throughput economics.
- Pharmaceuticals:Biologics manufacturers require autosamplers with embedded audit trails, electronic signatures, and automated IQ/OQ/PQ protocols. Monoclonal antibody producers in Massachusetts and Switzerland are scaling batch release capacity with mass-spectrometry-compatible injection systems. FDA and EMA inspection readiness dictates firmware-level compliance architecture over cost optimization.
- Environmental Labs:Commercial testing organizations face ISO/IEC 17025 accreditation pressure for documented calibration traceability. United States EPA enforcement of lower detection limits for semivolatile organics is forcing replacement of aging manual systems in regional water and soil analysis facilities. Procurement prioritizes diagnostic self-qualification to minimize external metrology costs.
- Food & Beverage:Contaminant screening and authenticity testing drive demand for robust sample handling of high-viscosity matrices.
- Clinical Research:Biomarker quantification studies in contract research organizations are expanding automated liquid handling for bioanalytical method development.
Pharmaceutical accounts anchor the premium tier through multi-year service contracts. Clinical research represents the steepest expansion trajectory as precision medicine trials scale biomarker analysis throughput.
Technology:
Automated platforms displace manual and semi-automated alternatives where labor costs and data integrity requirements intersect.
- Automated:Fully robotic sample handling with integrated barcode scanning, liquid-level sensing, and remote diagnostic capability defines this category. Pharmaceutical quality control operations in the United States and European manufacturing hubs are standardizing on unattended overnight sequencing to maximize instrument utilization. Embedded predictive maintenance algorithms are shifting service models from scheduled to condition-based interventions.
- Semi-Automated:Operator-mediated sample loading with automated injection execution offers intermediate positioning for mid-sized contract testing labs. Environmental laboratories in cost-constrained municipal settings deploy these for EPA compliance workflows where full automation cannot be capitalized. Procurement decisions weigh technician availability against throughput requirements.
- Manual:Basic syringe-based injection without motorized drives persists in academic research and teaching laboratories.
- Portable:Battery-powered field-deployable units serve on-site environmental monitoring and emergency response applications.
Automated technology dominates new capital allocation in regulated industries. Portable configurations are gaining share fastest in field-based environmental monitoring where laboratory infrastructure is absent.
Application:
Quality control applications demand validated reproducibility while research and development segments prioritize method flexibility.
- Quality Control:Pharmaceutical batch release and incoming raw material verification require documented injection precision within ±0.5% relative standard deviation. Generic drug manufacturers in India and Eastern Europe are building analytical capacity to meet US FDA and EMA inspection standards. Autosampler selection prioritizes native 21 CFR Part 11 compliance architectures over retrofit validation pathways.
- Research & Development:Method development and biomarker discovery workflows demand configurable injection parameters and rapid solvent switching. Clinical research organizations in the United States are scaling automated platforms for biomarker quantification studies. Procurement favors modular systems accommodating diverse sample matrices without hardware reconfiguration.
- Compliance Testing:Regulatory-mandated environmental and food safety monitoring drives standardized method execution.
- Process Monitoring:At-line and in-line autosampler integration supports real-time pharmaceutical manufacturing analytics.
Quality control commands the largest revenue share through replacement cycles tied to regulatory inspection schedules. Process monitoring is expanding most quickly as continuous manufacturing adoption accelerates real-time analytical integration.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Autosampler manufacturing concentrates in precision engineering clusters across Switzerland, Germany, Massachusetts, and Japan, while consumption spreads across pharmaceutical and environmental testing facilities in North America, Europe, and Asia-Pacific. This geographic split creates trade flows from component fabrication hubs to analytical laboratories in regulated markets.
United States
FDA 21 CFR Part 11 enforcement drives pharmaceutical quality control labs in Massachusetts and North Carolina to replace legacy systems with audit-trail-enabled autosamplers. Biologics manufacturers in the Boston-Cambridge corridor are scaling batch release capacity with mass-spectrometry-compatible injection systems. EPA Method 8270 revisions are forcing environmental testing facilities in California and Texas to automate semivolatile organic compound analysis.
Germany
EMA Annex 11 compliance obligations push pharmaceutical manufacturers in Baden-Württemberg and Bavaria toward integrated chromatography-autosampler platforms. The country's environmental laboratories face REACH-related detection limit requirements that favor robotic sample handling over manual protocols. Industrial clusters around Ludwigshafen and Leverkusen anchor demand from chemical quality control operations.
Switzerland
Swissmedic inspection standards and pharmacopeial documentation requirements sustain premium-tier autosampler procurement from biologics manufacturers in Basel and Zurich. The country's contract research organizations are expanding biomarker quantification capacity with unattended overnight sequencing systems. Precision mechatronics engineering talent concentrated in the Lake Geneva region supports domestic instrument development.
India
CDSCO alignment with US FDA inspection protocols drives active pharmaceutical ingredient manufacturers in Gujarat and Telangana to build analytical capacity with 21 CFR Part 11-ready autosamplers. The country's pharmaceutical export growth is compelling generic drug facilities in Hyderabad and Ahmedabad to upgrade from manual injection systems. Environmental testing labs in Maharashtra face tightening detection limits under national water quality monitoring programs.
Japan
PMDA quality system regulations and JIS calibration standards shape autosampler specifications for pharmaceutical manufacturers in Kanto and Kansai regions. The country's environmental monitoring networks are replacing aging manual systems to meet tightened MEE-equivalent detection protocols for persistent organic pollutants. Precision stepper motor suppliers concentrated in Nagoya and Osaka create upstream component advantages for domestic instrument assembly.
Autosamplers Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the autosampler market, with integrated chromatography vendors maintaining in-house manufacturing while specialized component suppliers focus on precision fluidic modules. The vendor base organizes around three strategic archetypes: full-platform integrators bundling autosamplers with chromatography systems, standalone autosampler specialists serving retrofit markets, and contract manufacturers producing subassemblies for branded instrument houses. Consolidation pressures are intensifying as pharmaceutical procurement teams centralize vendor relationships, while technology licensing agreements allow regional players to access precision drive motor designs without captive R&D investment.
Among diversified analytical instrument conglomerates, Agilent Technologies, Thermo Fisher Scientific, and Waters Corporation exemplify the integrated-platform archetype, anchoring competitive positioning through chromatography-autosampler bundling that raises customer switching costs. These entities occupy positions where multi-year service contracts and global qualification infrastructure lock in pharmaceutical accounts. Shimadzu Corporation and PerkinElmer represent the mid-tier diversified specialists, sitting within competitive terrain where regional service density and application-specific configurations matter. The standalone precision segment includes entities like Gilson and Restek Corporation, which exemplify focused positioning in sample preparation and chromatography accessories rather than full instrument platforms.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| Waters Corporation |
| Shimadzu Corporation |
| PerkinElmer |
| Gilson |
| Restek Corporation |
| Bio-Rad Laboratories |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
Hastelloy and titanium fluidic pathway costs cascade through three distinct pricing tiers as raw material volatility from South African and Russian mining operations compresses margins at the economy end while premium-tier vendors absorb volatility through long-term service contract bundling with pharmaceutical accounts.
Pricing Analysis
Cost-down pressure on economy-tier autosamplers accelerates because generic drug manufacturers in Eastern Europe prioritize capital expenditure minimization over embedded compliance architectures. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FDA 21 CFR Part 11-native firmware commands substantial premiums over retrofit-validated alternatives—while volume scale discounts concentrate among contract research organizations negotiating enterprise-wide instrument standardization. Price differentiation hinges on after-sales service bundling, with pharmaceutical quality control labs showing lowest price sensitivity due to inspection-readiness imperatives and municipal environmental labs exhibiting highest sensitivity amid constrained public procurement budgets.
Supply Chain Analysis
Single-source vulnerability sits with precision stepper motor suppliers concentrated in Nagoya and Osaka, Japan, and select German industrial clusters, where sub-microliter dispensing mechanisms draw from captive engineering expertise. Component fabrication anchors in Switzerland, Germany, Massachusetts, and Japan, with downstream distribution running through chromatography system integrators and specialized life science distributors serving pharmaceutical quality control installations. Supply chain risk centers on tariff exposure affecting precision mechatronics imports into North American assembly facilities, while raw material dependencies span rare earth elements for motor magnets and corrosion-resistant alloys for biological matrix compatibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autosampler architectures are transitioning from universal platforms toward application-specific configurations as microfluidic modularization displaces fixed-pathway legacy designs.
For Market Incumbents: Deploy predictive maintenance algorithm integration to lock in multi-year service contracts before third-party metrology providers disintermediate original equipment manufacturer service networks. Incumbents must accelerate firmware-level 21 CFR Part 11 compliance development to defend against lower-cost Asian competitors offering software-overlay validation pathways, while consolidating precision fluidic module manufacturing through backward integration into hastelloy machining capabilities. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian pharmaceutical export facilities creates white-space opportunity for mid-tier autosamplers offering CDSCO-aligned compliance without Swiss or Massachusetts brand premiums. New entrants should target Gujarat and Telangana active pharmaceutical ingredient manufacturers building analytical capacity for US FDA inspection readiness, entering through direct relationships with centralized procurement functions at multinational pharmaceutical headquarters rather than distributed laboratory sales channels. For Investors and Strategic Acquirers: Pharmaceutical procurement teams unbundling service contracts from hardware acquisition is the leading indicator that standalone precision autosampler specialists face strategic pressure to integrate or exit. Long-term viability favors acquisition targets possessing native mass-spectrometry-compatible injection architectures and embedded AI-driven diagnostic capabilities, with inflection signals appearing in contract research organization biomarker quantification scaling announcements.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Module Integration | Enables pharmaceutical quality control labs to swap extraction cartridges without reconfiguring core injection mechanisms. |
| Firmware-Level Compliance Architecture | Addresses FDA 21 CFR Part 11 tamper-evident audit trail mandates without external laboratory information management system dependency. |
| Condition-Based Service Contract | Shifts vendor-customer relationships from scheduled maintenance to predictive intervention using injection pressure trace analytics. |
| Geographic Manufacturing Footprint Expansion | Positions suppliers to serve Indian pharmaceutical export growth while mitigating tariff exposure on precision stepper motor imports. |
| AI-Driven Predictive Maintenance Development | Machine learning analysis of motor current signatures enables shift from calendar-based to condition-based service interventions. |
Research Approach
Document review covered FDA 21 CFR Part 11 guidance documents, EPA Method 8270 revision notices, and EMA Annex 11 computerized system requirements, complemented by interviews with pharmaceutical quality control directors, environmental laboratory accreditation managers, chromatography system procurement leads, and precision mechatronics engineering specialists. Secondary validation drew from ISO/IEC 17025 accreditation body reports, SEC filings of diversified analytical instrument conglomerates, and customs records of precision stepper motor trade flows. Bottom-up instrument shipment data triangulated against top-down pharmaceutical R&D expenditure allocations and environmental compliance testing budget projections.
Cross-referencing historical chromatography-autosampler replacement cycles against expert panel input on regulatory inspection timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed chromatography type, end-use industry, technology tier, and application focus, with CAGRs derived from regression analysis of correlated drivers including biopharma batch release testing expansion and EPA detection limit tightening schedules. Industry-specific forecast inputs incorporated monoclonal antibody manufacturing capacity buildouts and contract research organization biomarker study pipeline scaling.
Inputs from pharmaceutical procurement databases and environmental laboratory accreditation registries were available through the study window; gaps in real-time precision stepper motor inventory levels and hastelloy spot pricing introduce uncertainty bands around cost assumptions. Forecasts reflect documented regulatory enforcement patterns and instrument replacement cycle assumptions, with outcomes best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vascular Guidewires Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Facial Implant Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Cervical Implants Market
Medical Devices
Vibrating Mesh Nebulizer Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Transcatheter Pulmonary Valve Replacement Market
Medical Devices
Neuroprosthetics Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Global Breast Surgery Retractors Market