
 Powered Mattress System Market | 2026-2036
Powered Mattress System Market Size, Share, and Industry Trends Forecast 2026-2036
Powered Mattress System Market Insights
Homecare is recalibrating the end-use vertical mix for powered mattress systems, drawing investment away from traditional hospital procurement channels. Stryker Corporation leverages its clinical bed ecosystem to extend into adjacent powered surfaces, while Hill-Rom sustains institutional dominance through intensive care specialization. Arjo anchors European distribution with deep rehabilitation segment expertise, and Drive Medical competes on value-engineered homecare configurations.
A powered mattress system integrates motorized adjustment mechanisms, pressure-sensing arrays, and therapeutic support surfaces within a sleep platform, typically operating on 110-240V electric actuators with weight capacities exceeding 350 pounds for bariatric applications. Adjustable beds and hybrid mattresses command the strongest margin pools as consumers and facilities prioritize customization over commodity innerspring units. Smart technology represents the fastest-expanding technology segment, though pneumatic systems retain share in acute care settings where infection control protocols favor sealed air-cell architectures.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern device safety and clinical performance claims across the United States and export markets. The EU Medical Device Regulation imposes enhanced post-market surveillance obligations that lengthen certification timelines for new entrants. Stakeholders must monitor evolving homecare reimbursement codes and pressure injury quality metrics that increasingly determine procurement authority shifts from supply chain managers to chief nursing officers.
Market Dynamics
Medicare reimbursement codes for hospital-at-home programs are redirecting procurement authority from supply chain managers toward chief nursing officers, fundamentally altering how powered mattress systems are specified and purchased across the United States.
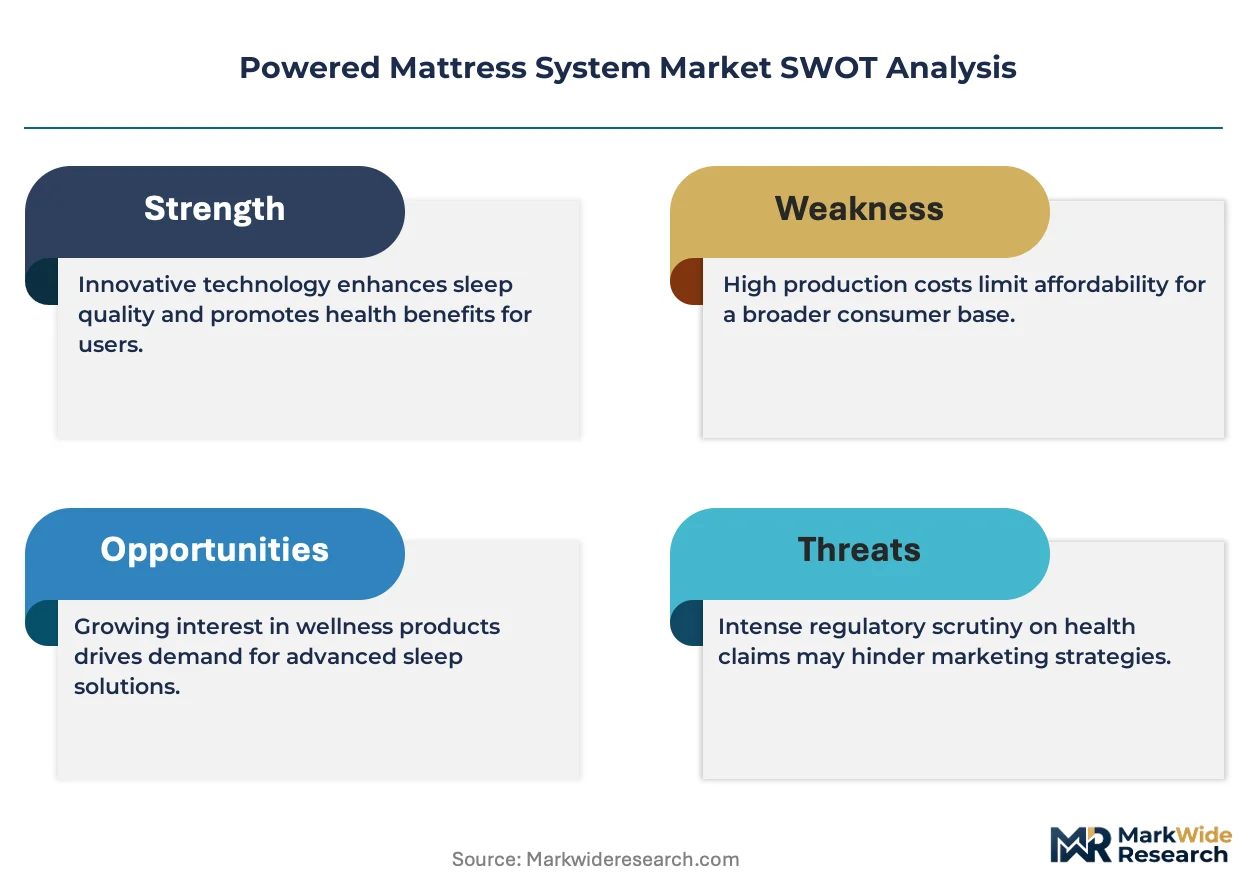
Growth Catalysts
- Pressure injury prevention mandates:FDA 510(k) clearance requirements for therapeutic support surfaces are elevating clinical performance standards across acute and post-acute care settings, expanding reimbursable indications for powered systems.
- Hospital-at-home infrastructure:Medicare's expanded reimbursement for home-based acute care is creating new demand channels for bariatric-capable adjustable mattresses with remote monitoring integration.
- Aging demographic concentration:Germany and Japan are deploying public long-term care insurance reforms that subsidize powered sleep surfaces for home-dwelling elderly, directly stimulating replacement cycles.
Market Restraints
- Electric actuator supply concentration:Production of precision linear actuators for medical-grade load capacity concentrates among German and Japanese component specialists, exposing assemblers to extended lead times.
- EU MDR certification timelines:Enhanced post-market surveillance obligations under the EU Medical Device Regulation are lengthening new entrant approval cycles by 12-18 months versus previous directives.
- Pneumatic system substitution limits:Sealed air-cell architectures retain institutional preference in acute infection-control protocols, constraining foam-hybrid penetration in high-acuity segments.
Strategic Opportunities
- Underpenetrated homecare channels:Durable medical equipment retailers in secondary US metropolitan markets lack trained staff to demonstrate therapeutic positioning features, creating white space for manufacturer-direct education programs.
- Smart-pneumatic convergence:Integration of IoT pressure-mapping arrays with traditional air-cell systems enables predictive maintenance and remote compliance monitoring for distributed homecare deployments.
- IRA healthcare infrastructure incentives:US tax credits for domestic medical device manufacturing are reducing effective capital costs for reshoring final assembly operations.
Industry Challenges
- Clinical engineering talent scarcity:Health systems face persistent shortages of biomeds trained to service motorized bed platforms and integrated mattress systems, extending mean time to repair.
- Legacy EMR integration complexity:Smart mattress data streams require HL7 FHIR compliance to feed into hospital electronic medical records, demanding specialized software development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powered Mattress System Market |
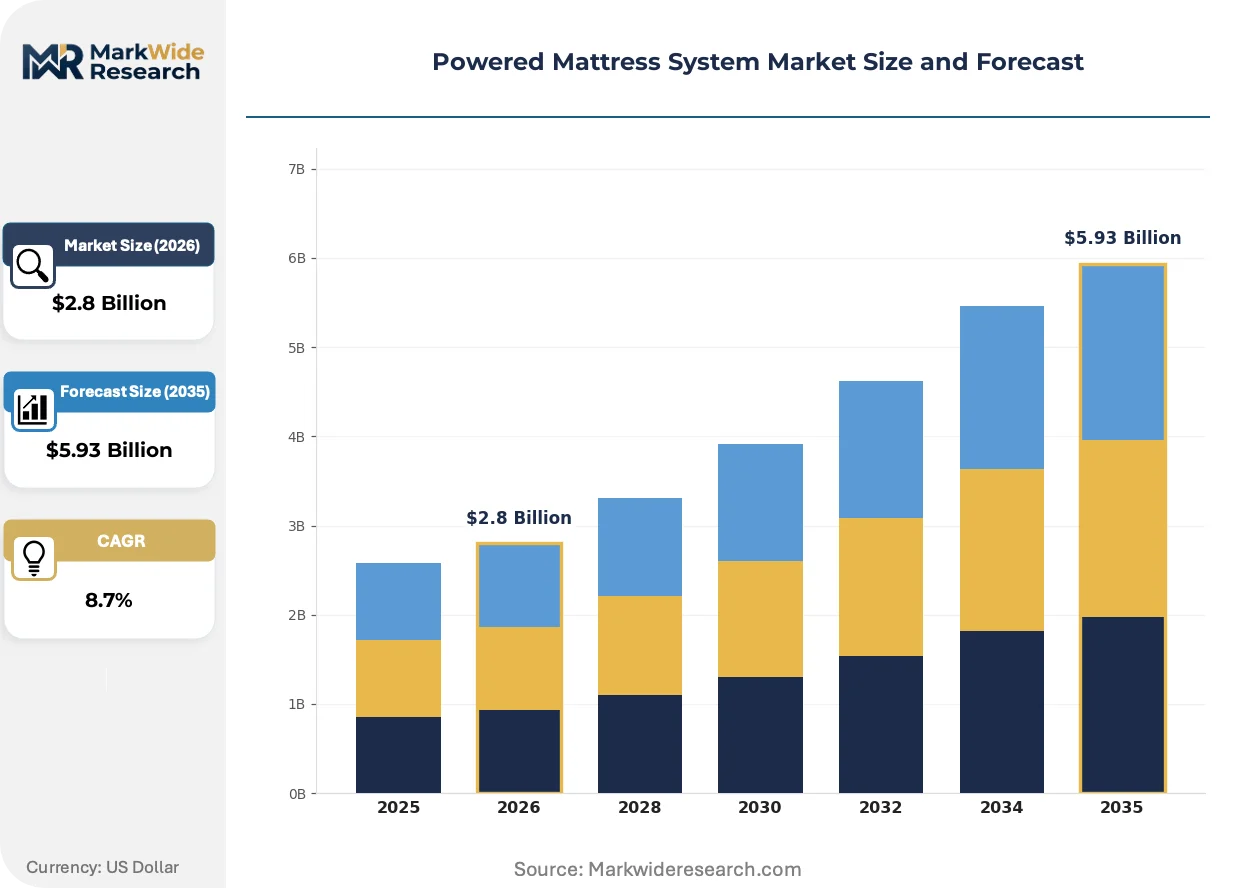
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustable Beds, Memory Foam Mattresses, Innerspring Mattresses, Hybrid Mattresses End User: Hospitals, Nursing Homes, Homecare, Hotels Technology: Electric, Mechanical, Pneumatic, Smart Technology Application: Health Monitoring, Comfort Adjustment, Pressure Relief, Sleep Quality Improvement |
| Companies Covered | Invacare Homecare, Medline, Hill-Rom, Proactive Medical Products, Drive Medical, Stryker Corporation, Arjo, Joerns Healthcare, Linet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powered Mattress System Market Trends and Innovations
Sensor-embedded sleep surfaces are generating continuous biometric data streams that transform mattresses from passive support platforms into active clinical monitoring nodes. This capability expansion is redrawing competitive boundaries between furniture manufacturers and medical device suppliers.
Capacitive pressure-mapping arrays embedded within foam-hybrid constructions are decentralizing pressure injury surveillance from scheduled nursing rounds to real-time automated alerts. Skilled nursing facilities in the United States are adopting these systems at accelerating pace to reduce liability exposure. The technology is decentralizing clinical oversight responsibility toward centralized remote monitoring centers, compressing staffing models.
The EU Medical Device Regulation's Unique Device Identification requirements are forcing manufacturers to reconfigure supply chain traceability systems for component-level serialization. This obligation is elevating compliance costs disproportionately for mid-tier assemblers lacking enterprise resource planning infrastructure. German distributors are responding by consolidating supplier bases to reduce audit complexity.
Chief nursing officers in US health systems are unbundling mattress procurement from capital bed purchases, creating separate specification and sourcing processes for therapeutic surfaces. Group purchasing organizations are losing influence as clinical quality metrics determine selection criteria. This pattern is most visible in academic medical centers pursuing Magnet designation.
Powered Mattress System Market Segmentation
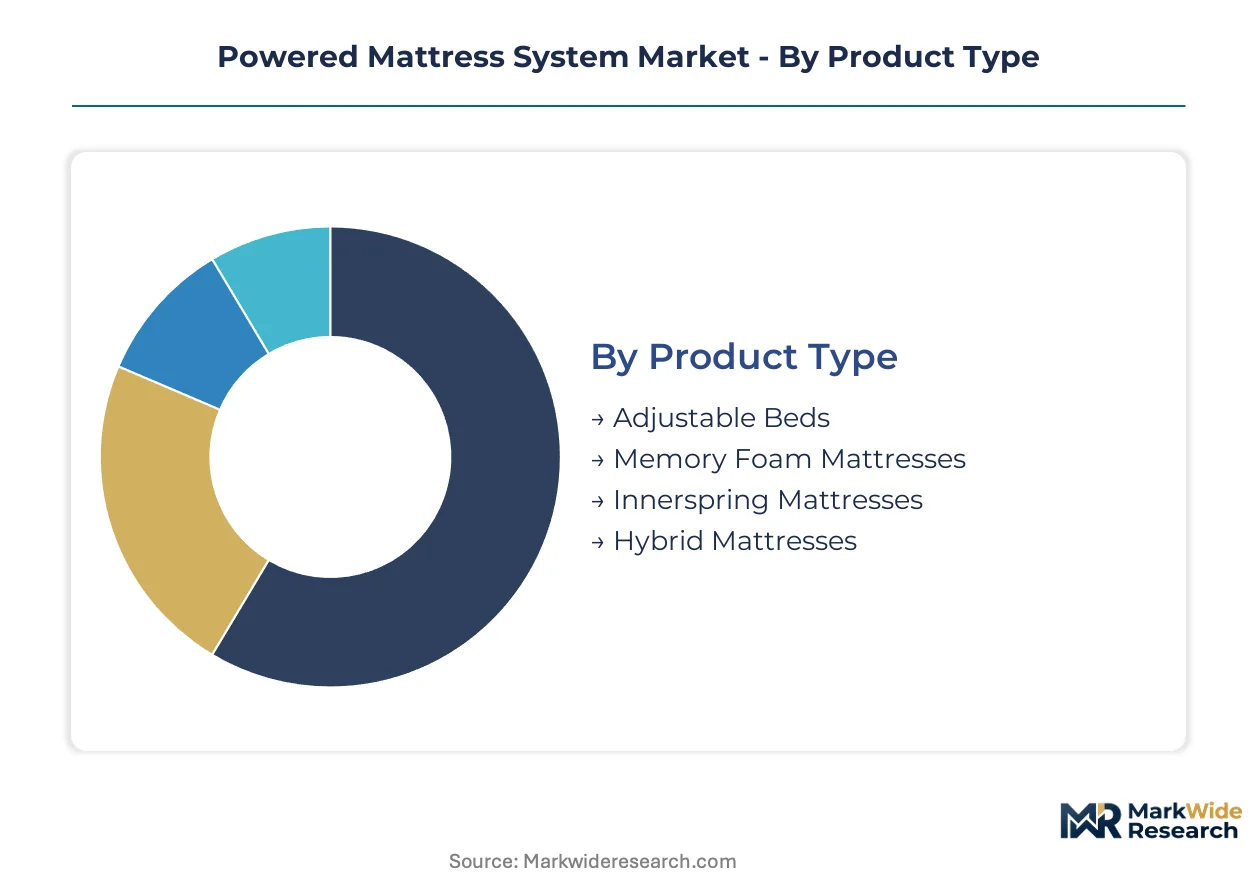
Powered mattress system segmentation reveals divergent integration architectures across care settings. Standalone adjustable beds serve distributed homecare deployments, while embedded pressure-sensing surfaces integrate into capital-intensive hospital platforms.
Product Type:
Integration depth separates standalone sleep platforms from surfaces embedded within clinical bed systems. Adjustable beds and hybrid mattresses operate as independent units, while memory foam and innerspring variants typically embed within larger capital equipment.
- Adjustable Beds:Motorized frame systems with 110-240V electric actuators enable head and foot articulation for therapeutic positioning. Demand concentrates in United States homecare channels where Medicare hospital-at-home reimbursement codes now cover bariatric-capable units exceeding 350-pound weight ratings.
- Hybrid Mattresses:Foam-spring composites with integrated pressure-sensing arrays bridge consumer comfort and clinical performance. Skilled nursing facilities in Germany are adopting these for pressure injury prevention compliance under public long-term care insurance reforms.
- Memory Foam Mattresses:Viscoelastic polyurethane constructions contour to body topography without motorized components.
- Innerspring Mattresses:Steel coil support cores remain standard in budget hospitality and legacy institutional procurement.
Adjustable beds lead volumes today; hybrid mattresses are gaining share fastest.
End User:
Customer type determines specification authority and procurement channel structure. Institutional buyers prioritize ISO 13485-certified therapeutic surfaces, while consumer-direct channels emphasize demonstration and education.
- Homecare:Distributed deployments of bariatric-capable adjustable mattresses with remote monitoring integration. United States durable medical equipment retailers in secondary metropolitan markets lack trained demonstration staff, creating white space for manufacturer-direct education programs.
- Hospitals:Acute care settings demand FDA 510(k)-cleared therapeutic support surfaces with sealed air-cell architectures for infection control protocol compliance. Chief nursing officers are unbundling mattress procurement from capital bed purchases, elevating clinical quality metrics over supply chain manager authority.
- Nursing Homes:Post-acute facilities face liability exposure from pressure injury litigation, accelerating capacitive pressure-mapping adoption.
- Hotels:Hospitality procurement prioritizes durability and guest comfort customization over clinical certification.
Hospitals dominate revenue concentration; homecare is expanding most quickly.
Technology:
Actuation mechanism determines maintenance burden, infection control profile, and data integration capability. Electric and smart systems enable remote monitoring, while pneumatic and mechanical architectures minimize electronic failure modes.
- Smart Technology:IoT-enabled pressure-mapping arrays with HL7 FHIR-compliant data streams feed into electronic medical records. Academic medical centers in the United States pursuing Magnet designation are specifying these for predictive maintenance and remote compliance monitoring.
- Electric:Precision linear actuators from German and Japanese component specialists power position adjustment. Supply concentration among these specialists exposes assemblers to extended lead times.
- Pneumatic:Sealed air-cell architectures retain institutional preference in acute infection-control protocols.
- Mechanical:Manual adjustment systems persist in cost-constrained hospitality and developing market deployments.
Electric systems anchor installed base; smart technology shows steepest expansion trajectory.
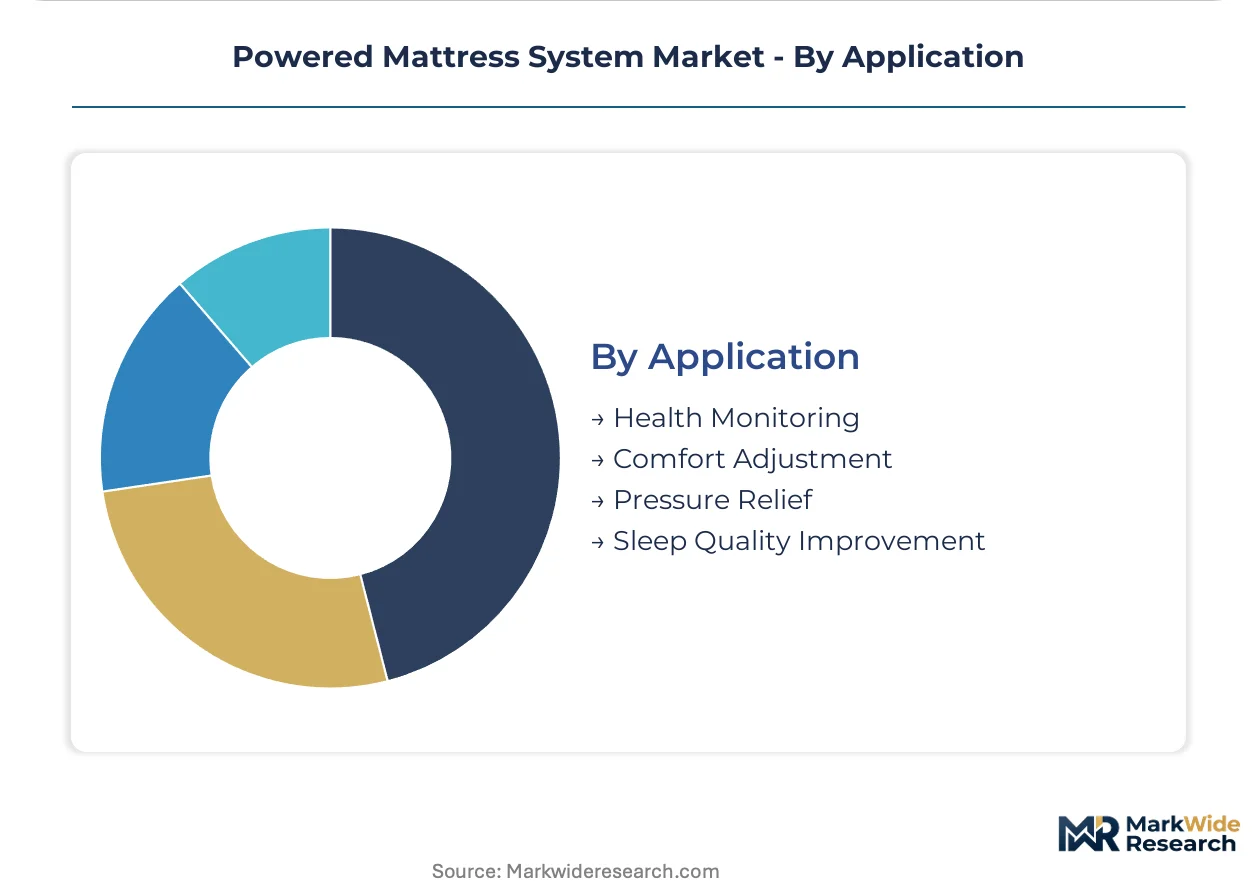
Application:
Functional purpose determines sensor configuration, software integration depth, and reimbursement eligibility. Health monitoring and pressure relief applications command clinical premiums, while comfort adjustment and sleep quality improvement align with consumer markets.
- Pressure Relief:Therapeutic support surfaces redistribute interface pressure to prevent Stage I-IV injuries. FDA 510(k) clearance requirements for these devices are elevating clinical performance standards across acute and post-acute care settings.
- Health Monitoring:Continuous biometric data streams transform mattresses into active clinical nodes. Capacitive pressure-mapping arrays decentralize surveillance from scheduled nursing rounds to real-time automated alerts.
- Comfort Adjustment:Position customization for consumer sleep quality without clinical certification requirements.
- Sleep Quality Improvement:Consumer-facing wellness applications with limited reimbursement eligibility.
Pressure relief commands highest average selling prices; health monitoring is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate final assembly to jurisdictions offering streamlined FDA 510(k) equivalency pathways or accelerated EU MDR conformity assessments. Cost-of-compliance gaps between Germany, the United States, and select Asian manufacturing hubs now exceed 18 months in certification timeline differential.
United States
Medicare's hospital-at-home reimbursement expansion is accelerating demand for bariatric-capable adjustable mattresses with remote monitoring integration. FDA 510(k) clearance requirements for therapeutic support surfaces are elevating clinical performance standards across acute and post-acute care settings. The Southeast corridor, particularly Florida and Georgia, is witnessing concentrated durable medical equipment retailer expansion to serve aging demographic clusters.
Germany
Public long-term care insurance reforms are subsidizing powered sleep surfaces for home-dwelling elderly, directly stimulating replacement cycles. EU MDR certification timelines have lengthened by 12-18 months versus previous directives, favoring incumbent manufacturers with established quality management systems. The Baden-Württemberg industrial cluster hosts precision linear actuator specialists whose component supply concentrates among German and Japanese specialists.
Japan
Meti's aging-in-place infrastructure investments are redirecting procurement authority toward homecare channels with bariatric weight capacity requirements. PMDA streamlined approval pathways for therapeutic support surfaces are reducing time-to-market for pneumatic-hybrid configurations. The Kansai region around Osaka maintains deep rehabilitation segment expertise anchoring regional distribution networks.
China
NMPA's evolving medical device classification for powered sleep surfaces is creating compliance arbitrage opportunities for domestic manufacturers targeting export markets. Domestic demand concentrates in tier-one hospital procurement for acute care infection-control protocols. The Yangtze River Delta manufacturing corridor is consolidating component supply for electric actuator assembly.
United Kingdom
NHS England's hospital-at-home pilot programs are creating procurement channels for adjustable mattress systems with HL7 FHIR-compliant data integration. MHRA post-Brexit regulatory autonomy is diverging from EU MDR timelines in limited therapeutic device categories. The Southeast corridor retains concentration of clinical engineering talent for servicing motorized bed platforms.
Powered Mattress System Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent medical device manufacturers extend from capital bed systems into adjacent powered mattress surfaces. The vendor base concentrates among three tiers: diversified hospital equipment conglomerates with intensive care specialization, European rehabilitation-focused distributors with deep segment expertise, and value-engineered homecare specialists competing on Medicare reimbursement-optimized configurations. Strategic archetypes include clinical ecosystem integrators, regional distribution anchors, and direct-to-patient educators. M&A activity and backward integration into precision actuator supply chains represent the dominant competitive vectors.
Within the diversified medical equipment tier, Stryker Corporation and Hill-Rom exemplify clinical ecosystem integrators leveraging established hospital procurement relationships to extend specification authority into therapeutic mattress surfaces. Arjo occupies a position as the European distribution anchor with rehabilitation segment depth. Among value-engineered specialists, Drive Medical represents the Medicare-optimized configuration archetype targeting homecare channel expansion.
| Leading Market Players |
|---|
| Invacare Homecare |
| Medline |
| Hill-Rom |
| Proactive Medical Products |
| Drive Medical |
| Stryker Corporation |
| Arjo |
| Joerns Healthcare |
| Linet |
| Others |
Pricing and Supply Chain Analysis
Smart-pneumatic convergence in mattress architectures is compressing component costs while concentrating procurement leverage among IoT sensor suppliers and precision actuator specialists. This dual transformation simultaneously elevates R&D thresholds for new entrants and tightens margin pools for mid-tier assemblers lacking captive supply relationships.
Pricing Analysis
Distributor margin compression in durable medical equipment channels is forcing manufacturers toward direct-to-patient education models. Three-tier pricing structure across FDA 510(k)-cleared therapeutic surfaces, ISO-certified institutional units, and consumer-grade adjustable beds reflects certification-grade differentiation. Cost compression in pneumatic-hybrid configurations is intensifying because Medicare reimbursement codes now bundle remote monitoring capabilities into base coverage rates. Homecare patients exhibit highest price sensitivity; academic medical centers pursuing Magnet designation show lowest.
Supply Chain Analysis
Reverse-logistics networks for refurbished actuator assemblies and remanufactured pressure-sensing arrays remain underdeveloped across North American homecare corridors. Precision linear actuator production concentrates in Germany and Japan; foam-hybrid substrate fabrication anchors in China and Vietnam. Supply chains draw from medical-grade polyurethane suppliers, capacitive sensor foundries, and 110-240V power electronics specialists. Single-source vulnerability in German-Japanese actuator supply exposes assemblers to extended lead times. Distribution runs through hospital GPOs, durable medical equipment retailers, and manufacturer-direct homecare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in powered mattress systems rests on software-enabled service bundling and premium-tier clinical certification investments that offset commodity pressure in consumer adjustable beds.
For Market Incumbents: Hedge against pneumatic system substitution limits by embedding predictive maintenance algorithms into legacy air-cell architectures. Pursue backward integration into precision actuator supply chains to reduce exposure to German-Japanese component concentration. Defensive consolidation around HL7 FHIR-compliant data platforms protects against software-native entrants. For New Entrants and Emerging Players: Capacitive pressure-mapping arrays as a technology-first wedge open underpenetrated skilled nursing facility channels where liability exposure drives rapid adoption. Target secondary US metropolitan markets lacking trained durable medical equipment demonstration staff. Pursue manufacturer-direct education partnerships bypassing distributor margin layers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier foam-hybrid assemblers lacking ISO 13485 certification infrastructure but possessing established Medicare reimbursement code expertise. Long-term viability over the projection horizon favors clinical ecosystem integrators with intensive care specialization depth. Monitor EU MDR certification timeline convergence as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Pneumatic Platform Integration | IoT sensor arrays embedded in sealed air-cell architectures enable predictive maintenance for distributed homecare deployments. |
| FDA 510(k) Clearance Pathway | Therapeutic support surface certification elevates clinical performance claims and expands reimbursable indications. |
| Hospital System Partnership | Chief nursing officer relationships unbundle mattress procurement from capital bed purchases toward quality-based selection. |
| Backward Integration into Actuators | In-house precision linear actuator production reduces exposure to German-Japanese supply concentration. |
| Reimbursement Strategy | Medicare hospital-at-home code optimization drives bariatric-capable adjustable mattress specification authority. |
Research Methodology
Direct dialogue with chief nursing officers, biomedical engineering directors, durable medical equipment procurement managers, and GPO contracts specialists grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR conformity assessment timelines. Bottom-up unit economics triangulated against top-down therapeutic surface demand models across the analysis window.
Segment-level projections across product type, end user, technology, and application dimensions informed volume and value outputs. CAGRs derived from regression analysis of replacement cycle acceleration, demographic concentration patterns, and reimbursement code expansion trajectories. Modeled inputs incorporated precision actuator lead time volatility, EU MDR certification timeline differentials, and HL7 FHIR integration adoption curves.
The model holds under stable Medicare reimbursement policy and EU MDR implementation pace; deviation in FDA therapeutic device reclassification or pneumatic-hybrid substitution breakthroughs would shift trajectory. Practitioners should monitor hospital-at-home program scale-up rates and chief nursing officer procurement authority consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Animal Ultrasound Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Global Automated Suturing Devices Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
US Surgical Microscopes Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Injection Pen Market
Medical Devices
Global Blood Ketone Meter Market