
 US Telehealth Market | 2026-2036
US Telehealth Market Size, Share, and Industry Trends Forecast 2026-2036
US Telehealth Market Intelligence
Subscription-based remote patient monitoring is rebalancing how care gets monetized, shifting from episodic visits to recurring revenue tied to chronic condition oversight. Teladoc Health Inc. leverages its multi-specialty physician network to sustain national coverage depth. American Well anchors enterprise contracts with large health systems seeking white-label virtual care infrastructure. MDLIVE competes on speed-to-appointment metrics in urgent care triage.
Telehealth encompasses real-time audio-visual clinical consultation, asynchronous store-and-forward diagnostics, and remote physiologic monitoring transmitted through HIPAA-compliant encrypted channels with latency thresholds under 150 milliseconds for acute encounters. Its primary commercial purpose extends specialist reach to underserved geographies while reducing per-episode cost structures for capitated payment models. Software Solutions and Telehealth Platforms capture the dominant margin pools as health systems prioritize integrated EHR interoperability over standalone communication tools. Chronic Disease Management and Mental Health Services represent the fastest-expanding application areas, driven by CMS-guided reimbursement codes that favor longitudinal virtual relationships over one-time consultations.
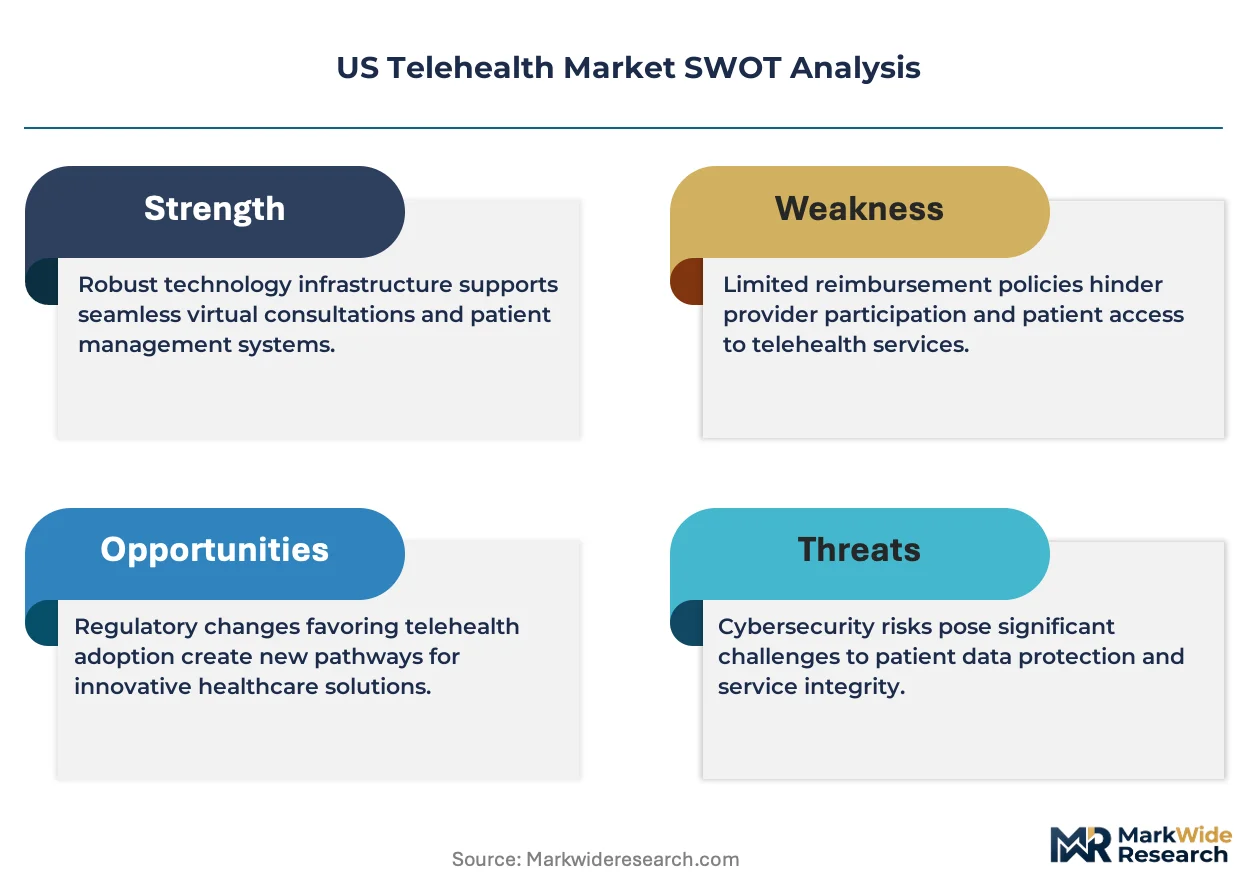
FDA oversees software-as-medical-device classifications for diagnostic algorithms, while CMS reimbursement parity rules directly shape provider willingness to scale virtual offerings, and HIPAA security standards dictate minimum encryption and access-log specifications for platform certification. State-level medical licensing compacts fragment operational scalability, requiring platforms to maintain credentialing infrastructure across multiple jurisdictions. Stakeholders must monitor whether Congress codifies pandemic-era telehealth flexibilities before existing waivers expire, as this legislative decision will reset baseline demand assumptions for platform operators and health system capital planners alike.
Market Dynamics
CMS reimbursement parity rules are compressing the economic gap between virtual and in-person encounters, forcing health systems to rebuild care delivery around longitudinal digital relationships rather than episodic office visits.
Growth Catalysts
- HIPAA-compliant encryption standards:Federal security specifications for platform certification have created baseline trust infrastructure that accelerates enterprise adoption by hospital systems.
- Texas health system infrastructure:Dallas-Fort Worth providers are constructing dedicated telehealth operations for chronic disease populations, concentrating demand and vendor investment in the state.
- Remote physiologic monitoring:Continuous glucose monitors and blood pressure cuffs transmitting through encrypted channels are enabling capitated payment models to reduce per-episode costs.
Market Restraints
- State-level medical licensing compacts:Jurisdictional fragmentation forces platforms to maintain redundant credentialing infrastructure across multiple state medical boards.
- Latency threshold compliance:The under-150-millisecond requirement for acute encounters demands specialized network architecture that elevates platform development costs.
- Software-as-medical-device classification:FDA diagnostic algorithm oversight creates approval timelines that delay commercialization of AI-augmented triage tools.
Strategic Opportunities
- Rural hospital system anchor contracts:Underserved geographies in Montana, Wyoming, and the Dakotas present whitespace for specialist reach programs.
- Mental health services reimbursement codes:CMS-guided longitudinal relationship billing favors virtual psychiatric care over one-time consultations.
- Asynchronous store-and-forward integration:Convergence with EHR interoperability standards is opening enterprise contracts previously locked by standalone communication tools.
Industry Challenges
- Multi-jurisdictional credentialing workflows:Platform operators face operational complexity maintaining provider verification across state medical boards with non-uniform requirements.
- EHR interoperability capex cycles:Health systems must commit capital to integrated virtual care infrastructure rather than lightweight communication add-ons.
- Pandemic-era waiver expiration timeline:Congressional legislative uncertainty is freezing long-term capital planning for platform operators and health system strategists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Telehealth Market |
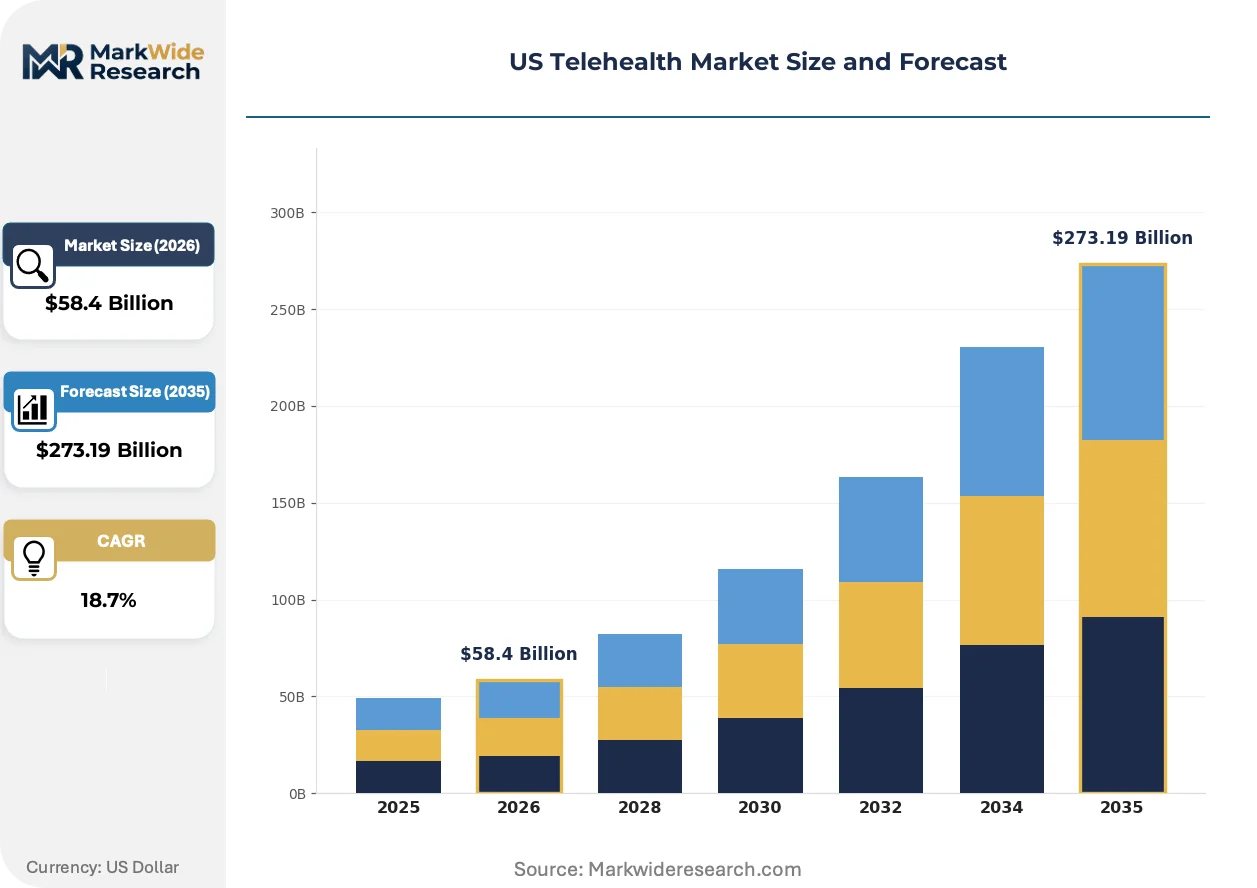
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $273.19 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Telehealth Platforms, Remote Monitoring Devices, Communication Tools End User: Patients, Healthcare Providers, Insurers, Employers Technology: Video Conferencing, Mobile Apps, Cloud Solutions, Wearable Devices Application: Chronic Disease Management, Mental Health Services, Preventive Care, Emergency Consultations |
| Companies Covered | Teladoc Health Inc., American Well, MDLIVE, Doctor On Demand, GE Healthcare, Oracle, Siemens Healthineers, Koninklijke Philips N.V., Medtronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Telehealth Market Strategic Shifts & Innovations
Real-time audio-visual infrastructure is displacing asynchronous modalities as the default clinical encounter format, while reimbursement policy and procurement behavior shift in parallel to lock in virtual-first care models.
Remote patient monitoring hardware paired with diagnostic algorithms is electrifying chronic disease management by enabling continuous data streams that trigger automated care interventions. Medicare Advantage plans are deploying these bundled device-and-platform contracts at accelerating velocity. The structural consequence is compressing traditional episodic billing into recurring subscription revenue tied to patient oversight rather than visit volume.
CMS reimbursement parity rules are mandating equivalent payment rates for virtual and in-person encounters across qualifying service categories. This industrial consequence eliminates the financial penalty that previously constrained provider willingness to scale telehealth offerings. Rural hospital systems in Texas, Montana, and Wyoming are responding most aggressively, building dedicated virtual infrastructure to capture specialist reach revenue previously lost to urban academic medical centers.
Subscription-based remote patient monitoring contracts are displacing fee-for-service billing in chronic disease verticals. Health systems are unbundling device procurement from platform licensing, creating direct purchasing relationships with hardware manufacturers. This pattern is most visible in diabetes and hypertension management programs across Medicare Advantage populations in the Southwest and Mountain West regions.
US Telehealth Market Segmentation
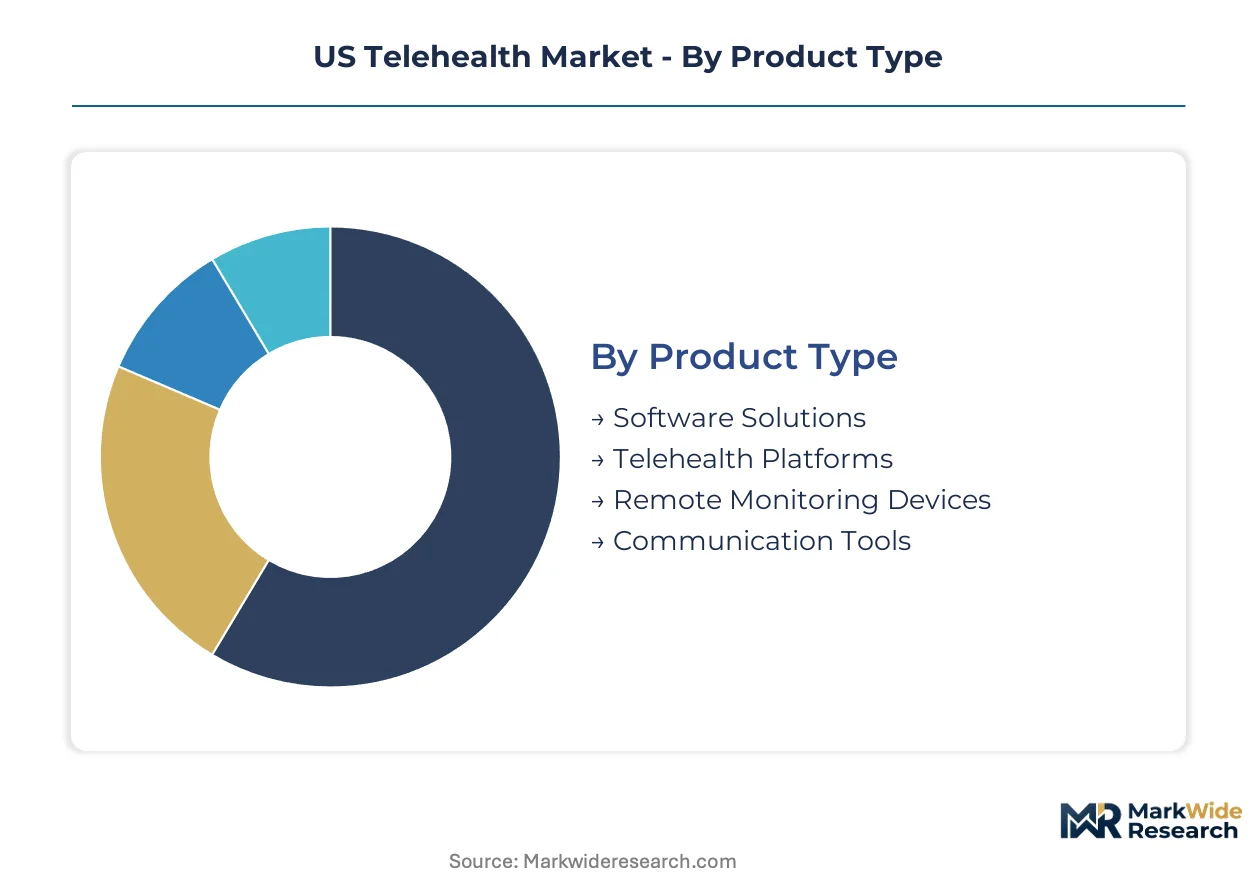
Telehealth segmentation reveals how reimbursement policy and procurement behavior split across distinct technology stacks and care delivery models. Understanding these divisions exposes where health systems allocate capital and where platform vendors capture recurring revenue.
Product Type:
Health system procurement committees prioritize integration depth over standalone functionality when evaluating vendor proposals.
- Software Solutions:Modular architectures enabling EHR interoperability dominate enterprise RFPs. Texas health systems in Dallas-Fort Worth demand API-first designs that ingest continuous monitoring data without workflow disruption.
- Telehealth Platforms:White-label infrastructure anchors multi-specialty network contracts. Rural hospital systems in Montana and Wyoming select vendors offering credentialing support across state medical licensing compacts.
- Remote Monitoring Devices:Blood pressure cuffs and continuous glucose monitors transmit through HIPAA-compliant encrypted channels.
- Communication Tools:Lightweight messaging applications face procurement scrutiny without diagnostic algorithm integration.
Software Solutions leads on scale; Telehealth Platforms leads on momentum.
End User:
Revenue concentration follows the entity controlling reimbursement flow rather than direct service consumption.
- Healthcare Providers:Hospital systems and physician groups drive platform licensing decisions based on CMS reimbursement parity rule alignment. Capitated payment models in Medicare Advantage accelerate subscription adoption for chronic oversight.
- Insurers:Payers structure bundled device-and-platform contracts for diabetes and hypertension populations. Prior authorization workflows increasingly require virtual-first encounter documentation.
- Patients:Direct-to-consumer demand concentrates in urgent care triage and mental health access.
- Employers:Self-insured plans purchase telehealth benefits as cost-containment tools for workforce populations.
Healthcare Providers leads on current revenue capture; Insurers leads on contract velocity.
Technology:
Latency tolerance thresholds segment infrastructure investment between acute and longitudinal care modalities.
- Video Conferencing:Real-time audio-visual encounters demand under-150-millisecond latency compliance. Specialized network architecture elevates development costs for vendors serving emergency consultation verticals.
- Cloud Solutions:Scalable storage and compute resources enable asynchronous store-and-forward diagnostics. FDA software-as-medical-device classifications delay AI-augmented triage commercialization timelines.
- Mobile Apps:Consumer-facing interfaces compete on speed-to-appointment metrics.
- Wearable Devices:Physiologic sensors transmit encrypted data streams triggering automated interventions.
Video Conferencing leads on encounter volume; Cloud Solutions leads on infrastructure scalability.
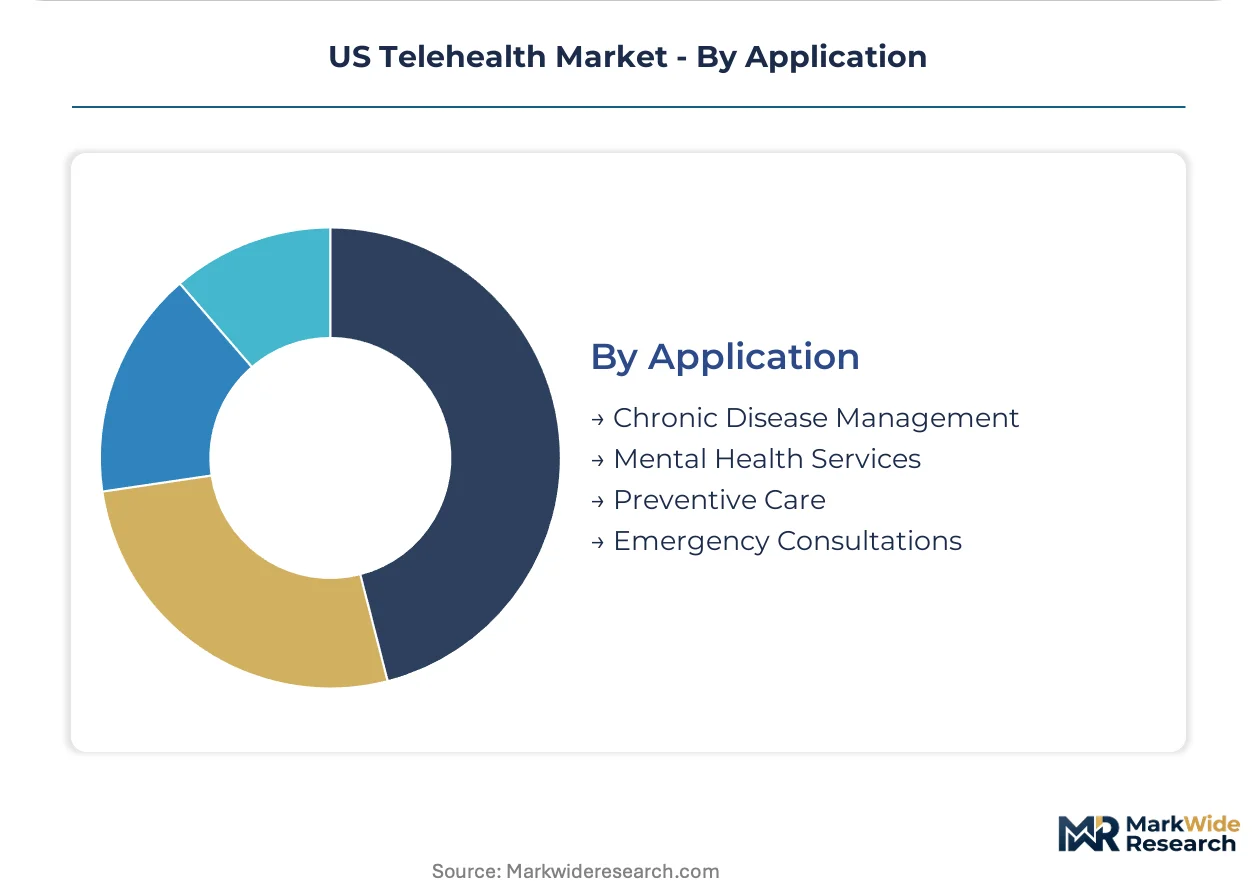
Application:
CMS-guided reimbursement codes determine which clinical domains support sustainable virtual economics.
- Chronic Disease Management:Continuous monitoring of diabetes and hypertension enables subscription revenue models. Medicare Advantage plans in the Southwest and Mountain West deploy bundled contracts at accelerating velocity.
- Mental Health Services:Longitudinal psychiatric relationships bill under codes favoring recurring virtual contact over one-time consultations. Texas health systems build dedicated infrastructure for this vertical.
- Preventive Care:Annual wellness visits and screening protocols face reimbursement variability across state Medicaid programs.
- Emergency Consultations:Acute triage encounters require latency-compliant infrastructure and specialized clinician credentialing.
Chronic Disease Management leads on revenue predictability; Mental Health Services leads on policy tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas health systems deploy chronic disease infrastructure at scale unmatched elsewhere, while Montana and Wyoming rural hospitals anchor specialist reach programs with different reimbursement economics.
Texas
Dallas-Fort Worth health systems construct dedicated telehealth operations for diabetes and hypertension populations. CMS reimbursement parity rules enable equivalent payment rates for virtual encounters, eliminating prior financial penalties. Houston medical centers integrate remote patient monitoring with Medicare Advantage bundled contracts at accelerating velocity.
Montana
Rural hospital systems in Billings and Missoula pursue specialist reach revenue previously captured by urban academic centers. State medical licensing compact membership reduces credentialing friction for multi-state physician networks. Yellowstone County providers build white-label virtual infrastructure with enterprise platform vendors.
Wyoming
Frontier health systems in Cheyenne and Casper deploy asynchronous store-and-forward diagnostics for dermatology and radiology consultations. HIPAA security standards mandate encrypted channels with access-log specifications that elevate platform procurement requirements. Campbell County Memorial Hospital anchors regional virtual care adoption.
California
Los Angeles and San Francisco Bay Area health systems prioritize EHR interoperability in enterprise RFPs. FDA software-as-medical-device classifications delay commercialization of AI-augmented triage tools for diagnostic algorithms. Kaiser Permanente and Sutter Health integrate continuous monitoring data through API-first architectures.
Florida
Miami and Tampa health systems concentrate direct-to-consumer demand in urgent care triage and mental health access. State Medicaid program reimbursement variability creates procurement uncertainty for preventive care protocols. Jackson Health System builds dedicated psychiatric virtual infrastructure for longitudinal relationship billing.
US Telehealth Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with health system procurement committees prioritizing integration depth over standalone functionality. The vendor base concentrates around three strategic archetypes: multi-specialty physician networks, white-label infrastructure providers, and speed-to-appointment urgent care platforms. M&A activity targets credentialing infrastructure assets that reduce multi-jurisdictional operational complexity. Strategic partnerships between device manufacturers and platform operators unbundle hardware procurement from software licensing.
Within the multi-specialty network tier, Teladoc Health Inc. and American Well occupy positions exemplifying national coverage depth and enterprise contract anchoring respectively. MDLIVE represents the speed-optimized urgent care archetype competing on appointment access metrics.
| Leading Market Players |
|---|
| Teladoc Health Inc. |
| American Well |
| MDLIVE |
| Doctor On Demand |
| GE Healthcare |
| Oracle |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Medtronic |
| Others |
Cost & Logistics Intelligence
Vertical integration into remote patient monitoring hardware anchors supply positions for Texas health systems while compressing platform licensing margins. CMS reimbursement parity rules enable Dallas-Fort Worth providers to capture specialist reach revenue without pricing penalties, embedding subscription economics deep into chronic disease verticals.
Pricing Analysis
Capacity additions in California and Texas are reshaping price floors for HIPAA-compliant platform infrastructure. Three-tier pricing structure across enterprise, mid-market, and direct-to-consumer levels stratifies by EHR integration depth and credentialing support scope. Cost compression in the mid-market tier intensifies because health systems unbundle device procurement from software licensing. Medicare Advantage plans exhibit highest price sensitivity; rural hospital anchor contracts show lowest.
Supply Chain Analysis
Software engineering talent availability in California, Massachusetts, and Texas shapes platform development velocity and cost structures. Cloud compute resources and encryption protocol licenses draw from hyperscaler networks concentrated in Northern Virginia and Pacific Northwest data center clusters. Single-source vulnerability in FDA-cleared diagnostic algorithm pipelines elevates risk for AI-augmented triage commercialization. Distribution runs through health system procurement committees and GPO contract vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Telehealth Market reads as a late-cycle quality story where Medicare Advantage demand shifts toward longitudinal virtual relationships with continuous monitoring specifications. Platform operators must now defend subscription economics against unbundling pressure from device manufacturers.
For Market Incumbents: Lock in rural hospital anchor contracts across Montana and Wyoming before state medical licensing compacts simplify competitor entry. Deepen backward integration into remote monitoring device manufacturing to offset margin compression from health system unbundling. Prioritize API-first architecture investments that embed platforms into EHR workflows, creating switching costs against standalone communication tools. For New Entrants and Emerging Players: Enter via asynchronous store-and-forward diagnostics for dermatology and radiology in frontier health systems where specialist reach gaps remain acute. Target Wyoming and the Dakotas where Yellowstone County and Campbell County Memorial Hospital anchor regional virtual care adoption with white-label infrastructure demand. Lead with Medicare Advantage bundled contracting that packages device procurement with platform licensing. For Investors and Strategic Acquirers: Roll-up economics work for credentialing infrastructure assets because state-level medical licensing compacts fragment operational scalability across jurisdictions. Multi-jurisclictional verification platforms offer 5-10 year viability as Congressional legislative uncertainty around pandemic-era waiver expiration sustains demand for compliance automation. Monitor CMS reimbursement code expansions for mental health longitudinal relationships as the inflection signal for psychiatric virtual infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Texas health systems in Dallas-Fort Worth demand dedicated chronic disease infrastructure with EHR interoperability. |
| Reimbursement Strategy | CMS parity rules eliminate financial penalties for virtual encounters across qualifying service categories. |
| Software Companion Development | FDA software-as-medical-device classifications delay AI-augmented triage commercialization timelines. |
| Platform Integration | API-first designs enable continuous monitoring data ingestion without clinician workflow disruption. |
| Acquisition of Specialist Firm | Credentialing infrastructure assets reduce multi-jurisdictional operational complexity for platform operators. |
Research Approach
Direct dialogue with telehealth platform executives, hospital purchasing committee members, Medicare Advantage plan administrators, and biomedical engineers combined with secondary validation from CMS reimbursement databases, FDA 510(k) filings, and GPO contract repositories. Bottom-up sizing of software licensing revenue and top-down triangulation against health system IT expenditure disclosures anchored market estimates.
Segmentation outputs reflect modeled splits across product type, end user, technology stack, and application vertical throughout the forecast period. CAGRs derived from health system capital expenditure trajectories and Medicare Advantage enrollment patterns. Forecast inputs incorporate HIPAA security standard compliance timelines and state medical licensing compact adoption rates.
The model holds under sustained CMS reimbursement parity and Congressional extension of pandemic-era flexibilities; deviation in waiver expiration or diagnostic algorithm reclassification would shift platform operator revenue assumptions. Practitioners should monitor Congressional legislative timelines and FDA software-as-medical-device guidance updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telemedicine Workstations Market
Telemedicine
Teledermatology Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
Telepathology Service Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
Next Generation Telehealth Market
Telemedicine
Tele-Care Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
GCC Telemedicine Market
Telemedicine
Tele-Epilepsy Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
US Virtual Care Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
US Virtual Visits Market