
 Osteotomy Plates Market | 2026-2036
Osteotomy Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Osteotomy Plates Market Intelligence
Modular plate-and-screw systems with instrument kits is realigning how orthopedic purchasers evaluate total cost of ownership against standalone component sourcing. DePuy Synthes leverages its broad trauma portfolio to dominate hospital contracting channels. Stryker Corporation anchors its position through integrated power tools and navigation compatibility. Zimmer Biomet differentiates via specialized limb-reconstruction platforms that bundle hardware with software planning tools.
Osteotomy plates are metallic or polymer implants engineered with specific screw-hole patterns, plate thicknesses ranging from 1.5 mm to 4.5 mm, and anatomically contoured profiles to stabilize bone after surgical cutting and realignment. These devices maintain fragment position during osseous healing while permitting early mobilization in weight-bearing applications. Locking plates command premium positioning due to angular stability advantages in osteoporotic bone, while titanium alloys capture preference over stainless steel for magnetic resonance imaging compatibility and reduced stress shielding. Biodegradable polymers represent the fastest-expanding material category as surgeons seek to eliminate secondary removal procedures in pediatric and adolescent patient populations.
The FDA's 510(k) premarket notification framework governs metallic osteotomy plate clearances in the United States, while the EU Medical Device Regulation mandates notified-body conformity assessments and clinical evidence for CE marking access across European markets. ISO 5832 standards for implant materials and ASTM F138 specifications for surgical stainless steel establish baseline metallurgical requirements that manufacturers must satisfy for regulatory acceptance. Stakeholders should monitor evolving biocompatibility testing protocols for magnesium-based resorbable alloys, as these materials could disrupt existing material hierarchies if long-term degradation profiles demonstrate equivalence to current titanium fixation outcomes.
Market Dynamics
Patient-specific 3D-printed osteotomy guides are compressing preoperative planning timelines and forcing traditional instrument kit suppliers to bundle digital surgical planning services or lose hospital contracts.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter conformity assessment requirements under the 2017/745 regulation are accelerating consolidation among notified bodies, favoring established plate manufacturers with robust quality management systems.
- High-volume trauma centers:Germany's specialized lower-limb realignment centers generate concentrated procedural demand that justifies dedicated osteotomy plate inventory and specialized surgical teams.
- Magnesium alloy resorption:Biodegradable fixation materials eliminate secondary removal surgeries in pediatric populations, expanding addressable indications beyond permanent implant candidates.
Market Restraints
- Titanium sponge price volatility:Raw material cost fluctuations for implant-grade titanium alloys compress margin buffers for mid-tier manufacturers without long-term supply agreements.
- Notified body capacity constraints:EU MDR implementation has reduced the pool of designated conformity assessment organizations, extending CE marking timelines by 12-18 months for new plate designs.
- Polymer screw mechanical limitations:Biodegradable fixation lacks torsional strength equivalence to metallic constructs in high-load metaphyseal applications, restricting adoption to specific anatomical sites.
Strategic Opportunities
- Outpatient surgery centers:Ambulatory surgical facilities in the United States seek streamlined osteotomy plate systems with reduced instrument tray complexity to support same-day discharge protocols.
- Software-hardware bundling:Preoperative planning platforms integrated with patient-specific cutting guides create recurring revenue streams beyond single-use implant sales.
- Japan's aging surgical population:METI reimbursement incentives for minimally invasive procedures favor locking plate technologies that reduce operative time in osteoporotic bone.
Industry Challenges
- Biomechanical modeling expertise:Manufacturers lack sufficient computational engineers to validate patient-specific plate designs against physiological loading conditions within compressed product development cycles.
- Legacy sterilization infrastructure:Hospital central sterile processing departments face tray consolidation pressure as customized instrument sets proliferate, creating workflow friction with expanded osteotomy plate portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osteotomy Plates Market |
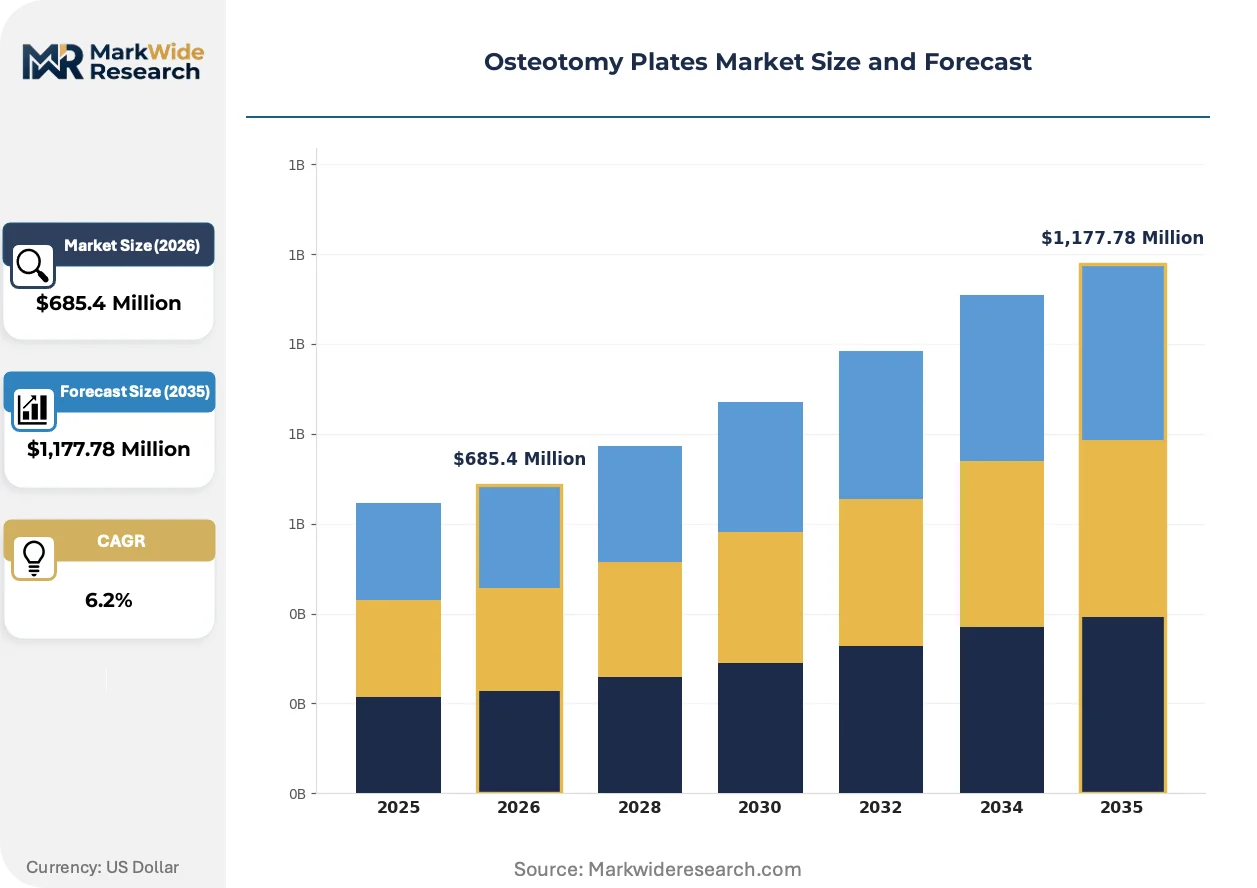
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locking Plates, Non-Locking Plates, Cannulated Plates, Reconstruction Plates Material: Titanium, Stainless Steel, Biodegradable Polymers, Composite Materials End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Trauma Centers Application: Joint Reconstruction, Limb Lengthening, Fracture Fixation, Osteochondral Defects |
| Companies Covered | DePuy Synthes, Stryker Corporation, Smith+Nephew, Zimmer Biomet, Arthrex, Inc., B. Braun Melsungen AG, Johnson & Johnson, Acumed LLC, OrthoPediatrics Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osteotomy Plates Market Strategic Shifts & Innovations
Digital surgical planning tools are migrating from standalone software licenses to embedded features within implant procurement contracts, reshaping how orthopedic vendors monetize preoperative services.
Point-of-care 3D printing is decentralizing production of anatomical models and surgical guides, allowing high-volume orthopedic centers to manufacture patient-specific osteotomy instruments in-house rather than outsourcing to centralized facilities. Academic medical centers in the United States and Germany have adopted hospital-based additive manufacturing workflows that compress guide delivery from two weeks to 48 hours. This capability is decentralizing the value chain for surgical planning services and eroding traditional instrument suppliers' service revenue.
The EU Medical Device Regulation's enhanced post-market surveillance requirements are mandating systematic clinical follow-up data collection for high-risk orthopedic implants, compelling manufacturers to invest in registry partnerships and real-world evidence infrastructure. Plate suppliers must now demonstrate sustained performance across extended follow-up periods rather than relying on premarket clinical studies alone. German trauma centers are responding by participating in national arthroplasty and osteotomy registries that satisfy MDR vigilance obligations.
Surgeon training programs are shortening the learning curve for complex realignment procedures through immersive simulation platforms that replicate specific osteotomy plate instrumentation sequences. Residency programs in the United States have integrated virtual reality modules for high-tibial osteotomy techniques, reducing cadaveric lab dependence. This pedagogical shift is visible most prominently in academic medical centers where fellowship-trained surgeons drive adoption of advanced fixation methods.
Osteotomy Plates Market Segmentation
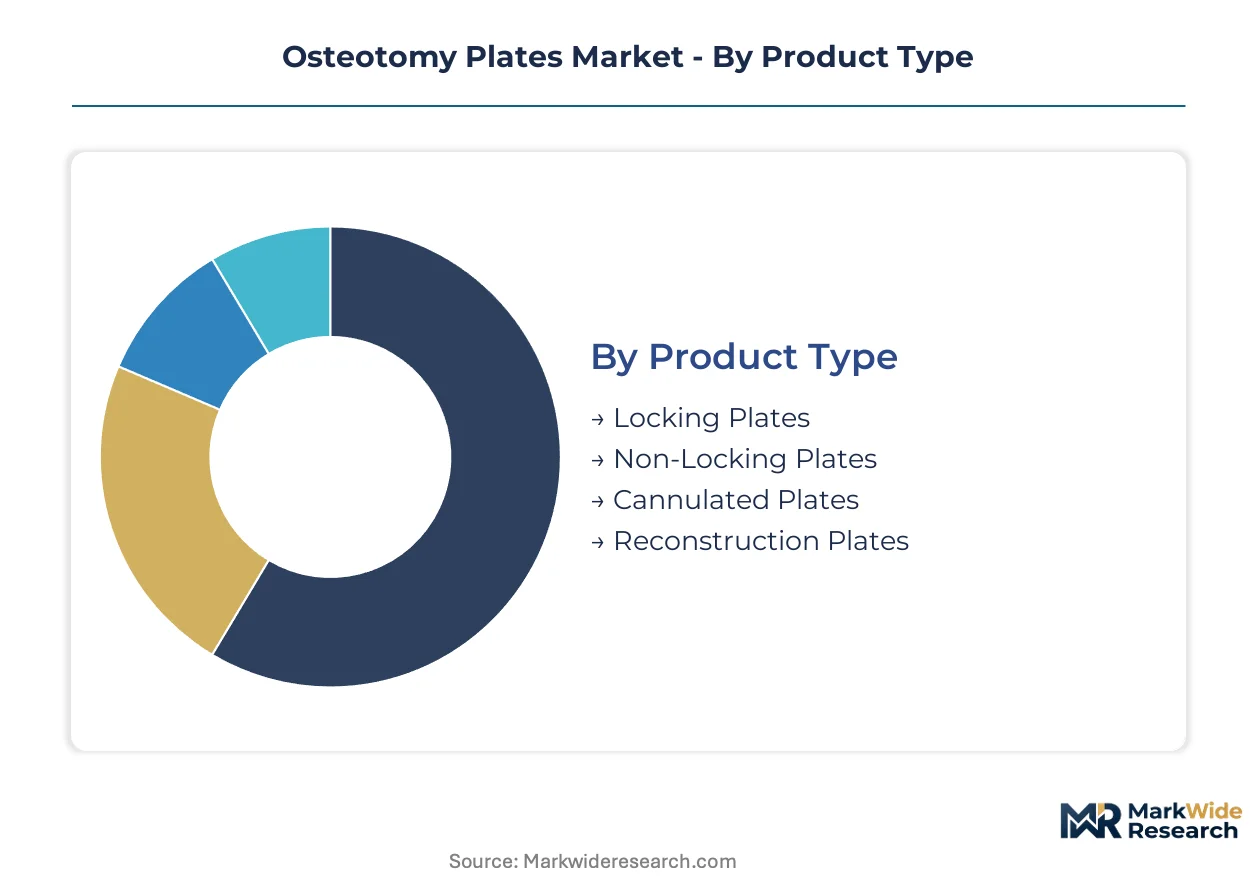
Osteotomy plate purchasing decisions fragment across multiple technical and clinical dimensions. Surgeons select fixation systems based on bone quality, anatomical site, and procedural setting rather than applying uniform specifications.
Product Type:
Upgrade cycles for plate systems accelerate as locking technology displaces conventional constructs in high-volume orthopedic centers.
- Locking Plates:These constructs employ threaded screw heads that lock into plate holes, creating angular stability independent of bone-plate friction. Demand concentrates in German trauma centers performing complex lower-limb realignment surgeries where osteoporotic bone compromises traditional compression fixation.
- Non-Locking Plates:Compression plates rely on friction between plate undersurface and bone cortex for stability, requiring precise contouring during implantation. These systems retain preference in cost-sensitive markets and straightforward metaphyseal osteotomies where bone quality supports conventional fixation mechanics.
- Cannulated Plates:Hollow-core designs accommodate guidewire placement for minimally invasive surgical techniques.
- Reconstruction Plates:Malleable profiles permit intraoperative bending to match complex anatomical contours.
Locking plates sit at the top of the volume ranking, with cannulated plates climbing the fastest.
Material:
Material selection cost tiers separate premium titanium systems from standard stainless steel offerings across procurement categories.
- Titanium:Implant-grade titanium alloys exhibit superior strength-to-weight ratios and magnetic resonance imaging compatibility. Japanese orthopedic centers under METI reimbursement incentives favor these materials for reduced stress shielding and enhanced postoperative imaging flexibility.
- Stainless Steel:Surgical stainless steel per ASTM F138 specifications delivers cost-effective mechanical performance with established supply chain reliability. These alloys dominate emerging market procurement where procurement budgets prioritize capital efficiency over advanced material properties.
- Biodegradable Polymers:Resorbable fixation eliminates secondary removal surgeries in pediatric populations.
- Composite Materials:Hybrid constructs combine metallic strength with polymer modularity for specialized applications.
Titanium commands the premium tier by revenue contribution, while biodegradable polymers are expanding most quickly.
End User:
Customer type determines tray complexity requirements and service bundling expectations across the delivery infrastructure.
- Hospitals:Academic medical centers maintain comprehensive osteotomy plate inventories spanning multiple anatomical applications. These institutions generate concentrated demand for integrated power tools and navigation-compatible systems that support fellowship-trained surgical teams.
- Ambulatory Surgical Centers:Outpatient facilities prioritize streamlined instrument sets with reduced sterilization burden. Same-day discharge protocols in United States ambulatory settings favor simplified plate systems that compress operative time and post-anesthesia recovery.
- Orthopedic Clinics:Specialized practices drive adoption of patient-specific planning solutions.
- Trauma Centers:High-acuity facilities require rapid availability across fracture fixation and realignment indications.
Hospitals anchor procurement volume, with ambulatory surgical centers gaining share fastest.
Application:
Procedure-specific mechanical demands dictate plate thickness, screw density, and anatomical contouring requirements.
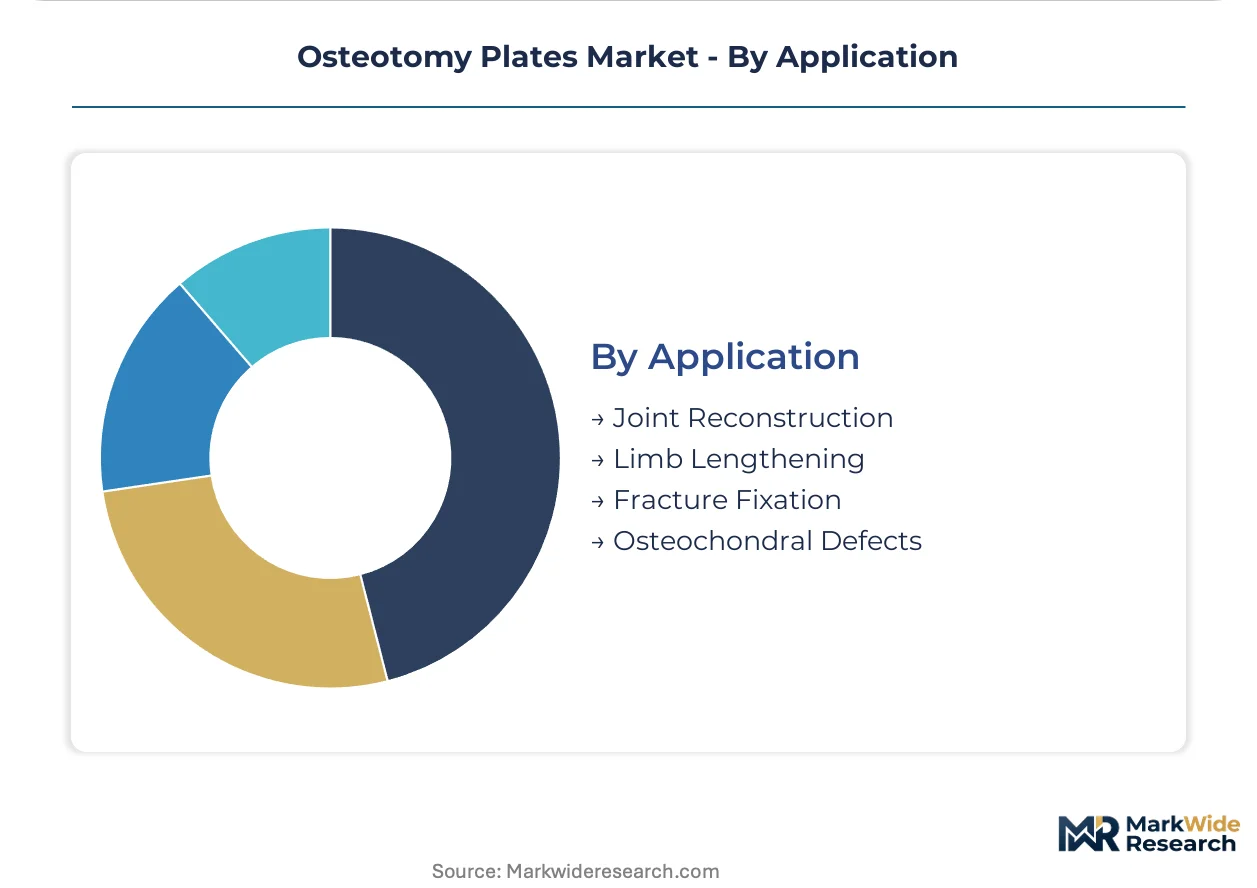
- Joint Reconstruction:High-tibial and distal femoral osteotomies for knee preservation require anatomically precontoured plates with polyaxial screw options. German specialized trauma centers generate procedural volume that justifies dedicated inventory and surgeon training pathways.
- Limb Lengthening:Gradual distraction osteogenesis demands plates compatible with external fixation transitions and weight-bearing progression. These applications concentrate in pediatric orthopedic centers managing congenital and developmental limb discrepancies.
- Fracture Fixation:Acute trauma applications require rapid implant availability across multiple sizes.
- Osteochondral Defects:Cartilage restoration procedures utilize low-profile plates for subchondral support.
Joint reconstruction leads application volume, with limb lengthening showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The osteotomy plates industry traces its modern origins to German orthopedic engineering traditions established in the mid-20th century, with subsequent scaling through trauma center specialization across Central Europe and North America.
United States
Ambulatory surgical centers and academic medical centers drive procedural volume for knee preservation surgeries. The FDA's 510(k) premarket notification pathway accelerates commercialization timelines for metallic implant systems. The Boston-Cambridge corridor hosts concentration of digital surgical planning firms integrating with plate manufacturers.
Germany
Specialized lower-limb realignment centers generate concentrated demand for locking plate systems in osteoporotic bone applications. The EU Medical Device Regulation mandates notified-body conformity assessments that favor established manufacturers with robust quality management systems. The Ruhr-Rhine industrial cluster maintains precision machining capabilities for titanium alloy implant production.
Japan
Aging surgical populations and METI reimbursement incentives favor minimally invasive procedures with reduced operative times. The Pharmaceuticals and Medical Devices Agency oversees premarket approvals for orthopedic implants with enhanced post-market surveillance requirements. The Kanto region around Tokyo anchors procurement volume for navigation-compatible fixation systems.
China
Expanding hospital infrastructure and rising procedural volumes for joint preservation surgeries create demand for cost-effective plate systems. The National Medical Products Administration governs Class III medical device registrations with increasing emphasis on clinical evidence. The Yangtze River Delta manufacturing base supplies titanium sponge processing for domestic implant production.
Switzerland
Swissmedic regulatory frameworks emphasize biocompatibility testing protocols that influence material selection across European markets. Precision engineering clusters in the Basel-Zurich corridor specialize in additive manufacturing for patient-specific surgical guides. Private orthopedic clinics drive adoption of bundled hardware-software planning solutions.
Osteotomy Plates Market Key Industry Players
Premium-margin players sit above commodity-margin players across material technology and regulatory certification dimensions. The vendor base organizes into three tiers: integrated orthopedic conglomerates with broad trauma portfolios, specialized limb-reconstruction firms with bundled planning tools, and regional manufacturers serving cost-sensitive procurement channels. Dominant competitive moves include strategic partnerships with digital surgical planning platforms and backward integration into titanium alloy supply chains.
Among integrated orthopedic conglomerates, DePuy Synthes and Stryker Corporation exemplify scale-driven archetypes with diversified trauma portfolios, while Zimmer Biomet occupies a position within the specialized reconstruction tier through bundled hardware-software offerings. These three entities anchor competitive dynamics across hospital contracting channels, ambulatory surgical center procurement, and academic medical center adoption pathways.
| Leading Market Players |
|---|
| DePuy Synthes |
| Stryker Corporation |
| Smith+Nephew |
| Zimmer Biomet |
| Arthrex, Inc. |
| B. Braun Melsungen AG |
| Johnson & Johnson |
| Acumed LLC |
| OrthoPediatrics Corp. |
| Others |
Cost & Logistics Intelligence
Titanium sponge volatility feeds directly into three-tier pricing stratification across premium titanium systems, standard stainless steel constructs, and economy-grade polymer alternatives. German trauma centers absorb premium locking-plate costs through dedicated reimbursement pathways, while ambulatory surgical centers in the United States pressure vendors to compress instrument-kit pricing for same-day discharge protocols.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared titanium locking systems from CE-marked stainless steel plates and emerging biodegradable polymer alternatives. Price differentiation hinges on ISO 5832 material certification tiers and bundled digital planning software inclusion. Pricing pressure stems from titanium sponge cost volatility squeezing mid-tier manufacturers without long-term supply agreements. Ambulatory surgical centers exhibit highest price sensitivity, while German specialized trauma centers prioritize angular stability over procurement cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese titanium sponge processing, where the Yangtze River Delta concentrates implant-grade alloy production. Manufacturing draws from German precision machining clusters for plate finishing and Swiss additive manufacturing facilities for patient-specific guide production. Supply chain risk centers on EU MDR notified-body capacity constraints extending CE marking timelines. Distribution runs through hospital GPO contracts in the United States and direct procurement channels with specialized trauma centers in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between German premium-reimbursement environments and United States ambulatory cost-compression dynamics, with regulatory pathway efficiency determining margin capture.
For Market Incumbents: Cement hospital contracting dominance by deepening backward integration into titanium alloy supply chains and securing long-term GPO agreements before EU MDR consolidation eliminates mid-tier competitors. Magnesium-alloy resorbable fixation represents the primary substitution threat requiring pre-emptive patent positioning and clinical registry investment to defend permanent-implant revenue streams. For New Entrants and Emerging Players: Begin with biodegradable polymer fixation for pediatric limb-lengthening applications, where secondary removal surgery elimination creates reimbursement leverage and regulatory pathways remain less congested than adult joint reconstruction. Target ambulatory surgical center procurement committees with streamlined instrument sets that reduce sterile processing burden and support same-day discharge protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed revenue thresholds for sub-scale manufacturers lacking notified-body relationships and quality-management infrastructure. Acquisition candidates include specialized limb-reconstruction firms with bundled hardware-software offerings and established registry partnerships. The signal to watch is notified-body designation withdrawals, which will force distressed exits among non-compliant plate suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR compliance secures market access across German trauma center procurement channels. |
| Hospital System Partnership | GPO contracts with academic medical centers lock out competing plate manufacturers. |
| Software Companion Development | Preoperative planning platforms create recurring revenue beyond single-use implant sales. |
| Reimbursement Strategy | METI incentive alignment in Japan accelerates locking-plate adoption for aging surgical populations. |
| FDA 510(k) Submission Acceleration | Premarket notification efficiency compresses commercialization timelines for metallic implant systems. |
Research Approach
Multiple input streams — orthopedic surgeon interviews, hospital procurement database analysis, regulatory filing review, and titanium alloy trade-flow tracking — were reconciled to construct segment-level demand estimates. Primary discussions included fellowship-trained limb-reconstruction surgeons, GPO contracts managers, biomedical engineers at academic medical centers, and notified-body technical assessors. Secondary validation drew from FDA 510(k) clearances, EU MDR designation databases, CMS Medicare reimbursement schedules, and ISO 5832 material standard revisions. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations.
Data-stream reconciliation anchored volume projections across the analysis window to German trauma center procedural registries, Japanese METI reimbursement filings, and United States ambulatory surgery center utilization trends. Segmentation modeling incorporated plate type, material grade, end-user facility category, and anatomical application site. CAGRs were derived from procedure volume elasticity against aging demographics, regulatory pathway efficiency differentials, and material substitution trajectories. Forecast inputs included titanium sponge price indices, notified-body capacity utilization rates, and 3D-printed guide adoption curves.
Caveats apply where titanium sponge supply disruptions, notified-body designation withdrawals, or magnesium-alloy degradation profile failures could materially shift the outlook. Forecasts reflect assumptions about reimbursement stability, regulatory pathway continuity, and surgeon training program expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Outsourcing Market
Medical Devices
Nasal Implant Market
Medical Devices
Clinical Rollators Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Global Vaginal Sling Market
Medical Devices
Eye Massage Device Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
Global Blood Banking Devices Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Asia Pacific Apheresis Market