
 Digital Stethoscope Market | 2026-2036
Digital Stethoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Stethoscope Market Analysis
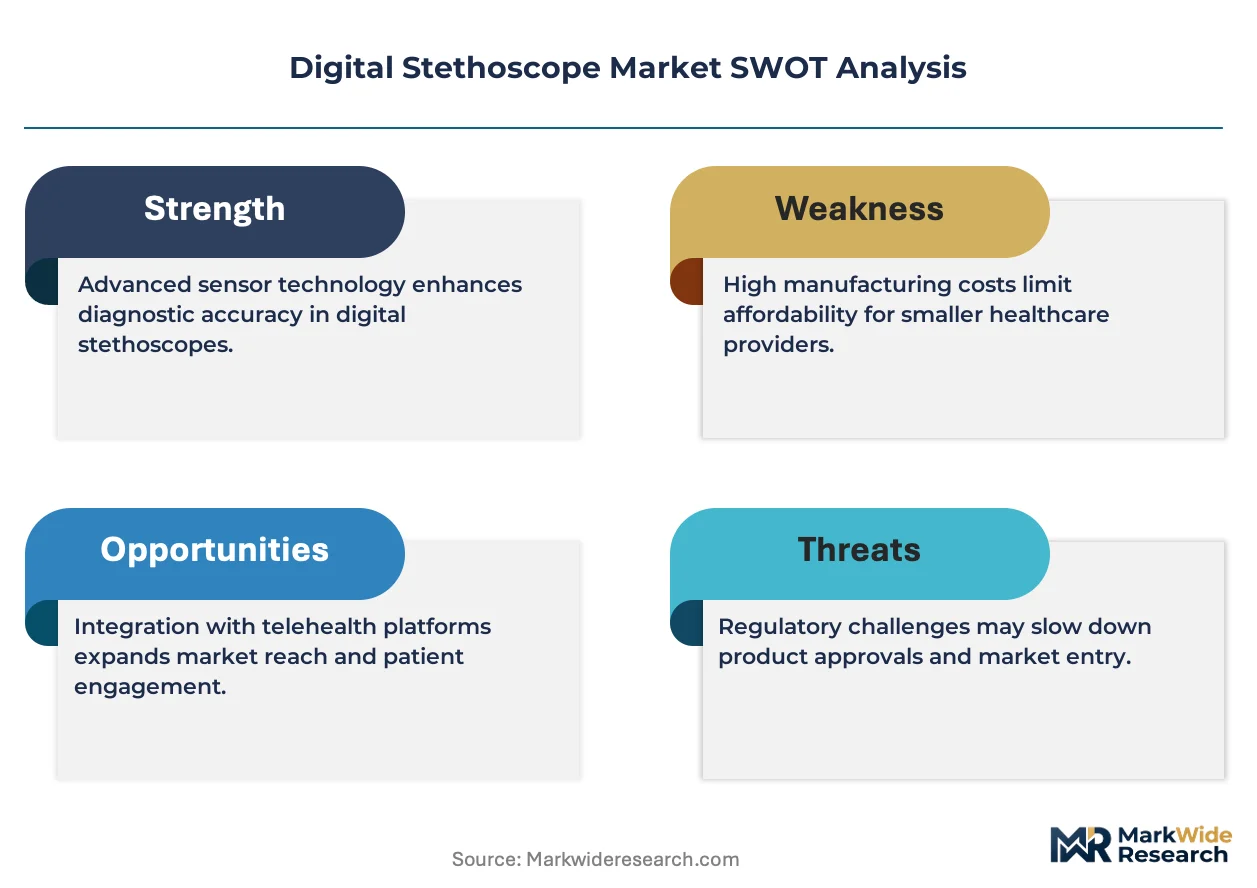
The direct-to-clinic sales channel is narrowing as telehealth platforms and medical equipment suppliers consolidate procurement decisions for connected diagnostic devices. Eko Health leverages FDA-cleared AI algorithms to anchor its position in cardiology screening workflows. 3M Littmann sustains brand dominance through backward integration into acoustic sensor manufacturing. HD Medical specializes in wireless form factors that compete on signal fidelity against traditional analog alternatives.
A digital stethoscope converts acoustic heart and lung sounds into electronic signals via piezoelectric or MEMS sensors, typically sampling at 44.1 kHz with 16-bit resolution for clinical-grade reproduction, then transmits data through Bluetooth or USB to visualization software for real-time waveform analysis and remote consultation. Wireless stethoscope configurations now lead volume shipments as homecare providers and telehealth services prioritize untethered patient examinations. Smartphone-compatible stethoscopes represent the fastest-growing product category because they eliminate dedicated hardware costs while integrating with existing clinical communication platforms.
FDA 510(k) clearance requirements shape product development cycles and predicate device selection for AI-enhanced auscultation tools entering the United States market. The EU Medical Device Regulation (MDR) and CE marking obligations enforce clinical evidence standards that filter out lower-technology entrants across European markets. Stakeholders must monitor evolving reimbursement codes for remote physiological monitoring as payers determine whether digital auscultation qualifies for separate billing or bundles into existing telehealth fee schedules.
Market Dynamics
Telehealth infrastructure deployment is compressing procurement cycles for connected diagnostic devices, forcing manufacturers to integrate FDA-cleared AI algorithms directly into hardware platforms rather than selling standalone acoustic sensors.
Growth Catalysts
- Remote Patient Monitoring Infrastructure:United States healthcare systems are deploying Bluetooth-enabled auscultation tools across homecare networks to reduce hospital readmission penalties under CMS value-based care programs.
- FDA 510(k) Clearance Pathways:Streamlined predicate device recognition for AI-enhanced stethoscopes is accelerating product development timelines for cardiology screening applications.
- MEMS Sensor Miniaturization:Piezoelectric transducer advances are enabling wireless form factors that match analog stethoscope acoustic fidelity at lower unit costs.
Market Restraints
- Silicon Supply Concentration:Taiwan-based foundries control 65% of MEMS microphone wafer production, creating input vulnerability for sensor manufacturers.
- EU MDR Clinical Evidence Requirements:The Medical Device Regulation mandates extensive performance testing that filters out lower-technology entrants from European markets.
- Reimbursement Code Uncertainty:Payer determination of whether digital auscultation qualifies for separate CPT billing or bundles into existing telehealth fee schedules creates revenue recognition risk.
Strategic Opportunities
- Smartphone-Compatible Form Factors:Elimination of dedicated hardware costs through 3.5mm jack and USB-C adapters opens veterinary and emergency medical services segments previously priced out of digital adoption.
- India PLI Scheme for Medical Devices:Production-linked incentive programs for electronics manufacturing are attracting contract assembly partners to serve South Asian and Middle Eastern demand.
- AI-Cloud Convergence:Real-time machine learning inference on edge devices combined with centralized waveform databases enables population-level cardiac screening programs.
Industry Challenges
- FDA Software-as-a-Medical-Device Validation:Algorithm update protocols require documented verification workflows that extend engineering timelines and complicate post-market surveillance obligations.
- Interoperability with Legacy EHR Systems:HL7 FHIR integration demands specialized health informatics talent that mid-size device manufacturers struggle to recruit against enterprise software competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Stethoscope Market |
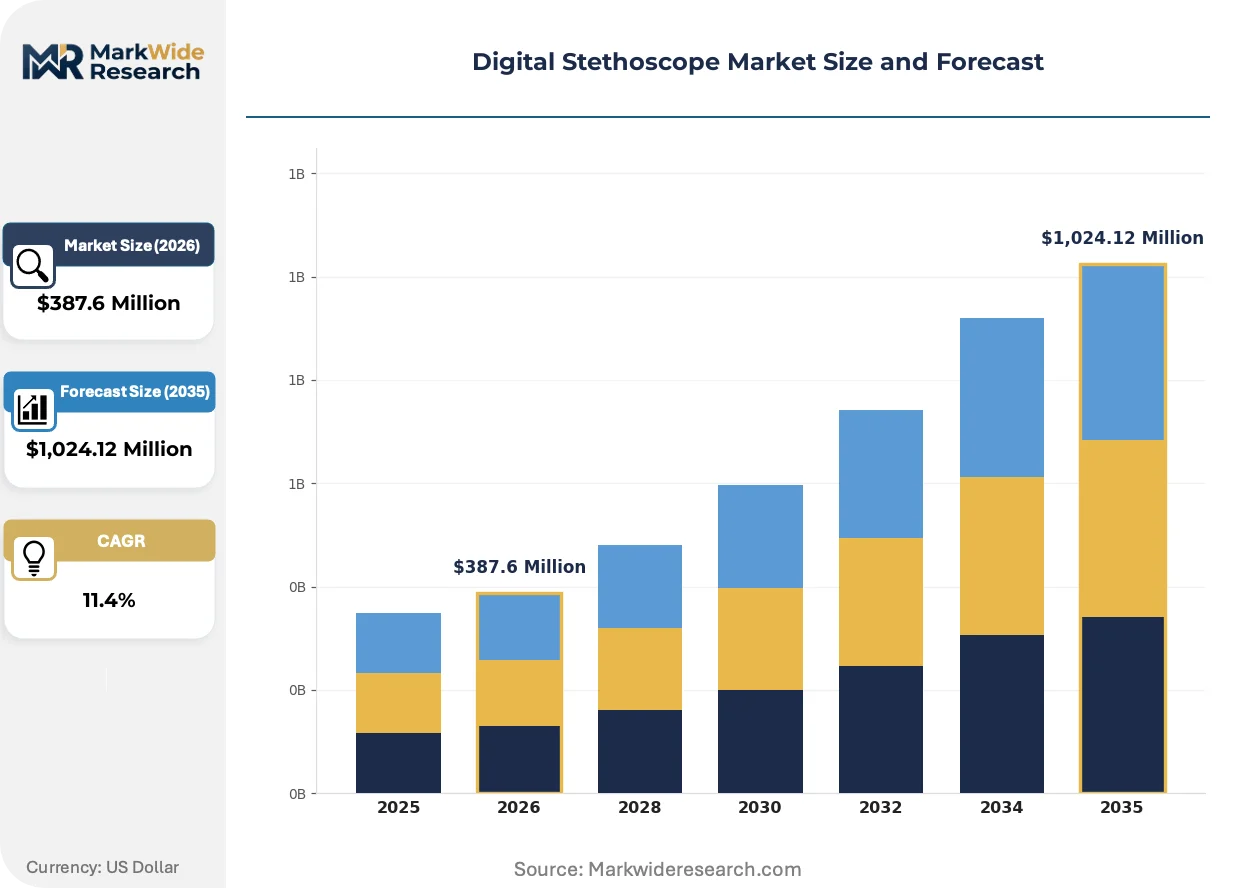
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Stethoscope, Bluetooth Stethoscope, Smartphone-Compatible Stethoscope, Dual-Head Stethoscope End User: Hospitals, Clinics, Homecare Providers, Telehealth Services Technology: Analog-to-Digital Converter, Noise-Cancellation Technology, Signal Amplification, Cloud Integration Delivery Mode: Online Retail, Direct Sales, Distributors, Medical Equipment Suppliers |
| Companies Covered | HD Medical, Cardionics, Solventum, American Diagnostic Corporation, Welch Allyn, Eko Health, 3M Littmann, Rudolf Riester, Thinklabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Stethoscope Market Emerging Trajectories
Signal processing hardware and regulatory frameworks for AI diagnostics are converging to redefine how auscultation data flows through clinical workflows and remote care platforms.
MEMS-based acoustic sensors are digitizing heart and lung sound capture at 44.1 kHz sampling rates with 16-bit resolution. Rural health clinics and homecare nurses are adopting these wireless configurations to replace analog alternatives during untethered patient examinations. This sensor transition is digitizing the entire diagnostic chain from bedside capture to specialist consultation, compressing the need for dedicated hardware intermediaries.
The EU Medical Device Regulation enforces clinical evidence standards that predicate device manufacturers must satisfy for CE marking renewal. European notified bodies are demanding expanded performance validation for AI-enhanced classification features. Cardiology-focused stethoscope vendors are responding by front-loading clinical trial investment to secure MDR certificates before 2027 recertification deadlines.
Telehealth platforms are consolidating procurement decisions for connected diagnostic devices, displacing traditional direct-to-clinic sales relationships. Medical equipment suppliers and virtual care networks now negotiate enterprise licenses spanning multiple specialties and geographies. This channel concentration is most visible in United States integrated delivery networks, where standardized device fleets reduce training overhead and simplify supply chain management across affiliated clinics.
Digital Stethoscope Market Segmentation
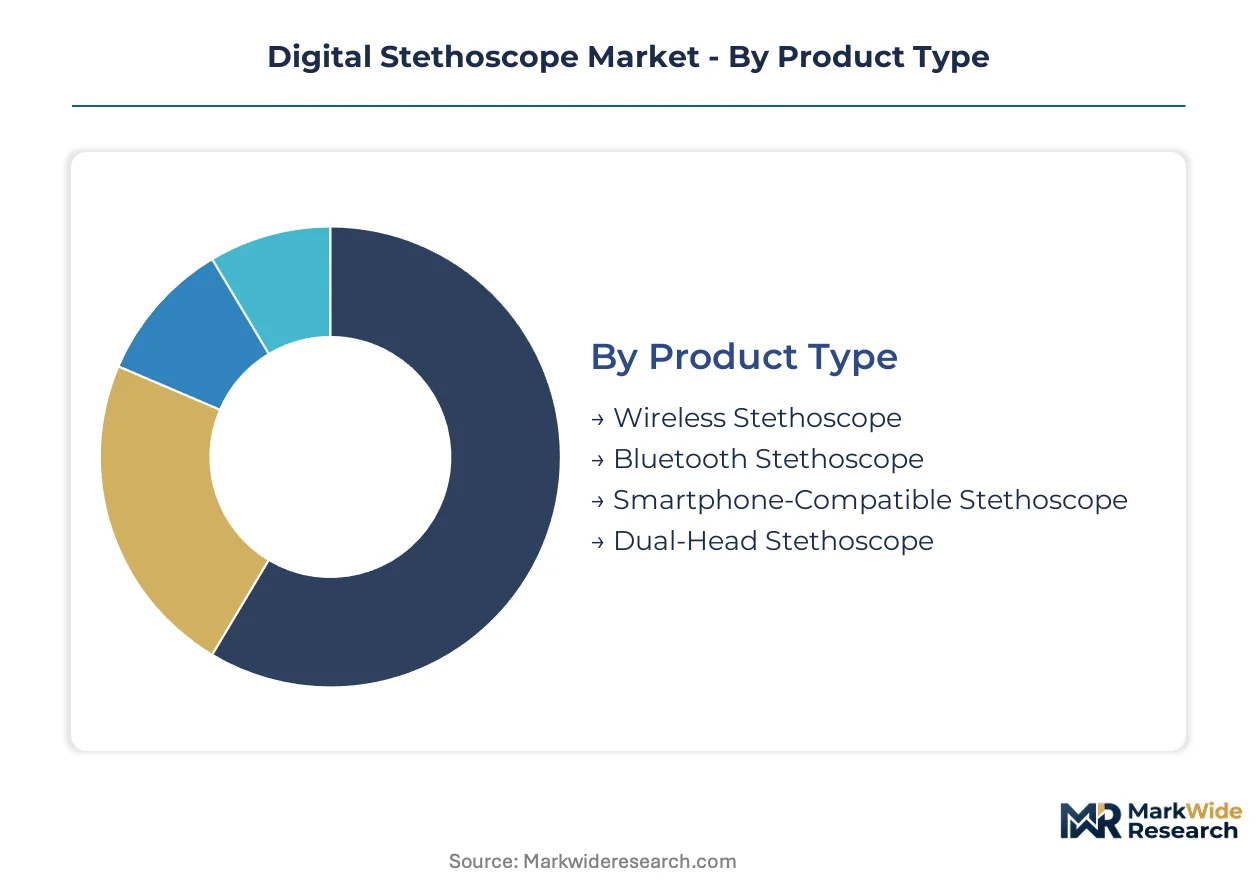
Digital stethoscope segmentation reveals how hardware form factors, clinical settings, and procurement channels fragment into distinct commercial battlegrounds. Each dimension carries specific technical requirements and regulatory burdens that shape vendor positioning.
Product Type:
Mature wireless configurations dominate hospital procurement while emerging smartphone adapters unlock veterinary and emergency services segments previously priced out of digital adoption.
- Wireless Stethoscope:Untethered configurations sampling at 44.1 kHz with 16-bit resolution now anchor hospital fleet deployments across United States integrated delivery networks. Bluetooth Low Energy transmission eliminates cable clutter during bedside examinations while maintaining signal fidelity for cardiology screening workflows.
- Smartphone-Compatible Stethoscope:3.5mm jack and USB-C adapters eliminate dedicated hardware costs by leveraging existing clinical communication platforms. Homecare nurses and rural health clinics in Germany and Japan are adopting these configurations fastest as telehealth services prioritize capital-efficient device rollouts.
- Bluetooth Stethoscope:Dedicated wireless modules with paired receiver units serve specialist consultation workflows requiring guaranteed connectivity.
- Dual-Head Stethoscope:Combined bell and diaphragm sensors in digital form factors preserve traditional auscultation training for medical education markets.
Wireless stethoscopes handle the majority of throughput; smartphone-compatible configurations are expanding most quickly on share.
End User:
Cost tier segmentation separates capital-rich hospital systems from budget-constrained homecare networks with diverging performance requirements.
- Hospitals:Enterprise fleet deployments demand FDA 510(k) cleared devices with centralized device management and EHR integration through HL7 FHIR protocols. United States academic medical centers are standardizing on AI-enhanced platforms for cardiology screening.
- Telehealth Services:Virtual care networks negotiate multi-specialty enterprise licenses spanning cardiology, pulmonology, and primary care. These platforms are consolidating procurement decisions and displacing traditional direct-to-clinic sales relationships.
- Clinics:Outpatient facilities prioritize single-device flexibility across examination rooms with simplified training requirements.
- Homecare Providers:Bluetooth-enabled tools support remote patient monitoring programs under CMS value-based care frameworks.
Hospitals absorb the largest procurement volumes; telehealth services are climbing the fastest as channel concentration accelerates.
Technology:
Volume concentration sits with core signal processing hardware while margin capture flows to AI-enhanced classification layers.
- Analog-to-Digital Converter:Piezoelectric and MEMS sensors digitize acoustic capture at clinical-grade specifications, forming the foundational layer where Taiwan-based foundries control MEMS microphone wafer production.
- Noise-Cancellation Technology:Adaptive filtering algorithms isolate heart and lung sounds from ambient clinical environments, essential for emergency medical services and air transport applications.
- Signal Amplification:Low-noise preamplification circuits boost faint murmurs and bruits to diagnostic levels for pediatric and geriatric patients.
- Cloud Integration:Real-time waveform transmission to centralized databases enables population-level cardiac screening programs and specialist consultation networks.
Analog-to-digital conversion handles the majority of component shipments; cloud integration is gaining share fastest as AI-cloud convergence matures.
Delivery Mode:
Customer type fragmentation separates enterprise procurement teams from individual practitioner purchasing with diverging service expectations.
- Medical Equipment Suppliers:Consolidated distributors now negotiate standardized device fleets across United States integrated delivery networks, reducing training overhead and simplifying supply chain management.
- Direct Sales:Manufacturer field organizations serve high-volume hospital accounts with specialized health informatics talent for EHR integration.
- Distributors:Regional medical device wholesalers maintain inventory positions for mid-size clinic chains with shorter procurement cycles.
- Online Retail:E-commerce channels serve individual practitioners and veterinary segments with lower minimum order quantities.
Medical equipment suppliers control the majority of throughput; direct sales channels are expanding most quickly as telehealth platforms consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States healthcare grid anchors digital stethoscope demand through CMS value-based care programs that penalize hospital readmissions. Germany's dense hospital network and Japan's aging demographic infrastructure create parallel adoption corridors for connected auscultation tools.
United States
FDA 510(k) clearance pathways compress development timelines for AI-enhanced cardiology screening devices. CMS remote patient monitoring reimbursement codes determine whether digital auscultation qualifies for separate billing under value-based care frameworks. The Boston-Cambridge corridor concentrates health informatics talent for HL7 FHIR EHR integration projects.
Germany
EU MDR clinical evidence requirements filter lower-technology entrants from CE marking renewal processes before 2027 deadlines. The country's national pharmaceutical regulator enforces expanded performance validation for AI-enhanced classification features. Baden-Württemberg hosts precision sensor manufacturers supplying MEMS microphone wafers for wireless form factors.
Japan
METI deployment of remote patient monitoring infrastructure targets rural healthcare access gaps for aging populations. PMDA regulatory harmonization with FDA predicate device recognition accelerates product registration for cardiology applications. The Osaka-Kobe industrial zone concentrates medical device assembly operations for Asia-Pacific distribution.
India
Production-linked incentive schemes for electronics manufacturing attract contract assembly partners to serve South Asian and Middle Eastern demand. CDSCO medical device regulations align with international standards to streamline import substitution for diagnostic equipment. Karnataka's Bengaluru-Tumkur corridor hosts emerging health technology clusters focused on affordable diagnostic hardware.
United Kingdom
NHS Long Term Plan commitments to virtual care expand telehealth procurement for connected diagnostic devices across integrated care systems. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for software-as-a-medical-device innovations. The Oxford-Cambridge Arc concentrates digital health venture capital flowing into auscultation AI development.
Digital Stethoscope Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: acoustic heritage manufacturers with backward integration into sensor production, AI-native platform developers securing FDA-cleared algorithms, and wireless hardware specialists competing on signal fidelity. Dominant competitive moves include enterprise licensing negotiations with telehealth platforms and clinical trial investment to secure MDR certificates ahead of 2027 renewal deadlines.
Within the AI-enhanced tier, Eko Health and Thinklabs exemplify algorithm-first positioning that anchors cardiology screening workflows. HD Medical occupies a position among wireless form factor specialists competing on untethered examination capabilities. 3M Littmann represents acoustic heritage manufacturers leveraging in-house sensor production to sustain brand dominance across hospital fleet deployments.
| Leading Market Players |
|---|
| HD Medical |
| Cardionics |
| Solventum |
| American Diagnostic Corporation |
| Welch Allyn |
| Eko Health |
| 3M Littmann |
| Rudolf Riester |
| Thinklabs |
| Others |
Supply Flow & Price Mechanics
The Kaohsiung-Taoyung freight corridor's container rates transmit cost volatility directly to MEMS microphone wafer procurement, amplifying pricing power for Taiwan-based foundries while forcing tiered cost absorption across downstream device manufacturers serving hospital and homecare segments.
Pricing Analysis
Volume-discount tiering separates enterprise fleet contracts for United States integrated delivery networks from single-unit purchases by rural clinics and veterinary practices. Pricing stratifies across FDA 510(k) cleared AI-enhanced platforms, standard Bluetooth-enabled devices, and economy smartphone adapters. Cost compression in the standard tier intensifies as telehealth platforms consolidate procurement decisions and squeeze supplier margins. Homecare providers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize certification grade over unit cost.
Supply Chain Analysis
Extended payment terms from medical equipment suppliers now stretch to 90-120 days for Taiwan-based MEMS foundries, straining working capital across sensor manufacturers. Component sourcing draws from Taiwan for MEMS wafers, Germany for precision acoustic housings, and Japan for low-noise preamplification circuits. Single-source vulnerability concentrates in Taiwan's 65% share of MEMS microphone production, exposing device makers to geopolitical disruption. Distribution runs through consolidated medical equipment suppliers serving United States integrated delivery networks, with direct sales expanding for telehealth platform enterprise licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth infrastructure deployment fragments procurement authority across virtual care networks, specialty clinics, and homecare programs, creating multiple entry points for differentiated positioning beyond incumbent hospital fleet dominance.
For Market Incumbents: Harden algorithm differentiation through accelerated FDA 510(k) submissions for expanded cardiology indications, locking in predicate device advantages before 2027 EU MDR recertification deadlines. Deepen backward integration into MEMS sensor production to offset Taiwan foundry pricing power and secure supply continuity for wireless form factor rollouts. For New Entrants and Emerging Players: Build out smartphone-compatible stethoscope offerings targeting veterinary practices and emergency medical services, segments previously priced out of digital adoption by dedicated hardware costs. Prioritize USB-C and 3.5mm jack adapters that leverage existing clinical communication platforms, using channel partnerships with regional distributors to bypass consolidated hospital procurement gates. For Investors and Strategic Acquirers: AI-native platform developers with FDA-cleared algorithms and established telehealth platform integrations represent the most defensible acquisition targets for long-term viability. Monitor CMS reimbursement code determinations for remote physiological monitoring as the critical inflection signal; separate CPT billing for digital auscultation would unlock substantial revenue expansion and validate AI-enhanced diagnostic premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Secures predicate device recognition for AI-enhanced cardiology screening algorithms in United States markets. |
| CE Marking Pathway | Front-loads clinical trial investment to satisfy EU MDR performance validation before 2027 renewal deadlines. |
| Hospital System Partnership | Standardizes device fleets across United States integrated delivery networks, reducing training overhead. |
| Software Companion Development | Enables HL7 FHIR EHR integration that mid-size manufacturers struggle to build in-house. |
| Reimbursement Strategy | Positions digital auscultation for separate CMS billing codes under value-based care frameworks. |
Methodological Framework
Operator-level perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and telehealth platform procurement leads anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from device shipment data and component supply chain disclosures.
Scenario-bracketing framed optimistic, baseline, and conservative volume assumptions across the projection horizon, with segmentation dimensions spanning product type, end user, technology layer, and delivery mode. CAGRs were derived from fitted growth curves applied to annual shipment estimates, incorporating MEMS sensor cost trajectories, regulatory approval timelines, and telehealth infrastructure deployment schedules as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-native platform developers or MEMS foundry capacity expansion would shift outcomes. Macroeconomic contraction affecting healthcare capital expenditure, regulatory delay in CMS reimbursement determinations, or technological disruption from alternative cardiac monitoring modalities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
North America Pen Needles Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Global Peripheral IV Catheters Market
Medical Devices
Vaginal Applicators Market
Medical Devices
Global Breast Implants Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Heat Therapy Units Market
Medical Devices
ADA Substitute Market
Medical Devices
Argentina Ultrasound Devices Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Anesthesia Vaporizers Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market