
 Europe Viscosupplementation Market | 2026-2036
Europe Viscosupplementation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Viscosupplementation Market Foresight
Single-source supply agreements for hyaluronic acid raw material are consolidating into multi-source frameworks across European viscosupplementation manufacturing. Sanofi S.A. leverages its integrated pharmaceutical distribution network to secure hospital formulary placement in France and Italy. Anika Therapeutics, Inc. sustains competitive positioning through specialized R&D in cross-linked sodium hyaluronate formulations. Fidia Farmaceutici S.p.A. anchors regional production gravity with manufacturing facilities concentrated in Northern Italy.
Viscosupplementation refers to intra-articular injection of hyaluronic acid or derivatives to restore synovial fluid viscosity and reduce mechanical joint friction, typically requiring molecular weights between 500 and 6,000 kDa for optimal rheological performance. Hyaluronic acid products dominate current revenue pools due to established reimbursement codes and clinician familiarity, while cross-linked sodium hyaluronate formulations represent the fastest-growing segment driven by extended residence time in the joint cavity and reduced injection frequency protocols. Orthopedic clinics capture the largest end-user share, though sports medicine centers are expanding fastest as athletic injury recovery applications broaden beyond geriatric osteoarthritis populations.
EMA oversight through the Medical Device Regulation and national competent authorities in Germany, France, and Italy enforce clinical evidence requirements that shape product registration timelines and market access conditions. REACH compliance for hyaluronic acid sourcing adds supply chain documentation burdens that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor reimbursement recalibration decisions by statutory health insurers in Germany and France, as these will determine whether premium cross-linked formulations retain favorable tariff positioning against standard hyaluronic acid alternatives.
Market Dynamics
The EU Medical Device Regulation is tightening clinical evidence requirements and reshaping competitive access across European viscosupplementation markets. This regulatory compression favors established manufacturers with dedicated regulatory affairs infrastructure while raising barriers for new entrants.
Growth Catalysts
- MDR Compliance Frameworks:The Medical Device Regulation's phased implementation deadlines are accelerating consolidation among manufacturers with pre-existing CE-marked portfolios. Germany's notified bodies are processing technical documentation faster than Southern European counterparts.
- Sports Medicine Infrastructure:Spain's expanding network of dedicated sports medicine centers is broadening viscosupplementation applications beyond geriatric populations into athletic injury recovery protocols.
- Cross-linked Formulation R&D:Extended residence time technologies are reducing injection frequency requirements and improving patient compliance metrics in orthopedic clinic settings.
Market Restraints
- Hyaluronic Acid Supply Concentration:Raw material sourcing remains dependent on a limited cohort of fermentation-based suppliers concentrated in Northeast Asia, creating price volatility exposure for European formulators.
- REACH Documentation Burden:Chemical registration requirements for hyaluronic acid intermediates impose compliance costs that disproportionately impact small-to-mid scale manufacturers without dedicated regulatory teams.
- Reimbursement Compression:Statutory health insurers in France and Germany are recalibrating tariff structures, threatening premium positioning for cross-linked formulations against standard hyaluronic acid alternatives.
Strategic Opportunities
- Italian Manufacturing Expansion:Northern Italy's existing pharmaceutical production clusters offer underutilized sterile filling capacity for viscosupplementation contract manufacturing.
- Ambulatory Surgical Center Networks:Germany's outpatient clinic infrastructure is creating direct-to-provider distribution channels that bypass traditional hospital pharmacy gatekeepers.
- Single-Injection Protocols:High molecular weight cross-linked formulations are enabling reduced treatment regimens that align with payer cost-containment objectives.
Industry Challenges
- Clinical Evidence Generation:MDR-compliant post-market surveillance requires sustained investment in real-world outcome registries that smaller manufacturers struggle to fund.
- Formulation Stability Expertise:Cross-linking chemistry specialization remains concentrated among a narrow talent pool, constraining R&D velocity for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Viscosupplementation Market |
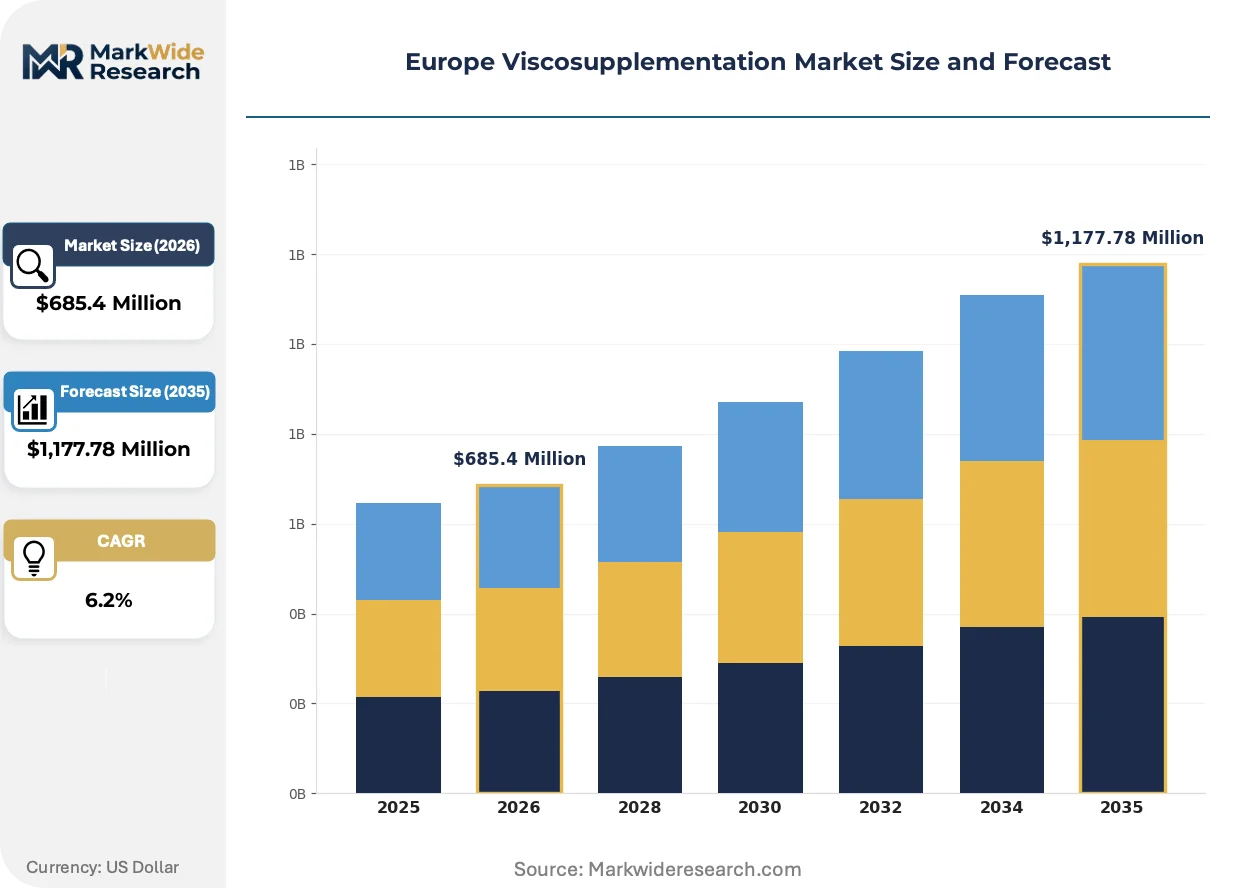
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Gel-Conditioned Serum, Cross-Linked Sodium Hyaluronate, Natural Based Products End User: Orthopedic Clinics, Sports Medicine Centers, Rehabilitation Facilities, Home Healthcare Delivery Mode: Intra-Articular Injection, Intravenous Injection, Injectable Boosters, Non-Injection Methods Application: Osteoarthritis Treatment, Joint Lubrication, Pain Management, Athletic Injury Recovery |
| Companies Covered | Sanofi S.A., Anika Therapeutics, Inc., Fidia Farmaceutici S.p.A., Zimmer Biomet Holdings, Inc., Bioventus LLC, Ferring B.V., DePuy Synthes, Seikagaku Corp., Smith & Nephew PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Viscosupplementation Market Shifts & Advancements
Formulation chemistry and regulatory compliance requirements are converging to reshape product development priorities across European viscosupplementation markets. Manufacturers are redirecting R&D investment toward extended-duration technologies while navigating tightened clinical evidence standards.
Cross-linked sodium hyaluronate formulations are consolidating market share among orthopedic clinics seeking reduced injection frequency protocols. German ambulatory surgical centers are adopting these technologies faster than hospital-based departments, driven by operational efficiency targets. The technology is consolidating competitive positioning around residence time performance rather than molecular weight specifications alone.
REACH compliance mandates for hyaluronic acid sourcing are extending supply chain documentation requirements to raw material importers. European formulators are responding by qualifying secondary suppliers and investing in fermentation capacity partnerships. Northern Italian manufacturers with integrated pharmaceutical chemical operations are adapting faster than pure-play device companies.
Direct procurement relationships between orthopedic clinics and manufacturers are displacing traditional wholesale distribution in high-volume markets. Spain's sports medicine centers are negotiating formulary agreements that bundle viscosupplementation with rehabilitation services. This channel evolution is most visible in Germany's fragmented outpatient sector, where purchasing cooperatives are aggregating clinic demand.
Europe Viscosupplementation Market Segmentation
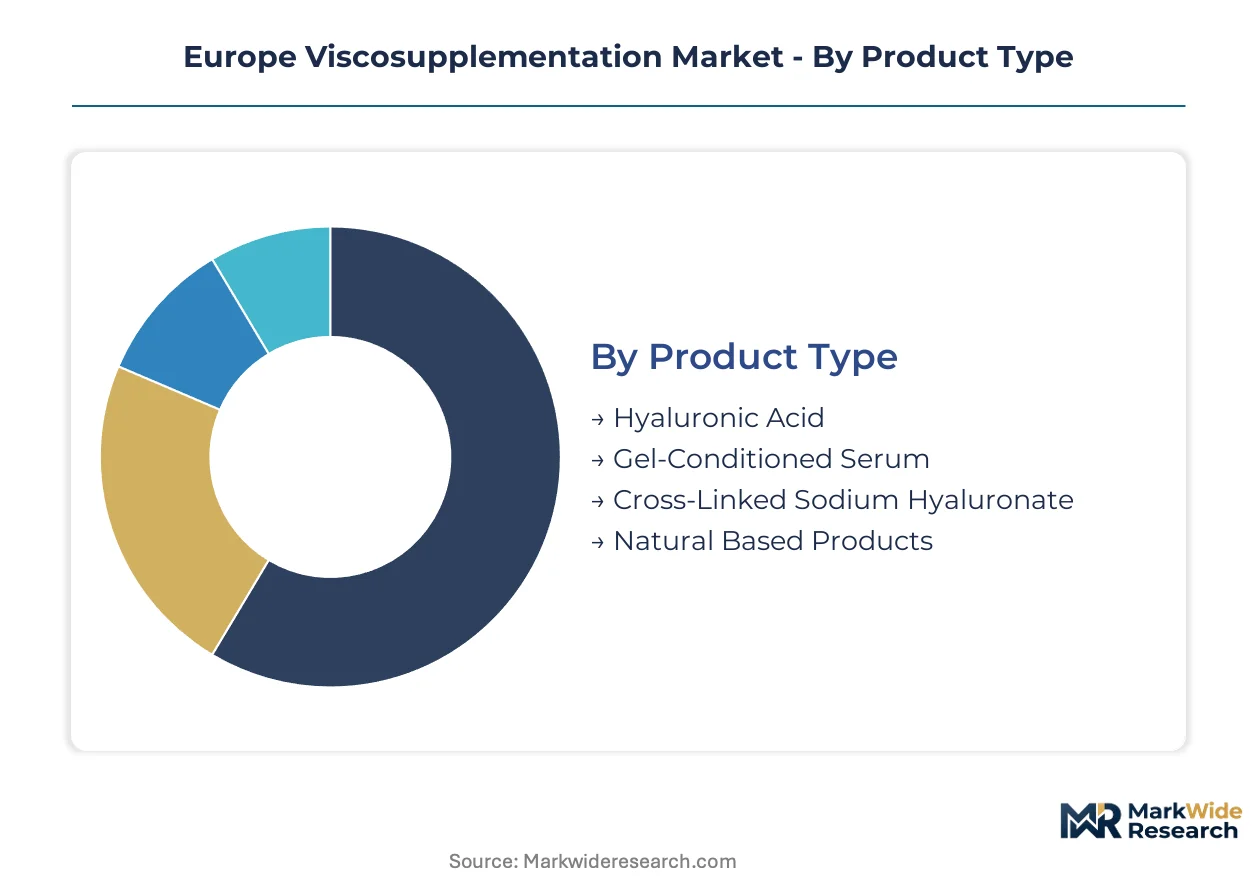
Segmentation in European viscosupplementation reveals distinct demand profiles across formulation chemistry, clinical setting, and therapeutic application. Each dimension carries specific regulatory, reimbursement, and operational constraints that determine commercial viability.
Product Type:
Volume leadership sits with established hyaluronic acid formulations, while premium positioning concentrates around cross-linked technologies with extended residence profiles.
- Hyaluronic Acid:Standard molecular weight formulations between 500 and 6,000 kDa dominate current procedure volumes across Germany and France. Reimbursement familiarity and established CE-marked portfolios sustain hospital formulary placement despite shorter intra-articular residence times.
- Cross-Linked Sodium Hyaluronate:Chemical modification extends joint cavity persistence and reduces injection frequency from weekly to monthly protocols. Spanish sports medicine centers and Italian orthopedic networks are adopting these formulations fastest as operational efficiency metrics reshape procurement criteria.
- Gel-Conditioned Serum:Autologous preparation protocols requiring on-site processing limit scalability to high-volume clinic settings.
- Natural Based Products:Avian and bacterial fermentation sourcing alternatives face REACH documentation burdens that constrain mid-scale manufacturer participation.
Mature deployment sits with hyaluronic acid. Newer deployment is concentrated in cross-linked sodium hyaluronate.
End User:
Procurement authority fragments across institutional purchasing cooperatives, direct manufacturer negotiations, and hospital pharmacy gatekeepers depending on care setting.
- Orthopedic Clinics:Ambulatory surgical centers in Germany's fragmented outpatient sector aggregate demand through purchasing cooperatives that bypass traditional wholesale distribution. France's clinic networks retain tighter hospital affiliation, preserving centralized pharmacy control.
- Sports Medicine Centers:Spain's expanding dedicated facilities negotiate bundled agreements combining viscosupplementation with rehabilitation protocols. Athletic injury recovery applications are climbing the fastest as patient demographics broaden beyond geriatric osteoarthritis populations.
- Rehabilitation Facilities:Post-procedural follow-on injection protocols align with extended-care reimbursement frameworks in Italy and France.
- Home Healthcare:Self-administration constraints and sterile handling requirements limit penetration to specialized nursing networks.
Procurement consolidation is most advanced in orthopedic clinics. Sports medicine centers are gaining share fastest.
Delivery Mode:
Route selection determines regulatory pathway complexity, with intra-articular injection carrying established MDR technical documentation precedents.
- Intra-Articular Injection:Direct synovial cavity administration remains the clinically validated standard with established outcome registries supporting CE-marked claims. German notified bodies process technical documentation for these devices faster than Southern European counterparts.
- Injectable Boosters:Adjunctive formulation protocols designed to prolong primary injection efficacy are gaining traction in high-volume French clinic networks seeking differentiation.
- Intravenous Injection:Systemic administration routes face heavier clinical evidence requirements under MDR post-market surveillance obligations.
- Non-Injection Methods:Topical and oral alternatives occupy marginal positioning pending demonstration of comparable rheological performance.
Established deployment centers on intra-articular injection. Injectable boosters are expanding most quickly.
Application:
Therapeutic indication determines reimbursement tariff positioning and patient eligibility criteria across national health insurance frameworks.
- Osteoarthritis Treatment:Knee joint applications capture the largest procedure volumes with established statutory health insurance coverage in Germany and France. Tariff recalibration decisions by these insurers threaten premium formulation positioning.
- Athletic Injury Recovery:Meniscal and ligament-adjacent applications in younger patient populations are steepest expansion trajectory as Spanish sports medicine infrastructure broadens addressable demand.
- Joint Lubrication:Preventive and maintenance protocols face tighter prior authorization requirements in cost-containment environments.
- Pain Management:Adjunctive analgesic positioning competes with established pharmacological alternatives in formulary negotiations.
Reimbursement maturity sits with osteoarthritis treatment. Athletic injury recovery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-based hyaluronic acid supply from Northeast Asian suppliers anchors European viscosupplementation manufacturing, with finished product demand concentrating in Germany, France, Italy, Spain, and the United Kingdom. National reimbursement frameworks and MDR implementation timelines create divergent market access conditions across these markets.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia drive procedure volumes through purchasing cooperatives that aggregate clinic demand. The Federal Institute for Drugs and Medical Devices (BfArM) processes MDR technical documentation faster than Southern European notified bodies, accelerating product registration timelines. Berlin-Brandenburg hosts regulatory affairs infrastructure serving manufacturers seeking streamlined CE-marking pathways.
France
Hospital formulary placement remains centralized through pharmacy gatekeepers in Île-de-France and Auvergne-Rhône-Alpes, preserving tighter affiliation networks than Germany's fragmented outpatient sector. ANSM oversight enforces clinical evidence standards that shape product registration requirements for cross-linked formulations. Lyon-based orthopedic networks negotiate bundled service agreements combining viscosupplementation with rehabilitation protocols.
Italy
Northern Italy's pharmaceutical production clusters in Lombardy and Piedmont offer underutilized sterile filling capacity for contract manufacturing expansion. Fidia Farmaceutici S.p.A. anchors regional production gravity with concentrated manufacturing facilities. REACH compliance documentation for hyaluronic acid intermediates imposes supply chain burdens that favor established manufacturers with dedicated regulatory teams in Milan-Turin corridor operations.
Spain
Sports medicine infrastructure in Madrid and Catalonia broadens viscosupplementation applications beyond geriatric populations into athletic injury recovery. Regional health authorities recalibrate reimbursement tariffs for knee osteoarthritis treatments, creating pricing pressure on premium formulations. Barcelona-based rehabilitation centers negotiate direct procurement relationships that bypass traditional wholesale distribution channels.
United Kingdom
Post-Brexit regulatory divergence from EU MDR frameworks creates parallel registration requirements through the Medicines and Healthcare products Regulatory Agency (MHRA). London-Southeast orthopedic networks maintain adoption rates for intra-articular injection therapies comparable to continental European benchmarks. Manchester and Birmingham clinic systems face reimbursement constraints from NHS England tariff structures that favor standard hyaluronic acid over cross-linked alternatives.
Europe Viscosupplementation Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and distribution reach, creating a tiered structure where integrated pharmaceutical networks face specialized device manufacturers. The vendor base separates into three archetypes: diversified healthcare conglomerates with orthopedic portfolios, pure-play viscosupplementation specialists, and contract manufacturing organizations serving private-label brands. Dominant competitive moves include M&A activity targeting cross-linking technology capabilities and strategic partnerships securing multi-source hyaluronic acid supply agreements.
Among diversified healthcare conglomerates, Sanofi S.A. and Zimmer Biomet Holdings, Inc. occupy positions spanning pharmaceutical and device market segments. Anika Therapeutics, Inc. exemplifies the specialized device manufacturer archetype with concentrated focus on hyaluronic acid-based therapies. Fidia Farmaceutici S.p.A. anchors the regional European manufacturer tier with Italy-based production infrastructure. These three company types represent distinct strategic positioning around regulatory affairs scale, R&D specialization depth, and geographic production concentration.
| Leading Market Players |
|---|
| Sanofi S.A. |
| Anika Therapeutics, Inc. |
| Fidia Farmaceutici S.p.A. |
| Zimmer Biomet Holdings, Inc. |
| Bioventus LLC |
| Ferring B.V. |
| DePuy Synthes |
| Seikagaku Corp. |
| Smith & Nephew PLC |
| Others |
Supply & Pricing Matrix
Cross-linking chemistry specialists concentrated in Northern Italy's pharmaceutical corridor create labor-cost differentials that widen pricing-tier spreads between standard hyaluronic acid formulations and extended-residence premium products. REACH compliance documentation burdens for hyaluronic acid intermediates compound these cost structures, favoring established manufacturers with dedicated regulatory affairs teams over smaller formulators competing on price.
Pricing Analysis
Warranty and post-injection monitoring services are unbundled from product pricing in German ambulatory surgical centers, while French hospital networks bundle formulary placement with outcome guarantees. Three-tier pricing structure across premium cross-linked formulations, standard molecular weight hyaluronic acid, and economy unbranded alternatives dominates procurement negotiations. Cost compression in the standard tier intensifies as statutory health insurers in France and Germany recalibrate reimbursement tariffs. Orthopedic clinic purchasing cooperatives exhibit highest price sensitivity, while sports medicine centers prioritize residence-time performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by European formulators now extend to fermentation-based hyaluronic acid suppliers in China, South Korea, and Japan. Raw material dependencies center on bacterial fermentation capacity, sterile filling infrastructure, and cross-linking reagent supply. Single-source vulnerability persists for specialized high-molecular-weight intermediates despite multi-source frameworks for standard grades. Distribution runs through direct procurement relationships between orthopedic clinics and manufacturers in Germany, displacing traditional wholesale channels in high-volume markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over hyaluronic acid fermentation capacity and cross-linking chemistry expertise determines margin sustainability. Players are pursuing upstream raw material security as the decisive competitive lever.
For Market Incumbents: Lock in multi-year supply agreements with Northeast Asian fermentation suppliers before REACH documentation requirements tighten further. Secure dedicated sterile filling capacity in Northern Italy's underutilized pharmaceutical clusters to defend against contract manufacturing entrants. MDR compliance infrastructure represents a sunk-cost barrier that emerging players cannot easily replicate. For New Entrants and Emerging Players: Spain's sports medicine centers represent an underserved buyer archetype with faster procurement cycles and lower formulary entry barriers than German hospital networks. Target bundled service agreements combining viscosupplementation with rehabilitation protocols to differentiate from product-only incumbents. Direct-to-clinic distribution partnerships bypass entrenched wholesale relationships in the fragmented German outpatient sector. For Investors and Strategic Acquirers: Re-rating potential sits with specialized cross-linking technology developers given EMA's extended residence time preference in forthcoming MDR guidance. Long-term viability hinges on formulation stability expertise rather than commodity hyaluronic acid sourcing. Monitor ANSM tariff recalibration decisions as the inflection signal for premium formulation margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical documentation acceleration through German notified bodies shortens time-to-revenue for cross-linked formulations. |
| Backward Integration into Fermentation | Captive hyaluronic acid supply insulates margin structures from REACH-driven documentation cost inflation. |
| Hospital System Partnership | Direct formulary agreements with Lyon and Paris orthopedic networks secure volume commitments against reimbursement compression. |
| Software Companion Development | Injection protocol apps bundled with cross-linked products improve compliance metrics for sports medicine center procurement. |
| Reimbursement Strategy | Single-injection protocol evidence generation aligns with German statutory health insurer cost-containment objectives. |
Research Methodology
Document review covered EMA MDR guidance documents, REACH substance registration databases, and national health insurance tariff schedules, complemented by interviews with regulatory affairs directors at viscosupplementation manufacturers, orthopedic clinic procurement managers in Germany and France, and hyaluronic acid raw material suppliers. Primary fieldwork included discussions with notified body auditors and hospital pharmacy gatekeepers. Secondary validation drew from BfArM device registration records, ANSM market surveillance reports, and purchasing cooperative contract disclosures. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Segmented projections across formulation chemistry, clinical setting, and therapeutic application generated volume and value trajectories over the projection horizon. Modeled dimensions included molecular weight tier, cross-linking density, end-user facility type, and national reimbursement framework. CAGRs derived from regression analysis of historical procedure growth rates adjusted for MDR implementation phase-ins and payer policy shifts. Forecast inputs incorporated REACH compliance cost pass-through assumptions and sports medicine infrastructure build-out timelines.
Revisions become necessary when EMA issues revised MDR clinical evidence guidance, when statutory health insurers finalize tariff recalibrations, or when REACH substance restrictions alter hyaluronic acid sourcing economics. Deviation in cross-linked formulation reimbursement positioning would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Heart Valve Devices Market
Medical Devices
Laryngeal Airway Mask Market
Medical Devices
Micro Syringes Market
Medical Devices
Ovulation Microscope Market
Medical Devices
GCC Implantable Medical Devices Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Europe C-Arms Market
Medical Devices
Breast Lesion Localization Device Market
Medical Devices
Electrocautery Devices Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Global Assistive Listening Device Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Absorbable Nasal Implant Market