
 Medical Hydrophilic Coatings Market | 2026-2036
Medical Hydrophilic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Hydrophilic Coatings Market Analysis
Catheter applications are rebalancing the end-use mix toward minimally invasive cardiovascular and urological interventions. Surmodics Inc. leverages its surface modification expertise to anchor North American supply relationships with major catheter OEMs. Hydromer Inc. competes through polymer chemistry specialization in custom coating formulations for device manufacturers. DSM-Firmenich sustains European market presence with pharmaceutical-grade polymer portfolios that extend into coating adjacencies.
Medical hydrophilic coatings comprise water-attracting polymer layers, typically polyvinylpyrrolidone or polyethylene glycol formulations applied at 1-50 micron thicknesses, that reduce friction coefficients below 0.05 when hydrated. These coatings enable smooth device insertion through biological tissues while maintaining structural integrity during procedure duration. Multi-component systems command premium positioning due to tailored adhesion and lubrication stratification. Nano-coatings represent the fastest-expanding technology segment as device miniaturization demands molecular-level surface precision. Catheter applications dominate volume consumption while surgical instruments concentrate margin pools through specialized antimicrobial-lubricious hybrid formulations.
The FDA enforces biocompatibility standards under ISO 10993 frameworks that govern cytotoxicity and sensitization testing for all blood-contacting coatings. The EU MDR requires enhanced clinical evidence for permanently implanted coated devices, extending certification timelines for manufacturers serving European hospitals. Japan's PMDA maintains distinct polymer purity specifications that create separate qualification pathways for coating suppliers. Stakeholders must monitor evolving harmonization tensions between FDA breakthrough device pathways and EU MDR clinical data requirements when prioritizing geographic registration investments.
Market Dynamics
FDA biocompatibility protocol updates are compressing product development timelines while catheter OEMs accelerate procurement of lubricious coatings to minimize tissue trauma in minimally invasive procedures. This regulatory-demand convergence is restructuring competitive positioning across coating chemistry tiers.
Growth Catalysts
- ISO 10993 cytotoxicity frameworks:Harmonized biocompatibility standards reduce redundant testing burdens for coating suppliers seeking multi-market registration.
- Catheter OEM procurement expansion:Cardiovascular and urological device manufacturers are increasing coating specifications to differentiate minimally invasive portfolios.
- Baden-Württemberg precision clusters:German medical device manufacturing concentration anchors European coating innovation and supplier qualification pathways.
Market Restraints
- Polymer feedstock volatility:Polyvinylpyrrolidone and polyethylene glycol input costs fluctuate with specialty chemical supply chains concentrated in Asia-Pacific.
- EU MDR clinical evidence requirements:Enhanced documentation mandates for permanently implanted coated devices extend certification timelines by 18-24 months.
- Silicone-based substitution:Alternative low-friction surface technologies threaten pricing power in surgical instrument applications.
Strategic Opportunities
- Japan PMDA polymer purity pathways:Distinct qualification requirements create first-mover advantages for suppliers investing in dedicated Japanese regulatory infrastructure.
- Antimicrobial-lubricious hybrid formulations:Surgical instrument manufacturers seek dual-function coatings combining infection control with friction reduction.
- Nano-coating molecular precision:Device miniaturization trends favor sub-micron surface engineering capabilities for neurovascular and ophthalmic applications.
Industry Challenges
- Cross-functional polymer chemist scarcity:Coating formulation expertise combining biocompatibility knowledge with process engineering remains concentrated among senior specialists at established suppliers.
- Multi-jurisdiction certification synchronization:Divergent FDA breakthrough device pathways and EU MDR clinical data requirements complicate geographic prioritization decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Hydrophilic Coatings Market |
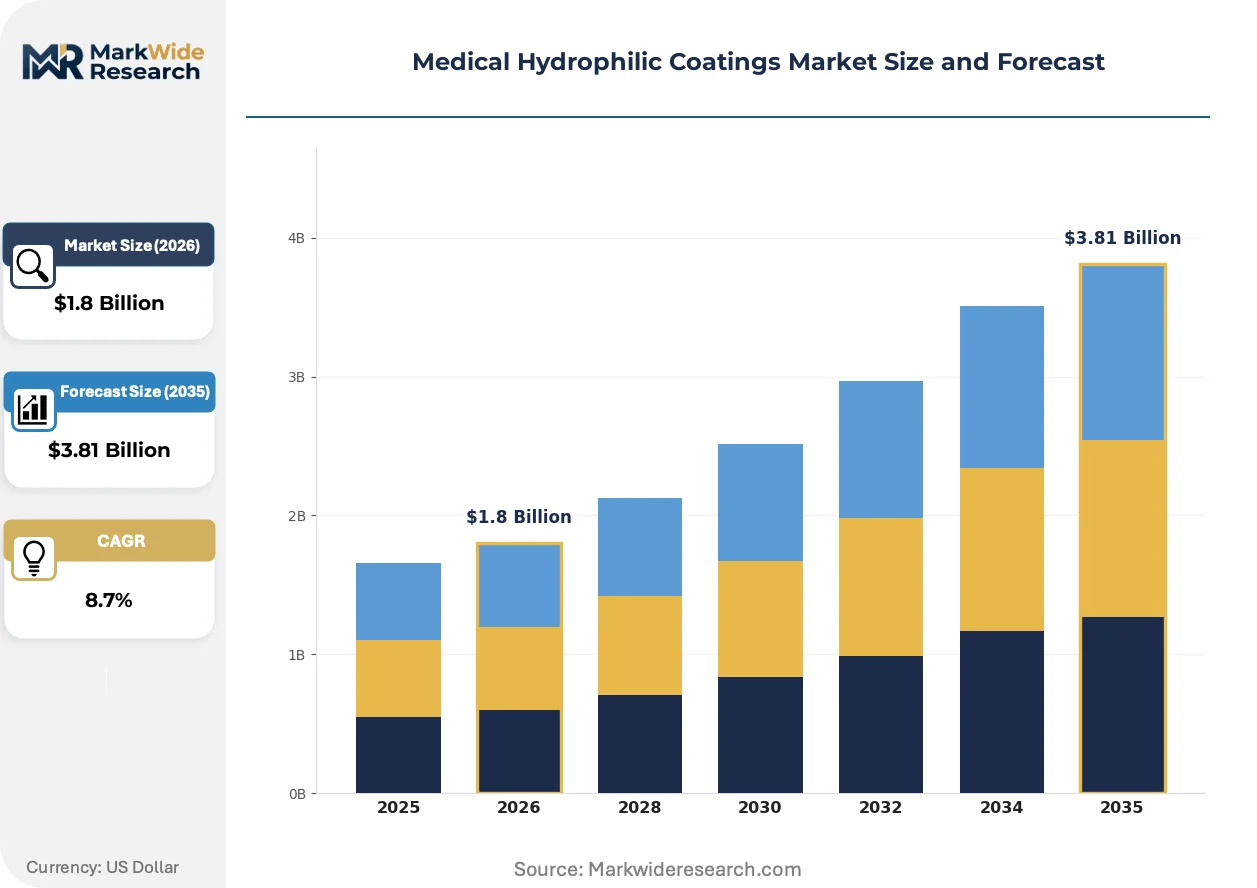
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Component, Multi-Component, Spray Coatings, Liquid Coatings End User: Hospitals, Clinics, Laboratories, Medical Device Manufacturers Application: Drug Delivery, Catheters, Surgical Instruments, Diagnostic Devices Technology: Polymer Coating, Surface Modification, Self-Assembling Monolayers, Nano-coatings |
| Companies Covered | Surmodics Inc., Hydromer Inc., Biocoat Incorporated, DSM-Firmenich, AST Products Inc., Harland Medical Systems Inc., Surface Solutions Group LLC, Applied Medical Coatings LLC, Specialty Coating Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Hydrophilic Coatings Market Emerging Trajectories
Coating technology is fragmenting into application-specific architectures as device manufacturers reject one-size-fits-all surface solutions. Regulatory convergence pressures and miniaturization demands are simultaneously pulling innovation toward molecular precision and modular system design.
Multi-component coating architectures are modularizing around stratified adhesion and lubrication layers tailored to specific tissue contact durations. Catheter OEMs are specifying these systems for cardiovascular interventions requiring both immediate insertion smoothness and prolonged structural integrity. This modularization is compressing single-polymer coating margins while expanding service revenue for formulation customization.
The EU MDR enhanced clinical evidence mandate is restructuring development economics for permanently implanted coated devices. Manufacturers serving European hospitals must now generate longitudinal safety data previously unnecessary under legacy directives. Cardiac implant coating suppliers are responding by front-loading clinical trial investments to secure notified body approvals ahead of competitor submissions.
Hospital procurement teams are consolidating coating specification authority previously dispersed across device engineering and infection control departments. Centralized value analysis committees now evaluate total cost of ownership including thrombosis rates and retrieval complication frequencies. This concentration is visible most acutely in German university hospital networks where standardized coating qualification scorecards are displacing brand-specific preferences.
Medical Hydrophilic Coatings Market Segmentation
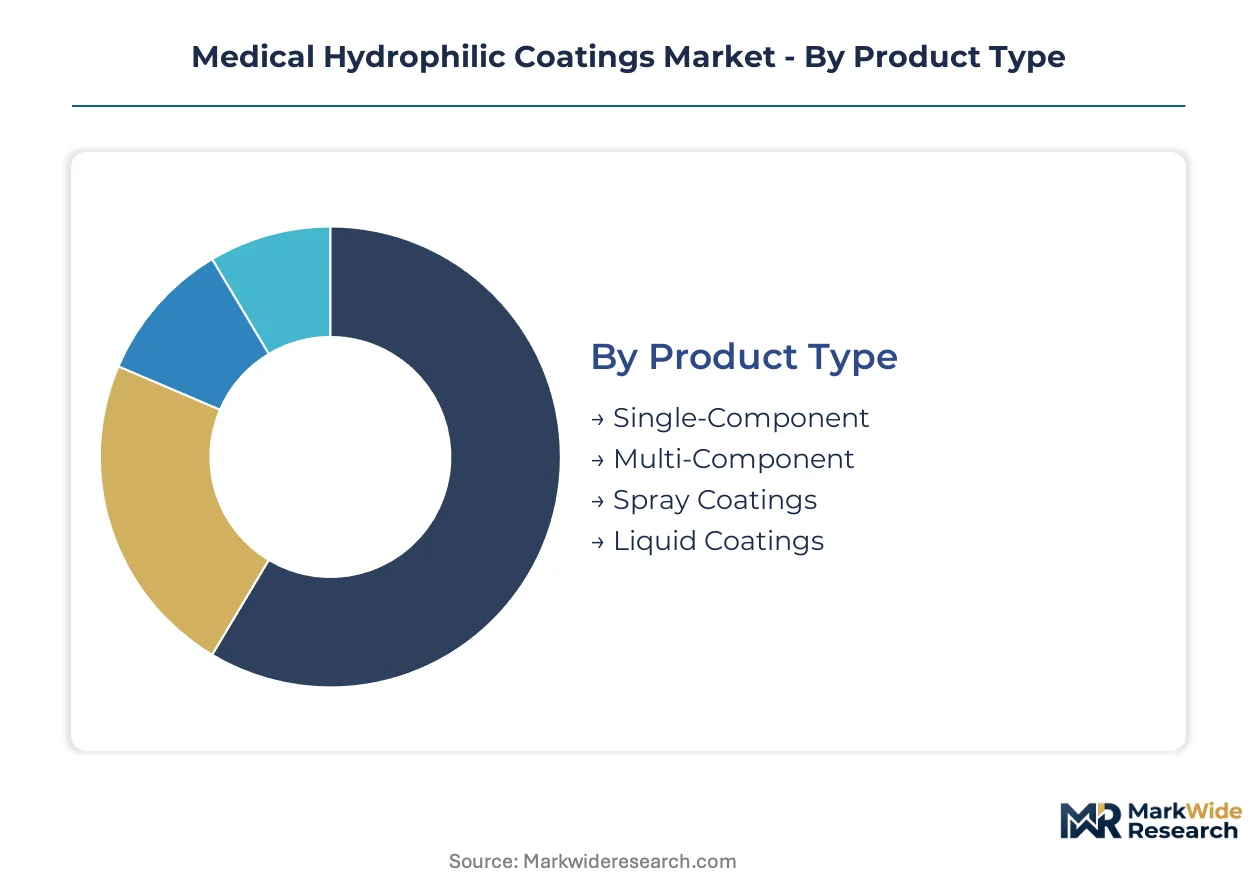
Segmentation in medical hydrophilic coatings reveals how capital intensity, regulatory pathways, and application-specific performance requirements stratify supplier economics. Understanding these divisions exposes where formulation expertise concentrates and where procurement leverage shifts.
Product Type:
Capital requirements vary sharply across coating architectures, with multi-layer systems demanding substantially higher upfront investment in precision deposition equipment and cleanroom infrastructure.
- Multi-Component:Stratified adhesion and lubrication layers enable tailored performance for cardiovascular catheters requiring both immediate insertion smoothness and prolonged structural integrity. German precision device clusters in Baden-Württemberg anchor demand for these premium systems. Surmodics Inc. leverages surface modification expertise to supply major catheter OEMs with these architectures.
- Nano-coatings:Sub-micron surface engineering addresses device miniaturization trends in neurovascular and ophthalmic applications where molecular-level precision governs performance. Japan's PMDA maintains distinct polymer purity specifications that create separate qualification pathways for these advanced formulations.
- Single-Component:Homogeneous polymer layers, typically polyvinylpyrrolidone or polyethylene glycol formulations, serve cost-sensitive surgical instruments and diagnostic devices.
- Spray Coatings:Aerosolized application methods suit high-volume catheter manufacturing lines requiring rapid throughput.
- Liquid Coatings:Dip-coating and flow-coating processes dominate medical device manufacturer in-house finishing operations.
Multi-Component coatings absorb the bulk of installed capacity; Nano-coatings are expanding most quickly.
End User:
Procurement authority concentration differs markedly across customer types, with medical device manufacturers wielding specification power while hospitals exercise growing total-cost-of-ownership scrutiny.
- Medical Device Manufacturers:Catheter OEMs and surgical instrument producers drive volume demand through embedded coating specifications in minimally invasive portfolios. Cardiovascular and urological device manufacturers anchor North American and European coating procurement.
- Hospitals:German university hospital networks deploy standardized coating qualification scorecards that displace brand-specific preferences, centralizing value analysis committee authority.
- Clinics:Outpatient surgical centers prioritize pre-coated disposable instruments to minimize reprocessing infrastructure.
- Laboratories:Diagnostic equipment producers specify hydrophilic surfaces for microfluidic channels and sample handling components.
Medical Device Manufacturers command the dominant procurement volume; Hospitals are gaining specification influence fastest.
Application:
Clinical performance requirements and regulatory classification intensity fragment demand across use cases, with permanent implants facing distinct evidence burdens from transient devices.
- Catheters:Cardiovascular and urological interventions dominate volume consumption, with lubricious coatings reducing tissue trauma during minimally invasive procedures. FDA biocompatibility protocols under ISO 10993 frameworks govern cytotoxicity testing for these blood-contacting applications.
- Surgical Instruments:Antimicrobial-lubricious hybrid formulations command margin premiums by combining infection control with friction reduction. Specialized coatings here face substitution pressure from silicone-based alternatives.
- Drug Delivery:Coated stents and implantable pumps require controlled release kinetics that extend development timelines under EU MDR enhanced clinical evidence mandates.
- Diagnostic Devices:Hydrophilic surfaces enable fluid transport in point-of-care testing equipment and imaging catheter assemblies.
Catheters anchor installed production capacity; Surgical Instruments concentrate margin pools through hybrid formulation premiums.
Technology:
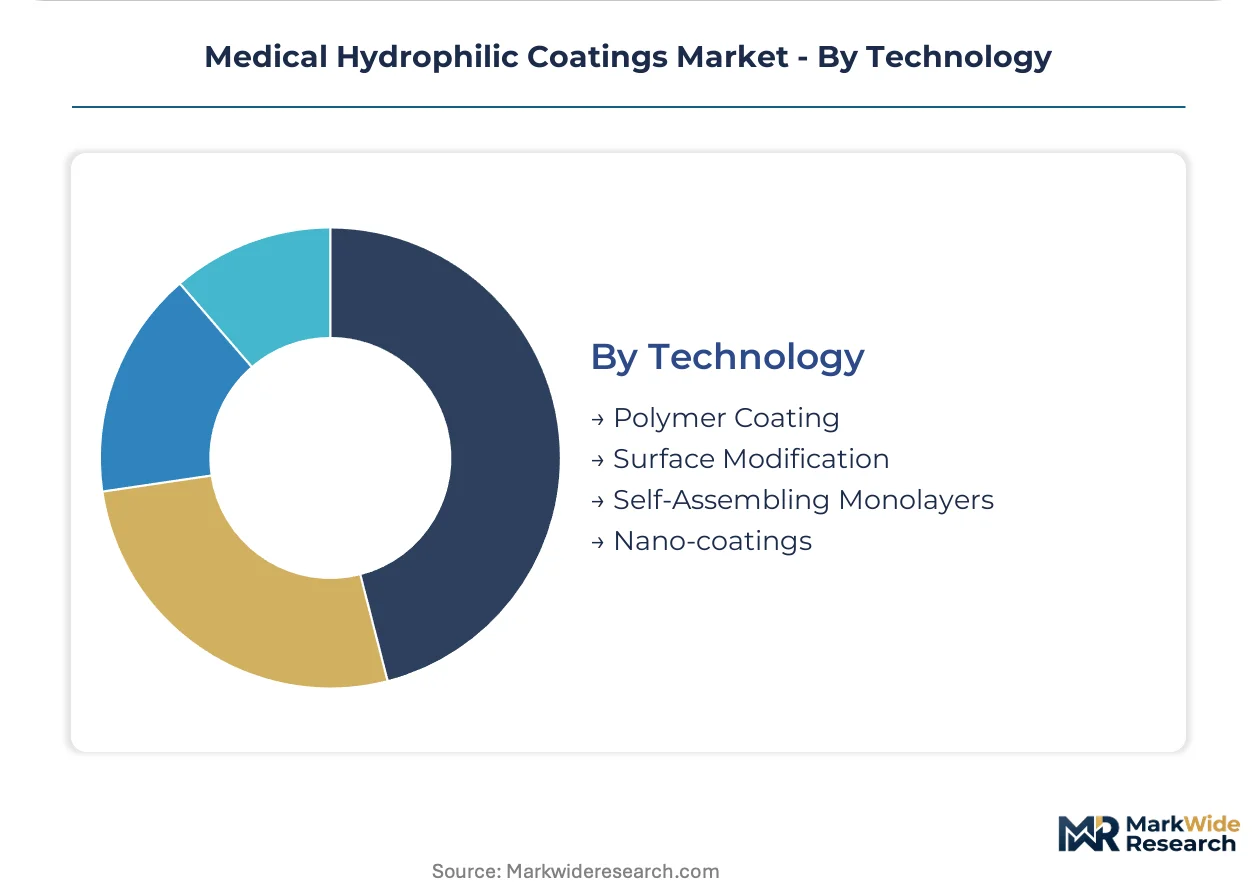
Technical sophistication and patent estate thickness determine competitive moats across coating methodologies, with nano-scale approaches requiring specialized equipment investments.
- Polymer Coating:Polyvinylpyrrolidone and polyethylene glycol formulations at 1-50 micron thicknesses reduce friction coefficients below 0.05 when hydrated. DSM-Firmenich sustains European market presence with pharmaceutical-grade polymer portfolios.
- Surface Modification:Covalent bonding and plasma treatment approaches create durable lubricious layers for devices requiring extended tissue contact duration.
- Self-Assembling Monolayers:Molecular-level ordering enables precise control over surface energy and biocompatibility characteristics.
- Nano-coatings:Molecular-level surface precision addresses device miniaturization demands in neurovascular and ophthalmic segments.
Polymer Coating retains the largest installed base; Nano-coatings show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision medical device clusters anchor European coating innovation through tax-advantaged manufacturing zones. The United States, Germany, Japan, China, and Switzerland concentrate regulatory infrastructure and specialized polymer chemistry capabilities.
United States
Catheter OEMs in Minnesota and Massachusetts drive procurement volume for lubricious coatings. FDA biocompatibility protocols under ISO 10993 frameworks govern cytotoxicity testing for blood-contacting applications. Surmodics Inc. leverages surface modification expertise to supply major cardiovascular device manufacturers from its Minnesota base.
Germany
Precision device clusters in Baden-Württemberg and Bavaria anchor European demand for multi-component coating architectures. EU MDR enhanced clinical evidence mandates extend certification timelines for permanently implanted coated devices. Stuttgart-based medical technology manufacturers specify tailored adhesion and lubrication stratification for minimally invasive portfolios.
Japan
Neurovascular and ophthalmic device miniaturization demands molecular-level surface precision from Tokyo and Osaka manufacturers. PMDA maintains distinct polymer purity specifications that create separate qualification pathways for nano-coating suppliers. Nagoya's precision engineering corridor concentrates coating formulation expertise for sub-micron applications.
China
Domestic catheter manufacturers in Shanghai and Suzhou expand coating specifications to differentiate minimally invasive portfolios. NMPA biocompatibility standards align with international frameworks while maintaining separate polymer registration requirements. Yangtze River Delta medical device parks attract coating suppliers through specialized economic zone incentives.
Switzerland
Pharmaceutical-grade polymer portfolios extend into coating adjacencies from Basel and Zurich chemical clusters. Swissmedic maintains stringent purity specifications for permanently implanted coated devices. The country's precision manufacturing heritage supports specialized formulation capabilities for hybrid antimicrobial-lubricious systems.
Medical Hydrophilic Coatings Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise concentrating among established suppliers possessing integrated polymer chemistry and process engineering capabilities. The vendor base organizes around three strategic archetypes: surface modification specialists, polymer chemistry pure-plays, and diversified chemical conglomerates with pharmaceutical-grade portfolios. M&A activity targets niche formulation capabilities, while capacity expansion focuses on cleanroom infrastructure for nano-coating deposition.
Within the surface modification specialist tier, Surmodics Inc. and Hydromer Inc. exemplify distinct competitive positioning approaches. Surmodics Inc. occupies a position anchored in North American catheter OEM relationships, while Hydromer Inc. represents polymer chemistry specialization in custom coating formulations. DSM-Firmenich sits within the diversified chemical conglomerate archetype, leveraging pharmaceutical-grade polymer portfolios that extend into coating adjacencies from its European base.
| Leading Market Players |
|---|
| Surmodics Inc. |
| Hydromer Inc. |
| Biocoat Incorporated |
| DSM-Firmenich |
| AST Products Inc. |
| Harland Medical Systems Inc. |
| Surface Solutions Group LLC |
| Applied Medical Coatings LLC |
| Specialty Coating Systems Inc. |
| Others |
Supply Flow & Price Mechanics
Nano-coating deposition equipment upgrades are simultaneously elevating capital barriers for new entrants and compressing margins for legacy single-polymer suppliers. This technology transition concentrates pricing power among German and Swiss precision manufacturers while forcing Asian commodity producers toward volume-driven contract structures.
Pricing Analysis
Short lead-time premiums of 15-25% apply to nano-coating formulations for neurovascular devices, while spot inventory of standard polyvinylpyrrolidone coatings trades at contracted discounts. Three-tier pricing structure across premium, standard, and economy levels separates multi-component cardiovascular architectures from single-polymer surgical instruments and bulk diagnostic coatings. Price differentiation hinges on ISO 10993 biocompatibility certification tiers and cleanroom manufacturing infrastructure. Cost compression in standard-grade coatings is intensifying because Chinese catheter manufacturers are backward-integrating into in-house finishing operations. Hospital procurement committees demonstrate highest price sensitivity through total-cost-of-ownership scorecards, while cardiac implant OEMs prioritize performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German specialty chemical houses for pharmaceutical-grade polyethylene glycol precursors. Raw material concentration centers on China for polyvinylpyrrolidone monomers, Germany for precision polymer synthesis, and Switzerland for ultra-pure coating additives. Feedstock dependencies include ethylene oxide derivatives, N-vinylpyrrolidone monomers, and platinum-group catalysts for surface modification chemistry. Tariff exposure threatens margin stability as EU-China chemical trade frictions escalate over polymer registration reciprocity. Distribution runs through medical device OEM direct procurement teams, hospital GPO contracts, and specialized coating applicator networks serving mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR certification timeline extensions are accelerating consolidation among coating suppliers lacking clinical trial infrastructure. Smaller European players face existential pressure as notified body backlogs favor capitalized incumbents with dedicated regulatory affairs teams.
For Market Incumbents: Anchor market position through captive supply of polymer precursors and dedicated Japanese PMDA qualification pathways. Surmodics Inc. and DSM-Firmenich demonstrate how backward integration into pharmaceutical-grade raw materials defends margin structures against Asian commodity entrants. Capacity addition in Baden-Württemberg cleanroom clusters addresses nano-coating demand from neurovascular device miniaturization.
For New Entrants and Emerging Players: Launch via contract coating services for mid-tier Chinese catheter manufacturers seeking European market access without in-house formulation expertise. White-space opportunity concentrates in antimicrobial-lubricious hybrid formulations for surgical instruments, where silicone substitution threats have suppressed incumbent R&D investment. Target Japanese ophthalmic device manufacturers through PMDA polymer purity compliance as a differentiated entry angle.
For Investors and Strategic Acquirers: Re-rating potential sits with nano-coating specialists given device miniaturization catalysts across neurovascular and ophthalmic segments. Long-term viability favors acquisition targets possessing integrated polymer chemistry and cleanroom deposition capabilities rather than pure formulation IP. The signal to watch is FDA breakthrough device designation velocity for coated implants, indicating which suppliers have secured preferred OEM relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Front-loaded trial spending secures notified body approval ahead of competitor submissions. |
| Japan PMDA Polymer Purity Qualification | Dedicated regulatory infrastructure creates first-mover advantage in nano-coating segments. |
| Antimicrobial-Lubricious Hybrid Development | Dual-function coatings address surgical instrument procurement committee infection control priorities. |
| Backward Integration into Pharmaceutical-Grade Polymers | Captive supply of polyethylene glycol precursors defends margin against feedstock volatility. |
| Hospital GPO Contract Consolidation | Centralized value analysis committee relationships displace brand-specific preferences in German networks. |
Methodological Framework
Independent corroboration across primary interviews with catheter OEM procurement directors, biomedical engineers at German university hospitals, coating formulation chemists, and GPO contracts managers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR notified body submission databases, ISO 10993 biocompatibility test registries, and pharmaceutical-grade polymer import records. Bottom-up demand modeling triangulates against top-down industry association capacity estimates.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window. Segmentation dimensions include coating architecture tier, end-use application intensity, regulatory certification pathway, and regional manufacturing cluster. CAGRs derive from installed capacity utilization rates, OEM procurement pipeline visibility, and polymer feedstock cost trajectory modeling. Forecast inputs incorporate catheter procedure volume projections and EU MDR implementation pace assumptions.
The model assumes a particular technology adoption path; alternative pathways for self-assembling monolayer surface modification would alter the outlook. Forecasts reflect assumptions about regulatory harmonization progress and polymer purity standard convergence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
Diode Laser Aesthetic Medical Device Market
Medical Devices
Powered Wheelchair Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
China Intrauterine Devices Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Artificial Pancreas Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Asia-Pacific Surgical Visualization Products Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
3D Printed Implants Market