
 Mexico Contraceptive Devices Market | 2026-2036
Mexico Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Contraceptive Devices Market Foresight
Younger, unmarried women are unwinding the historical dominance of married-couple purchasing patterns in Mexico's contraceptive landscape. Bayer AG leverages its hormonal IUD portfolio to anchor hospital procurement contracts across central Mexico. CooperSurgical sustains competitive pressure through specialized intrauterine device manufacturing scale and gynecological training programs for clinic staff.
Contraceptive devices encompass barrier, hormonal, and long-acting reversible technologies engineered from medical-grade silicone, copper alloys, or synthetic progestin matrices to prevent pregnancy through mechanical obstruction or sustained hormone release. The product type dimension shows IUDs and implants capturing margin pools as clinics shift from episodic pill dispensing toward multi-year insertion protocols, while condoms remain a mature, price-sensitive category with pharmacy-heavy distribution. The distribution channel structure tilts toward hospitals and clinics for device insertion, though online retail is expanding for condom and emergency contraception access.
COFEPRIS, Mexico's national health regulator, classifies IUDs and implants as Class II medical devices requiring biocompatibility testing and manufacturing facility inspections, while the Secretaría de Salud shapes demand through public sector tendering and family planning program subsidies. The General Health Law and Norma Oficial Mexicana standards further govern product labeling, sterility assurance, and post-market surveillance obligations. Stakeholders must monitor whether pending regulatory harmonization with U.S. FDA quality systems will reshape import pathways for multinational suppliers.
Market Dynamics
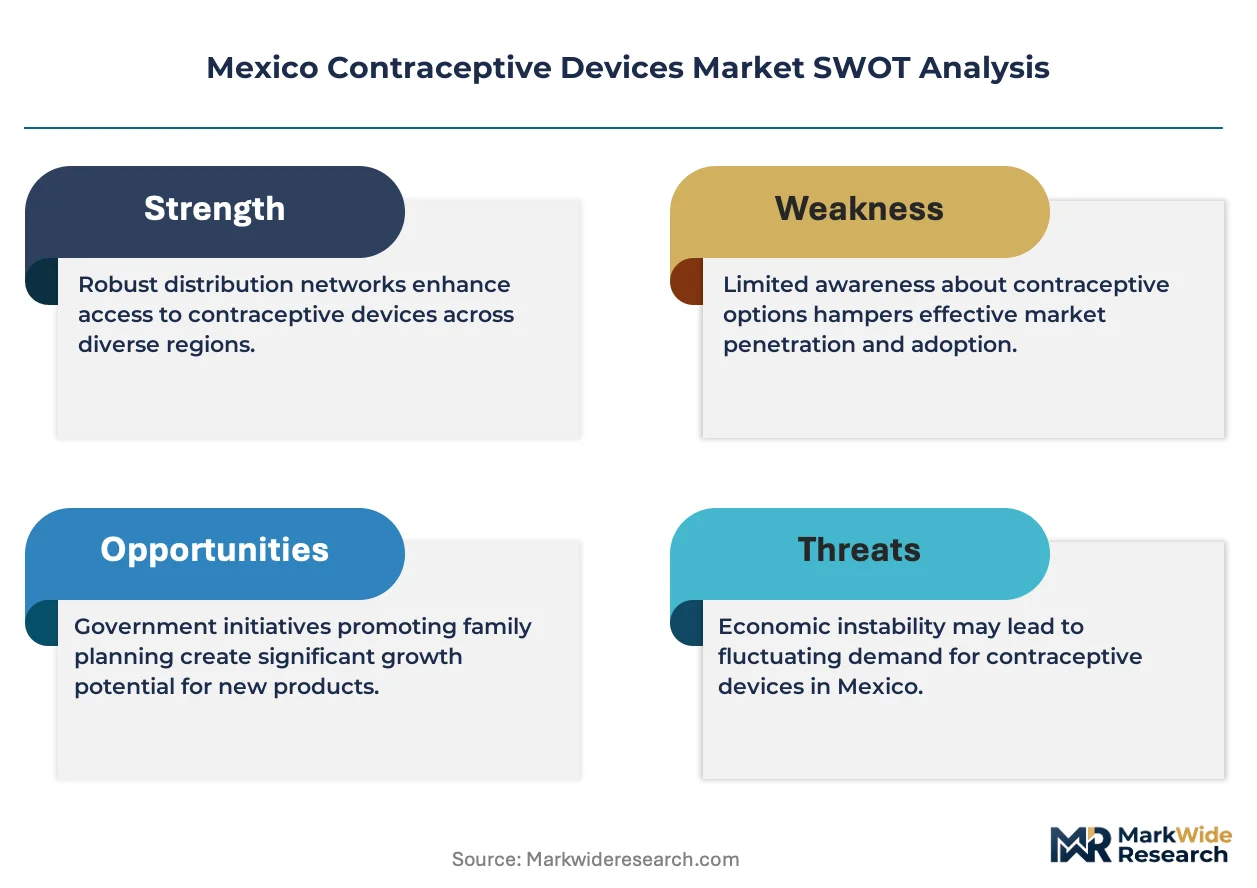
COFEPRIS biocompatibility testing mandates are compressing supplier margins while accelerating migration toward medical-grade silicone and hormone-eluting polymer formulations across Mexico's device manufacturing base.
Growth Catalysts
- Secretaría de Salud tender expansion:Federal procurement protocols now prioritize multi-year insertion devices over episodic contraceptive dispensing, channeling volume toward IUD and implant categories.
- Estado de México clinic density:Urban corridor concentration of public health facilities creates localized demand clusters that manufacturers target with specialized distribution infrastructure.
- Copper alloy IUD technology:Non-hormonal mechanical devices gain preference among patient segments seeking to avoid systemic hormone exposure, expanding addressable populations.
Market Restraints
- Medical-grade silicone cost volatility:Petrochemical feedstock fluctuations compress margin pools for domestic device fabricators dependent on imported elastomer supplies.
- COFEPRIS facility inspection backlog:Manufacturing site certification queues extend 14-18 months, freezing capacity expansion timelines for emerging suppliers.
- Oral contraceptive substitution:Pill formulations retain pharmacy channel dominance through lower upfront costs and familiar prescribing patterns among general practitioners.
Strategic Opportunities
- Guadalajara-Monterrey corridor penetration:Secondary metropolitan zones outside Mexico City show 40% lower device insertion rates per capita, representing expansion white space.
- Telemedicine-enabled prescription pathways:Remote consultation platforms bypass traditional clinic gatekeepers for emergency contraception access, opening direct-to-consumer channels.
- Norma Oficial Mexicana harmonization:Pending alignment with FDA quality systems would streamline import pathways for multinational suppliers holding dual certifications.
Industry Challenges
- Gynecological insertion training scarcity:Public sector clinic staff require supervised procedure hours that outstrip available specialist preceptor capacity.
- Post-market surveillance infrastructure:Adverse event reporting systems lack real-time integration between hospital networks and COFEPRIS pharmacovigilance databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Contraceptive Devices Market |
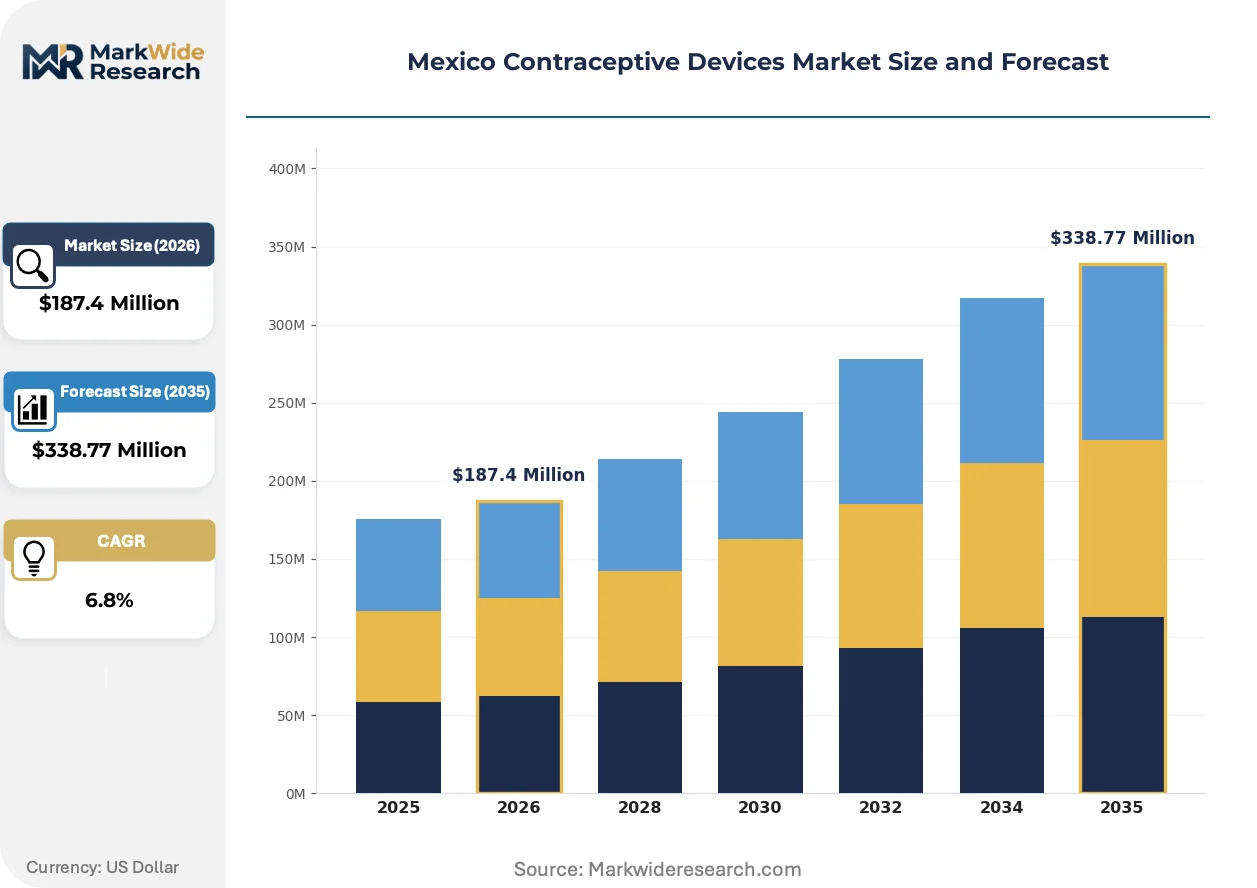
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condoms, IUDs, Pills, Implants Distribution Channel: Pharmacies, Hospitals, Online Retail, Clinics End User: Married Women, Adolescents, Healthcare Providers, Couples Application: Family Planning, Emergency Contraception, Sexual Health, Reproductive Rights |
| Companies Covered | Bayer AG, CooperSurgical, Reckitt Benckiser Group PLC, Pfizer, Church & Dwight, Allergan PLC, Pregna International Limited, Organon & Co., Teva Pharmaceutical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Contraceptive Devices Market Shifts & Advancements
Device formulation sophistication and patient autonomy preferences are restructuring competitive advantage around material science capabilities and digital access channels rather than traditional pharmaceutical marketing.
Hormone-eluting polymer matrices is bifurcating the implant category between sustained-release levonorgestrel systems and next-generation bioresorbable alternatives. Public sector tenders in Mexico City favor established polymer platforms with five-year efficacy data, while private clinic networks pilot biodegradable formulations eliminating removal procedures. This technology is bifurcating procurement criteria between cost-per-protected-year metrics and total lifecycle convenience premiums.
COFEPRIS Class II medical device reclassification tightens biocompatibility testing protocols for silicone-based intrauterine systems. Manufacturers face expanded cytotoxicity and sensitization documentation requirements that extend pre-market submission timelines. Subdermal implant suppliers absorb the heaviest compliance burden, redirecting R&D resources toward polymer characterization laboratories.
Younger unmarried women bypass traditional couple-centered purchasing patterns through independent clinic consultations and direct pharmacy access. This demographic shift fragments historical household decision-making units, forcing manufacturers to retool messaging toward individual autonomy frames. The behavioral pivot concentrates in Mexico City metropolitan zone facilities serving university and early-career professional populations.
Mexico Contraceptive Devices Market Segmentation
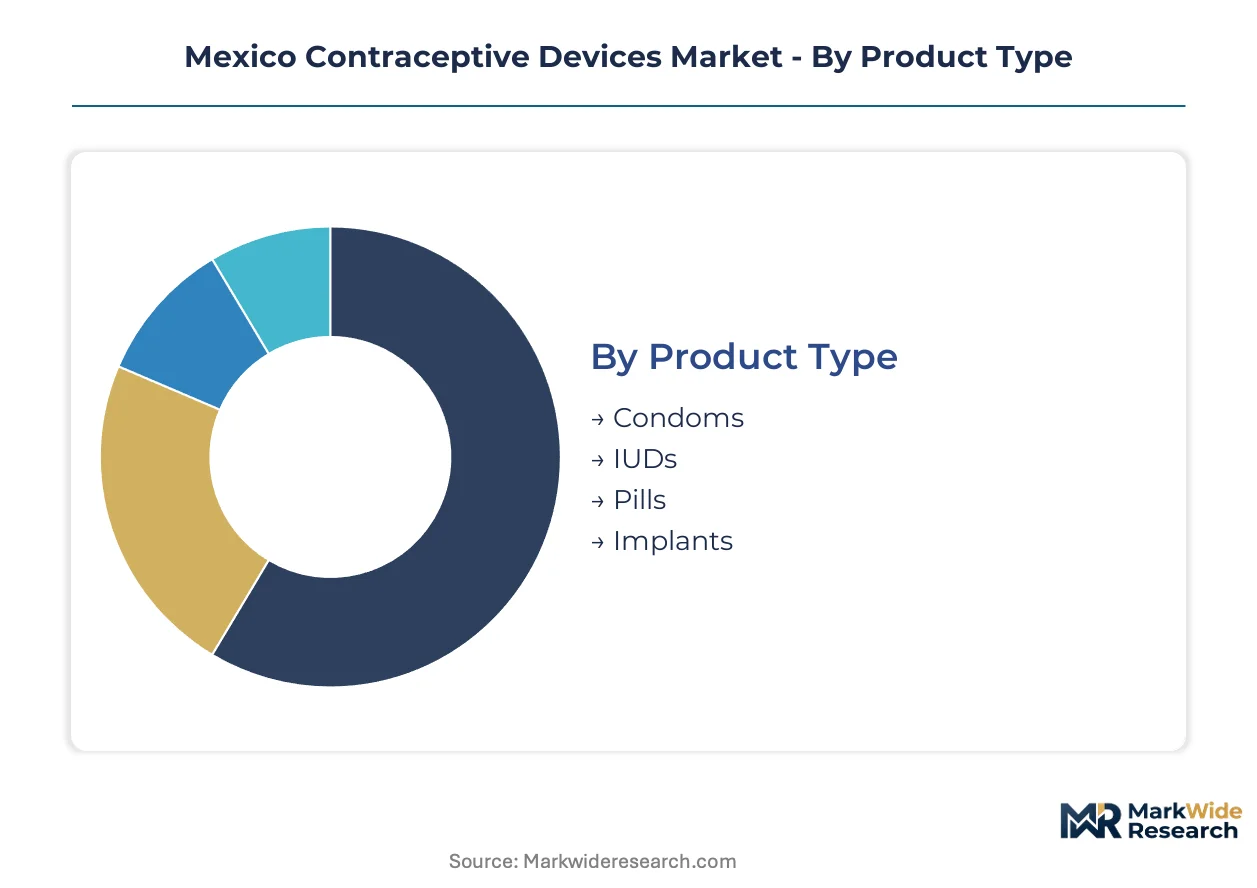
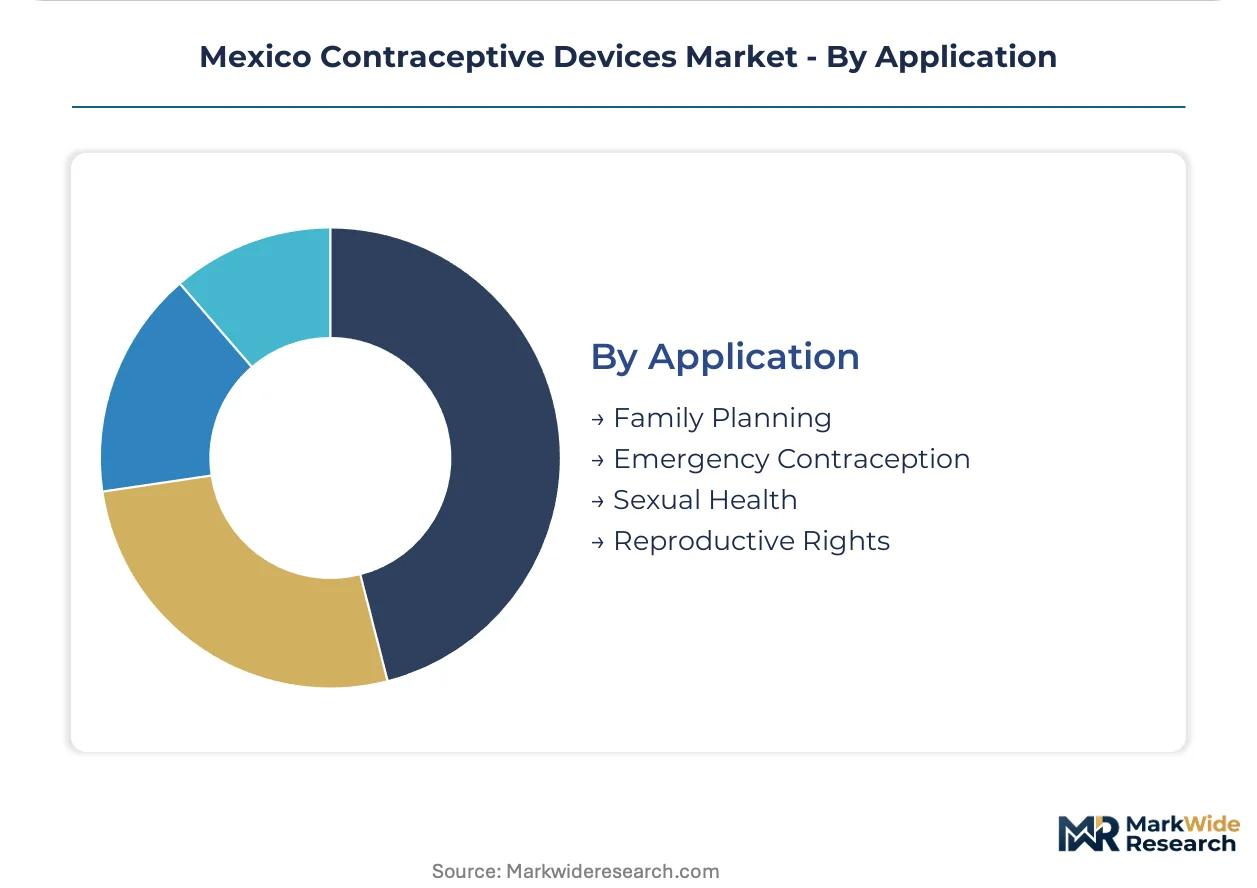
Segmentation reveals how procurement patterns, patient demographics, and care settings fragment Mexico's contraceptive device landscape. Understanding these divisions clarifies where COFEPRIS regulatory pressure concentrates and which channels capture volume as public health infrastructure expands.
Product Type:
Domestic manufacturing capacity concentrates on barrier and short-acting methods, while import dependence dominates long-acting reversible technologies requiring polymer science expertise.
- IUDs:Intrauterine devices deploy copper alloys or hormone-eluting polymer matrices for multi-year pregnancy prevention. Demand clusters in Mexico City and Estado de México public clinics where Secretaría de Salud tenders prioritize cost-per-protected-year metrics over upfront device costs.
- Implants:Subdermal rods release synthetic progestin through biocompatible polymer formulations. COFEPRIS Class II reclassification has extended pre-market timelines for new entrants, entrenching suppliers with existing biocompatibility documentation.
- Condoms:Latex and synthetic rubber barrier devices remain pharmacy-distributed staples with minimal regulatory friction.
- Pills:Oral hormonal formulations operate outside device classification but compete for procurement budgets and patient adherence.
IUDs hold the largest share; momentum sits with implants as clinic insertion capacity expands.
Distribution Channel:
Channel structure reflects the procedural complexity of device administration versus over-the-counter accessibility.
- Hospitals:Tertiary facilities manage complex insertions and adverse event protocols. These institutions anchor procurement volumes for hormonal IUDs through centralized Secretaría de Salud tender participation.
- Clinics:Public health clinics drive IUD and implant insertion rates in urban corridors. Staff training scarcity limits expansion pace despite federal reproductive rights coverage mandates.
- Pharmacies:Retail networks dominate condom and emergency contraception access with minimal clinical gatekeeping.
- Online Retail:Digital channels bypass traditional distribution for barrier methods and emergency contraception, particularly among younger unmarried women in metropolitan zones.
Hospitals command procurement volume; clinics represent the steepest expansion trajectory as insertion training programs scale.
End User:
User segmentation tracks a generational shift from couple-centered decision-making toward individual patient autonomy.
- Married Women:Historical core demographic for IUD adoption through family planning program enrollment. This segment retains preference for long-acting methods within established reproductive health frameworks.
- Adolescents:Younger unmarried women increasingly access devices independently through clinic consultations. Mexico City metropolitan facilities serving university populations concentrate this behavioral pivot.
- Healthcare Providers:Gynecologists and clinic staff function as gatekeepers through prescribing and insertion authority. Training capacity constraints create bottlenecks for device category expansion.
- Couples:Joint decision-making units persist for condom selection but fragment for long-acting methods as individual autonomy frames displace household purchasing patterns.
Married women retain volume concentration; adolescents are gaining share fastest as demographic preferences shift.
Application:
Application areas align with Mexico's national health system priorities and evolving reproductive rights jurisprudence.
- Family Planning:Scheduled contraception through IUDs, implants, and barrier methods. Secretaría de Salud subsidies channel procurement toward long-acting reversible technologies in this category.
- Reproductive Rights:Legal and policy frameworks expanding access to comprehensive contraceptive choice. COFEPRIS regulatory harmonization discussions with FDA quality systems would accelerate import pathways supporting this application area.
- Emergency Contraception:Post-coital intervention through hormonal pills or copper IUD insertion. Online retail and pharmacy channels capture demand outside clinic gatekeeping structures.
- Sexual Health:Disease prevention and wellness framing for barrier method use. Public health messaging increasingly integrates STI protection with pregnancy prevention objectives.
Family Planning dominates procurement allocation; Reproductive Rights shows the strongest policy tailwind as federal coverage mandates deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing capacity clusters in Mexico City and Estado de México, where Secretaría de Salud procurement contracts concentrate insertion volumes for long-acting reversible contraceptives.
Mexico City Metro
Public health clinics in the capital drive IUD and implant insertion rates through federal reproductive rights coverage mandates. COFEPRIS Class II medical device regulations govern biocompatibility testing for silicone-based systems entering this corridor. The Cuauhtémoc and Benito Juárez delegations host the densest clinic networks, with university-affiliated facilities serving younger unmarried women.
Estado de México
Urban density in Toluca and Ecatepec creates localized demand clusters for copper alloy IUDs preferred by patients avoiding hormone exposure. Secretaría de Salud tenders channel volume toward cost-per-protected-year metrics rather than upfront device costs. The Toluca industrial corridor supports domestic condom fabrication while importing polymer expertise for implant manufacturing.
Nuevo León
Monterrey's private hospital networks pilot biodegradable implant formulations that eliminate removal procedures. State health authorities operate outside direct federal procurement protocols, creating parallel demand channels for premium-tier devices. The city's medical device distribution infrastructure serves northern border populations with cross-border prescribing patterns.
Jalisco
Guadalajara metropolitan facilities show per capita insertion rates 40% below Mexico City levels, representing expansion white space for manufacturer field teams. State-level family planning programs lack equivalent Secretaría de Salud subsidy depth, compressing addressable volumes. The city's pharmaceutical manufacturing base concentrates on oral contraceptive formulations rather than device fabrication.
Bajío Region
Querétaro and Guanajuato host emerging medical device assembly operations serving COFEPRIS certification requirements for silicone elastomer processing. Manufacturing site inspection queues extend 14-18 months, freezing capacity expansion timelines for regional entrants. The corridor's automotive polymer expertise offers potential technology transfer pathways for hormone-eluting matrix development.
Mexico Contraceptive Devices Market Competitive Landscape
Concentration sits with multinational pharmaceutical conglomerates possessing established biocompatibility documentation and COFEPRIS registration histories. Bayer AG and CooperSurgical anchor procurement volumes through hospital tender participation and clinic staff training programs. The vendor base fragments between these scale-driven incumbents and regional distributors serving pharmacy channels for barrier methods. Strategic moves center on gynecological insertion training partnerships and polymer formulation R&D redirection toward medical-grade silicone specifications.
Among Germany-based conglomerates, Bayer AG exemplifies the integrated pharmaceutical-device archetype with hormonal IUD portfolios. CooperSurgical represents the specialized gynecological device manufacturer archetype through dedicated intrauterine system expertise. Reckitt Benckiser Group PLC occupies the consumer health multinational position with pharmacy-distributed barrier method scale. These three anchors demonstrate how regulatory compliance depth and clinical training infrastructure separate procurement winners from commodity distributors.
| Leading Market Players |
|---|
| Bayer AG |
| CooperSurgical |
| Reckitt Benckiser Group PLC |
| Pfizer |
| Church & Dwight |
| Allergan PLC |
| Pregna International Limited |
| Organon & Co. |
| Teva Pharmaceutical |
| Others |
Supply & Pricing Matrix
Fourteen-to-eighteen-month COFEPRIS facility inspection queues compress supplier margins while concentrating pricing power among incumbents with established biocompatibility documentation. This lead-time band forces emerging manufacturers to absorb inventory carrying costs for medical-grade silicone stockpiles, amplifying working capital requirements that feed into premium-tier pricing for hormone-eluting polymer systems.
Pricing Analysis
COFEPRIS Class II medical device regulations dictate the pricing tier structure across Mexico's contraceptive device landscape. Three-tier pricing structure across premium, standard, and economy levels separates multinational hormonal IUD portfolios from domestic copper alloy fabricators and pharmacy-distributed barrier methods. Price differentiation hinges on biocompatibility certification grade and gynecological training bundling. Cost compression in the standard tier is intensifying because petrochemical feedstock volatility squeezes medical-grade silicone margins. Public sector procurement through Secretaría de Salud tenders exhibits highest price sensitivity, while private hospital networks in Monterrey show lowest sensitivity due to patient out-of-pocket structures.
Supply Chain Analysis
United States and Germany anchor polymer science expertise for hormone-eluting matrices, while China and Malaysia concentrate latex and synthetic rubber processing for barrier methods. Mexico's domestic fabrication draws from imported medical-grade silicone, copper alloy feedstock, and synthetic progestin APIs. Single-source vulnerability sits with COFEPRIS-certified polymer characterization laboratories, where capacity constraints bottleneck new entrant qualification timelines. Distribution runs through hospital procurement committees and public clinic networks for long-acting devices, with pharmacy and online retail channels capturing condom and emergency contraception volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around COFEPRIS biocompatibility documentation creates a defensive moat favoring incumbents with decade-long registration histories. Switching costs for hospital procurement committees amplify this structural advantage.
For Market Incumbents: Fortify market position through backward integration into medical-grade silicone compounding and captive polymer characterization laboratory capacity in the Bajío Region. Emerging entrants with biodegradable implant formulations threaten premium-tier positioning. Certification investment in dual FDA-COFEPRIS quality systems represents the critical defensive lever. For New Entrants and Emerging Players: Lead with telemedicine-enabled prescription pathways for emergency contraception and direct-to-consumer barrier method distribution in Guadalajara-Monterrey corridor markets. Guadalajara metropolitan facilities show 40% lower device insertion rates per capita versus Mexico City, representing the most penetrable geography. Digital pharmacy partnerships offer the cleanest go-to-market angle bypassing clinic gatekeeper bottlenecks. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting non-core women's health device portfolios. Long-term viability across the analysis window hinges on polymer formulation R&D depth and COFEPRIS registration asset quality. Acquisition candidates with existing biocompatibility documentation for subdermal implants warrant priority screening. The signal to watch as inflection indicator is pending Norma Oficial Mexicana harmonization with FDA quality systems, which would streamline import pathways and revalue registration assets.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Dual Certification Investment | Biocompatibility documentation for Class II devices unlocks hospital tender participation across central Mexico. |
| Gynecological Training Partnership | Supervised insertion capacity expansion addresses the primary bottleneck limiting IUD and implant volume growth. |
| Bioresorbable Polymer R&D | Next-generation implant formulations eliminating removal procedures capture premium positioning in private clinic networks. |
| Telemedicine Platform Integration | Remote consultation infrastructure bypasses traditional clinic gatekeepers for emergency contraception access channels. |
| Bajío Region Manufacturing Footprint | Querétaro and Guanajuato assembly operations reduce lead times for silicone elastomer processing certification. |
Research Methodology
Operator-level perspectives from gynecologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interview data combined with secondary validation from COFEPRIS medical device registration databases, Secretaría de Salud procurement tender records, and customs import documentation for polymer feedstocks. Bottom-up volume modeling across product type, distribution channel, and end user segments triangulated against top-down market sizing from national health expenditure frameworks.
Sensitivity analysis tested forecast robustness across regulatory inspection timeline scenarios and petrochemical price volatility assumptions. Segmentation dimensions modeled include product category, care setting, patient demographic cohort, and regional clinic density cluster. CAGRs were derived from trend extrapolation of insertion rate trajectories and public sector tender allocation shifts. Industry-specific inputs encompassed COFEPRIS approval pipeline tracking and Secretaría de Salud reproductive health budget allocation patterns throughout the projection horizon.
Forecasts assume regulatory continuity in COFEPRIS Class II device classification and Secretaría de Salud tender protocols; material policy shifts would require re-modeling. Assumptions reflect current biocompatibility testing standards and public clinic insertion capacity expansion schedules. Adverse event reporting system integration delays or polymer feedstock supply disruptions would necessitate forecast revision. Recalibration cycles align with material shifts in federal procurement priorities and regulatory harmonization developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Needle-Free Injectors Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Gel Implants Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Capnography Devices Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Global Wheelchair Market
Medical Devices
Neuromodulation Devices Market